
 Beekeeping Equipment Market | 2026-2036
Beekeeping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Beekeeping Equipment Market Outlook
Agricultural supply cooperatives is reconfiguring how beekeeping equipment reaches commercial operators in North America and Eastern Europe. Mann Lake Ltd. leverages its Minnesota manufacturing base to sustain direct-to-apiary fulfillment networks across the Upper Midwest. Dadant & Sons Inc. anchors its competitive position through century-old brand recognition among professional beekeepers in Illinois and neighboring states. Lyson Sp. z o.o. competes aggressively on plastic hive component innovation from its Polish production facilities.
Beekeeping equipment encompasses hives, extractors, protective apparel, and specialized tools engineered from wood, plastic, metal, or composite substrates to house colonies and harvest hive products. Honey extractors typically operate via radial or tangential mechanisms spinning frames at controlled RPMs to separate honey from wax comb without destroying cell structure. Bee Hives command the largest product category share due to replacement cycles driven by colony splitting and winter mortality, while Protective Gear extracts premium pricing from commercial operators facing liability exposure. Composite Materials represent the fastest-growing material segment as manufacturers blend fiberglass and polymer resins to reduce hive weight and extend field lifespan versus traditional pine constructions.
The EPA regulates miticide residues in hive products under tolerances that shape equipment sanitation protocols, while the EU Green Deal pollinator strategy through EFSA mandates habitat buffers influencing apiary siting and transport equipment specifications. ISO standards for beekeeping hygiene equipment create baseline compliance costs for exporters targeting multiple jurisdictions. Stakeholders must monitor evolving chemical residue thresholds and habitat corridor requirements that will determine which equipment configurations retain market access across regulatory boundaries.
Market Dynamics
Commercial pollination contracts from almond orchards and berry farms are compressing equipment replacement cycles while EU Green Deal habitat mandates reshape apiary siting requirements across member states.
Growth Catalysts
- Commercial Pollination Contracts:Almond growers in California and berry producers in Poland's Masovian Voivodeship are scaling hive deployments, forcing equipment procurement at volumes unseen in hobbyist segments.
- EU Green Deal Pollinator Strategy:EFSA-mandated chemical exposure buffers near apiaries are triggering transport equipment upgrades and mobile hive investments to maintain compliance while accessing forage.
- Composite Material Substitution:Fiberglass-polymer resin blends are displacing pine constructions in hive manufacturing, extending field lifespan and reducing colony management labor for commercial operators.
Market Restraints
- Lumber Price Volatility:Baltic pine and cedar input costs fluctuate with construction sector demand, squeezing margins for wooden hive manufacturers serving price-sensitive hobbyist segments.
- Specialized Component Concentration:Precision-manufactured extractors and centrifugal mechanisms rely on German and Italian metalworking suppliers, creating vulnerability to regional energy cost spikes.
- Miticide Residue Thresholds:EPA tolerances for hive product contamination enforce equipment sanitation protocols that add operational steps and chemical testing costs for commercial apiaries.
Strategic Opportunities
- Cooperative Buying Consolidation:Poland's Masovian Voivodeship demonstrates how apiary cooperatives can aggregate procurement volumes, creating channel power that equipment vendors must address with tailored financing.
- Smart Hive Monitoring Convergence:Temperature sensors and acoustic analysis tools are integrating with traditional hive structures, opening premium pricing tiers for data-enabled colony management systems.
- Protective Gear Certification Premiums:ISO hygiene equipment standards create compliance differentiation that liability-exposed commercial operators will pay to secure, separating certified from uncertified suppliers.
Industry Challenges
- Apiary Technician Shortage:Skilled queen breeding and colony splitting expertise concentrates among aging practitioners, constraining expansion for commercial operations seeking to scale hive counts.
- Multi-Jurisdiction Compliance Timelines:Exporters targeting both EPA-regulated US markets and EFSA-governed EU territories face divergent equipment sanitation documentation requirements that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beekeeping Equipment Market |
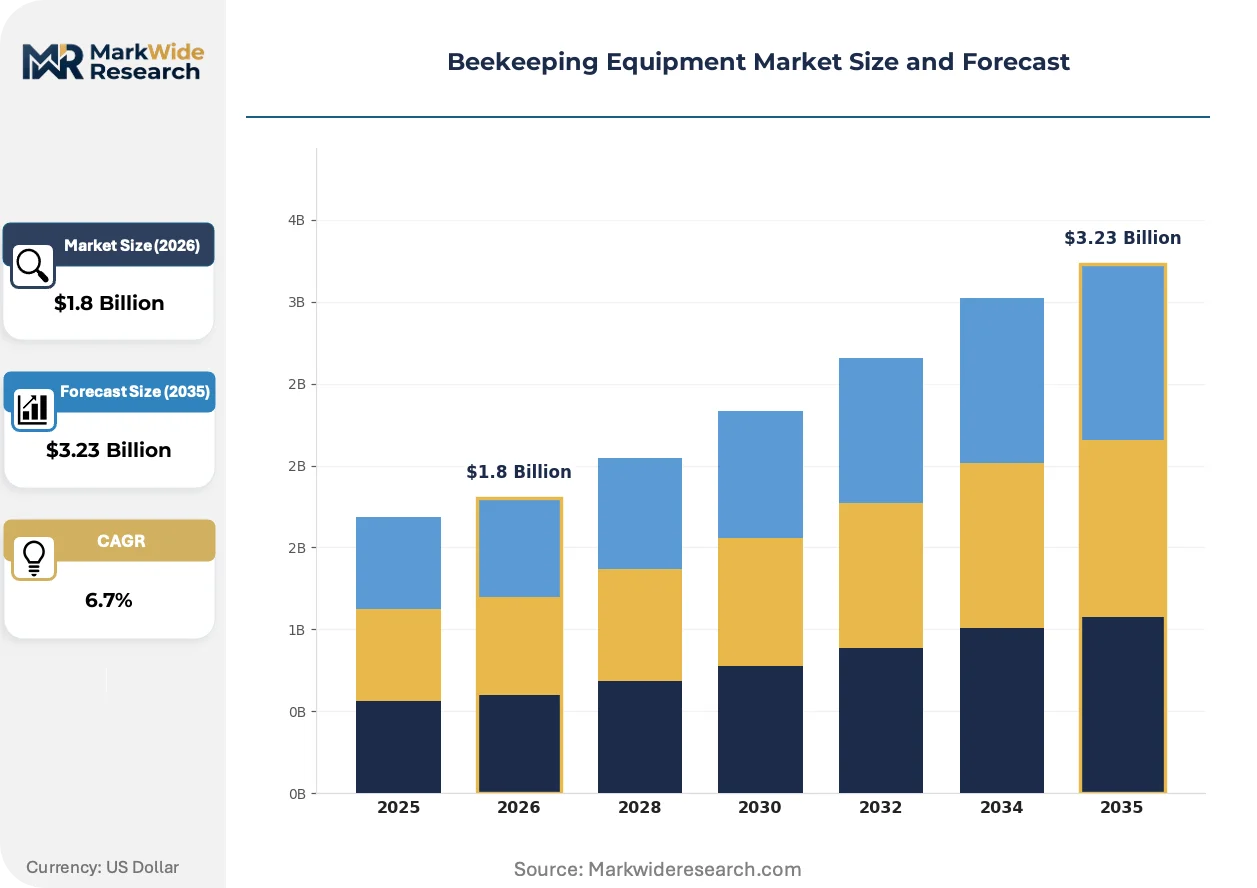
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bee Hives, Honey Extractors, Protective Gear, Beekeeping Tools End User: Commercial Beekeepers, Hobbyist Beekeepers, Agricultural Producers, Research Institutions Material: Wood, Plastic, Metal, Composite Materials Distribution Channel: Online Retail, Specialty Stores, Trade Shows, Direct Sales |
| Companies Covered | Mann Lake Ltd., Dadant & Sons Inc., Thorne Beehives Ltd., Betterbee Inc., GloryBee Inc., Kelley Beekeeping Company, Thomas Apiculture, Lyson Sp. z o.o., Brushy Mountain Bee Farm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beekeeping Equipment Market Strategic Shifts
Equipment manufacturers are racing to reduce hive weight and integrate sensor capabilities while regulatory pressure on chemical exposure reshapes how colonies are housed and transported.
Polystyrene and polyurethane foam hive bodies are rendering obsolete traditional wooden Langstroth designs in northern climates. Commercial operators in Minnesota and Upper Midwest states are adopting these insulated structures at accelerating rates to reduce winter mortality and heating costs. The shift is compressing demand for seasonal wrapping accessories and enabling year-round colony strength that supports earlier pollination contract fulfillment.
REACH chemical authorization restrictions on neonicotinoid-class compounds are tightening equipment decontamination protocols across EU member states. Manufacturers must now design hive components with smoother internal surfaces and removable parts to facilitate pressure washing and heat treatment. German and Polish apiary equipment exporters are retooling production lines to meet these specifications ahead of anticipated EFSA enforcement ramp-ups.
Direct-to-apiary fulfillment networks are displacing traditional agricultural supply cooperative distribution for commercial beekeepers. Mann Lake's Minnesota-based fulfillment model and similar regional direct channels are capturing volume from multi-step distribution. This pattern concentrates most visibly in North American Upper Midwest states where commercial apiary density justifies dedicated logistics investment over generalized farm supply routes.
Beekeeping Equipment Market Segmentation
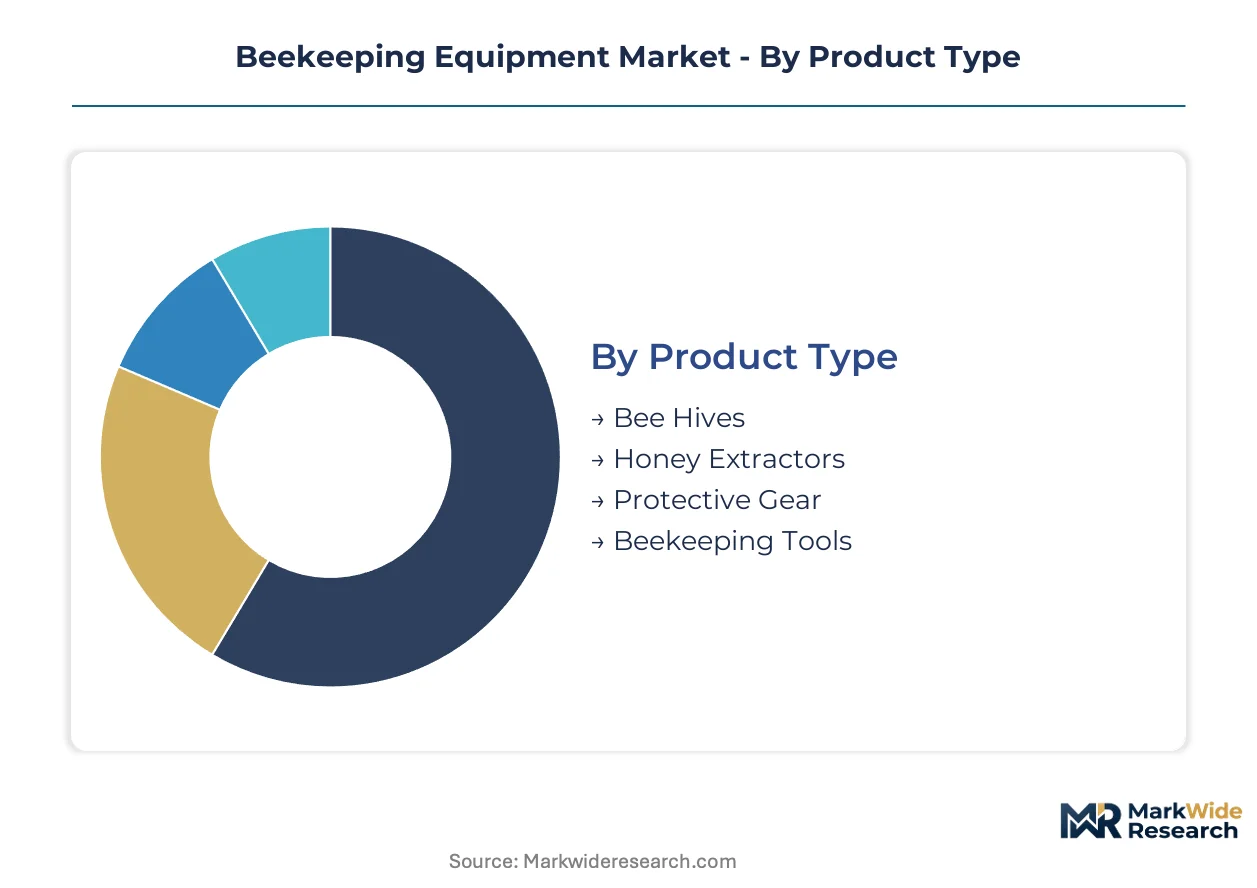
Segmentation in beekeeping equipment determines service intensity, replacement cadence, and channel economics. Commercial operators demand rapid parts availability and technical support, while hobbyists tolerate longer lead times. Material choices and distribution access further stratify margin profiles across supplier portfolios.
Product Type:
After-sales service intensity varies sharply across product categories, with extractors requiring precision maintenance and hives demanding seasonal replacement part availability.
- Bee Hives:Wooden and composite structures house colonies in Langstroth, top-bar, or Warre configurations. Replacement cycles concentrate in Poland's Masovian Voivodeship and California almond districts, driven by colony splitting mandates and winter mortality. Pine constructions face shorter lifespans in humid climates, accelerating turnover.
- Honey Extractors:Radial and tangential centrifugal mechanisms spin frames at controlled RPMs to separate honey without destroying comb cell structure. Demand clusters among commercial beekeepers in Minnesota and Illinois serving pollination contracts, where extraction throughput directly impacts contract fulfillment timelines.
- Protective Gear:Veils, suits, and gloves engineered from cotton, polyester, or ventilated mesh reduce sting exposure during colony inspection.
- Beekeeping Tools:Smokers, hive tools, and queen catchers enable colony manipulation and harvest operations.
By volume, Bee Hives leads. By growth pace, Honey Extractors is ahead.
End User:
Cost tier stratification separates capital-intensive commercial operations from price-sensitive hobbyist segments, reshaping product specifications and financing terms.
- Commercial Beekeepers:Professional apiaries managing 500-plus colonies require durable equipment with standardized dimensions for mechanized handling. Procurement concentrates in California almond corridors and Upper Midwest pollination circuits, where equipment downtime translates directly to contract penalties.
- Hobbyist Beekeepers:Small-scale operators maintaining fewer than 50 colonies prioritize affordability over durability. Demand localizes in suburban and rural residential zones across the United States and Poland, where backyard apiary permits and zoning restrictions constrain scale.
- Agricultural Producers:Berry farms and orchard operators purchase equipment to maintain captive colonies for on-site pollination.
- Research Institutions:Universities and agricultural extension services acquire specialized equipment for breeding programs and pathogen studies.
Commercial Beekeepers command the premium tier. Hobbyist Beekeepers is expanding most quickly.
Material:
Volume concentration in wood processing shapes supply chain vulnerability, while emerging substrates promise labor reduction and extended field life.
- Wood:Baltic pine and cedar constructions dominate traditional hive manufacturing, valued for thermal properties and bee acceptance. Sourcing concentrates in Baltic states and Pacific Northwest timber regions, where construction sector demand volatility creates input cost pressure.
- Composite Materials:Fiberglass-polymer resin blends reduce hive weight by 40 percent versus pine while resisting moisture degradation and pest intrusion. Adoption accelerates among commercial operators in Minnesota and Poland, where reduced colony management labor and extended replacement intervals justify price premiums.
- Plastic:Polystyrene and polyurethane foam bodies provide insulation in northern climates, reducing winter feed consumption.
- Metal:Stainless steel and aluminum components reinforce extractor drums and protective gear fasteners.
Wood retains volume leadership. Composite Materials shows the steepest expansion trajectory.
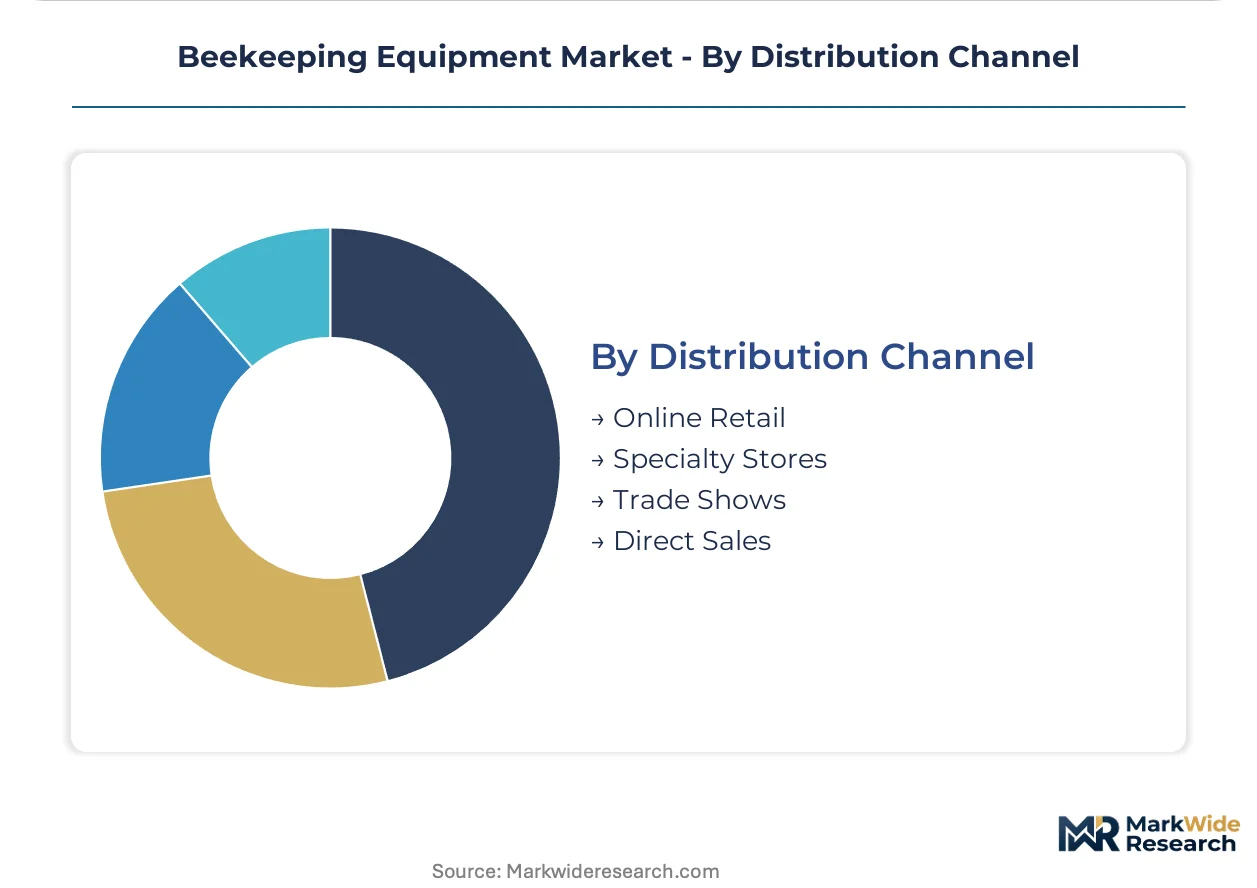
Distribution Channel:
Customer type and geography determine channel viability, with dense commercial apiary clusters justifying dedicated logistics investment over generalized farm supply routes.
- Direct Sales:Manufacturer-to-apiary fulfillment eliminates distributor margins and enables customized volume pricing. Mann Lake's Minnesota-based model captures share in Upper Midwest commercial segments, where apiary density supports dedicated route economics and technical service deployment.
- Specialty Stores:Agricultural supply cooperatives and beekeeping-specific retailers provide hands-on product evaluation and local expertise. Poland's Masovian Voivodeship cooperative buying groups demonstrate how aggregated procurement creates channel power demanding tailored financing terms.
- Online Retail:E-commerce platforms serve dispersed hobbyist segments with standardized products and comparison shopping convenience.
- Trade Shows:Annual conventions enable product demonstration and relationship cultivation among professional beekeeper associations.
Specialty Stores leads by established volume. Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland's refrigerated container throughput underwrites California's almond export dominance, compressing equipment replacement cycles for pollination contractors serving Pacific Rim markets.
United States
Almond orchards in California's Central Valley deploy over two million colonies annually, forcing rapid extractor and transport equipment turnover. EPA miticide residue tolerances shape sanitation protocols for hive products crossing state lines. Minnesota's Upper Midwest apiary belt concentrates procurement through direct manufacturer networks serving commercial pollination circuits.
Poland
Masovian Voivodeship cooperative buying groups aggregate equipment volumes for berry farm pollination contracts across the Central European Plain. EU Green Deal pollinator protection mandates through EFSA tighten chemical exposure buffers near apiaries. Warsaw-based distributors finance seasonal procurement spikes for migratory beekeepers serving rapeseed and buckwheat monocultures.
Germany
Precision metalworking suppliers in Baden-Württemberg and Bavaria fabricate extractor centrifugal mechanisms for export across the continent. REACH chemical authorization restrictions on neonicotinoid-class compounds pressure equipment decontamination design standards. Stuttgart-area manufacturers retool production lines for smoother hive surfaces facilitating pressure washing compliance.
Canada
Prairie provinces sustain honey production volumes requiring winter-resistant hive configurations and insulated transport systems. Health Canada PMRA regulates varroacide residues in hive products, influencing equipment sanitation documentation for cross-border exporters. Alberta's Peace River valley clusters commercial apiaries supplying northern pollination contracts.
Australia
Eucalyptus honey harvests in New South Wales and Victoria drive extractor throughput requirements for high-volume seasonal operations. Biosecurity protocols through the Department of Agriculture mandate equipment sterilization between apiary movements to contain pest spread. Queensland's subtropical coastal belt concentrates migratory operations chasing floral sequences.
Beekeeping Equipment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision-manufactured centrifugal mechanisms and polymer resin formulations. The vendor base stratifies between century-old brand anchors and regional fabricators competing on material innovation. Three archetypes dominate: heritage manufacturers leveraging generational customer loyalty, composite material innovators displacing traditional pine constructions, and direct-fulfillment operators compressing distribution margins in dense apiary clusters. Competitive moves concentrate on geographic expansion into cooperative buying territories and backward integration into polymer resin compounding.
Among Upper Midwest-based direct-fulfillment operators, Mann Lake Ltd. exemplifies the platform-integrator archetype with dedicated route economics serving commercial density. Heritage manufacturers represented by Dadant & Sons Inc. anchor the premium tier through professional beekeeper relationships spanning multiple generations. Polish fabricators including Lyson Sp. z o.o. occupy the composite innovation vector, displacing wooden constructions through fiberglass-polymer resin blends. These three patterns illustrate how geographic concentration and material substitution reshape competitive positioning without requiring specific strategic claims about individual firm behavior.
| Leading Market Players |
|---|
| Mann Lake Ltd. |
| Dadant & Sons Inc. |
| Thorne Beehives Ltd. |
| Betterbee Inc. |
| GloryBee Inc. |
| Kelley Beekeeping Company |
| Thomas Apiculture |
| Lyson Sp. z o.o. |
| Brushy Mountain Bee Farm |
| Others |
Value Chain & Pricing Dynamics
Baltic pine price volatility determines both pricing tier spreads and supply chain shape across wooden hive manufacturing. Lumber input cost fluctuations compress margins for pine-based producers serving price-sensitive hobbyist segments while pushing commercial operators toward composite material alternatives with more stable polymer resin feedstock costs.
Pricing Analysis
Volume-discount tiering structures separate commercial apiary procurement from hobbyist purchasing patterns across the beekeeping equipment market. Three-tier pricing stratification across premium certified gear, standard commercial-grade equipment, and economy hobbyist tiers reflects ISO hygiene certification premiums and mechanized handling compatibility. Pricing pressure stems from lumber cost compression in wooden hive segments, forcing manufacturers to absorb margin erosion or risk volume loss to polystyrene foam alternatives. Commercial beekeepers demonstrate lowest price sensitivity due to contract penalty exposure from equipment downtime, while backyard operators in residential zones exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock dependencies center on Baltic states timber regions, German and Italian metalworking clusters, and polymer resin compounding facilities in Poland and the United States. Baltic pine and cedar sourcing concentrates in Estonia, Latvia, and Pacific Northwest timber regions, while precision extractor centrifugal mechanisms draw from Baden-Württemberg and Bavaria fabrication centers. Single-source vulnerability concentrates in German metalworking suppliers for precision-manufactured extractor components, exposing equipment vendors to regional energy cost spikes. Distribution runs through direct-to-apiary fulfillment networks displacing traditional agricultural supply cooperative channels in dense commercial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beekeeping equipment market is entering a cyclical recovery phase driven by almond orchard pollination contract expansion in California. Colony deployment mandates from berry farms and orchard operators are forcing equipment replacement cycles that favor suppliers with rapid fulfillment capabilities.
For Market Incumbents: Build switching-cost moats through integrated sensor-enabled hive monitoring systems that embed proprietary data analytics. Deepen backward integration into polymer resin compounding to secure composite material cost advantages against lumber price volatility. Anchor capacity expansion in Minnesota and Poland's Masovian Voivodeship where commercial apiary density justifies dedicated logistics investment and technical service deployment.
For New Entrants and Emerging Players: Pursue white-space opportunities in smart hive monitoring convergence where temperature sensors and acoustic analysis tools command premium pricing tiers. Target Poland's cooperative buying groups with tailored financing structures that aggregate procurement volumes. Lead with direct-to-apiary fulfillment models bypassing legacy distribution markups in Upper Midwest commercial segments.
For Investors and Strategic Acquirers: EU Green Deal pollinator protection mandates through EFSA reshape the acquisition landscape by privileging equipment vendors with decontamination-compliant designs ahead of enforcement ramp-ups. Long-term viability centers on composite material innovators displacing traditional pine constructions and direct-fulfillment operators capturing share in dense apiary clusters. Monitor REACH chemical authorization restriction timelines as the critical signal for equipment sanitation protocol inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Manufacturing Scale-Up | Polish polymer resin compounding captures share from Baltic pine suppliers facing construction sector demand volatility. |
| Direct-to-Apiary Fulfillment Network Expansion | Mann Lake's Minnesota model demonstrates route economics that outperform agricultural supply cooperative distribution. |
| Smart Hive Monitoring Platform Integration | Temperature sensors and acoustic analysis tools open premium pricing tiers for data-enabled colony management. |
| EU Green Deal Compliance Certification Investment | EFSA-mandated chemical exposure buffers pressure equipment designs with smoother surfaces for pressure washing. |
| Cooperative Buying Group Financing Partnership | Masovian Voivodeship aggregation models create channel power demanding tailored procurement structures. |
Study Parameters
Cross-validation between primary interviews with commercial beekeepers, equipment manufacturers, and agricultural supply cooperative managers anchors the qualitative findings against secondary validation. Stakeholder engagement encompassed apiary operators managing 500-plus colonies in California and Minnesota, Polish cooperative buying group organizers, German precision metalworking suppliers, and EPA regulatory affairs specialists. Secondary sources included EPA miticide residue tolerance documentation, EFSA pollinator protection mandate filings, EU Green Deal strategy papers, ISO hygiene equipment standards, and customs records tracking Baltic pine and polymer resin trade flows. Bottom-up equipment shipment data triangulates against top-down pollination contract volume estimates.
Calibration approaches weight historical replacement cycle patterns against projected almond orchard and berry farm expansion trajectories across the analysis window. Segmentation dimensions encompass product type hierarchies, end-user scale tiers, material substrate categories, and distribution channel structures. CAGRs derive from equipment procurement intensity models tied to colony splitting mandates and winter mortality replacement rates. Forecast inputs incorporate EU Green Deal implementation timelines and REACH chemical authorization restriction enforcement phases.
Sensitivities concentrate around lumber price volatility in wooden hive segments, EFSA enforcement ramp-up schedules for decontamination protocols, and commercial pollination contract cancellation risks from almond export demand fluctuations. Forecasts reflect documented assumptions regarding composite material substitution rates and direct-to-apiary fulfillment network penetration. Cross-checking against almond export volume data from the Port of Oakland is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market