
 Agriculture Equipment Market | 2026-2036
Agriculture Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Equipment Market Analysis
The capital-intensity divergence between full-line manufacturers and regional specialists is unwinding competitive dynamics across the sector. Deere & Company leverages its vertically integrated precision agriculture ecosystem to command premium positioning in North American row-crop segments. AGCO Corporation anchors its strategy through targeted brand portfolios spanning Fendt, Massey Ferguson, and Challenger, each occupying distinct price-performance tiers. CNH Industrial competes aggressively in emerging markets through localized production footprints and cooperative financing structures.
Agriculture equipment comprises self-propelled and trailed machinery engineered to specifications of engine power, implement width, and hydraulic flow rate measured in liters per minute, designed to execute soil tillage, planting, crop care, and harvesting operations with measurable throughput per hectare. Tractors and harvesters dominate installed base value, though precision agriculture technology represents the fastest-expanding margin pool as subscription-based telemetry services displace pure hardware sales. Automation and IoT integration across seeders and plows is reshaping how agricultural cooperatives and contractors manage fleet utilization and input application timing.
EPA Tier 4 Final and EU Stage V emissions regulations are forcing engine redesigns and after-treatment adoption, while India's CEA and BIS certification requirements shape import eligibility and local assembly incentives. The EU Green Deal's Farm to Fork strategy further tightens sustainability benchmarks for equipment lifecycle emissions and recyclability. Stakeholders must monitor how regulatory divergence between jurisdictions fragments product platform strategies and determines where manufacturers localize engine production versus import complete powertrains.
Market Dynamics
Precision agriculture telemetry is compressing equipment sales cycles as subscription-based fleet management replaces transactional hardware purchases across commercial farming operations.
Growth Catalysts
- EPA Tier 4 Final mandates:Emissions compliance deadlines are accelerating fleet turnover among North American row-crop operators, forcing replacement of pre-2015 diesel powertrains with after-treatment-equipped engines.
- India PLI scheme for farm mechanization:Production-linked incentives for domestic tractor and harvester assembly are expanding manufacturing capacity in Punjab and Maharashtra.
- Autosteer retrofit kits:Aftermarket guidance systems are extending useful life of existing machinery while delivering sub-inch accuracy for input application.
Market Restraints
- Steel and semiconductor input volatility:Hydraulic component foundries face margin compression from alloy price swings and chip allocation constraints for controller modules.
- Single-source DEF dosing systems:Selective catalytic reduction hardware concentrates with German and Japanese suppliers, creating vulnerability for Tier 2 engine builders.
- Battery energy density limits:Lithium-ion cell chemistry constraints prevent electrification of 300+ horsepower tractor categories without unacceptable weight penalties.
Strategic Opportunities
- Ukraine reconstruction demand:Post-conflict agricultural recovery will require massive fleet replenishment of tractors and combines destroyed or seized during hostilities.
- EU Green Deal Farm to Fork:Lifecycle emissions scoring for equipment procurement favors manufacturers with localized remanufacturing capabilities and biofuel-compatible engines.
- Drone-sprayer convergence:Unmanned aerial application systems are creating new channel partnerships between traditional dealerships and agritech service providers.
Industry Challenges
- Mechatronics technician scarcity:Rural dealerships cannot hire sufficient staff to service CAN-bus diagnostics, hydraulic electronics, and telematics integration.
- CE marking timeline compression:EU machinery directive conformity assessments for autonomous implements are extending product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Equipment Market |
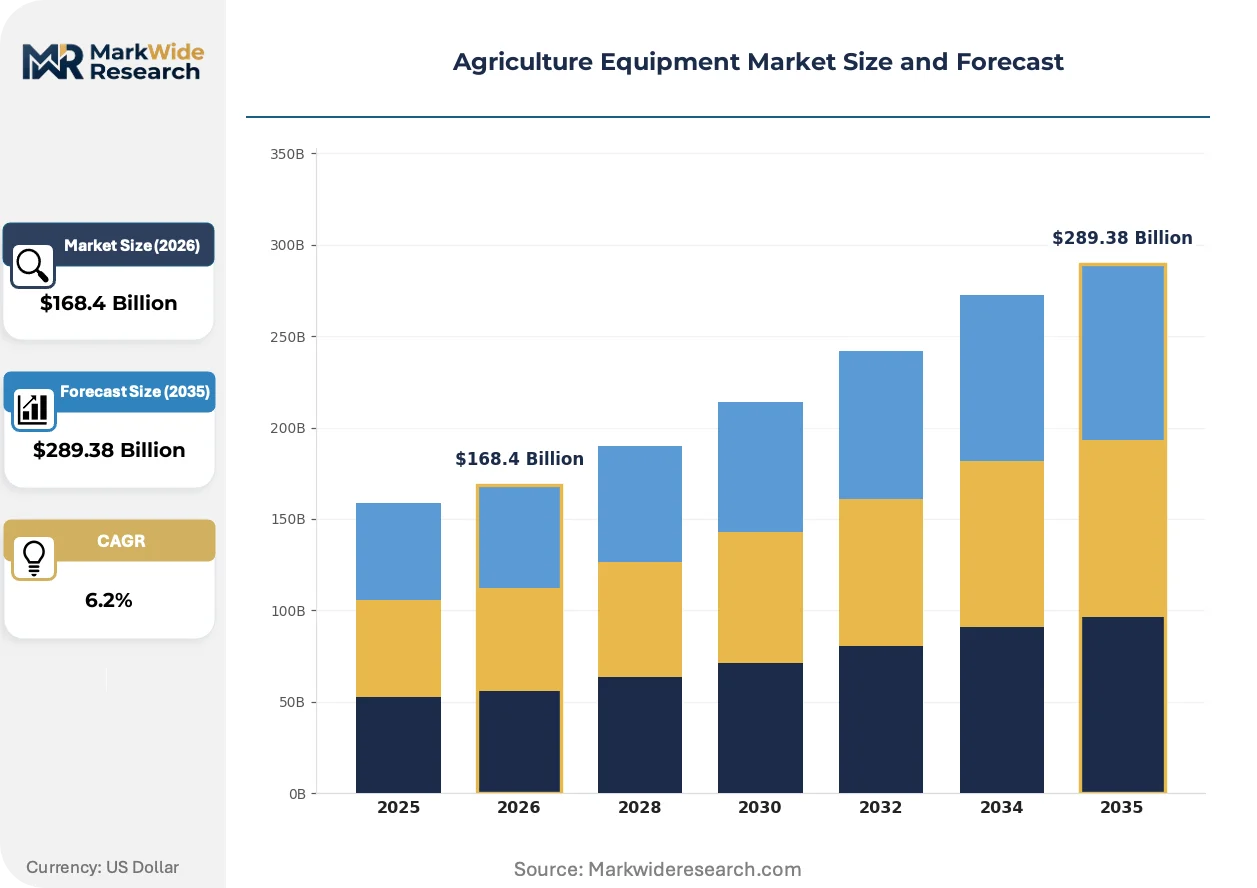
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $289.38 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plows, Seeders Application: Crop Production, Livestock Management, Soil Preparation, Irrigation Technology: Precision Agriculture, Automation, IoT, Bioengineering End User: Farmers, Agricultural Cooperatives, Research Institutions, Contractors |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, Kubota Corporation, Mahindra & Mahindra Limited, CLAAS KGaA mbH, JC Bamford Excavators Limited, ISEKI & Co., Ltd., Escorts Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Equipment Market Emerging Trajectories
Electrification and autonomy are bifurcating product development roadmaps, with manufacturers placing divergent bets on battery-electric platforms versus continued diesel optimization with precision controls.
Variable-rate seeding technology is displacing uniform planting density across Brazilian soybean operations. Large-scale contract farming enterprises in Mato Grosso are retrofitting existing planters with electric drive meters and prescription map integration. This hardware-software bundle is displacing per-hectare seeding service contracts with equipment-as-margin models that capture input savings.
EU Stage V emissions enforcement is forcing exhaust after-treatment standardization across all imported engines above 56 kW. Italian and German manufacturers are consolidating engine platform architectures to spread compliance costs across multiple horsepower categories. The 130-175 kW tractor segment faces the steepest price escalation as compact packaging requirements collide with thermal management needs.
Cooperative purchasing collectives are consolidating equipment acquisition decisions among Midwest grain operations. These farmer-owned entities negotiate fleet-scale pricing directly with manufacturers, bypassing traditional dealer networks for specified configurations. Illinois and Iowa host the densest concentration of these buying groups, which now account for a measurable share of annual row-crop machinery volume.
Agriculture Equipment Market Segmentation
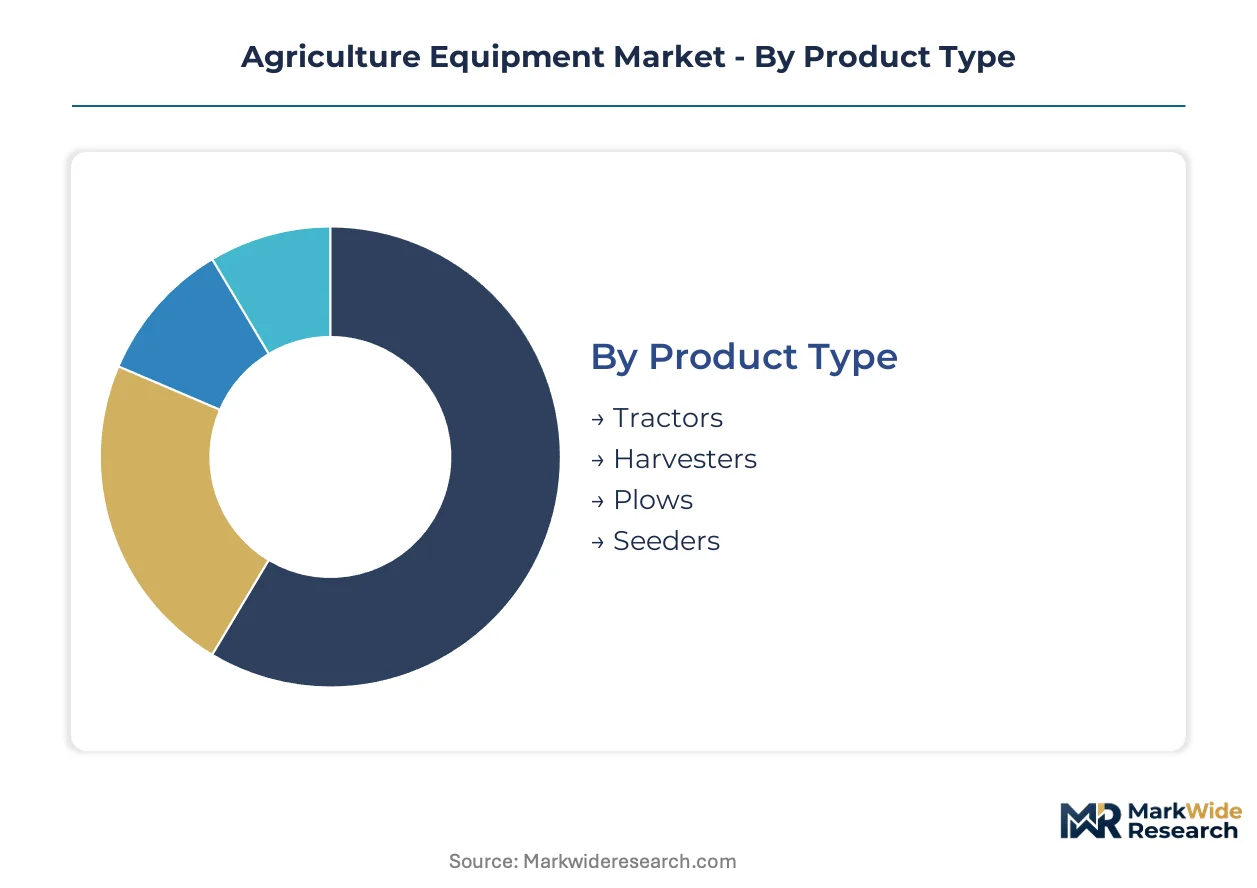
Equipment segmentation in this market tracks divergent regulatory pathways across jurisdictions while mapping how precision technology reconfigures traditional hardware categories. Understanding these splits reveals where capital deployment concentrates and which specifications determine import eligibility.
Product Type:
EPA Tier 4 Final and EU Stage V standards apply differential compliance burdens based on engine power band and equipment weight class, fragmenting platform architectures across horsepower categories.
- Tractors:Self-propelled machines ranging from sub-40 hp utility models to 400+ hp articulated 4WD units, classified by engine displacement and hydraulic flow capacity measured in liters per minute. Demand clusters in India's Punjab and Maharashtra corridors where PLI scheme subsidies accelerate fleet replacement of pre-Stage IV diesel units.
- Harvesters:Combine platforms integrating threshing, cleaning, and grain handling systems with throughput measured in tonnes per hour. Brazilian Mato Grosso soybean operators dominate procurement volumes, driven by contract farming consolidation that demands 24-hour harvesting windows during narrow weather windows.
- Plows:Trailed tillage implements with working widths from 2.5 to 15 meters, requiring draft force matching tractor hydraulic capacity. Primary adoption concentrates in Black Sea grain belts where deep ripping offsets soil compaction from heavy freight logistics.
- Seeders:Planting equipment with meter types ranging from fluted to pneumatic to electric drive, calibrated for seed population per hectare. Variable-rate retrofit demand is climbing fastest among Midwest cooperative purchasing collectives seeking prescription map integration.
Established volume favors tractors; emerging adoption favors seeders with precision retrofit bundles.
Application:
Margin profiles diverge sharply between input-intensive annual cropping and capital-light perennial management, with irrigation systems commanding premium pricing in water-stressed districts.
- Crop Production:Machinery dedicated to grain, oilseed, and fiber cultivation with seasonal utilization peaks. EPA compliance deadlines in Iowa and Illinois are compressing replacement cycles for pre-2015 combines and planters.
- Livestock Management:Feed handling, manure management, and animal housing equipment with year-round duty cycles. Demand concentrates in Denmark and the Netherlands where EU Green Deal ammonia emission limits mandate precision slurry application technology.
- Soil Preparation:Primary and secondary tillage operations preceding planting, with implement selection dictated by soil texture and residue management requirements. Ukrainian reconstruction requirements will drive substantial fleet replenishment of disc harrows and chisel plows in post-conflict zones.
- Irrigation:Center-pivot, linear-move, and drip systems with pumping requirements tied to aquifer depth and energy costs. India's CEA certification requirements for electric pump efficiency are reshaping import eligibility for surface water extraction equipment.
Input cost pressure elevates irrigation; livestock ammonia regulations accelerate equipment turnover fastest.
Technology:
Customer willingness to pay for telemetry subscriptions versus capital hardware separates precision agriculture adopters from conventional equipment purchasers.
- Precision Agriculture:GNSS guidance, prescription mapping, and variable-rate application systems with sub-inch accuracy specifications. Subscription-based fleet management is compressing sales cycles across North American row-crop operations as telemetry displaces transactional hardware purchases.
- Automation:Autosteer, implement control, and autonomous function packages reducing operator fatigue and input overlap. Aftermarket retrofit kits are extending useful life of existing machinery while delivering accuracy gains without full platform replacement.
- IoT:CAN-bus diagnostics, telematics integration, and remote monitoring platforms for fleet utilization optimization. Mechatronics technician scarcity at rural dealerships creates service bottlenecks for connected equipment deployments.
- Bioengineering:Equipment modifications for biofuel-compatible engines and biomass harvesting attachments. EU Green Deal Farm to Fork lifecycle emissions scoring favors manufacturers with biofuel adaptation capabilities and localized remanufacturing footprints.
Hardware margins favor precision agriculture bundles; service revenue expansion favors IoT telemetry platforms.
End User:
Procurement scale and financing access determine equipment specification tiers, with cooperatives leveraging collective bargaining power against manufacturer direct channels.
- Farmers:Owner-operators with fleet sizes from single tractors to multi-machine operations, selecting horsepower bands based on hectare scale and crop rotation complexity. Individual purchasers in India access government subsidy programs that reduce effective acquisition cost for certified equipment.
- Agricultural Cooperatives:Farmer-owned entities consolidating acquisition decisions and negotiating fleet-scale pricing directly with manufacturers. Illinois and Iowa host the densest concentration of these buying groups, which now account for measurable share of annual row-crop machinery volume.
- Research Institutions:University and government trial stations requiring specialized plot equipment with data logging capabilities. Limited volume but high specification influence through variety testing and demonstration programs.
- Contractors:Custom service providers offering tillage, planting, and harvesting on per-hectare fee structures, prioritizing equipment throughput and transport efficiency. CE marking timeline compression for autonomous implements extends product launch windows, delaying contractor access to newest platforms.
Direct manufacturer relationships favor cooperatives; equipment utilization rates favor contractors with 24-hour operational models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across major demand centers. Indian buyers respond aggressively to subsidy adjustments, while Brazilian operators prioritize throughput metrics over capital cost. German and US purchasers weigh total cost of ownership against financing terms.
United States
Row-crop operators in Iowa and Illinois face compressed replacement cycles as EPA Tier 4 Final deadlines eliminate grandfathered pre-2015 diesel fleets. The USDA administers equipment cost-share programs that reduce effective acquisition prices for precision agriculture bundles. Equipment dealerships in the Corn Belt report accelerating trade-ins of mechanical-drive planters for electric-meter retrofits.
Germany
Farm cooperatives in Lower Saxony and Bavaria demand lifecycle emissions scoring under EU Green Deal procurement guidelines. The KBA enforces Stage V conformity assessments that extend product launch timelines for autonomous implements. Stuttgart-based engine foundries are consolidating platform architectures across the 130-175 kW tractor segment to spread compliance costs.
India
Punjab and Maharashtra corridors dominate tractor procurement as the PLI scheme for farm mechanization expands domestic assembly capacity. The CEA and BIS certification requirements reshape import eligibility for electric pump sets and surface water extraction equipment. Manufacturers in Haryana are scaling harvester production to capture replacement demand from aging Chinese-origin fleets.
Brazil
Mato Grosso soybean contract farming enterprises drive combine procurement volumes, prioritizing 24-hour harvesting windows during narrow weather intervals. ANVISA coordinates with agricultural ministries on chemical application equipment standards that affect sprayer specifications. Campo Grande hosts the densest concentration of autonomous retrofit installations for existing planter fleets.
China
Shandong and Hebei provinces anchor domestic tractor manufacturing as MIIT enforces GB standards for engine efficiency and hydraulic system safety. The dual carbon goals accelerate electrification pilots in the sub-100 hp utility segment where battery weight penalties remain manageable. Weifang industrial clusters supply transmission components to Southeast Asian assembly operations.
Agriculture Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-line manufacturers commanding premium positioning through captive precision agriculture ecosystems. Regional specialists compete on localized production footprints and cooperative financing structures. Three archetypes define the field: vertically integrated technology platforms, multi-brand portfolio holders, and emerging-market cost optimizers. Competitive moves center on M&A for telemetry capabilities and geographic expansion through localized assembly joint ventures.
Among the integrated tier, Deere & Company and AGCO Corporation exemplify divergent platform strategies. Deere anchors North American row-crop positioning through precision agriculture ecosystem control. AGCO occupies multi-brand portfolio architecture with distinct price-performance tiers across its holdings. CNH Industrial represents emerging-market penetration through cooperative financing and localized production scale.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| Kubota Corporation |
| Mahindra & Mahindra Limited |
| CLAAS KGaA mbH |
| JC Bamford Excavators Limited |
| ISEKI & Co., Ltd. |
| Escorts Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for steel and hydraulic components lock in supply access for Tier 1 manufacturers while freezing input cost visibility across multi-year production cycles. This contract structure insulates Deere and AGCO from alloy price swings that compress margins for regional assemblers in India and Brazil.
Pricing Analysis
After-sales service and parts revenue drives lifetime value across tractor and harvester fleets, with telemetry subscriptions now capturing recurring streams that offset transactional hardware compression. Three-tier pricing structure across premium, standard, and economy levels separates Fendt's integrated precision bundles from Massey Ferguson's utility-focused configurations. Pricing pressure stems from cooperative purchasing collectives in Illinois and Iowa that negotiate fleet-scale discounts directly with manufacturers. Individual farmers in India exhibit highest price sensitivity due to subsidy-dependent financing, while Brazilian contract farming enterprises prioritize throughput metrics over capital cost.
Supply Chain Analysis
German and Japanese selective catalytic reduction hardware suppliers create single-source vulnerability for DEF dosing systems that Tier 2 engine builders cannot easily circumvent. Steel mills in China and South Korea feed hydraulic component foundries, while lithium-ion cell production concentrates in China, South Korea, and Japan. Semiconductor allocation constraints for controller modules persist as a structural risk across all powertrain categories. Distribution runs through captive dealer networks in North America and cooperative financing structures in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against drone-sprayer convergence and agritech service providers that displace traditional equipment ownership models with per-hectare application contracts.
For Market Incumbents: Secure telemetry platform control through backward integration into CAN-bus diagnostics and telematics software stacks. Deepen precision agriculture ecosystem lock-in by bundling subscription-based fleet management with hardware trade-in programs. Autonomous retrofit kits from aftermarket competitors threaten installed base retention; counter by extending autosteer compatibility to legacy machine vintages. For New Entrants and Emerging Players: Aftermarket guidance system installation gaps in Midwest cooperative networks present immediate white-space opportunity. Target contractor segments in Mato Grosso and Ukraine reconstruction zones where fleet replenishment demand outstrips established service capacity. Partner with agritech service providers for drone-sprayer convergence rather than competing through traditional dealer channels. For Investors and Strategic Acquirers: Capital is best deployed toward precision agriculture software specialists with proven prescription map integration and variable-rate retrofit capabilities. Long-term viability favors platforms that capture recurring telemetry revenue over pure hardware manufacturers exposed to cyclical replacement demand. Watch EPA Tier 5 or EU Stage VI regulatory signaling as inflection indicator for accelerated fleet turnover timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Telemetry subscriptions displace transactional sales for Deere and AGCO in North American row-crop segments. |
| Localized Assembly Joint Venture | PLI scheme subsidies in Punjab and Maharashtra reduce import duty exposure for harvester production. |
| Aftermarket Autosteer Retrofit Program | Electric drive meter kits extend useful life of existing planters for Midwest cooperative purchasing collectives. |
| Biofuel-Compatible Engine Certification | EU Green Deal lifecycle emissions scoring favors remanufacturing capabilities in German cooperative procurement. |
| Mechatronics Technician Training Partnership | Rural dealership service bottlenecks for CAN-bus diagnostics constrain connected equipment deployment velocity. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, EU machinery directive conformity assessments, and Indian PLI scheme administrative records. Interviews with OEM platform engineers, aftermarket service heads, cooperative purchasing managers, and agricultural contractor operators informed demand-side validation. Customs data for tractor and harvester trade flows, SEC 10-K equipment revenue disclosures, and BIS certification registries provided supply-side triangulation. Bottom-up equipment unit economics and top-down macroeconomic drivers were cross-referenced for convergence.
Segmentation dimensions modeled include product type across horsepower bands, application by crop system intensity, technology tier from conventional to precision-autonomous, and end-user procurement scale from individual farmers to cooperative collectives. CAGRs were derived from regression analysis of replacement cycle compression, subsidy program trajectories, and regulatory deadline impacts across the projection horizon. Forecast inputs incorporated steel and semiconductor price volatility assumptions, emissions compliance cost pass-through rates, and telemetry subscription adoption curves.
Forecasts assume regulatory continuity in EPA Tier 4 Final enforcement, EU Stage V conformity timelines, and Indian CEA certification requirements; material policy shifts would require re-modeling of fleet turnover velocity and import eligibility criteria. Practitioners should keep alternative scenarios live as Ukraine reconstruction funding allocation and Brazil ANVISA chemical application standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market