
 Global Fishery Machinery Manufacturing Market | 2026-2036
Global Fishery Machinery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fishery Machinery Manufacturing Market Analysis
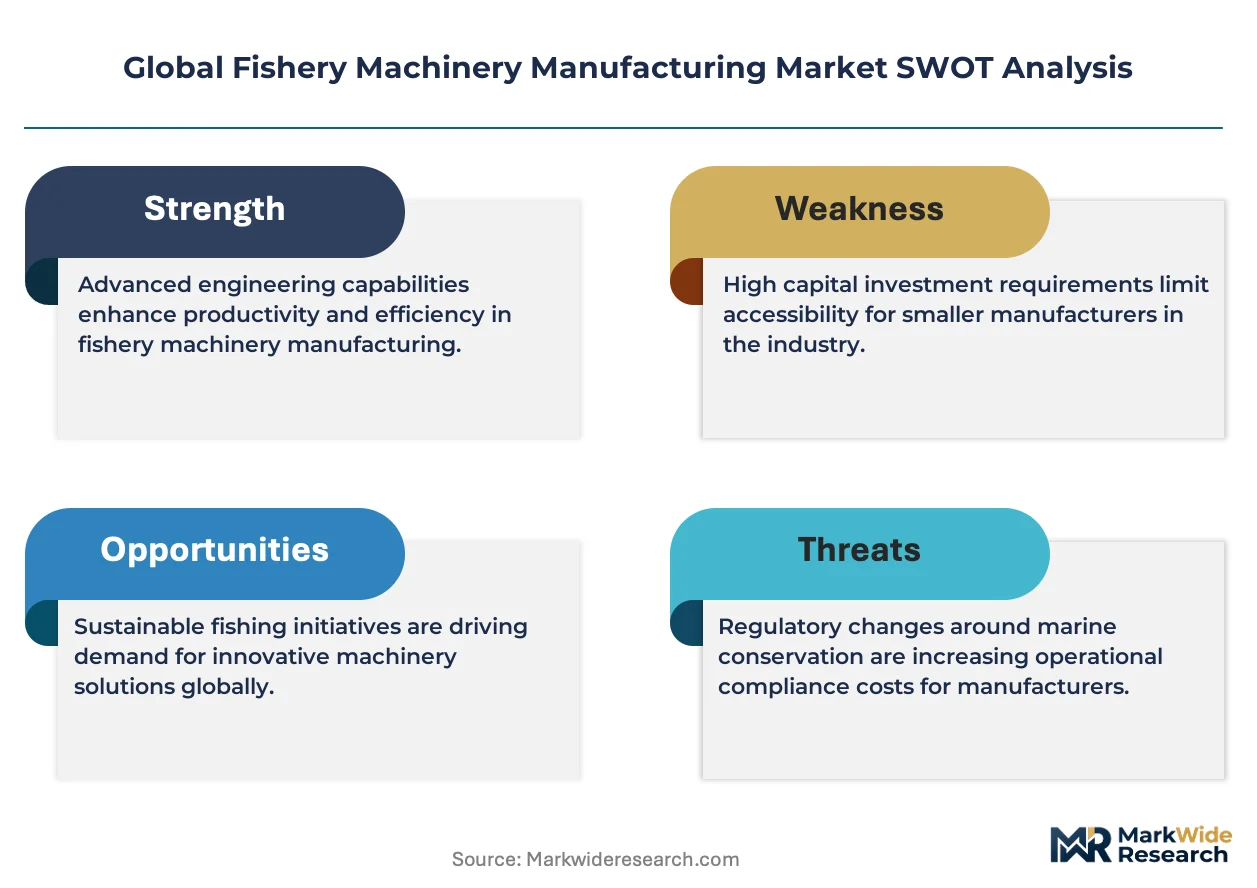
ISO 14001 environmental management certification is unwinding the competitive landscape for machinery suppliers serving regulated waters. Marel leverages its automation portfolio to dominate high-throughput processing lines for whitefish and pelagic species. AKVA Group anchors its position through integrated aquaculture feeding and monitoring systems that extend from cage to shore. Bettcher Industries Inc competes on precision trimming tools that sustain margin pools in labor-intensive manual processing segments.
Fishery machinery manufacturing encompasses the production of deck equipment, catch handling systems, onboard processing units, and shore-based processing lines engineered to operate in corrosive marine environments with stainless steel construction and IP67-rated electrical enclosures. Processing equipment leads value generation due to continuous throughput requirements and hygiene-critical design standards, while automation technology represents the fastest-expanding segment as vessel operators replace mechanical controls with sensor-driven sorting and filleting systems. Traditional technology still occupies substantial installed base across aging fleets in emerging fishing nations, creating a bifurcated replacement dynamic.
The EU F-Gas Regulation and MEE in China impose refrigerant phase-down schedules that force machinery redesigns for cold-chain dependent processing lines. CE marking requirements under the EU Machinery Directive shape export eligibility for Norwegian and Danish manufacturers serving European fleet operators. Stakeholders must monitor how impending IMO energy efficiency standards for fishing vessels redirect capital from hull machinery toward propulsion and auxiliary power systems.
Market Dynamics
Automation integration in onshore processing plants is compressing replacement cycles for legacy deck equipment across Norway, Vietnam, and Peru. Sensor-driven sorting systems are forcing vessel operators to reallocate capital from mechanical controls toward integrated catch-handling architectures.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down schedules mandate machinery redesigns for cold-chain dependent processing lines, accelerating equipment turnover in Danish and Spanish fleets.
- Protein demand surge:Southeast Asian commercial fisheries are scaling mechanized fleet upgrades to meet rising domestic and export consumption requirements.
- Stainless steel IP67 construction:Corrosion-resistant electrical enclosures are extending equipment lifespans in high-salinity operating environments, reducing total cost of ownership for operators.
Market Restraints
- Nickel and chromium price volatility:Stainless steel input costs fluctuate with Indonesian ore export policies, squeezing margin pools for fabricators of hygiene-critical processing surfaces.
- IMO energy efficiency standards:Pending vessel efficiency mandates redirect capital from hull machinery toward propulsion and auxiliary power systems, delaying deck equipment procurement.
- Mechanical control installed base:Aging fleets in emerging fishing nations maintain substantial traditional technology, creating bifurcated replacement dynamics that fragment demand.
Strategic Opportunities
- Indonesian fleet mechanization:Underpenetrated artisanal vessel segments present white space for compact, modular processing units designed for tropical corrosion conditions.
- Sensor-filtration convergence:Integration of real-time biomass monitoring with automated grading systems enables precision catch allocation across multi-species operations.
- EU Green Deal procurement incentives:Public fleet modernization programs favor ISO 14001-certified suppliers, creating preferential access channels for environmental management-compliant manufacturers.
Industry Challenges
- Marine electrician skill scarcity:Specialized technicians capable of servicing IP67-rated enclosures in remote port locations command premium wages, constraining after-sales network expansion.
- CE marking timeline compression:EU Machinery Directive conformity assessment procedures extend product launch schedules, disadvantaging smaller fabricators against established Norwegian and Danish competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fishery Machinery Manufacturing Market |
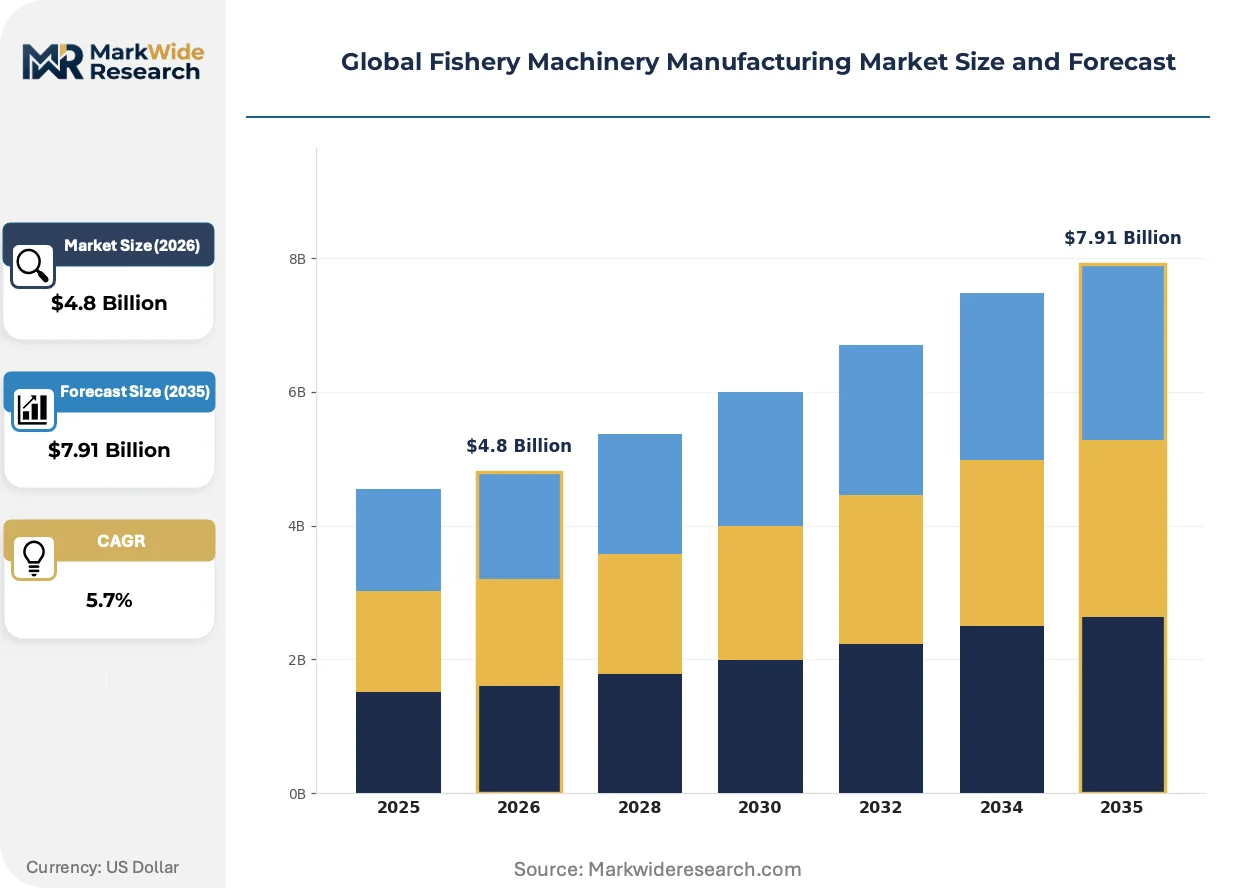
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fishing Vessels, Nets, Traps, Processing Equipment Technology: Automation, Robotics, IoT, Traditional End User: Commercial Fisheries, Aquaculture, Research Institutions, Government Agencies Capacity: Small Scale, Medium Scale, Large Scale, Enterprise |
| Companies Covered | BAADER Group, Carsoe Group A/S, Marel, KM Fish Machinery A/S, Optimar A/S, JBT Corporation, AKVA Group, Bettcher Industries Inc, GEA Group Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fishery Machinery Manufacturing Market Emerging Trajectories
Digital thread architectures are threading through catch documentation and processing traceability, rewriting how fleet operators demonstrate regulatory compliance. The convergence of onboard automation with shore-based data infrastructure is collapsing traditional boundaries between sea and land operations.
Machine vision-based species recognition is supplanting manual sorting stations in high-throughput pelagic processing lines. Icelandic and Norwegian whitefish operators are adopting these systems at accelerated replacement cycles. The technology is supplanting labor-intensive trimming roles while compressing yield loss from misclassification.
China's MEE refrigerant phase-down mandates are forcing redesigns of R22-dependent freezing systems in processing plants serving export markets. Domestic fabricators must retool cold-chain equipment to meet GB standard compliance for low-global-warming-potential alternatives. Shore-based salmon and shrimp processing facilities in Shandong and Liaoning provinces face the steepest retrofit timelines.
Buyers are unbundling after-sales service contracts from equipment procurement, favoring third-party maintenance providers over captive manufacturer networks. Vietnamese and Thai fleet operators are driving this shift through competitive tendering of technical support. The pattern is most visible in deck equipment categories where standardized components reduce vendor lock-in.
Global Fishery Machinery Manufacturing Market Segmentation
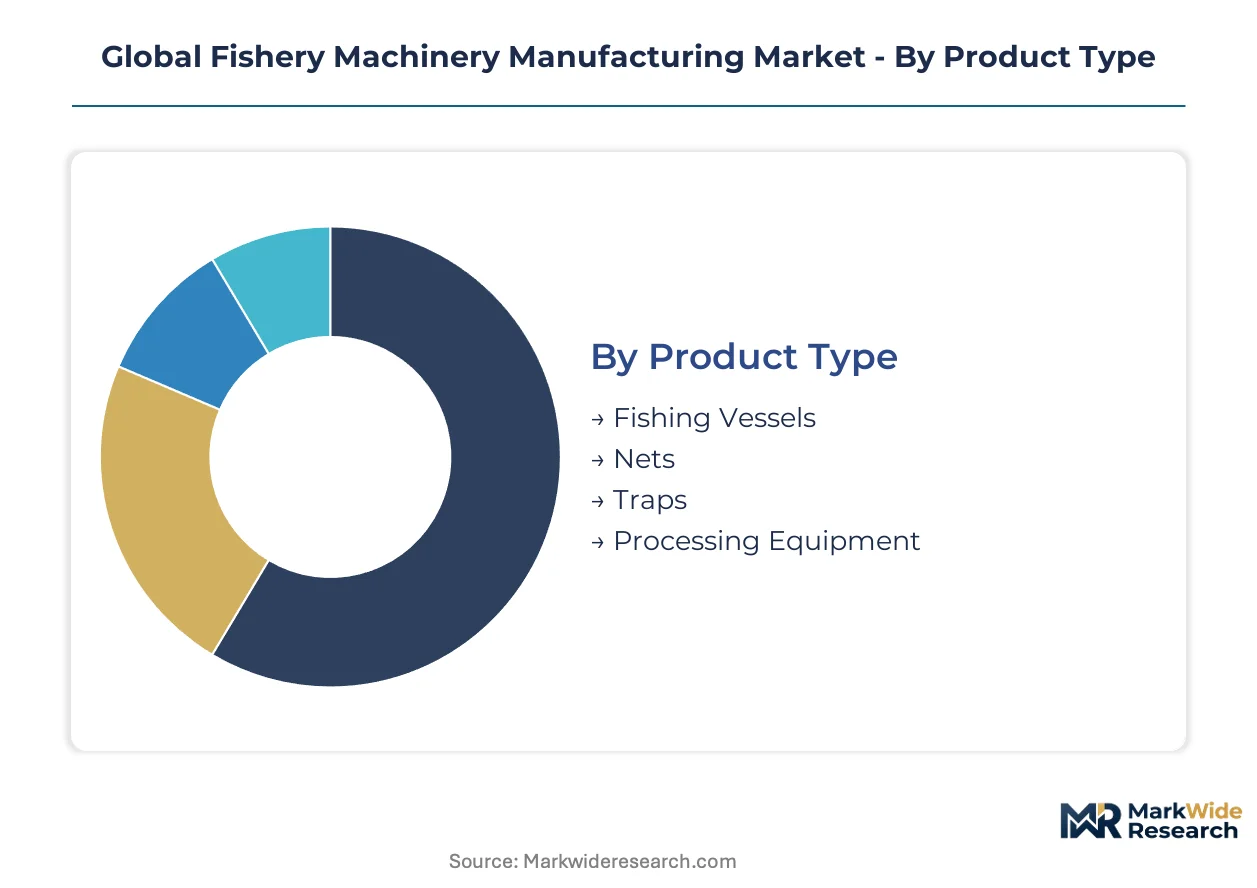
Equipment specialization in fishery machinery tracks regulatory pressure zones and protein supply chain nodes. Segmentation reveals how capital allocation splits between vessel-mounted systems and shore-based processing infrastructure.
Product Type:
CE marking under the EU Machinery Directive and F-Gas refrigerant mandates create divergent compliance burdens across equipment categories.
- Fishing Vessels:Hull-integrated machinery including winches, trawling gear, and live-fish tanks. Norwegian operators are replacing aging steel-hulled fleets with aluminum-composite designs that reduce fuel consumption while accommodating heavier deck equipment loads.
- Processing Equipment:Onshore filleting lines, freezing systems, and packaging units constructed with 316L stainless steel and IP67 electrical enclosures. Danish and Spanish processors face accelerated replacement cycles driven by EU F-Gas refrigerant phase-down schedules.
- Nets:Synthetic fiber trawls and purse seines with integrated acoustic sensors. Vietnamese commercial fleets are scaling mechanized net handling systems to meet export certification requirements.
- Traps:Pot and creel systems for crustacean and demersal species. Lobster fisheries in Maine and Atlantic Canada favor collapsible designs that reduce deck storage footprint.
Processing equipment handles the majority of throughput; automation-integrated processing lines are gaining share fastest as operators replace mechanical controls.
Technology:
Capital intensity separates technology tiers, with sensor-driven systems commanding premium pricing against mechanical alternatives.
- Automation:Programmable logic controllers, automated grading systems, and continuous processing lines. Icelandic whitefish operators deploy machine vision-based species recognition to compress yield loss from misclassification.
- IoT:Connected sensors for catch monitoring, equipment diagnostics, and fleet management. Peruvian anchovy fleets integrate real-time biomass tracking with shore-based quota management systems.
- Robotics:Articulated arms for precision trimming and packaging operations. Labor cost pressures in Norway and Japan accelerate adoption in high-throughput salmon processing.
- Traditional:Mechanical controls, hydraulic systems, and manual processing stations. Indonesia's artisanal fleet maintains substantial installed base of conventional deck equipment.
Traditional technology retains volume leadership in emerging fishing nations; automation is expanding most quickly in regulated European and North American waters.
End User:
Procurement authority and subsidy access determine equipment specification tiers across user categories.
- Commercial Fisheries:Industrial-scale operators with fleet-wide standardization protocols. Southeast Asian purse seiners are scaling mechanized upgrades to meet rising domestic and export protein demand.
- Aquaculture:Cage-based feeding systems and shore-based processing for farmed species. AKVA Group's integrated monitoring architectures dominate Norwegian salmon production clusters.
- Research Institutions:Specialized sampling equipment and precision measurement systems. Marine science vessels require modular deck configurations for multi-mission flexibility.
- Government Agencies:Patrol vessels and enforcement craft with surveillance-grade specifications. Coast guard procurement favors domestic fabricators under local content mandates.
Commercial fisheries absorb the dominant share of capital expenditure; aquaculture represents the steepest expansion trajectory as farmed seafood output climbs.
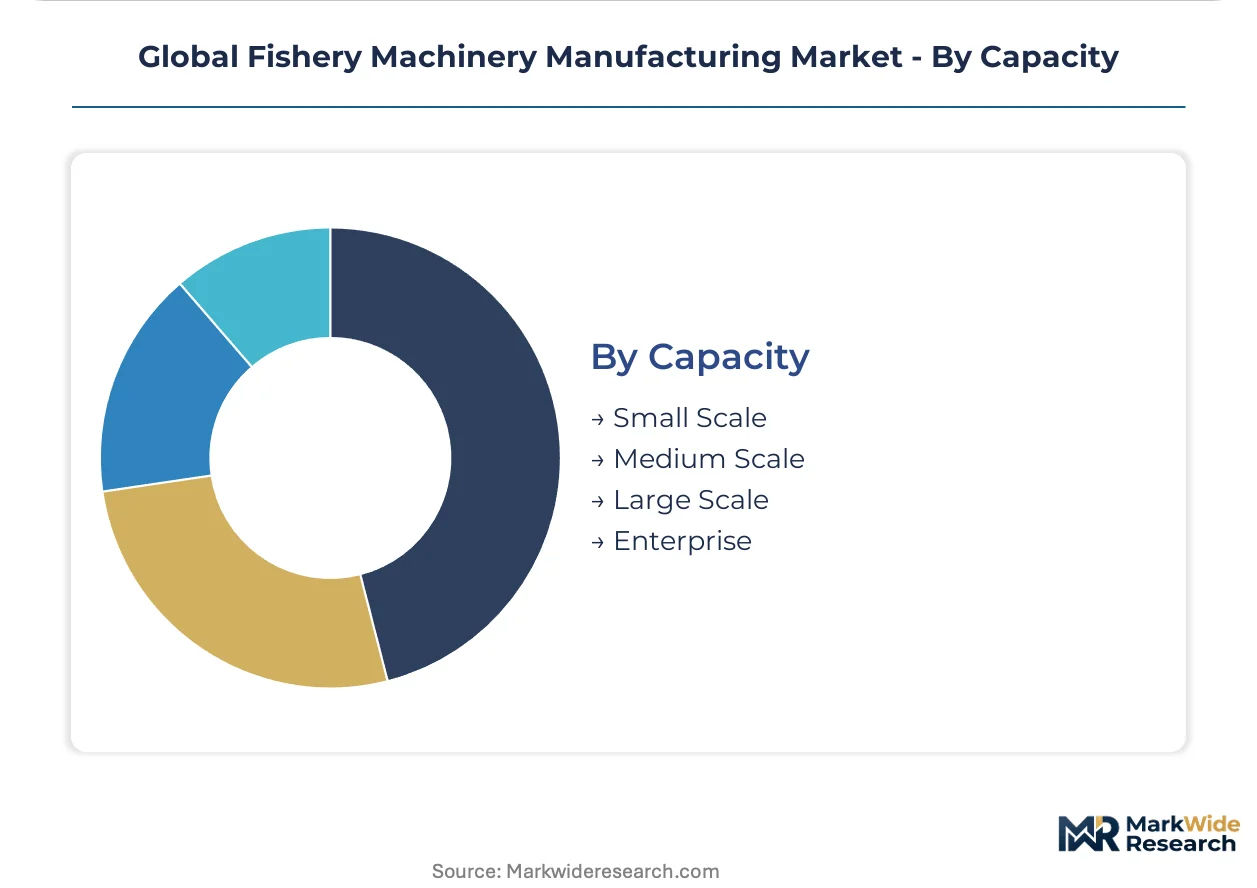
Capacity:
Scale determines equipment modularity, with compact systems designed for tropical corrosion conditions serving underpenetrated segments.
- Large Scale:Factory trawlers and enterprise processing plants with continuous throughput architectures. China's distant-water fleet upgrades focus on onboard freezing capacity for multi-week voyages.
- Enterprise:Vertically integrated operations spanning catch, processing, and distribution. Thai Union and Maruha Nichiro deploy standardized equipment specifications across multi-flag operations.
- Medium Scale:Regional processors and mid-sized vessel operators. Vietnamese fleet modernization programs target this tier with subsidized mechanization loans.
- Small Scale:Artisanal vessels and coastal processing cooperatives. Indonesian and Philippine municipal fisheries present white space for compact, modular units.
Large scale operations concentrate equipment value; small scale segments are climbing fastest on mechanization subsidies and fleet upgrade programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration tilts toward fleet operators in Norway, China, and Vietnam who command procurement scale for integrated processing systems. These three markets absorb disproportionate capital flows for deck equipment and onshore automation. Regulatory divergence across the EU F-Gas Regulation, China's MEE refrigerant mandates, and ASEAN subsidy programs fragments supplier access patterns.
Norway
Whitefish and salmon processors drive replacement cycles for legacy mechanical controls with sensor-driven automation. CE marking under the EU Machinery Directive shapes export eligibility for equipment serving European fleet operators. The Bergen-Stavanger corridor anchors advanced processing clusters where onshore plants integrate machine vision-based grading systems.
China
Distant-water fleet operators prioritize onboard freezing capacity for multi-week voyages serving export markets. MEE refrigerant phase-down schedules force redesigns of R22-dependent processing systems in Shandong and Liaoning facilities. Qingdao-based fabricators retool cold-chain equipment to meet GB standard compliance for low-global-warming-potential alternatives.
Vietnam
Commercial purse seiners scale mechanized net handling and catch processing to satisfy rising domestic and export protein requirements. Government subsidized mechanization loans target medium-scale fleet operators for equipment upgrades. Ho Chi Minh City and Da Nang concentrate processing infrastructure where operators unbundle after-sales contracts from procurement.
Denmark
Whitefish processors face accelerated equipment turnover driven by EU F-Gas refrigerant phase-down mandates for cold-chain dependent lines. The Danish fleet operates under strict discard reduction protocols from Common Fisheries Policy reforms. Skagen and Hirtshals harbor processing clusters where automation-integrated lines replace legacy mechanical systems.
Indonesia
Artisanal vessel segments present white space for compact, modular processing units engineered for tropical corrosion conditions. Municipal fisheries in Sulawesi and Maluku provinces maintain substantial installed base of traditional deck equipment. Surabaya and Makassar serve as distribution nodes for fleet mechanization programs targeting small-scale operators.
Global Fishery Machinery Manufacturing Market Vendor Landscape
Player mix skews toward European specialists with integrated automation portfolios and Asian fabricators serving cost-sensitive fleet segments. Market structure concentrates around Norwegian and Danish engineering houses that anchor premium-tier positioning through CE marking compliance and cold-chain expertise. Two strategic archetypes dominate: automation-integrated system suppliers and corrosion-resistant component specialists. Competitive moves center on geographic expansion into Southeast Asian fleet upgrade cycles and technology licensing partnerships for sensor-filtration convergence.
Within the European specialist tier, BAADER Group and Marel exemplify integrated system suppliers that occupy positions across whitefish and pelagic processing lines. AKVA Group anchors the aquaculture automation vector through cage-to-shore monitoring architectures. Among Danish engineering houses, KM Fish Machinery A/S and Optimar A/S represent corrosion-resistant fabrication expertise serving North Atlantic fleet operators. These named entities illustrate how geographic origin and company structure correlate with strategic archetype positioning rather than claiming specific market shares or product configurations.
| Leading Market Players |
|---|
| BAADER Group |
| Carsoe Group A/S |
| Marel |
| KM Fish Machinery A/S |
| Optimar A/S |
| JBT Corporation |
| AKVA Group |
| Bettcher Industries Inc |
| GEA Group Aktiengesellschaft |
| Others |
Supply Flow & Price Mechanics
Factory trawler scale economies in Norway and China's distant-water fleet anchor price floors through volume procurement leverage and captive maintenance networks. CE marking compliance costs and stainless steel input volatility feed directly into supplier pricing power, compressing margins for mid-tier fabricators serving price-sensitive Southeast Asian operators.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate procurement agreements for 316L stainless steel processing surfaces. Three-tier pricing structure across premium automation-integrated systems, standard mechanical controls, and economy-grade traditional equipment reflects CE certification status and after-sales bundling intensity. Pricing pressure stems from Indonesian ore export policy volatility and Vietnamese fleet operators unbundling service contracts from equipment purchases. Small-scale artisanal segments in Indonesia and the Philippines exhibit highest price sensitivity, while Norwegian salmon processors absorb premium automation premiums with minimal elasticity.
Supply Chain Analysis
Inventory cycles for IP67-rated electrical enclosures and corrosion-resistant drive components extend lead times for European fabricators serving North Atlantic fleets. Supply concentrates in Germany for precision drive systems, Denmark for stainless steel fabrication expertise, and China for compact modular units targeting tropical conditions. Raw material dependencies span Indonesian nickel ore, South African chromium, and Japanese precision bearings. Single-source vulnerability concentrates in specialized marine electrical components from Nordic engineering houses. Distribution runs through Bergen-Stavanger and Qingdao-anchored clusters for premium systems, with Surabaya and Ho Chi Minh City serving emerging market tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across Vietnamese purse seine cooperatives and Chinese distant-water state enterprises concentrates procurement leverage, shifting bargaining power toward buyers with volume standardization protocols.
For Market Incumbents: Secure automation-integrated processing line positions through backward integration into sensor-filtration convergence technologies, defending against modular Chinese entrants targeting ASEAN mechanization subsidies. Prioritize ISO 14001 certification maintenance to preserve EU Green Deal procurement channel access as public fleet modernization programs expand. For New Entrants and Emerging Players: CE marking fast-track partnerships with Danish and Norwegian engineering consultancies enable white-space penetration into Indonesian artisanal fleet segments demanding compact tropical-corrosion-resistant deck equipment. Target medium-scale Vietnamese operators through government-subsidized mechanization loan channels with unbundled third-party service support. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aquaculture automation specialists with cage-to-shore monitoring architectures as farmed seafood output climbs fastest. Long-term viability centers on sensor-driven species recognition capabilities displacing labor-intensive manual sorting. Watch for IMO energy efficiency standard finalization as capital reallocation signal between hull machinery and propulsion systems.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Integration Partnership | Machine vision-based grading systems compress yield loss for Icelandic whitefish operators. |
| CE Marking Fast-Track Investment | EU Machinery Directive compliance accelerates product launch schedules against Nordic incumbents. |
| Tropical Corrosion Engineering Center | Modular deck equipment designs penetrate Indonesian artisanal fleet upgrade programs. |
| Sensor-Filtration Convergence R&D | Real-time biomass monitoring enables precision catch allocation across multi-species operations. |
| After-Sales Service Unbundling | Third-party maintenance networks reduce vendor lock-in for Vietnamese fleet operators. |
Methodological Framework
Cross-validation between vessel operator procurement interviews and customs trade data anchors the qualitative findings on fleet mechanization trajectories. Primary fieldwork engaged fleet managers at Norwegian salmon processors, Danish whitefish engineering houses, Vietnamese purse seine cooperatives, and Chinese distant-water operators. Secondary validation drew from EU Common Fisheries Policy implementation reports, MEE refrigerant phase-down schedules, IMO vessel efficiency consultations, and stainless steel trade flow databases. Bottom-up equipment shipment analysis and top-down protein demand modeling triangulate market sizing.
Sensitivity analysis around nickel price volatility scenarios and ASEAN subsidy program continuity frames the projection horizon. Segmentation dimensions span product type, technology tier, end-user category, and vessel capacity scale, with regional regulatory cluster as the fishery-specific modeling layer. CAGRs derive from replacement cycle compression rates in automation-adopting fleets versus traditional technology persistence in emerging markets. Forecast inputs incorporate EU F-Gas refrigerant mandate timelines and China's MEE cold-chain retrofit schedules.
Underlying assumptions cover continued protein demand growth in Southeast Asia, with deviation risk concentrated in Indonesian ore export policy shifts and IMO energy efficiency standard implementation timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market