
 Global Tillage Equipment Market | 2026-2036
Global Tillage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tillage Equipment Market Outlook
High-horsepower compatibility is collapsing the historical gap between premium European implements and mid-tier North American offerings. Deere & Company leverages its integrated precision agriculture platform to bundle tillage tools with telemetry subscriptions. CNH Industrial N.V. anchors its Case IH brand in conservation tillage through dedicated strip-till and vertical-tillage product lines. AGCO Corporation differentiates via Fendt-branded high-speed disc systems engineered for minimum soil disturbance at transport speeds above 15 mph.
Tillage equipment comprises soil-working implements—typically constructed from boron steel discs, spring-cushioned shanks, and reversible points—designed to prepare seedbeds, manage residue, and control compaction in agricultural soils. Primary tillage tools operate at depths of 15–30 cm to fracture hardpan layers, while secondary implements finish surfaces at 5–10 cm for planter readiness. Harrows and cultivators lead volume shipments across the product type dimension, reflecting their versatility in both conventional and reduced-tillage systems. Fully automated and smart equipment categories capture expanding margin pools as ISOBUS-compatible implements with section control and variable-depth automation command price premiums over manual configurations. The end-use split shows agriculture dominating absolute units while horticulture and grounds maintenance segments drive compact tractor attachment demand.
EPA Tier 4 Final and EU Stage V emissions frameworks shape engine-powered self-propelled tillage units, forcing exhaust after-treatment retrofits that inflate capital costs and accelerate replacement cycles. Brazil's CONAMA resolutions and India's CEA agricultural mechanization directives add compliance layers for equipment sold into subsidized credit programs. Stakeholders must monitor convergence between carbon credit protocols and tillage practice verification, as soil carbon sequestration claims increasingly require GPS-documented pass records and residue retention thresholds.
Market Dynamics
Precision agriculture platforms are compressing replacement cycles for tillage implements as large-scale operators demand ISOBUS-compatible tools with real-time telemetry integration.
Growth Catalysts
- EPA Tier 4 Final compliance:Exhaust after-treatment mandates accelerate diesel engine upgrades across tractor-towed implements, forcing capital deployment into new equipment purchases.
- Brazil's Cerrado expansion zones:No-till transitions in this agricultural frontier generate specialized demand for disc harrows and strip-till rigs suited to tropical soil conditions.
- Boron steel disc adoption:Extended wear life and reduced maintenance intervals justify premium pricing for high-speed tillage systems in row-crop operations.
Market Restraints
- Steel price volatility:Boron alloy and spring steel input costs fluctuate with global commodity markets, squeezing manufacturer margins on fixed-price contract sales.
- EU Stage V retrofit costs:Exhaust after-treatment systems add substantial capital burden to self-propelled tillage units, dampening demand from mid-tier buyers.
- Precision tillage skill scarcity:Variable-depth automation and section control systems require trained operators, limiting adoption in regions with thin technical service infrastructure.
Strategic Opportunities
- India's CEA mechanization directives:Subsidized credit programs for agricultural equipment create entry pathways for conservation tillage tools in underpenetrated districts.
- Carbon credit protocol convergence:GPS-documented pass records and residue retention thresholds enable soil carbon sequestration verification, opening revenue streams for data-integrated implements.
- Horticulture attachment demand:Compact tractor tillage tools for grounds maintenance and specialty crop sectors remain underserved relative to row-crop equipment.
Industry Challenges
- ISOBUS integration complexity:Legacy tractor fleets lack compatible harnessing and display terminals, forcing retrofit costs that stall precision tillage upgrades.
- Certification timeline compression:Simultaneous EPA, EU Stage V, and Brazil CONAMA resolution compliance requires parallel testing programs that strain engineering resources.
- Dealer service capacity constraints:Section control diagnostics and telematics troubleshooting demand technician training investments that independent distributors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tillage Equipment Market |
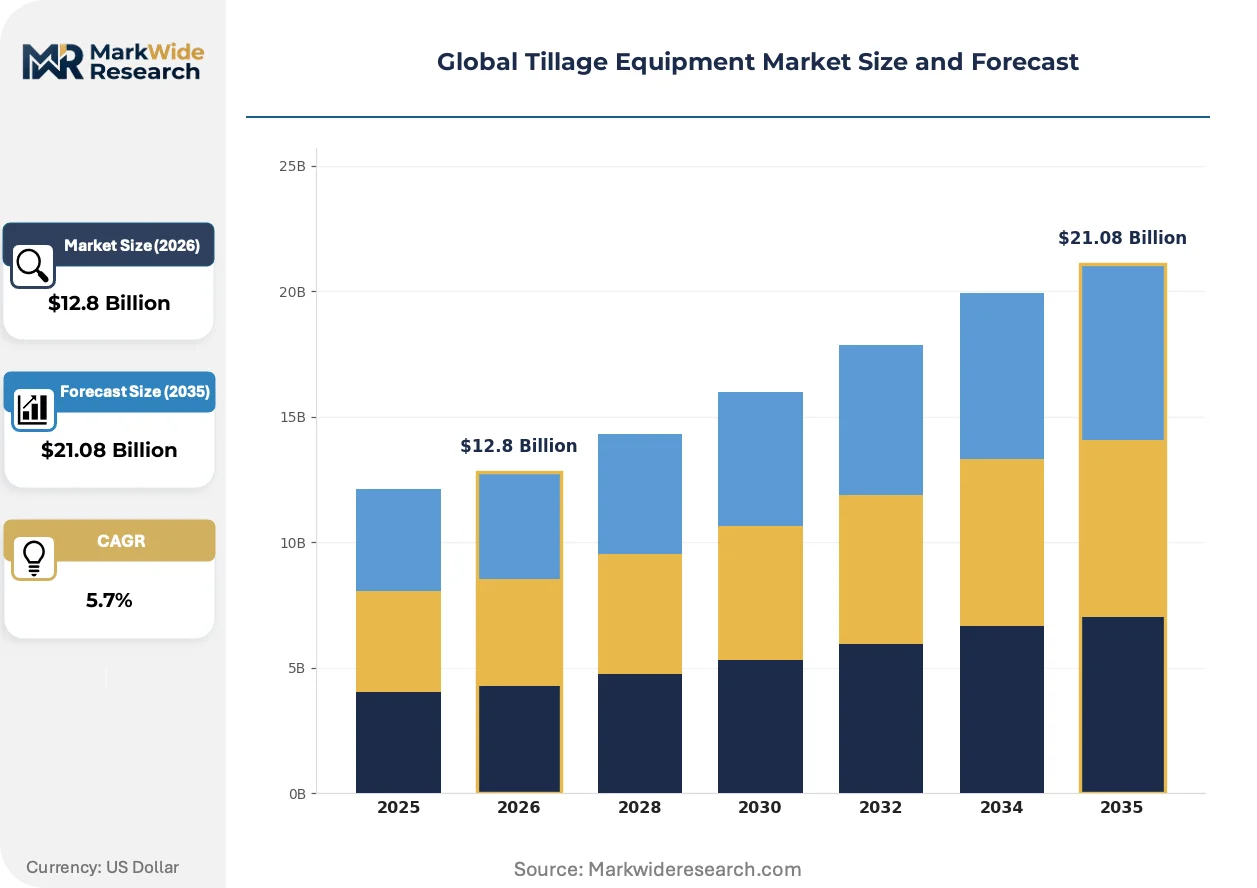
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plows, Harrows, Cultivators, Seeders End Use: Agriculture, Horticulture, Landscaping, Grounds Maintenance Technology: Manual, Semi-Automated, Fully Automated, Smart Equipment Sales Channel: Direct Sales, Online Retail, Distributors, Agricultural Shows |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, KUBOTA Corporation, Alamo Group Inc., Mahindra & Mahindra Ltd., ISEKI and CO.LTD., Case IH, Great Plains Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tillage Equipment Market Strategic Shifts
Autonomous tillage systems and sensor-integrated implements are redefining soil management economics, shifting value capture from mechanical durability to data-driven performance optimization.
High-speed disc systems engineered for minimum soil disturbance are decomposing the traditional trade-off between tillage depth and transport efficiency. Large-scale corn and soybean operations in the US Corn Belt are adopting these platforms at accelerated rates. The technology is decomposing historical equipment utilization models by enabling 15-plus mph field speeds without compromising seedbed quality.
EU Stage V emissions frameworks are forcing exhaust after-treatment retrofits across self-propelled tillage equipment categories. These mandates inflate capital costs and compress replacement cycles for diesel-powered units. Eastern European contractors face particular pressure as aging fleets confront simultaneous compliance deadlines and precision upgrade requirements.
Equipment-as-a-service models are emerging among fleet operators seeking to unbundle capital expenditure from seasonal utilization risk. Dealer networks and manufacturer finance arms are piloting subscription-based tillage tool access with bundled telemetry and maintenance. This shift is most visible in Brazil's subsidized credit zones where cash-flow-sensitive growers prioritize operational flexibility over ownership.
Global Tillage Equipment Market Segmentation
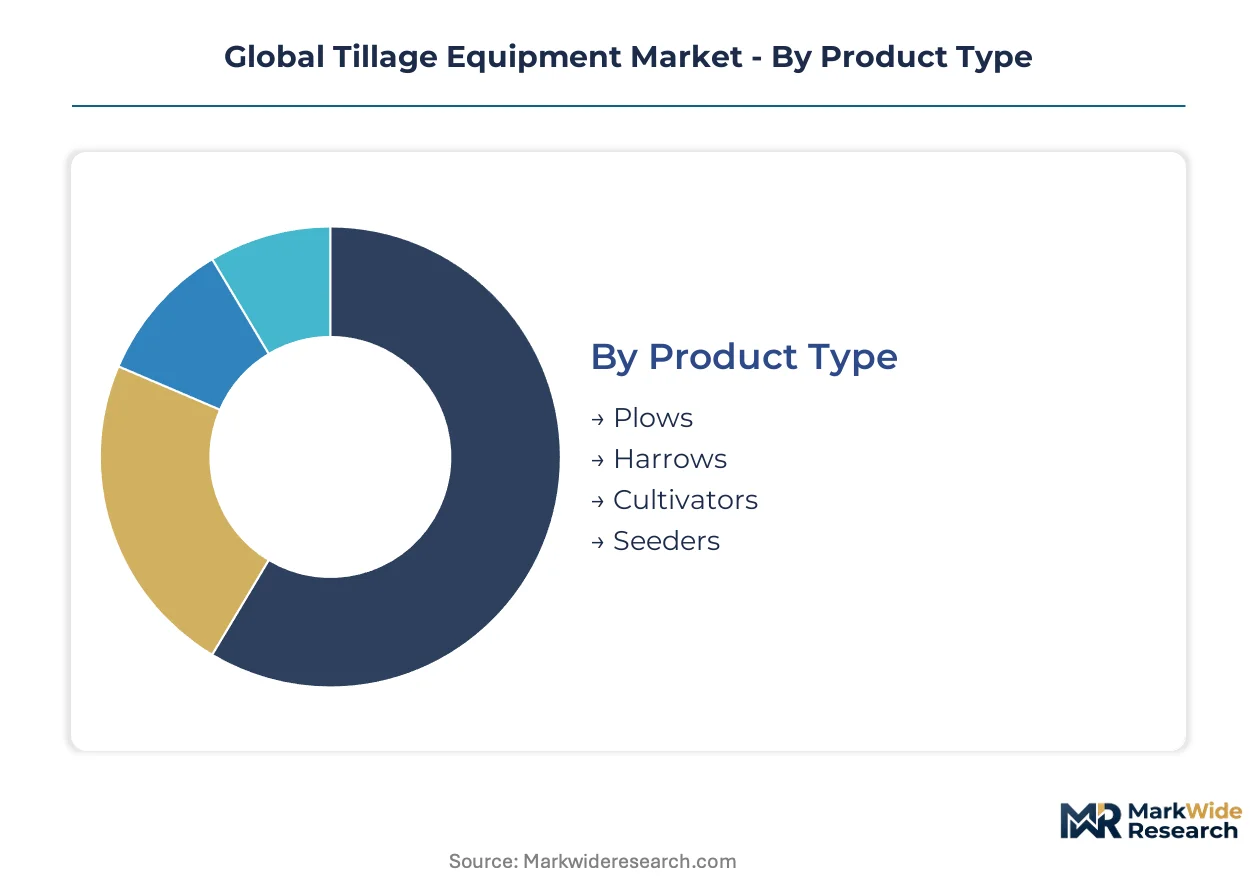
Tillage equipment segmentation reveals distinct margin architectures across mechanical, digital, and service layers. Equipment configuration, operational intensity, and buyer sophistication create four discrete category systems with uneven profit distribution.
Product Type:
Higher margin capture concentrates in implements engineered for residue management under precision agriculture protocols.
- Harrows:Disc and tine configurations constructed from boron steel alloys deliver extended wear life in high-residue corn-soybean rotations. Demand clusters in Brazil's Cerrado expansion zones where no-till transitions require specialized disc systems for tropical soil conditions.
- Cultivators:Spring-cushioned shank assemblies with reversible points dominate secondary tillage for seedbed finishing. US Corn Belt operators deploy these implements for controlled traffic farming systems that limit compaction in 24-row planter environments.
- Plows:Moldboard and chisel configurations serve primary tillage in regions with heavy clay soils or perennial weed pressure.
- Seeders:Combined tillage-planting units integrate seed placement with residue management in single-pass operations.
The dominant share belongs to Harrows, while Cultivators are gaining share fastest through conservation tillage adoption.
End Use:
Application intensity and equipment utilization rates determine pricing power across buyer categories.
- Agriculture:Row-crop and broadacre operations drive absolute unit volumes with seasonal replacement cycles tied to planting windows. Large-scale operators in Iowa, Illinois, and Mato Grosso prioritize ISOBUS-compatible implements with section control for input optimization.
- Horticulture:Specialty crop producers and vegetable operations require compact tractor attachments with precision depth control for bed formation. California's Central Valley and Almeria's greenhouse complexes generate concentrated demand for raised-bed tillage systems.
- Landscaping:Commercial turf and estate maintenance applications favor walk-behind and sub-compact tractor implements.
- Grounds Maintenance:Municipal parks, golf courses, and institutional campuses sustain steady demand for aeration and renovation equipment.
Agriculture commands the volume base, though Horticulture exhibits the steepest expansion trajectory as protected cultivation spreads.
Technology:
Automation tier directly correlates with service revenue attachment and replacement cycle compression.
- Smart Equipment:Sensor-integrated implements with real-time soil sensing and variable-rate depth adjustment command premium positioning. Australian broadacre contractors and Ukrainian agroholdings deploy these systems for GPS-documented pass records supporting carbon credit verification.
- Fully Automated:ISOBUS-compatible tools with section control and telematics integration enable precision agriculture platform bundling. German and Dutch farming cooperatives lead adoption where technician density supports diagnostic infrastructure.
- Semi-Automated:Hydraulic depth control and mechanical automation reduce operator fatigue without full telemetry integration.
- Manual:Basic mechanical configurations serve smallholder and developing market segments with price-sensitive procurement patterns.
Smart Equipment holds the margin concentration, while Fully Automated systems are climbing the fastest through OEM platform integration strategies.
Sales Channel:
Channel structure reflects capital intensity, technical service requirements, and buyer relationship depth.
- Distributors:Independent dealer networks dominate capital equipment flows through floorplan financing and seasonal inventory programs. Midwest US and São Paulo state networks maintain the densest service technician coverage for precision tillage diagnostics.
- Direct Sales:OEM-captive sales forces serve enterprise accounts and fleet operators with customized specification and volume pricing. Major grain producers in Saskatchewan and Queensland negotiate direct procurement for 50-plus implement orders.
- Agricultural Shows:Demo events and field days concentrate purchase decisions through side-by-side performance validation.
- Online Retail:E-commerce platforms capture attachment and wear-part sales with limited penetration for primary implements.
Distributors retain the structural share, though Direct Sales is expanding most quickly through consolidated farm enterprise growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for tillage equipment varies sharply by geography. Brazilian and Indian buyers exhibit acute price sensitivity under subsidized credit constraints, while US and German operators absorb premium pricing for precision-enabled implements.
United States
The US Corn Belt drives high-horsepower implement demand through 24-row controlled traffic farming systems. EPA Tier 4 Final compliance forces exhaust after-treatment retrofits that accelerate replacement cycles across Iowa and Illinois tractor fleets. Moline-based manufacturing clusters and Des Moines distribution hubs concentrate precision tillage production for North American export.
Brazil
Mato Grosso and Goiás states in the Cerrado expansion zone generate specialized demand for disc harrows and strip-till rigs suited to tropical no-till transitions. CONAMA resolutions layer emissions compliance onto subsidized credit programs through BNDES rural financing directives. Ribeirão Preto and Sorocaba industrial corridors anchor South American tillage equipment assembly for Mercosur distribution.
Germany
EU Stage V regulations impose the strictest exhaust after-treatment mandates across self-propelled tillage categories. Farming cooperatives in Lower Saxony and Schleswig-Holstein lead ISOBUS-compatible implement adoption where technician density supports diagnostic infrastructure. Mannheim and Hanover engineering clusters develop high-speed disc systems for minimum soil disturbance at transport speeds exceeding 15 mph.
India
CEA agricultural mechanization directives channel subsidized credit toward conservation tillage tools in underpenetrated districts of Punjab and Haryana. Smallholder price sensitivity sustains manual and semi-automated equipment procurement patterns despite precision agriculture pilot programs. Ludhiana and Rajkot manufacturing belts produce compact tractor attachments for domestic horticulture and grounds maintenance segments.
China
Dual carbon goals and agricultural modernization policies accelerate diesel engine upgrades across tractor-towed implements in the North China Plain. State-backed mechanization subsidies concentrate demand in Heilongjiang and Henan provinces for primary and secondary tillage tools. Zhengzhou and Luoyang industrial zones supply boron steel disc systems for domestic row-crop operations and Belt and Road export markets.
Global Tillage Equipment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the tillage equipment sector. The market structure consolidates around integrated agricultural machinery conglomerates with captive distribution networks, while regional fabricators compete on price-sensitive contract manufacturing. Three strategic archetypes dominate: precision agriculture platform bundlers, conservation tillage specialists, and emerging market volume producers. Competitive dynamics center on M&A consolidation of implement manufacturers by tractor OEMs and geographic expansion through dealer network acquisition in subsidized credit zones.
Among integrated machinery conglomerates, Deere & Company and CNH Industrial N.V. exemplify platform-bundling archetypes that leverage telemetry subscriptions to lock in implement replacement cycles. AGCO Corporation occupies a position within the high-speed precision tier through Fendt-branded systems engineered for minimum soil disturbance. KUBOTA Corporation represents the compact equipment specialist archetype, anchoring horticulture and grounds maintenance segments with sub-compact tractor attachment portfolios.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| KUBOTA Corporation |
| Alamo Group Inc. |
| Mahindra & Mahindra Ltd. |
| ISEKI and CO.LTD. |
| Case IH |
| Great Plains Manufacturing |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 Final and EU Stage V emissions frameworks simultaneously gate supplier qualification and stratify price tiers, forcing exhaust after-treatment certification as a mandatory cost layer that separates premium ISOBUS-compatible implement manufacturers from uncertified fabricators serving price-sensitive segments.
Pricing Analysis
After-sales service contracts and telemetry subscriptions now drive lifetime value capture more than initial equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates precision-enabled platforms with real-time soil sensing from mechanical-only configurations. Pricing pressure stems from steel input volatility squeezing fixed-contract manufacturers. Smallholder cooperatives in India's subsidized credit zones exhibit acute price sensitivity, while Australian broadacre contractors absorb premium positioning for carbon-verification-ready systems.
Supply Chain Analysis
China and Germany anchor boron steel disc production, while Brazil and India concentrate compact tractor attachment assembly. Raw material flows draw from Swedish spring steel, Ukrainian alloy feedstock, and Australian iron ore. Single-source vulnerability concentrates in specialized hydraulic component sourcing from German engineering clusters. Distribution runs through captive dealer networks in North America and subsidized credit channel partners in Mercosur markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as precision agriculture penetration accelerates equipment replacement beyond traditional mechanical wear schedules.
For Market Incumbents: Compound platform stickiness through telemetry subscription bundling that locks implement replacement cycles to tractor OEM ecosystems. Defend against emerging conservation-tillage specialists by deepening backward integration into boron steel disc forging. Prioritize certification investment in EU Stage V and Brazil CONAMA parallel compliance to maintain cross-border qualification. For New Entrants and Emerging Players: CE marking fast-track for ISOBUS-compatible implements opens entry into Eastern European contractor markets where technician density supports diagnostic infrastructure. Target India's CEA-subsidized credit zones with semi-automated cultivators priced below premium precision tiers. Pursue equipment-as-a-service pilot programs with Brazilian BNDES-financed cooperatives seeking operational flexibility over ownership. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart equipment categories as sensor integration and telematics development consume R&D budgets. Long-term viability favors precision-agriculture platform bundlers with recurring revenue attachment over pure-play mechanical fabricators. Monitor carbon credit protocol convergence as the inflection signal for data-integrated implement valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISOBUS Platform Integration | Deere and CNH leverage telemetry subscriptions to lock implement replacement cycles. |
| Backward Integration into Boron Steel | AGCO's in-house disc forging secures wear-life differentiation against contract fabricators. |
| Equipment-as-a-Service Pilot | Brazilian dealer networks trial subscription access to reduce cash-flow barriers for growers. |
| Carbon Credit Data Integration | Australian contractors deploy GPS-documented pass records for soil sequestration verification. |
| CEA Subsidized Credit Channel Entry | Kubota and Mahindra expand compact tractor attachment distribution in Punjab and Haryana. |
Study Parameters
A spread of perspectives from OEM product managers, independent dealer principals, broadacre farm operators, and agricultural cooperative procurement heads converged on the working assumptions. Primary fieldwork combined with secondary validation from USDA equipment shipment data, ANFAVEA production statistics, EU MARD registration databases, and SEC 10-K agricultural machinery segment disclosures. Bottom-up unit forecasts triangulated against top-down machinery investment projections across the analysis window.
Segmentation dimensions modeled include product type configuration, automation tier, end-use intensity, and regional regulatory cluster across the projection horizon. CAGRs derived from equipment replacement cycle compression rates and precision agriculture adoption curves. Industry-specific inputs incorporated EPA Tier 4 Final compliance timelines, Brazil CONAMA resolution phase-ins, and carbon credit protocol verification requirements.
Underlying assumptions cover sustained subsidized credit availability in India and Brazil, with deviation risk concentrated in steel price volatility and technician training bottlenecks. Recalibration cycles align with material shifts in emissions compliance deadlines and precision agriculture platform consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market