
 South Africa Agricultural Machinery Market | 2026-2036
South Africa Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Agricultural Machinery Market Analytics
Multi-source procurement among large commercial farming enterprises is hardening as a dominant sourcing pattern. Deere & Company leverages its precision farming technology portfolio to anchor premium segment positions across the Highveld grain belt. CNH Industrial N.V. competes through extensive dealer networks that sustain aftermarket parts availability in remote agricultural regions. AGCO Corporation differentiates via localized assembly configurations that navigate South Africa's import tariff structures and regional adaptation requirements.
South Africa Agricultural Machinery encompasses powered and towed equipment engineered for soil tillage, planting, crop management, and harvesting operations, typically featuring diesel powertrains rated from 50 to 400 horsepower and hydraulic implements designed for varied terrain conditions. Tractors occupy the largest volume position, though precision farming technology commands disproportionate margin pools as GPS-guided autosteer and variable-rate application systems penetrate commercial operations. Harvesters represent the fastest-growing product category, driven by expanding soybean and sunflower cultivation that demands specialized threshing and separation capabilities.
South Africa's National Regulator for Compulsory Specifications enforces mandatory safety and emissions standards for agricultural equipment imports, while the Department of Agriculture, Land Reform and Rural Development administers mechanization grant programs that shape demand patterns among emerging black commercial farmers. The South African Bureau of Standards certifies conformity to SANS codes for agricultural machinery, creating compliance barriers for unapproved equipment entrants. Stakeholders must monitor evolving carbon taxation frameworks and water-use licensing requirements that will determine equipment specification priorities and financing structures across the sector.
Market Dynamics
Commercial grain operations across the Free State and North West provinces are consolidating equipment procurement into multi-year fleet replacement cycles, compressing dealer margins while elevating precision farming technology requirements.
Growth Catalysts
- Mechanization Grant Programs:The Department of Agriculture, Land Reform and Rural Development directs capital subsidies toward emerging black commercial farmers in Limpopo and Mpumalanga, expanding the addressable buyer base for mid-horsepower tractors.
- Soybean Cultivation Expansion:Rotational cropping patterns across the Highveld are accelerating demand for specialized combine harvesters with advanced threshing and separation systems.
- Emissions Compliance Deadlines:South Africa's National Regulator for Compulsory Specifications mandates Tier 3 engine standards for imported equipment, forcing fleet upgrades among operators holding older diesel powertrains.
Market Restraints
- Import Tariff Structures:Localized assembly requirements and ad valorem duties on fully-built units elevate landed costs for European and North American manufacturers.
- Dealer Network Concentration:Aftermarket parts availability depends on a thin distributor layer concentrated in Gauteng and the Western Cape, extending downtime for remote Free State operations.
- Currency Volatility:Rand-dollar exchange rate swings distort equipment financing terms and compress importer margins on dollar-denominated supply contracts.
Strategic Opportunities
- Eastern Cape Underpenetration:Emerging irrigation schemes in the Eastern Cape present white-space demand for center-pivot systems and matched tillage equipment.
- Telematics-Financing Convergence:Usage-based equipment financing tied to GPS-verified hectare coverage is absorbing interest from commercial banks seeking collateral visibility.
- Water-Use Licensing Alignment:The Department of Water and Sanitation's licensing framework is redirecting capital toward precision irrigation machinery that demonstrates measurable consumption efficiency.
Industry Challenges
- Autosteer Technician Scarcity:GPS-guided system calibration and RTK network maintenance require skills concentrated among a limited pool of dealer-trained specialists.
- SANS Certification Timelines:South African Bureau of Standards conformity assessment delays product launches by six to twelve months, advantaging incumbent suppliers with established approval pathways.
- Legacy Fleet Integration:ISOBUS-compatible implements face interoperability friction with pre-2015 tractors, complicating precision agriculture adoption among smaller commercial operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Agricultural Machinery Market |
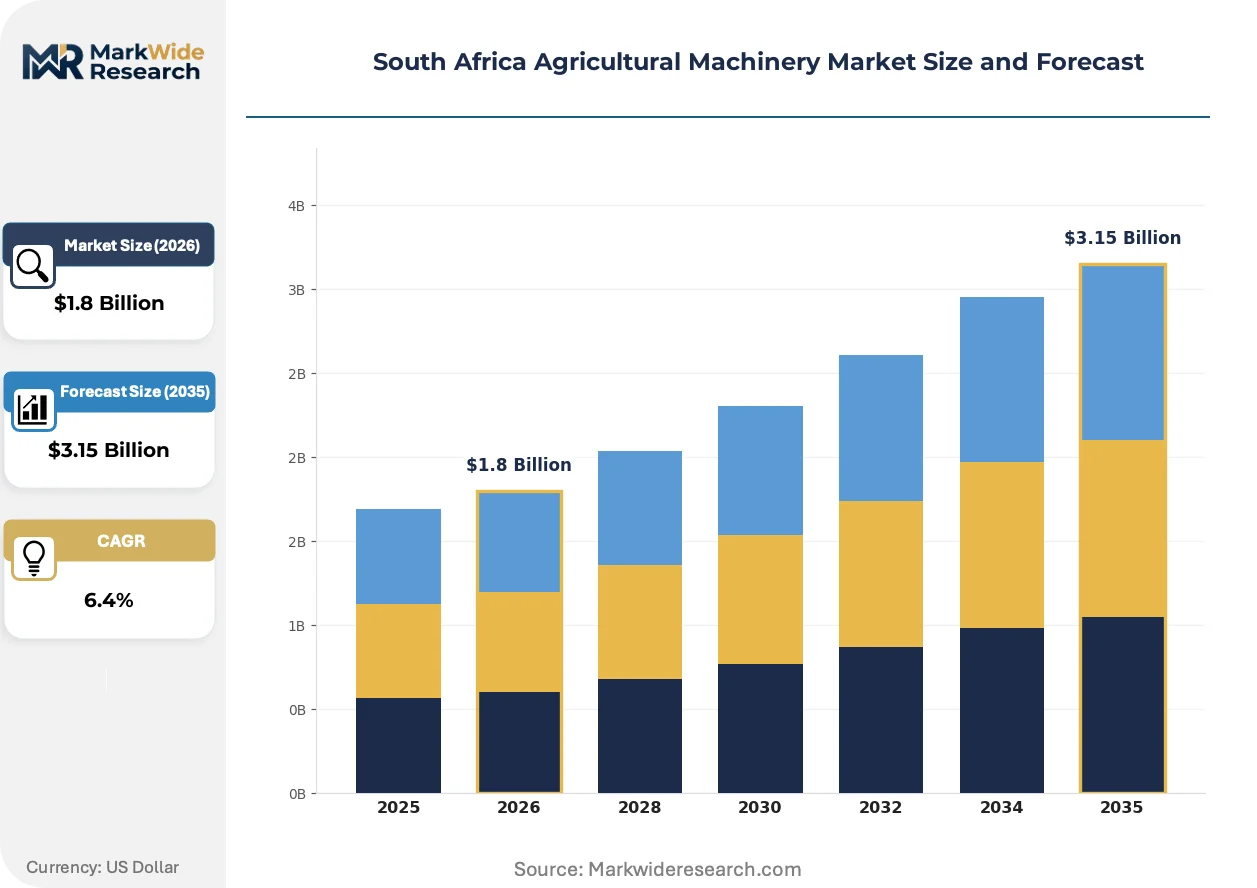
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Seeders, Plows Application: Crop Farming, Livestock Management, Soil Preparation, Irrigation End User: Farmers, Cooperatives, Agricultural Contractors, Government Agencies Technology: Automation, Precision Farming, GPS Tracking, Sensor Technology |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, Kubota Corporation, Mahindra & Mahindra Ltd., Claas KGaA mbH, SDF Group, J.C. Bamford Excavators Ltd., Kuhn Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Agricultural Machinery Market Evolving Landscape
Electrification pressures and data monetization models are restructuring equipment specification priorities across South Africa's commercial farming sector. These shifts are compressing traditional technology adoption curves.
Telematics platforms integrating engine diagnostics, fuel consumption monitoring, and predictive maintenance alerts are absorbing capital allocation from standalone GPS guidance systems. Large-scale maize operations in the Free State are deploying these systems fleet-wide. The structural consequence is that equipment manufacturers are capturing recurring revenue streams through subscription-based data services rather than one-time hardware sales.
South Africa's National Regulator for Compulsory Specifications is tightening safety certification requirements for autonomous operating modes, mandating redundant braking systems and geofencing capabilities. This regulatory friction delays self-driving tractor introductions by twelve to eighteen months. The commercial grain segment is responding by prioritizing semi-autonomous features that fall below the autonomous threshold.
Equipment-as-a-service contracting is displacing traditional installment purchase structures among mid-scale emerging farmers in KwaZulu-Natal. Commercial banks and manufacturer finance arms are unbundling maintenance, insurance, and uptime guarantees into per-hectare usage fees. This behavioral shift is most visible in sugarcane operations where seasonal cash flow volatility makes fixed debt servicing unsustainable.
South Africa Agricultural Machinery Market Segmentation
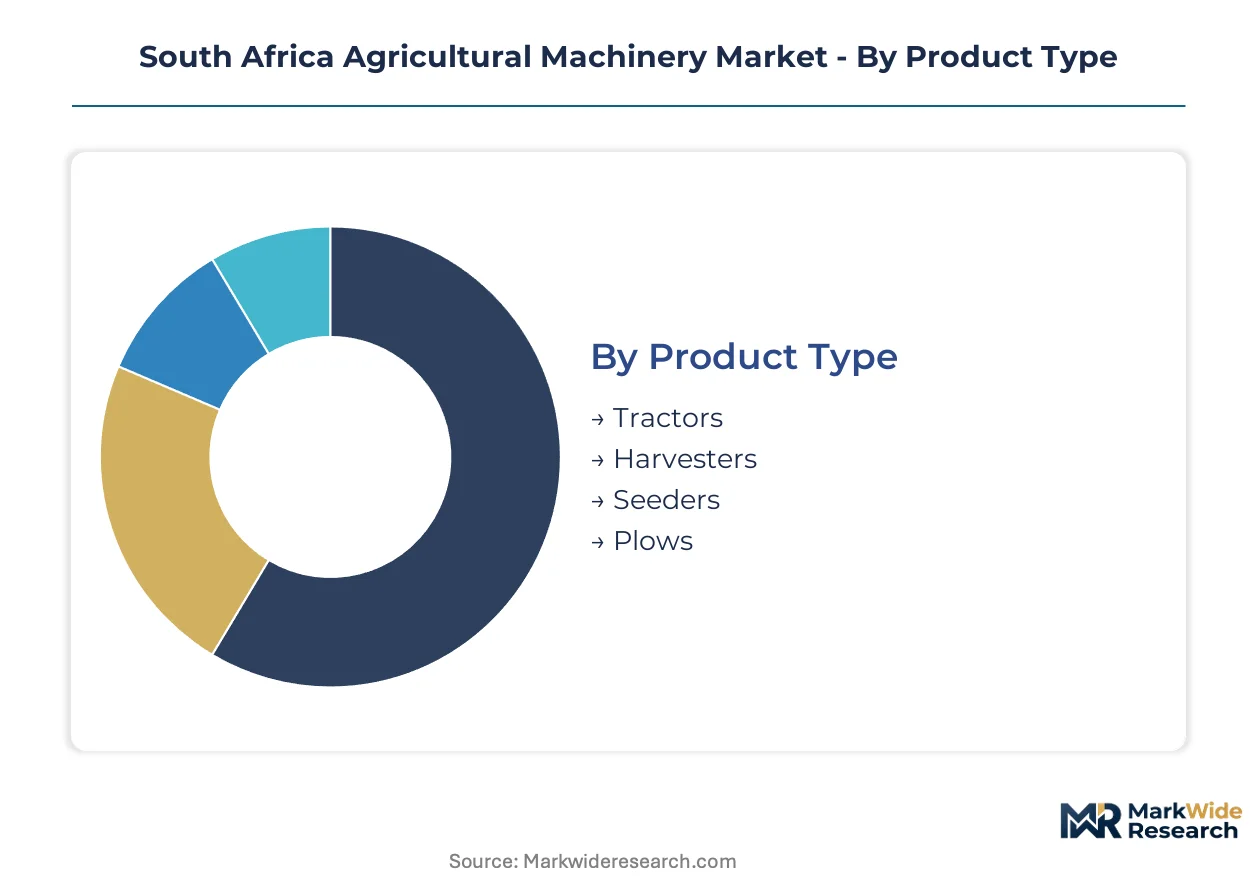
Equipment specification priorities diverge sharply across South Africa's agricultural machinery market. Buyer requirements in the Free State grain belt differ materially from emerging irrigation schemes in the Eastern Cape or livestock operations in the Northern Cape.
Product Type:
Farmers select equipment based on horsepower requirements, implement compatibility, and financing structure rather than brand loyalty alone.
- Tractors:Diesel powertrains rated 50-400 horsepower dominate procurement volumes, with mid-range units between 120-200 horsepower capturing emerging black commercial farmer demand through mechanization grant programs. Free State maize operations are consolidating fleets into fewer, higher-horsepower units with ISOBUS compatibility.
- Harvesters:Specialized threshing and separation systems for soybean and sunflower cultivation are accelerating replacement cycles. North West province grain cooperatives are prioritizing combine harvesters with real-time yield mapping and moisture sensing capabilities.
- Seeders:Precision planting equipment with variable-rate application technology enables accurate seed placement across variable Highveld terrain.
- Plows:Conventional tillage implements retain share among price-sensitive operators, though minimum-tillage alternatives are displacing volumes in conservation agriculture zones.
Tractors lead volumes today; harvesters are gaining share fastest.
Application:
Operational intensity and crop economics determine machinery investment sequencing across South Africa's diverse agricultural zones.
- Crop Farming:Maize, soybean, and sunflower production in the Free State and North West provinces drives the largest equipment procurement volumes. Precision planting and GPS-guided harvesting systems are penetrating commercial operations as labor costs rise and planting windows compress.
- Soil Preparation:Primary and secondary tillage operations require matched tractor-implement configurations that navigate the country's varied terrain conditions. Deep ripping equipment is expanding in former pasture lands converted to grain production.
- Irrigation:Center-pivot and linear-move systems are proliferating in Limpopo and Mpumalanga as water-use licensing frameworks tighten consumption efficiency requirements.
- Livestock Management:Feed handling, fodder processing, and pasture maintenance equipment serves cattle and sheep operations concentrated in the Eastern Cape and KwaZulu-Natal midlands.
Crop farming absorbs the capital allocation; irrigation equipment shows the steepest expansion trajectory.
End User:
Procurement scale and financing access create distinct equipment specification tiers across buyer categories.
- Farmers:Individual commercial operators in the Free State and North West provinces execute multi-year fleet replacement cycles, compressing dealer margins while elevating precision technology requirements. Emerging black commercial farmers in Limpopo access capital subsidies that redirect demand toward mid-horsepower tractors.
- Cooperatives:Aggregated purchasing power enables volume discounts and standardized equipment configurations that simplify maintenance training and parts inventory.
- Agricultural Contractors:Seasonal service providers in KwaZulu-Natal sugarcane zones prioritize equipment utilization rates and rapid turnaround capabilities over feature depth.
- Government Agencies:The Department of Agriculture, Land Reform and Rural Development channels mechanization grants toward specific beneficiary categories, shaping manufacturer go-to-market strategies.
Farmers command the largest share; cooperatives are consolidating procurement fastest.
Technology:
Adoption barriers vary by technical complexity, technician availability, and interoperability with legacy fleet assets.
- Precision Farming:Variable-rate application systems and prescription mapping tools are penetrating large-scale commercial operations that can amortize technology costs across extensive hectare bases. The Free State grain belt leads penetration.
- GPS Tracking:Fleet management and geofencing capabilities support theft recovery and usage verification for financed equipment, particularly valuable in remote agricultural regions.
- Automation:Semi-autonomous features such as GPS-guided autosteer are displacing manual steering in planting and harvesting operations, though fully autonomous modes face regulatory delays from the National Regulator for Compulsory Specifications.
- Sensor Technology:Engine diagnostics, fuel consumption monitoring, and predictive maintenance alerts are capturing capital allocation from standalone guidance systems.
Precision farming dominates current margins; automation is advancing most quickly despite certification friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Free State grain belt anchors South Africa's agricultural machinery demand, with large-scale maize and soybean operations driving fleet consolidation and precision technology adoption across the Highveld.
Free State
Commercial grain cooperatives execute multi-year replacement cycles for combine harvesters and high-horsepower tractors. The Department of Agriculture, Land Reform and Rural Development channels mechanization grants toward emerging black commercial farmers in the eastern districts. Bloemfontein and surrounding agricultural service clusters concentrate dealer networks and aftermarket parts distribution for the province's extensive commercial farming sector.
North West
Soybean cultivation expansion accelerates demand for specialized threshing equipment with real-time yield mapping capabilities. The National Regulator for Compulsory Specifications enforces Tier 3 emissions standards that force fleet upgrades among operators holding older diesel powertrains. Mahikeng and Rustenburg serve as procurement hubs where aggregated cooperative purchasing power secures volume discounts on standardized equipment configurations.
Limpopo
Emerging irrigation schemes and expanding horticulture operations redirect capital toward center-pivot systems and matched tillage equipment. The Department of Water and Sanitation's licensing framework tightens consumption efficiency requirements that favor precision irrigation machinery. Polokwane and the Levubu valley concentrate equipment demand from emerging black commercial farmers accessing mechanization subsidies.
Mpumalanga
Sugarcane operations and diversified crop farming sustain demand for mid-range tractors and seasonal harvesting equipment. The South African Bureau of Standards certifies conformity to SANS codes, creating compliance barriers for unapproved equipment entrants. Nelspruit and the Lowveld agricultural corridor host dealer networks that support high-utilization contracting operations serving fragmented landholdings.
KwaZulu-Natal
Sugarcane mechanization and livestock management equipment absorb capital from mid-scale operations facing seasonal cash flow volatility. Equipment-as-a-service contracting displaces traditional installment purchase structures among emerging farmers. Pietermaritzburg and the Midlands serve as financing and service hubs where commercial banks pilot usage-based equipment financing tied to GPS-verified hectare coverage.
South Africa Agricultural Machinery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision technology and localized assembly configurations. The market structure consolidates around three dominant supplier archetypes: premium technology integrators, extensive dealer network operators, and tariff-optimized local assemblers. Competitive positioning hardens through multi-year fleet contracts, aftermarket parts availability guarantees, and financing partnerships with commercial banks. M&A activity concentrates on dealership consolidation, while strategic partnerships focus on telematics integration and predictive maintenance platforms.
Among premium-tier technology providers, Deere & Company and CNH Industrial N.V. occupy positions anchored by precision farming portfolios and extensive service infrastructures. AGCO Corporation sits within the localized assembly tier, navigating South Africa's import tariff structures through regional adaptation configurations. Kubota Corporation and Mahindra & Mahindra Ltd. represent the mid-horsepower volume segment, capturing emerging farmer demand through mechanization grant program alignment and competitive financing structures.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra Ltd. |
| Claas KGaA mbH |
| SDF Group |
| J.C. Bamford Excavators Ltd. |
| Kuhn Group |
| Others |
Value Network & Pricing Analysis
Electrification pressures and telematics integration are simultaneously elevating R&D cost burdens and concentrating procurement leverage among manufacturers with captive software development capabilities. Tier 3 emissions compliance deadlines from South Africa's National Regulator for Compulsory Specifications are compressing margins on legacy diesel platforms while rewarding suppliers with certified engine architectures already in production.
Pricing Analysis
Steel and hydraulic component cost pass-through from European and Asian suppliers is elevating landed equipment prices by mid-single-digit percentages annually. Pricing stratifies across premium precision-farming tiers anchored by Deere and CNH Industrial, standard mid-horsepower segments served by AGCO and Kubota, and economy tiers dominated by Mahindra's localized assembly configurations. Pricing pressure stems from rand-dollar volatility distorting import financing terms, with emerging black commercial farmers in Limpopo and Mpumalanga exhibiting highest price sensitivity due to grant-dependent capital constraints.
Supply Chain Analysis
Skilled technician shortages in Germany, the United States, and Japan are extending lead times for precision guidance system components and Tier 3-certified engine modules. South African assembly operations draw from Chinese steel forgings, Indian hydraulic systems, and European electronic control units. Single-source vulnerability concentrates in GPS receiver chipsets and RTK correction network hardware. Distribution runs through Gauteng-based master distributors with satellite stocking points in Bloemfontein and Nelspruit serving Free State and Lowveld farming corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's agricultural machinery market functions as a regulatory compounder where Tier 3 emissions mandates and mechanization grant programs are accelerating fleet turnover among commercial operators.
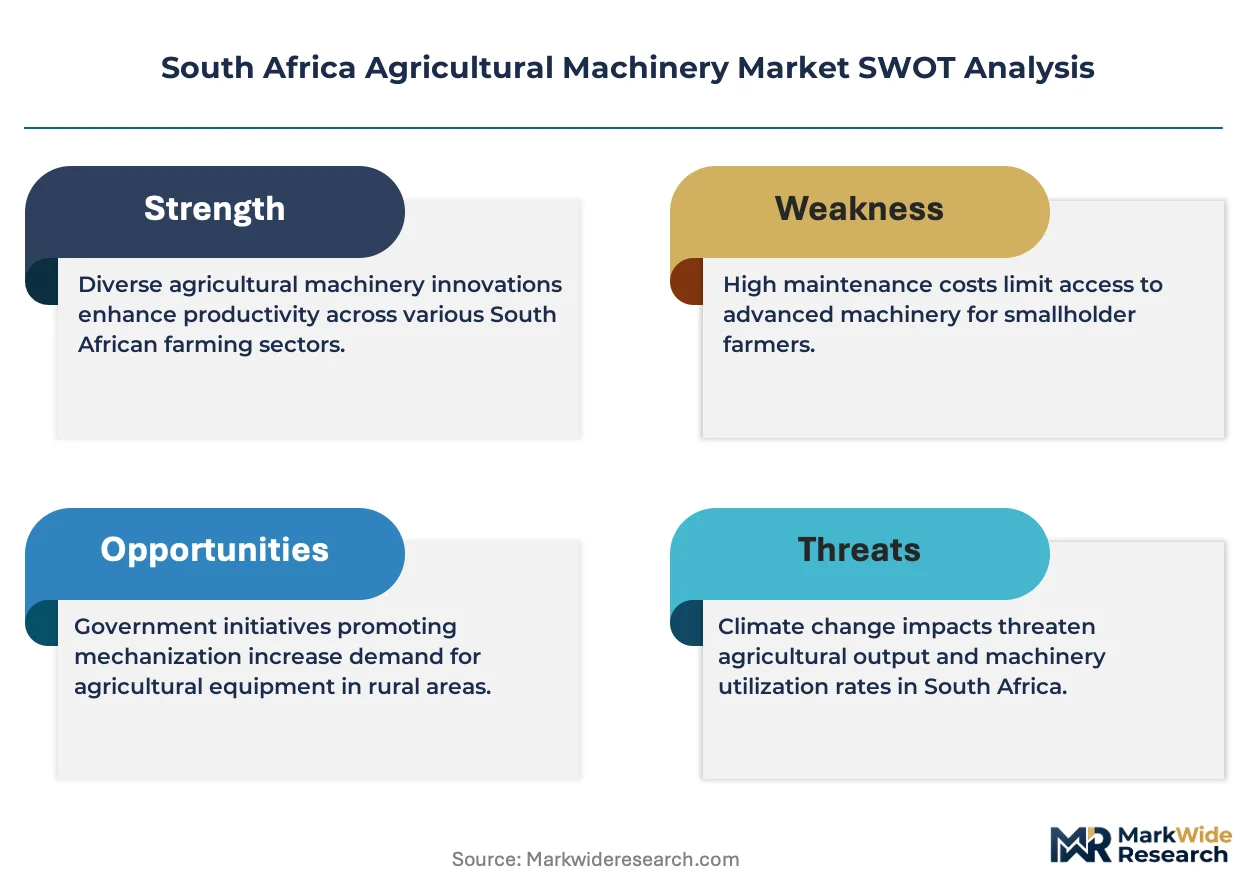
For Market Incumbents: Anticipate margin compression from emerging Asian assemblers by deepening backward integration into precision electronics manufacturing and securing exclusive RTK network partnerships. Defensive positioning requires locking multi-year fleet service contracts with Free State grain cooperatives before grant-program beneficiaries consolidate procurement power. Certification investment in SANS conformity pathways creates six-to-twelve-month competitive moats against unapproved entrants. For New Entrants and Emerging Players: The 120-200 horsepower tractor price gap between premium European brands and economy Indian assemblers offers white-space entry for mid-tier precision-capable platforms. Eastern Cape irrigation schemes present underpenetrated demand for center-pivot matched equipment where established dealer networks remain thin. Go-to-market execution should anchor on equipment-as-a-service contracting partnerships with commercial banks piloting usage-based financing in KwaZulu-Natal sugarcane zones. For Investors and Strategic Acquirers: Valuations sit cheapest among regional dealership consolidators with captive service revenue streams and SANS certification expertise. Long-term viability hinges on telematics platform ownership enabling recurring software subscription models rather than transactional hardware margins. Watch for inflection where mechanization grant program disbursement velocity accelerates beneficiary equipment procurement beyond current replacement-cycle baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Consolidation | Aggregated service revenue from Free State grain cooperatives reduces customer acquisition costs. |
| Telematics Platform Development | Subscription-based data services from John Deere Operations Center displace one-time hardware margins. |
| Localized Assembly Expansion | AGCO's regional configuration navigates ad valorem duties on fully-built European imports. |
| Mechanization Grant Alignment | Mid-horsepower tractor portfolios from Mahindra capture Limpopo beneficiary procurement flows. |
| RTK Network Partnership | Precision agriculture adoption in North West soybean operations hinges on correction signal availability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with agricultural equipment procurement managers at Free State cooperatives, aftermarket service heads at Gauteng distributor operations, precision farming specialists at commercial banks, and Department of Agriculture grant program administrators with secondary validation against customs import records, South African Bureau of Standards certification databases, and agricultural sector capital expenditure surveys. Bottom-up equipment shipment tallies and top-down mechanization grant disbursement analysis were triangulated against dealer inventory reports.
Historical reference periods anchored the projection horizon through verified replacement-cycle timing from North West and Free State grain operations. Segmentation modeling incorporated product type, application intensity, technology tier, and end-user financing access across the forecast period. CAGRs were derived from equipment procurement velocity indexed to soybean cultivation expansion rates and Tier 3 compliance deadline proximity. Forecast inputs included rand-dollar exchange rate scenario bands and mechanization grant budget allocation trajectories.
Caveats apply where currency volatility spikes, grant program suspension, or autonomous equipment regulatory acceleration could materially shift the outlook. Forecasts reflect documented assumptions on replacement-cycle compression and precision technology penetration curves. Material deviation in National Regulator for Compulsory Specifications enforcement intensity or Department of Water and Sanitation licensing velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market