
 Global Plant Based Food Market | 2026-2036
Global Plant Based Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant Based Food Market Intelligence
A reliance on venture capital funding for rapid scaling is narrowing the competitive entry points for smaller, unfunded startups. Beyond Meat Inc. leverages its strong brand recognition in retail channels. Impossible Foods Inc. specializes in developing proprietary heme ingredients for its meat alternatives. Meanwhile, established food giant Nestlé S.A. competes by deploying its extensive global distribution network for its plant-based lines.
Plant-based foods are products formulated from plant ingredients to emulate animal-derived items. These foods utilize components like soy or pea protein, processed through techniques such as high-moisture extrusion to create meat or dairy analogues. Meat alternatives and dairy alternatives represent the most mature product types. The expansion of online retail provides a direct-to-consumer route for new brands, challenging traditional supermarket distribution.
Labeling and naming conventions are shaped by national regulators like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). These agencies' rulings on terms such as 'milk' or 'burger' directly influence product marketing and consumer perception. Future success depends on navigating complex supply chains for novel ingredients while aligning with shifting consumer health priorities.
Market Dynamics
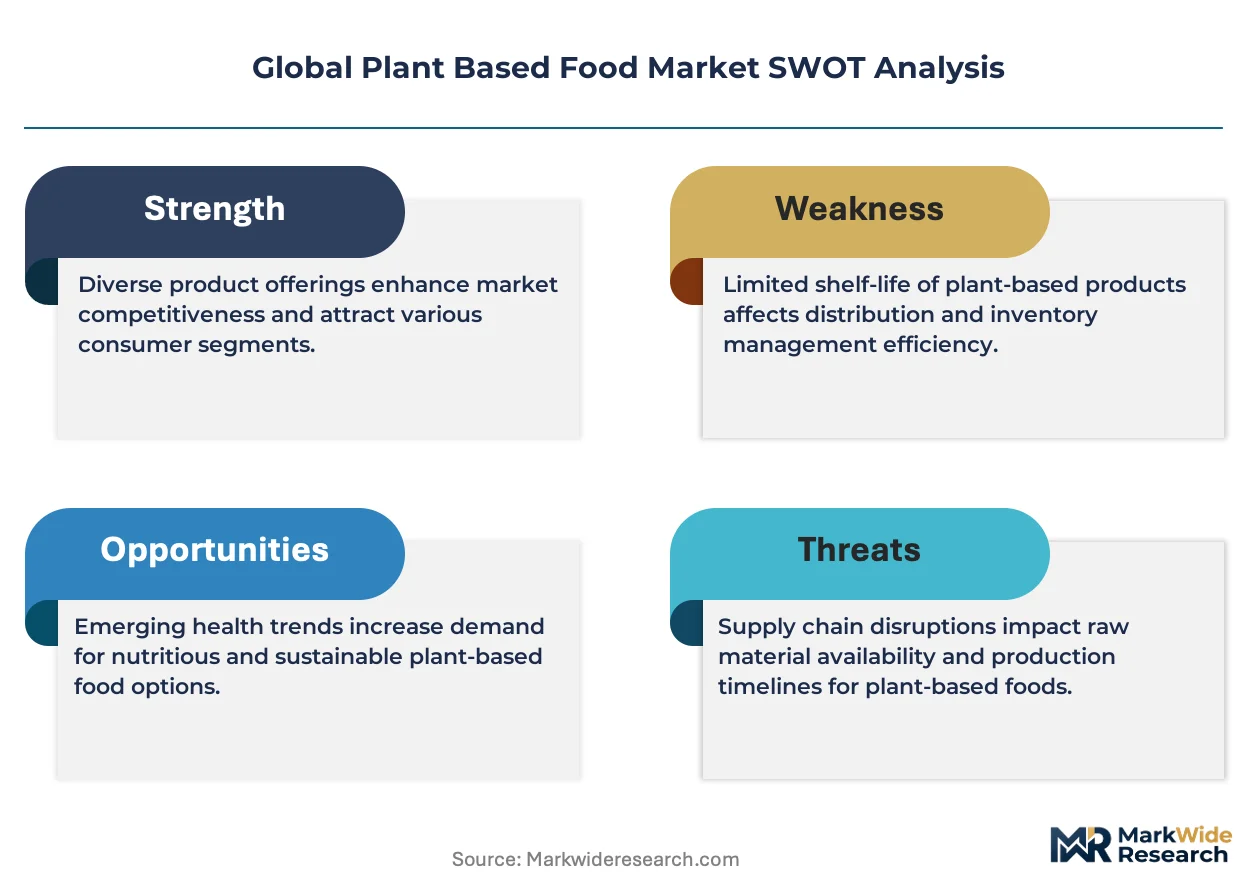
The central structural force shaping the plant-based food market is the friction between the development of novel ingredient supply chains and the industrial-scale production consistency demanded by the global food service sector. This dynamic governs investment in processing technologies and strategic sourcing partnerships.
Growth Catalysts
- Precision Fermentation Advances:This technology enables the creation of specific proteins and fats, such as heme or dairy caseins, without animal inputs, allowing for more authentic product formulations that closely mimic the taste and texture of their conventional counterparts.
- Food Service Sector Demand:Major quick-service restaurant chains in the United States and Europe are incorporating plant-based options into their menus, creating a substantial and consistent volume demand for standardized products like burgers, sausages, and chicken nuggets.
- National Food Security Policies:Governments in countries like Singapore and the Netherlands are providing grants and creating regulatory sandboxes for alternative protein companies, viewing the sector as a strategic component of long-term food resilience and sustainability.
Market Restraints
- Input Cost Volatility:The market is subject to price fluctuations of core agricultural inputs like pea and soy protein isolates, which are influenced by global weather patterns, crop yields, and competition from the animal feed industry.
- Technical Parity Gaps:While improving, current high-moisture extrusion and processing technologies still face challenges in perfectly replicating the complex fibrous structure and mouthfeel of whole-muscle meats, which can limit consumer acceptance and repeat purchases.
- Regulatory Naming Conventions:Ongoing legal and regulatory battles in jurisdictions like France and several U.S. states over the use of meat-related terms such as 'burger' or 'sausage' on plant-based product labels create marketing uncertainty and compliance costs.
Strategic Opportunities
- Geographic Expansion:Significant white space exists in regions with nascent adoption, such as the Middle East, where rising health awareness and a large expatriate population in cities like Dubai and Riyadh present a new consumer base.
- Whole-Cut Analogue Development:A key opportunity lies in moving beyond processed formats to create high-value, whole-cut alternatives like plant-based steaks, fish fillets, and chicken breasts, which command premium pricing and address a more sophisticated consumer segment.
- Clean Label Formulations:Developing products with shorter, more recognizable ingredient lists using novel binding and texturizing agents derived from sources like seaweed or mushroom root (mycelium) can capture the growing consumer segment that is wary of highly processed foods.
Industry Challenges
- Novel Ingredient Scaling:Ensuring a stable and scalable supply chain for emerging ingredients like fava bean, chickpea, or duckweed protein is a major operational hurdle, as agricultural and processing infrastructure has not yet matured for these inputs.
- Capital Expenditure Intensity:Building or retrofitting food production facilities with the necessary specialized equipment, such as high-capacity precision fermentation bioreactors and twin-screw high-moisture extruders, requires significant upfront capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant Based Food Market |
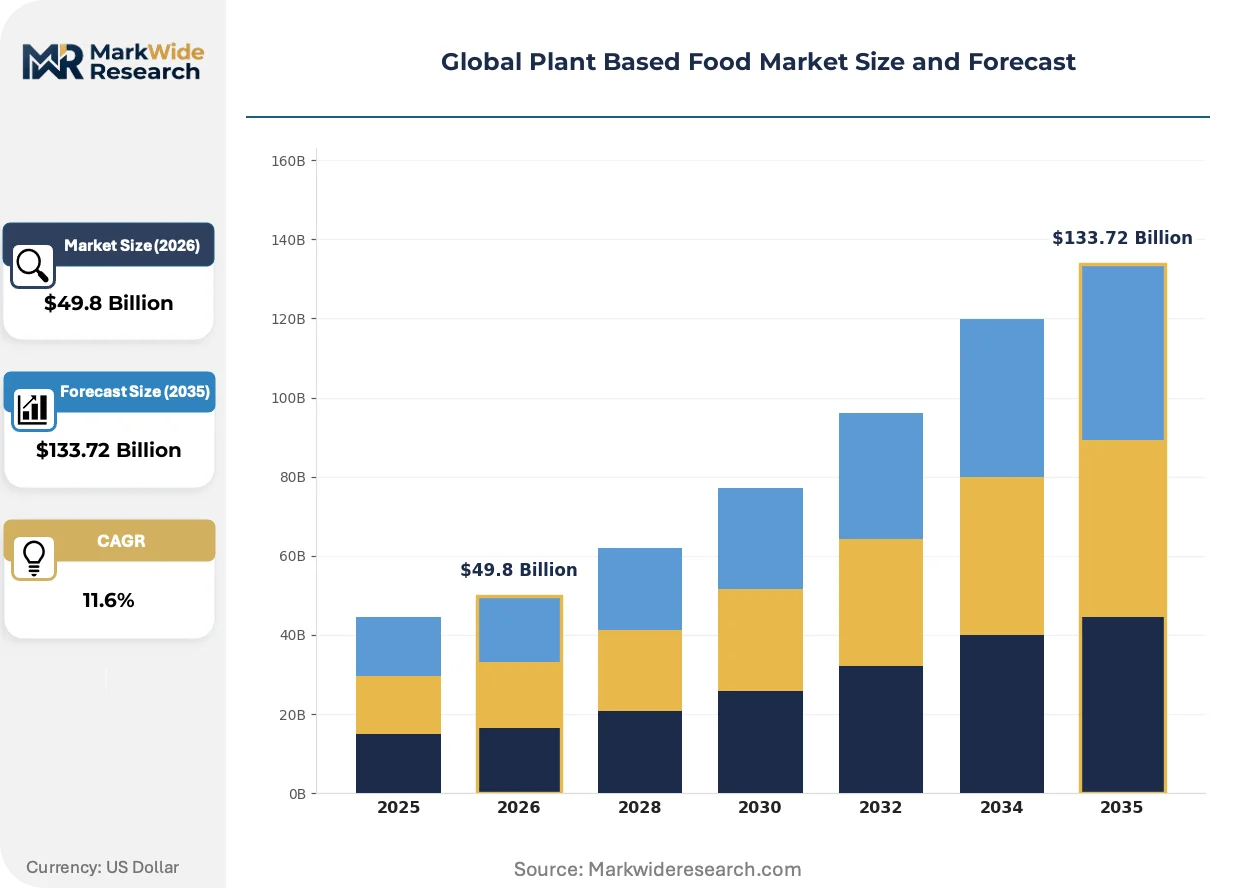
| Market Size in 2026 | $49.8 Billion |
| Market Size in 2035 | $133.72 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Alternatives, Snacks, Beverages End User: Retail Consumers, Food Services, Manufacturers, Wholesalers Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Stores Application: Ready-to-Eat Meals, Protein Supplements, Condiments, Bakery Products |
| Companies Covered | Beyond Meat Inc., Impossible Foods Inc., Nestlé S.A., Danone SA, Oatly Group AB, Amy's Kitchen Inc., Atlantic Natural Foods LLC, Garden Protein International Inc., Lightlife Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant Based Food Market Strategic Shifts & Innovations
The convergence of biotechnology with advanced food processing is accelerating the development of next-generation products. This fusion enables more sophisticated textures, functionalities, and nutritional profiles, moving the category beyond simple ingredient substitution toward creating novel food experiences.
Cellular agriculture, which involves cultivating animal cells to produce specific fats or proteins, provides key sensory components for plant-based foods. Food technology firms and ingredient suppliers are adopting this method to create more authentic flavor and mouthfeel in meat alternatives. This technology is hybridizing product formulations, blending plant-derived proteins with cultivated fats to create a new class of products that bridges the gap between purely plant-based and conventional meat.
Labeling regulations for plant-based products are being formalized by agencies including the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). These rulings on the use of meat and dairy-associated terms directly impact marketing strategies, forcing companies to regionalize their branding. The dairy alternatives segment is particularly affected, with legal challenges in countries like France influencing consumer perception and the competitive landscape.
A consumer-driven shift toward clean-label products is influencing purchasing decisions across the plant-based category. Shoppers are increasingly scrutinizing ingredient lists, favoring items with fewer, recognizable components over those with complex chemical additives. This trend is most visible in developed markets like Germany and the United Kingdom, where it pressures manufacturers to reformulate products and enhance supply chain transparency.
Global Plant Based Food Market Segmentation
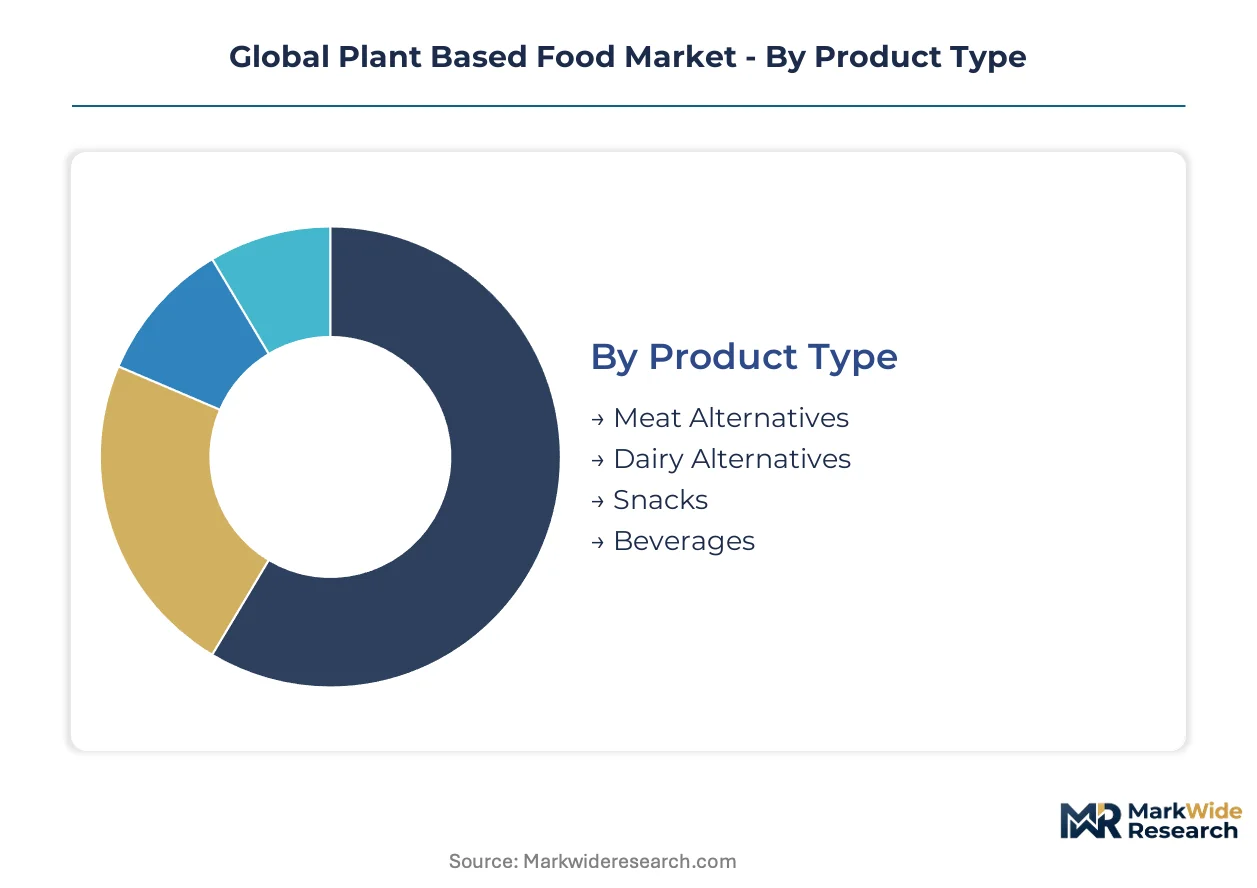
The Global Plant Based Food Market exhibits diverse structural components across its value chain. Understanding these distinct segments allows for a granular analysis of consumer preferences, technological adoption, and strategic investment priorities. This segmentation highlights areas of established market penetration and emerging growth opportunities for stakeholders.
Product Type:
The product type landscape reflects varying levels of market maturity and innovation cycles within the plant-based food sector.
- Meat Alternatives:These products are formulated to mimic the taste, texture, and appearance of conventional meat, primarily using proteins from soy, pea, or fungi. Demand concentrates in developed markets, particularly the United States and Germany, driven by health consciousness and environmental concerns.
- Dairy Alternatives:This category includes plant-based milks, yogurts, cheeses, and ice creams, typically derived from oats, almonds, soy, or coconut. Consumer adoption is high in retail channels, with innovation focusing on improved sensory profiles and nutritional parity.
- Snacks:Plant-based snacks encompass items like protein bars, jerky, and chips, catering to convenience and on-the-go consumption.
- Beverages:This segment primarily consists of plant-based milks and other drinkable alternatives, expanding beyond traditional dairy substitutes.
Meat Alternatives retains volume leadership; Dairy Alternatives holds the steepest expansion curve.
End User:
End user segmentation delineates the primary channels through which plant-based products reach their ultimate consumers, reflecting distinct volume requirements and purchasing behaviors.
- Retail Consumers:This segment includes individuals purchasing plant-based foods directly from supermarkets, online stores, or specialty shops for household consumption. Demand is concentrated in urban centers across North America and Europe, driven by personal dietary choices and health trends.
- Food Services:This segment comprises restaurants, cafes, institutional caterers, and quick-service chains incorporating plant-based options into their menus. Major quick-service restaurant chains in the United States and Europe create substantial, consistent volume demand for standardized products.
- Manufacturers:These entities utilize plant-based ingredients as components in their own food production, such as for ready-to-eat meals or baked goods.
- Wholesalers:Wholesalers serve as intermediaries, distributing bulk plant-based products to various businesses, including retailers and food service providers.
Consumer preference drives demand for Retail Consumers, while Food Services exhibits consistent growth.
Distribution Channel:
The distribution channel highlights how plant-based food products are physically moved and sold, reflecting evolving supply concentration and consumer access points.
- Supermarkets:These large retail outlets offer a broad selection of plant-based products, benefiting from high foot traffic and established consumer purchasing habits. Their extensive reach makes them a primary channel for mass-market adoption across most developed economies.
- Online Retail:This channel includes e-commerce platforms and direct-to-consumer websites, providing convenience and a wide product assortment to consumers. The expansion of online retail provides a direct-to-consumer route for new brands, challenging traditional supermarket distribution.
- Health Stores:These stores focus on organic, natural, and wellness products, catering to a niche consumer base seeking specific dietary or lifestyle-aligned options.
- Specialty Stores:This segment includes independent grocers and gourmet food shops, often offering unique or premium plant-based products not widely available elsewhere.
Supermarkets maintain broad accessibility, and Online Retail facilitates market entry for niche brands.
Application:
Application segmentation reveals how plant-based ingredients are integrated into final products, influencing potential margin structures and consumer utility.
- Ready-to-Eat Meals:This application involves pre-prepared plant-based dishes designed for convenience and quick consumption, often found in grocery stores or meal delivery services. Demand is strong in urban areas, driven by busy lifestyles and a preference for convenient, healthy options.
- Protein Supplements:Plant-based proteins, such as pea or soy isolates, are used in powders, bars, and drinks for athletic performance or dietary supplementation. Consumer demand is particularly high among fitness enthusiasts and individuals seeking alternative protein sources.
- Condiments:This segment includes plant-based alternatives for sauces, dressings, and spreads, offering flavor enhancements without animal-derived ingredients.
- Bakery Products:Plant-based ingredients are incorporated into breads, pastries, and other baked goods, catering to dietary restrictions and ethical preferences.
Innovation in Ready-to-Eat Meals captures premium value, as Protein Supplements addresses functional consumer needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National food security policies in countries like Singapore and the Netherlands drive investment in alternative protein companies. These governmental initiatives foster innovation and strategic sourcing partnerships for plant-based ingredients. Such policies aim to enhance long-term food resilience and sustainability across diverse global markets.
United States
Consumer demand in the United States concentrates on health consciousness and environmental concerns. The U.S. Food and Drug Administration (FDA) shapes labeling conventions for plant-based products, impacting marketing strategies. California's robust food tech ecosystem sees significant venture capital funding for novel ingredient development and rapid scaling.
Germany
German consumers show high adoption of plant-based foods, particularly for clean label formulations. The European Food Safety Authority (EFSA) influences product standards and consumer perception in the region. Berlin's vibrant startup scene attracts investment in new product development and sustainable protein sources.
Singapore
Singapore's food security policies strongly encourage domestic alternative protein production. The government provides grants and regulatory sandboxes for food technology companies. Its dedicated food innovation hubs actively support cellular agriculture research and novel ingredient scaling.
Netherlands
Dutch government support for alternative proteins aims to build a resilient food system. National policies create regulatory sandboxes for novel food companies, accelerating market entry. Wageningen, a prominent agri-food research valley, serves as a hub for precision fermentation advances and ingredient innovation.
United Kingdom
UK consumers increasingly scrutinize ingredient lists, favoring clean label plant-based options. National food standards, aligned with EFSA guidelines, influence product reformulation and transparency. London's dynamic food innovation clusters foster direct-to-consumer routes for new plant-based brands.
Global Plant Based Food Market Key Industry Players
Channel-controlling players compete with product-specialist players across the plant-based food market. The competitive structure is tiered, with large established food companies alongside agile, innovation-driven startups. Strategic archetypes include ingredient innovators, brand-focused retailers, and broad-portfolio manufacturers. Competitive moves emphasize strategic partnerships for supply chain stability and geographic expansion into nascent markets.
Specialists in novel ingredient development, such as Impossible Foods Inc., exemplify a focus on proprietary technology for meat alternatives. Beyond Meat Inc., a US-based corporation, represents a brand-driven approach, leveraging strong retail recognition for its plant-based products. Meanwhile, Nestlé S.A., a Swiss-based multinational food and drink processing conglomerate, sits within the broad-portfolio manufacturer archetype, deploying its extensive global distribution network for diverse plant-based lines.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Impossible Foods Inc. |
| Nestlé S.A. |
| Danone SA |
| Oatly Group AB |
| Amy's Kitchen Inc. |
| Atlantic Natural Foods LLC |
| Garden Protein International Inc. |
| Lightlife Foods Inc. |
| Others |
Cost & Logistics Intelligence
Under-capacity in novel ingredient processing infrastructure drives higher input costs for specialized proteins, influencing pricing strategies for advanced plant-based products and shaping supplier investment in scaling up production capabilities.
Pricing Analysis
Formulation complexity creates the primary spread in the plant-based food market, with specialized ingredients and advanced processing techniques commanding premium pricing. Pricing stratifies across premium, standard, and economy tiers, often linked to brand recognition and sensory profile. Pricing pressure stems from input cost volatility for pea and soy proteins, influenced by agricultural commodity markets. Food service buyers prioritize consistent volume and value pricing, while retail consumers exhibit higher price sensitivity, seeking parity with conventional animal products.
Supply Chain Analysis
Upstream feedstock for plant-based foods draws heavily from agricultural powerhouses like the United States, Canada, and China for pea and soy protein isolates. Raw material dependencies on these core agricultural commodities introduce supply chain risk through commodity price volatility and exposure to global weather patterns. Novel ingredients like fava bean and chickpea proteins face significant scaling challenges due to underdeveloped processing infrastructure. Downstream distribution runs through a hybrid model, utilizing established supermarket channels for mass market reach and online retail for direct-to-consumer niche brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant-based food market offers a defensive moat, primarily through regulatory entrenchment which formalizes labeling and ingredient standards, thereby creating barriers for non-compliant entrants.
For Market Incumbents: Build a proprietary ingredient moat by investing heavily in precision fermentation R&D and securing long-term supply contracts for next-generation proteins. This strategy mitigates input cost volatility and addresses technical parity gaps that limit consumer acceptance. Leverage established global distribution networks to scale new product introductions rapidly, particularly in the food service sector.
For New Entrants and Emerging Players: Pursue white-space opportunities in whole-cut analogue development and clean label formulations, which address sophisticated consumer preferences. The Middle East presents a penetrable geographic segment with rising health awareness and a growing expatriate population. A focused go-to-market angle emphasizing unique ingredient profiles, such as mycelium or seaweed, can differentiate offerings in crowded retail channels.
For Investors and Strategic Acquirers: Capital is best deployed toward ingredient innovators with scalable precision fermentation technology or specialized brands demonstrating strong clean-label appeal. The long-term viability of this market hinges on continued consumer shifts towards sustainable and health-conscious diets over the next decade. Commercialization success of next-generation whole-cut products, particularly plant-based steaks and fish fillets, serves as a key inflection indicator for investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Scales production of authentic proteins and fats, reducing reliance on traditional agricultural inputs. |
| Whole-Cut Analogue Product Launch | Captures premium consumer segments seeking advanced meat alternatives beyond processed formats. |
| Long-term Food Service Partnerships | Secures consistent volume demand and broadens market penetration for standardized products. |
| Clean Label Ingredient Repositioning | Aligns product formulations with evolving consumer health priorities and transparency demands. |
| Regulatory Compliance Pathway Investment | Navigates complex labeling conventions, ensuring market access and building consumer trust. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, academic journals, agricultural commodity reports, and company annual reports. This approach involved conversations with food scientists, R&D directors, supply chain managers, and marketing executives from leading plant-based food companies. Bottom-up market sizing was performed for various segments, with top-down validation against macroeconomic indicators.
Forecast inputs considered demand-side drivers, supply-side capabilities, and technological advancements across the analysis window. The analytical framework modeled segmentation dimensions including product type, end user, distribution channel, application, and primary protein source. Compound Annual Growth Rates were derived from historical growth trends, expert projections, and market penetration rates. Consumer dietary shifts and food service menu integration served as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global economic growth or agricultural commodity prices would shift the trajectory. Forecasts reflect assumptions regarding current regulatory environments and the pace of technological development. Material shifts in consumer health priorities or novel ingredient scaling success would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Vegan Tortillas Market
Plant Based Food
Vegan Food Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Vegan Steak Market