
 Plant-Based Spreads Market | 2026-2036
Plant-Based Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Spreads Market Analytics
Precision fermentation of plant proteins is tilting formulation economics toward cleaner-label products with shorter ingredient lists. Upfield leverages its European manufacturing footprint to sustain cost advantages in margarine-style spreads. Nestlé anchors its portfolio through retail partnerships across multiple continents. Miyoko's Creamery differentiates through cultured cashew bases and artisan positioning in premium channels.
Plant-based spreads are emulsified or pureed food products derived from nuts, seeds, or vegetables, typically containing 60-85% fat content by weight, designed to replace conventional dairy butter or cream cheese on bread and in cooking. Their primary commercial purpose centers on delivering functional spreadability and flavor while eliminating animal-derived ingredients. Nut butters occupy the largest volume share due to established peanut and almond supply chains, though chocolate spreads command higher per-unit margins through indulgence positioning. Glass jars dominate premium positioning in specialty stores, while plastic tubs and pouches capture mainstream supermarket volume through lower unit economics.
The FDA governs allergen labeling and nutrient content claims for plant-based spreads sold in the United States, directly affecting formulation transparency and front-of-package messaging. EFSA and EMA frameworks in Europe shape novel ingredient approvals and health claim substantiation, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor evolving protein fortification standards and front-of-package warning label expansions as regulators tighten scrutiny on processed plant-based alternatives.
Market Dynamics
Precision fermentation of plant proteins is compressing formulation costs while FDA labeling updates for plant-based dairy alternatives force reformulation across US portfolios. This dual pressure from technology economics and compliance mandates is restructuring competitive positioning.
Growth Catalysts
- FDA Labeling Modernization:Updated guidelines for plant-based dairy alternatives in the United States are clarifying permissible claims, reducing regulatory uncertainty for reformulated spreads.
- Foodservice Bulk Procurement:Menu diversification at restaurant chains is accelerating institutional purchasing of plant-based spreads for back-of-house applications.
- Precision Fermentation Scale-Up:Commercial deployment of microbial protein production is enabling cleaner-label formulations with reduced ingredient complexity.
Market Restraints
- Allergen Supply Concentration:Peanut and almond supply chains concentrate in specific growing regions, exposing margins to climate volatility and trade friction.
- Fat Mimetic Performance Gap:Current emulsion technologies fail to replicate dairy butter's crystallization behavior in high-heat cooking applications.
- EFSA Novel Ingredient Timelines:Extended approval pathways for new protein sources delay European product launches by 18-36 months versus conventional formulations.
Strategic Opportunities
- Private-Label Expansion in Germany:Retailer-controlled brands command growing shelf space, offering margin capture for contract manufacturers with flexible production lines.
- Cultured Cashew Positioning:Fermentation-based cashew processing creates premium tier differentiation through artisan flavor profiles and extended shelf stability.
- Foodservice Direct Distribution:Bypassing traditional retail distributors through dedicated institutional sales channels improves margin retention and formulation customization.
Industry Challenges
- Emulsion Science Talent Scarcity:Formulation chemists with expertise in plant lipid crystallization and protein stabilization remain concentrated at legacy dairy research centers.
- Dual Jurisdiction Compliance:Simultaneous FDA and EFSA substantiation requirements for health claims force parallel clinical and analytical testing programs.
- Legacy Equipment Retrofit Costs:Dairy processing infrastructure requires significant capital modification to handle allergen-segregated plant protein lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Spreads Market |
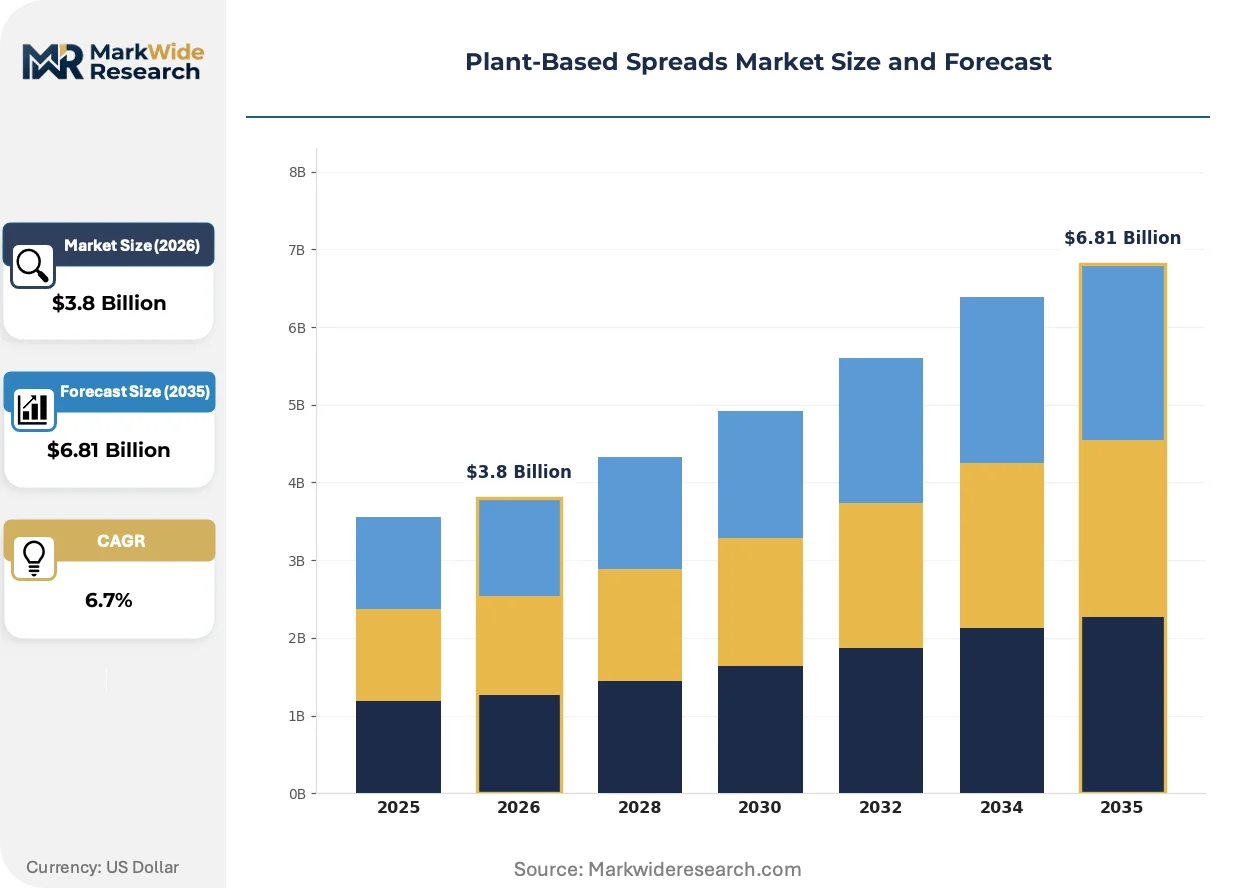
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut Butters, Seed Spreads, Vegetable Spreads, Chocolate Spreads Ingredient Source: Almonds, Peanuts, Cashews, Sunflower Seeds Packaging Type: Glass Jars, Plastic Containers, Pouches, Tubs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops |
| Companies Covered | Unilever, Upfield, Miyoko's Creamery, Nestlé, Daiya Foods Inc., Kite Hill, Follow Your Heart, Amy's Kitchen Inc., B&G Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Spreads Market Evolving Landscape
Formulation science and regulatory frameworks are converging to reshape product architecture. Three developments are compressing development cycles while expanding addressable use cases.
Precision fermentation of oleaginous yeast is hybridizing fat structuring with protein functionality in single-ingredient systems. Mid-tier manufacturers are adopting these consolidated inputs to reduce supplier count and simplify label declarations. The technology is hybridizing previously separate emulsifier and base-fat supply chains into unified ingredient platforms.
EFSA's evolving stance on novel protein health claims is tightening substantiation requirements for European launches. Manufacturers must now complete human clinical trials for satiety or cardiovascular benefit assertions before market entry. Premium-positioned spreads targeting functional benefits face extended development timelines and elevated regulatory capital deployment.
Restaurant procurement teams are consolidating supplier relationships around full-category plant-based vendors rather than single-product agreements. Multi-unit operators in the United States are replacing fragmented butter-alternative sourcing with integrated spread-and-cheese contracts. This concentration favors manufacturers with portfolio breadth across texture variants and price tiers.
Plant-Based Spreads Market Segmentation
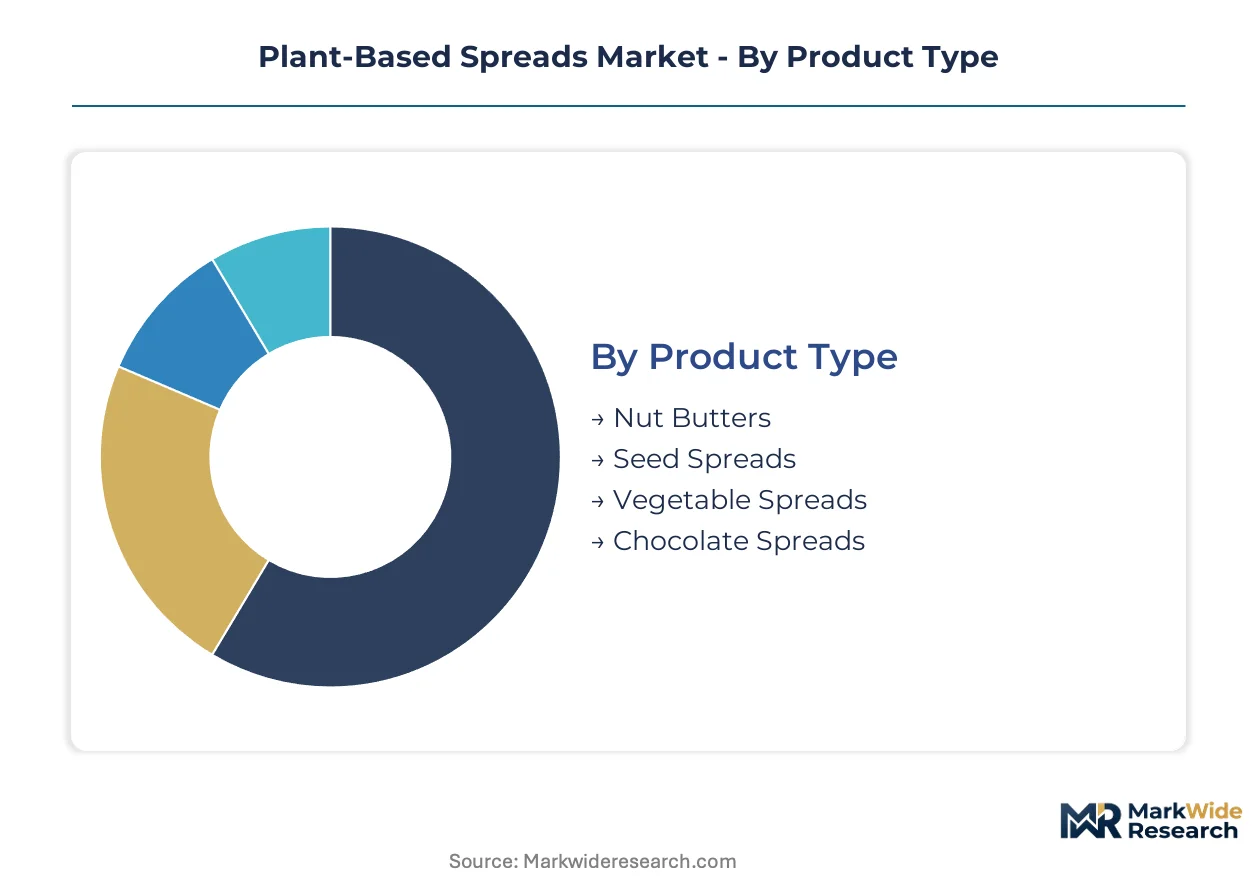
Segmentation in plant-based spreads determines formulation priorities, packaging investments, and channel economics. Manufacturers must align production capabilities with the specific performance requirements and margin structures of each segment tier.
Product Type:
Cost tier differentiation separates commodity volume plays from premium positioning strategies across the category.
- Nut Butters:Ground legume or tree nut pastes with 90-95% single-ingredient purity dominate institutional foodservice procurement. Peanut and almond variants anchor supermarket volume through established supply chains and price accessibility.
- Chocolate Spreads:Emulsified cocoa-fat systems with 30-40% sugar content command the highest per-unit margins through indulgence positioning. European retail channels concentrate demand for hazelnut-cocoa hybrids, while North American markets favor peanut-chocolate combinations.
- Seed Spreads:Sunflower and pumpkin seed butters serve allergen-free substitution demand in school nutrition and pediatric segments.
- Vegetable Spreads:Legume-based hummus and white-bean preparations target savory applications and Mediterranean cuisine positioning.
Nut butters command the established base. The steepest expansion runs through chocolate spreads.
Ingredient Source:
Application requirements dictate sourcing priorities, with functional properties determining suitability for spreadability, emulsion stability, and flavor intensity.
- Almonds:California's Central Valley cultivation supplies the bulk of global almond butter feedstock. High oleic acid content delivers oxidative stability for extended shelf-life products targeting export markets.
- Peanuts:Runner and Virginia cultivars from Georgia and Alabama provide the lowest-cost protein base. Runner varieties dominate commercial grinding operations through uniform kernel size and higher oil yield.
- Cashews:Vietnamese and Indian processing clusters supply raw kernels for premium cultured spreads. Creamy mouthfeel without grit distinguishes cashew bases in artisan positioning.
- Sunflower Seeds:Ukrainian and Russian growing regions historically anchored supply, with Argentine expansion displacing volume amid trade disruptions.
Peanuts anchor volume manufacturing. Cashews are climbing the fastest through premium channel expansion.
Packaging Type:
Customer type segmentation separates institutional buyers seeking unit economics from consumers responding to shelf presence and sustainability signaling.
- Glass Jars:Premium specialty retail and gift-channel positioning leverage perceived quality and infinite recyclability. Weight and breakage costs limit penetration beyond premium price tiers.
- Plastic Containers:Polypropylene tubs dominate mainstream supermarket velocity through lightweight logistics and shatter resistance. HDPE jars serve value-tier nut butters with cost-minimized barrier properties.
- Pouches:Flexible packaging captures single-serve and on-the-go consumption occasions. Reduced material intensity appeals to sustainability-conscious younger demographics.
- Tubs:Wide-mouth polyethylene containers serve foodservice bulk and club-store formats. Stackability and forklift compatibility optimize warehouse economics.
Plastic containers hold the volume core. Pouches are gaining share fastest through convenience-format innovation.
Distribution Channel:
Geography and channel maturity determine access economics, with digital infrastructure penetration varying sharply across regional markets.
- Supermarkets:Mass-market penetration depends on slotting fee negotiations and planogram positioning. German retailers lead private-label development through vertical integration into sourcing.
- Online Retail:Direct-to-consumer subscription models enable flavor customization and replenishment automation. Amazon and specialized platforms capture trial-driven purchases outside core urban markets.
- Specialty Stores:Independent natural grocers and gourmet shops provide brand-building visibility and early-adopter feedback. Staff recommendation influence exceeds mass-market environments.
- Health Food Shops:Pharmacy-adjacent positioning in European markets supports functional benefit claims and practitioner endorsement. Limited SKU breadth concentrates on allergen-specific and organic-certified variants.
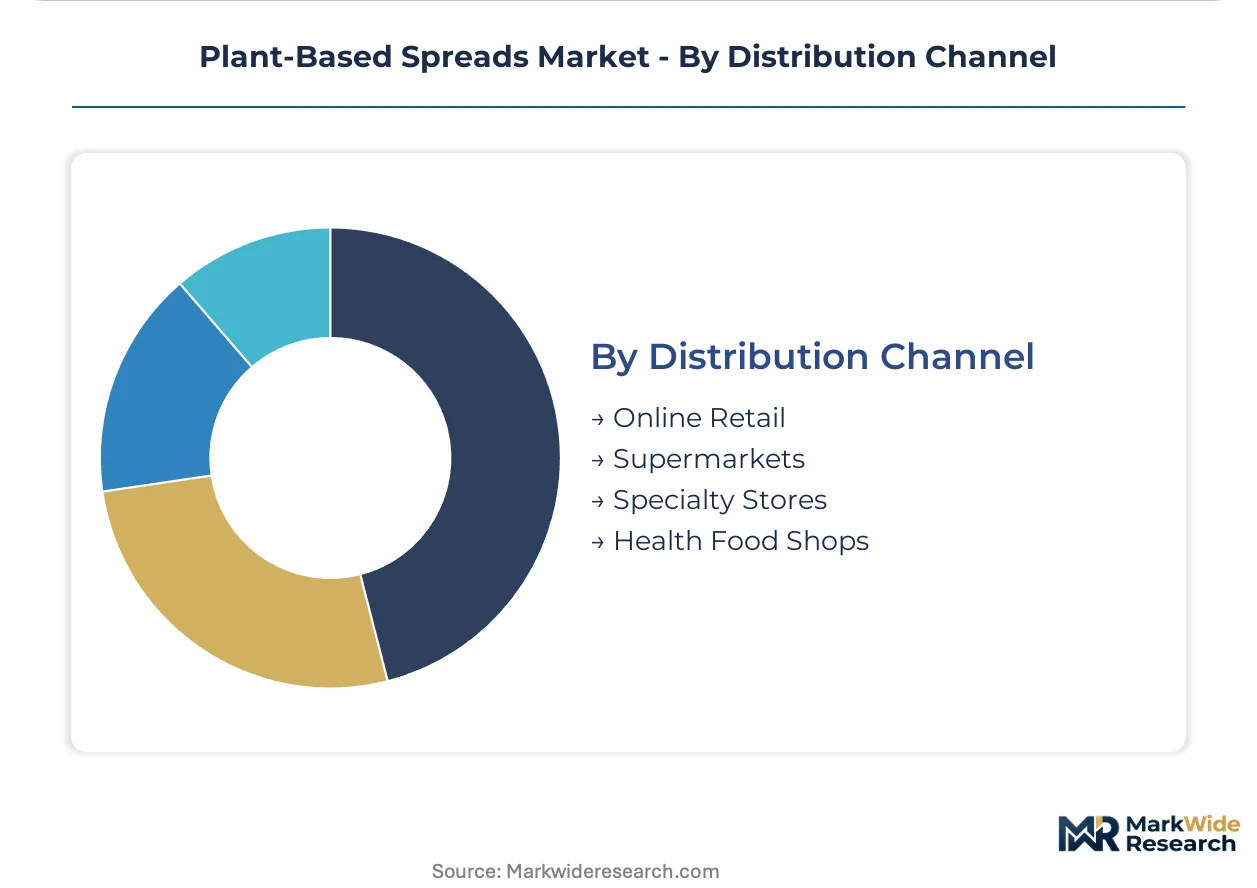
Supermarkets maintain the established base. Online retail shows the steepest expansion trajectory through fulfillment infrastructure maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement teams in the United States and institutional buyers across Germany concentrate bulk purchasing power, while retail channel fragmentation in France and the United Kingdom creates tiered entry points for differentiated positioning.
United States
Restaurant chain menu diversification and college campus dining contracts drive institutional volume. FDA updated labeling guidelines for plant-based dairy alternatives reshape permissible packaging claims and formulation transparency. California's Central Valley almond processing clusters supply raw material for spread manufacturers targeting export markets.
Germany
Discounter and supermarket private-label expansion captures margin from branded incumbents through vertical control over sourcing. EFSA novel ingredient approval pathways extend development timelines for functional benefit claims. Berlin and Hamburg anchor contract manufacturing capacity serving retailer-controlled brands across Northern Europe.
United Kingdom
Specialty grocer channel growth and direct-to-consumer subscription models support artisan positioning. Trading standards enforcement around dairy terminology alternatives affects front-of-package messaging. London and Southeast England concentrate premium brand headquarters and formulation development facilities.
France
Traditional cuisine adaptation and pâtisserie ingredient substitution sustain demand for butter-alternative functionality. ANSM and DGCCRF oversight of novel food notifications shapes protein fortification claims. The Île-de-France region hosts dairy-alternative research clusters transitioning expertise toward plant lipid emulsion science.
India
Urban middle-class dietary diversification and foodservice modernization in metro areas expand addressable occasions. FSSAI labeling requirements for vegan claims and allergen declarations tighten compliance obligations. Maharashtra and Karnataka processing hubs convert cashew and peanut supply chains into branded spread manufacturing.
Plant-Based Spreads Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price positioning. The vendor base organizes around three strategic archetypes: multinational consumer goods conglomerates with refrigerated distribution scale, dairy-alternative pure-plays with fermentation-based differentiation, and private-label contract manufacturers serving retailer-controlled brands. Competitive moves concentrate on portfolio diversification across texture variants and foodservice direct distribution bypassing traditional retail intermediaries.
Within the multinational tier, Unilever and Nestlé occupy positions defined by refrigerated logistics infrastructure and retail partnership density across multiple continents. Upfield exemplifies the European manufacturing footprint archetype with cost-optimized margarine-style production. Miyoko's Creamery represents the cultured fermentation specialist segment with artisan positioning in premium channels. These three anchors illustrate how scale, geography, and technology differentiation segment competitive space without requiring specific strategic action claims.
| Leading Market Players |
|---|
| Unilever |
| Upfield |
| Miyoko's Creamery |
| Nestlé |
| Daiya Foods Inc. |
| Kite Hill |
| Follow Your Heart |
| Amy's Kitchen Inc. |
| B&G Foods Inc. |
| Others |
Value Network & Pricing Analysis
California's Central Valley almond cultivation concentrates upstream supply for premium spreads, anchoring margin pools in branded retail channels and artisan positioning tiers where origin certification commands shelf price premiums.
Pricing Analysis
Cost-plus contracts with almond commodity indexation dominate procurement between processors and ingredient suppliers. Three-tier pricing structure across premium cultured cashew, standard nut butter, and economy seed spread levels separates buyers by application requirement and certification grade. Pricing pressure stems from private-label expansion in German retail, compressing branded margin. Foodservice procurement teams exhibit highest price sensitivity due to volume scale and formulation standardization demands.
Supply Chain Analysis
Export-control scrutiny on precision fermentation technology limits microbial protein equipment flows to certain processing hubs. Vietnam and India anchor cashew kernel supply; Ukraine and Argentina source sunflower seed feedstock; Georgia and Alabama concentrate peanut cultivation. Single-source vulnerability runs through Vietnamese cashew processing clusters. Distribution runs through refrigerated logistics networks serving retail and foodservice channels with divergent temperature and shelf-life requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up constitutes a technological inflection reshaping formulation economics, while FDA labeling modernization creates regulatory clarity accelerating portfolio reformulation cycles.
For Market Incumbents: Build fermentation technology moats through captive microbial protein production capacity. Invest in allergen-segregated manufacturing lines to capture private-label contract manufacturing demand from German retailers. Precision fermentation specialists threaten branded positioning through cleaner-label parity at lower cost structures. For New Entrants and Emerging Players: India's metro foodservice modernization offers underpenetrated white-space for back-of-house spread applications. Target direct-to-institutional distribution bypassing retail slotting fee barriers. Cultured cashew positioning in premium channels provides lowest competitive density entry angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed contract manufacturers serving European retailer-controlled brands. Five-to-ten year viability hinges on fermentation technology adoption curves and regulatory pathway clarity. Watch EFSA novel ingredient approval velocity as inflection signal for European portfolio expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial protein production consolidates emulsifier and base-fat supply chains into unified platforms. |
| Foodservice Direct Distribution | Bypassing retail intermediaries improves margin retention and enables formulation customization for institutional buyers. |
| Private-Label Contract Manufacturing | Flexible production lines capture shelf space growth from German retailer-controlled brand expansion. |
| Cultured Cashew Positioning | Fermentation-based processing creates artisan differentiation and extended shelf stability for premium channels. |
| Allergen-Segregated Production Investment | Capital modification of dairy infrastructure enables plant protein line handling with contamination risk mitigation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation chemists, foodservice procurement directors, retail category buyers, and contract manufacturing executives; and secondary validation through FDA labeling guidance documents, EFSA novel food submission databases, USDA crop production reports, and customs trade flow records. Bottom-up volume modeling triangulated against top-down category spend estimates.
Forecast inputs span product type tier, ingredient source origin, packaging format, and distribution channel maturity across the projection horizon. CAGRs derive from segment-level growth rate blending weighted by base-year value contribution. Modeled variables include precision fermentation adoption curves, foodservice menu diversification velocity, and regulatory approval timeline assumptions for novel protein claims.
Practitioners should monitor EFSA novel ingredient approval velocity and FDA enforcement patterns around dairy terminology alternatives for early signals of competitive repositioning requirements. Material shifts in almond supply chain climate resilience or precision fermentation capital cost trajectories would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Oat Protein Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Vegan Meat Alternatives Market