
 Organic Pea Protein Market | 2026-2036
Organic Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Pea Protein Market Outlook
Multi-source procurement for organic yellow pea supply is pivoting toward vertically integrated farm-to-ingredient models. Roquette Frères leverages its European milling network to secure non-GMO pea streams. Puris anchors North American output through domestic organic acreage partnerships. Glanbia plc competes on dairy-alternative protein blends that incorporate pea isolates alongside other plant inputs.
Organic pea protein denotes the isolated or concentrated protein fraction extracted from Pisum sativum cultivated under certified organic protocols, typically yielding 80-90% protein content in isolate form through wet-milling and air-classification processes. The ingredient serves as a functional emulsifier and amino acid source in formulated foods where allergen exclusion and sustainability claims carry purchase influence. Isolate commands the premium tier on protein density and solubility performance, while textured formats accelerate within meat alternatives as extrusion technology improves fibrous structure replication. Sports nutrition applications sustain higher per-kilogram pricing than conventional bakery inclusion, reflecting performance-positioned branding and certification premiums.
USDA organic certification governs raw material eligibility for this market, while EFSA reviews novel food dossiers for expanded protein extraction claims in Europe. FDA allergen labeling rules and EU REACH chemical safety standards shape formulation transparency and import compliance burdens. Stakeholders must monitor evolving carbon-border adjustment mechanisms and organic equivalency agreements that could reroute supply chain economics between North American and European processing hubs.
Market Dynamics
The organic pea protein market is reshaping around the EU Green Deal's Farm to Fork traceability mandates, which force ingredient suppliers to document cultivation-to-extraction carbon footprints. Wet-milling processors in Germany and France now compete on verified supply chain transparency rather than isolate purity alone.
Growth Catalysts
- EU Green Deal protein traceability:Mandatory carbon accounting for imported organic pulses creates captive demand for European-milled isolates. Food-tech clusters in Berlin accelerate clean-label formulation partnerships.
- Extrusion technology maturation:High-moisture extrusion now replicates fibrous meat textures from 80% protein isolates, expanding textured pea protein adoption in plant-based meat manufacturing.
- Sports nutrition functional positioning:Branched-chain amino acid profiles and rapid dispersibility drive isolate premiums in performance nutrition, where allergen-free claims command shelf space.
Market Restraints
- Organic yellow pea input volatility:Weather-driven yield fluctuations in Canadian prairie provinces and Ukrainian organic acreage create raw material price instability for non-integrated processors.
- EFSA novel food dossier delays:Pending approvals for expanded protein extraction claims in Europe freeze formulation innovation timelines for isolate suppliers seeking expanded use cases.
- Soy protein isolate substitution:Established supply chains and lower unit economics for conventional soy isolates retain cost-sensitive bakery and beverage applications.
Strategic Opportunities
- Underpenetrated Indian functional foods:FSSAI organic certification alignment and domestic pulse processing infrastructure gaps create first-mover potential for isolate suppliers targeting urban protein fortification.
- Carbon-border adjustment mechanism positioning:Early compliance with EU CBAM documentation requirements secures preferential access as 2026 full implementation raises import barriers for non-verified supply chains.
- Precision fermentation hybrid formulations:Combining pea protein isolates with fermentation-derived functional ingredients enables next-generation dairy alternatives with superior mouthfeel and amino acid completeness.
Industry Challenges
- Organic certification timeline compression:USDA three-year transition periods and EFSA equivalence verification create working capital intensity for suppliers scaling certified acreage.
- Extrusion operator skill scarcity:High-moisture extrusion requires specialized protein hydration and shear control expertise that outpaces technical training program output in European processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Pea Protein Market |
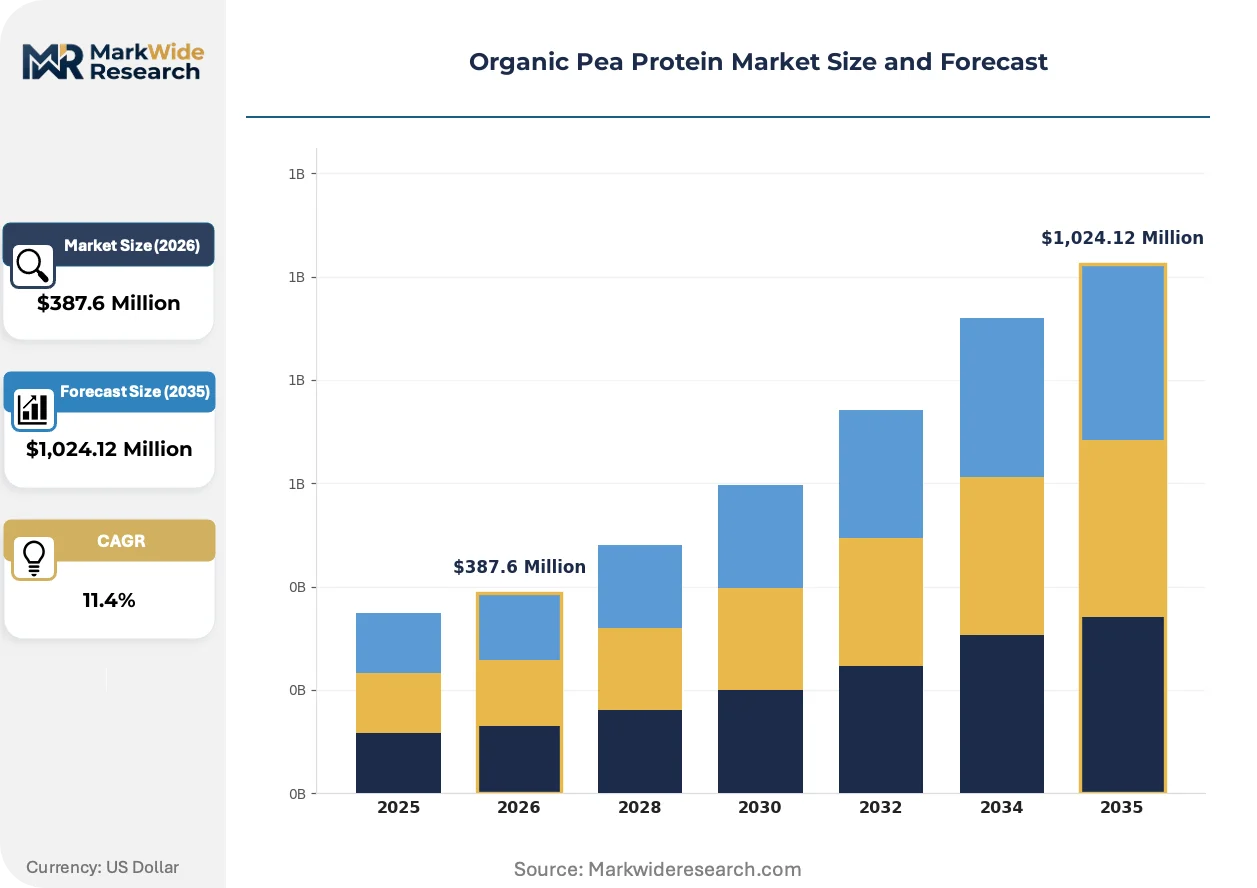
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured, Flour Application: Beverages, Snacks, Bakery, Meat Alternatives Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores End User: Food & Beverage, Sports Nutrition, Personal Care, Others |
| Companies Covered | Roquette Frères, Puris, Ingredion Incorporated, Axiom Foods, Inc., Glanbia plc, Emsland Group, The Scoular Company, Cosucra Groupe Warcoing SA, The Green Labs LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Pea Protein Market Strategic Shifts
Extrusion technology maturation and regulatory carbon accounting are converging to redefine competitive differentiation in organic pea protein. Suppliers now compete on verified supply chain transparency rather than isolate specifications alone.
High-moisture extrusion is overtaking traditional low-moisture processes for textured protein production. The technology enables fibrous structure replication from 80% organic pea isolates with superior water-holding capacity. Plant-based meat manufacturers in Germany and the Netherlands are adopting at scale, compressing development cycles for next-generation analogues while raising the technical barrier for commodity isolate suppliers.
EFSA's expanded novel food dossier requirements for protein extraction claims are tightening formulation transparency in Europe. The regulation mandates comprehensive toxicological and nutritional characterization for new isolate applications. Sports nutrition and infant formula segments face the longest approval timelines, driving suppliers to prioritize dossier investment over geographic expansion.
Clean-label procurement mandates from retail grocery chains are displacing conventional specification-based purchasing. Buyers now require third-party organic certification, carbon footprint documentation, and allergen-free processing guarantees as table stakes. This behavioral shift concentrates volume with vertically integrated processors in Germany and France who control certified acreage through direct farm partnerships.
Organic Pea Protein Market Segmentation
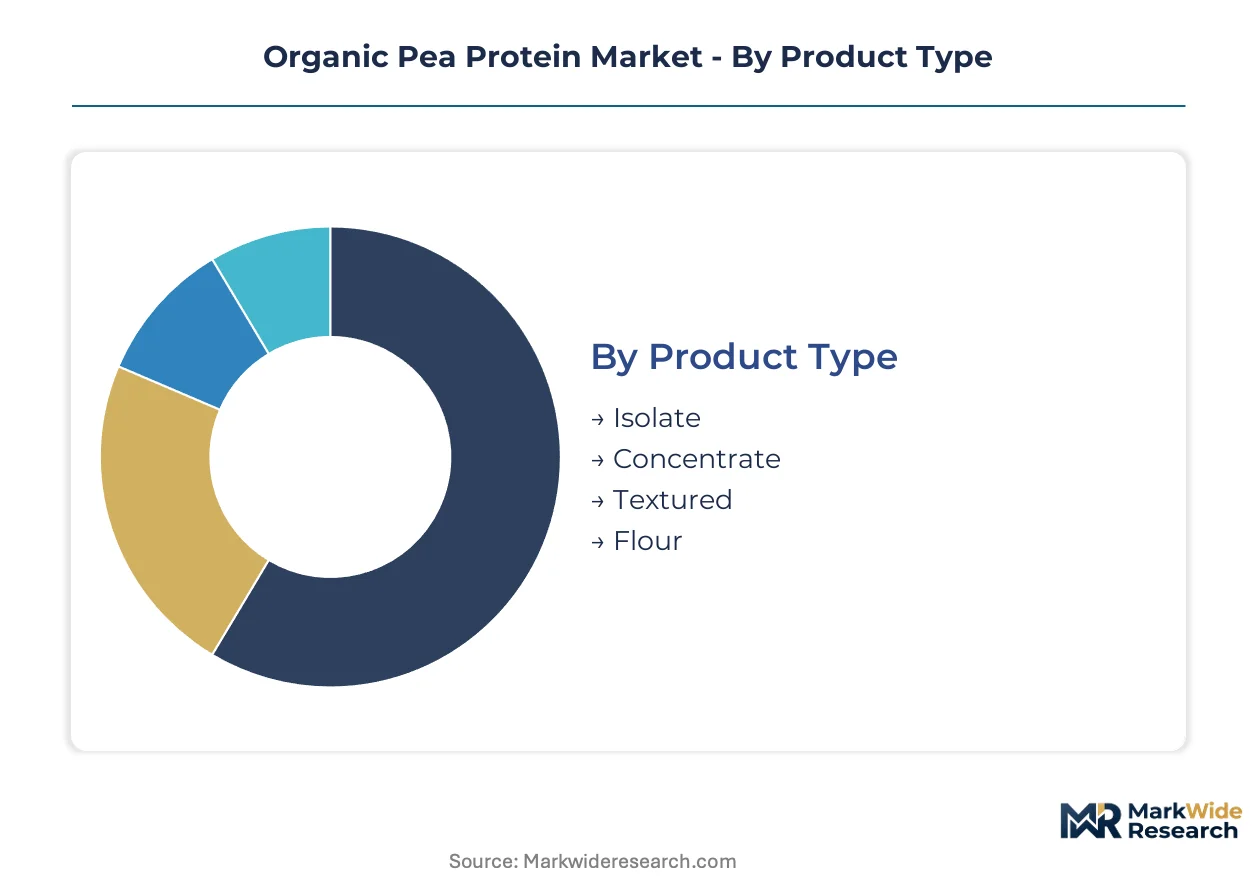
Organic pea protein segmentation reveals how purity grades, formulation requirements, and channel economics partition buyer priorities. Manufacturers select isolate or textured formats based on functional specifications, while application-driven procurement concentrates volume in meat alternatives and sports nutrition.
Product Type:
Buyers differentiate primarily on protein density thresholds and processing tolerances, with premium formulations demanding isolate purity while cost-sensitive applications absorb lower-concentration inputs.
- Isolate:Delivers 80-90% protein content through wet-milling and air-classification, achieving superior solubility for beverage applications. Demand concentrates in German sports nutrition manufacturing, where EFSA novel food dossier requirements for expanded extraction claims extend approval timelines for new entrants.
- Textured:Produced via high-moisture extrusion to replicate fibrous meat structures from 80% protein isolates. Plant-based meat manufacturers in the Netherlands and Germany adopt at scale as extrusion technology improves water-holding capacity and bite texture replication.
- Concentrate:Retains more starch and fiber than isolate, typically achieving 60-75% protein content for bakery fortification and cost-sensitive applications.
- Flour:Whole-milled organic yellow pea with minimal processing, serving gluten-free baking and traditional food applications where protein content matters less than binding functionality.
Volume sits with Concentrate for broad inclusion economics; growth tilts toward Textured as meat alternative formulation accelerates.
Application:
End-use specifications determine protein grade selection, with performance-positioned categories commanding isolate premiums while mass-market applications absorb concentrate or flour inputs.
- Meat Alternatives:Requires textured protein with fibrous structure replication through extrusion technology. Clean-label procurement mandates from European retail chains now require carbon footprint documentation alongside organic certification, favoring vertically integrated suppliers with German or French milling operations.
- Sports Nutrition:Demands isolate-grade purity for rapid dispersibility and branched-chain amino acid positioning. Per-kilogram pricing sustains premiums above conventional bakery inclusion, reflecting allergen-free claims and certification value capture.
- Beverages:Prioritizes solubility and neutral flavor profiles, with isolate dominating ready-to-drink protein fortification.
- Snacks:Absorbs concentrate and flour grades for protein-enriched bars and extruded products where texture tolerance is wider.
- Bakery:Utilizes lower-concentration inputs for gluten-free structure and protein fortification in conventional bread and pastry applications.
Revenue concentrates in Sports Nutrition; expansion runs fastest through Meat Alternatives as extrusion capability scales.
Distribution Channel:
Channel selection reflects buyer sophistication and volume scale, with institutional procurement bypassing retail entirely while emerging brands build through direct-to-consumer pathways.
- Supermarkets:Dominates volume for established food manufacturers integrating organic pea protein into mainstream product lines. Clean-label procurement mandates from German and French retail chains now require third-party organic certification and carbon footprint documentation as standard terms.
- Online Retail:Accelerates for direct-to-consumer sports nutrition brands and specialty ingredient suppliers targeting small-batch food manufacturers. The channel captures formulation experimentation demand before scale-up to conventional retail distribution.
- Health Stores:Serves premium-positioned isolate sales for consumer-packaged sports nutrition and allergen-free baking ingredients.
- Specialty Stores:Focuses on professional culinary and small-scale food service procurement for plant-based menu development.
Transaction value concentrates with Supermarkets; channel development favors Online Retail as ingredient e-commerce infrastructure matures.
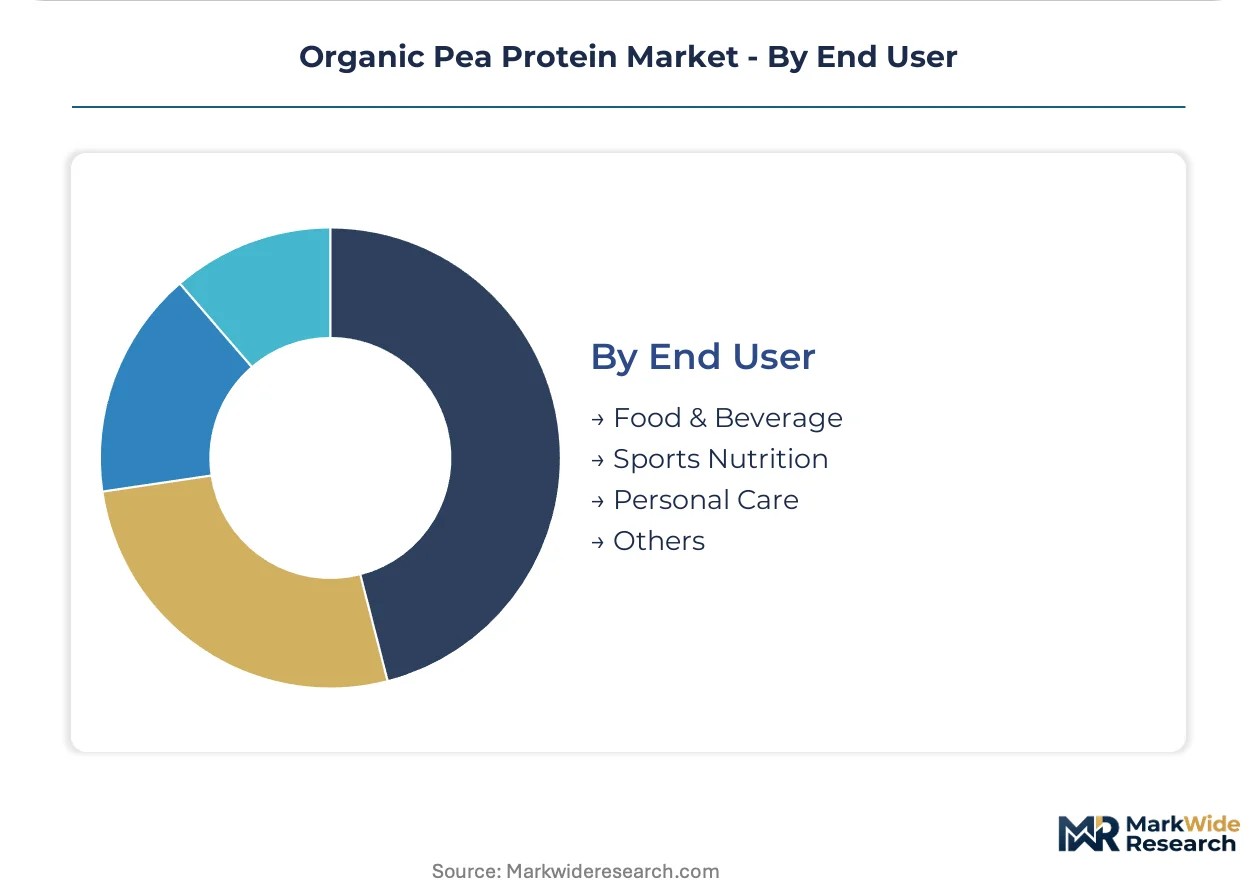
End User:
User category determines specification stringency, with regulated segments facing extended approval timelines while conventional food applications move faster from trial to scale.
- Sports Nutrition:Commands highest per-kilogram pricing through performance-positioned branding and rapid dispersibility requirements. EFSA novel food dossier delays for expanded protein extraction claims freeze formulation innovation timelines, particularly for infant-adjacent positioning.
- Food & Beverage:Absorbs broadest volume across beverage, bakery, and meat alternative applications, with procurement concentrating on verified supply chain transparency under EU Green Deal traceability mandates.
- Personal Care:Emerges for protein hydrolysates in cosmetic formulations, though volumes remain fractional compared to nutritional applications.
- Others:Captures pet nutrition and specialized industrial applications with non-standard specification requirements.
Volume aggregates in Food & Beverage; margin capture peaks in Sports Nutrition as certification premiums compound functional positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian prairie provinces anchor organic yellow pea cultivation, supplying North American and European processing hubs with certified non-GMO feedstock. Weather-driven yield volatility in Saskatchewan and Alberta creates input price instability for non-integrated ingredient manufacturers.
Germany
Food-tech clusters around Berlin and Hamburg accelerate clean-label formulation partnerships with plant-based meat manufacturers. The EU Green Deal's Farm to Fork strategy mandates carbon footprint documentation for imported organic pulses, favoring domestic wet-milling processors with verified supply chain transparency. Emsland Group leverages its Lower Saxony milling network to secure captive organic pea streams for isolate production.
France
Roquette Frères operates a vertically integrated processing footprint that combines European organic acreage partnerships with advanced air-classification capabilities. ANSM and DGCCRF enforcement of EU novel food regulations shapes isolate approval timelines for sports nutrition applications. The Hauts-de-France region concentrates extrusion technology expertise serving Dutch and German meat alternative manufacturers.
United States
Puris anchors North American output through domestic organic acreage partnerships across Minnesota and the Dakotas. FDA allergen labeling rules and USDA organic certification requirements create compliance complexity for isolate suppliers targeting beverage and bakery applications. The Midwest processing corridor links prairie cultivation to wet-milling infrastructure with shorter carbon-accounting trails than transatlantic alternatives.
Netherlands
High-moisture extrusion adoption scales rapidly among plant-based meat manufacturers seeking fibrous texture replication from 80% protein isolates. EFSA novel food dossier requirements for expanded extraction claims extend approval timelines for Dutch formulators targeting infant-adjacent positioning. Food Valley Wageningen clusters accelerate clean-label procurement mandates from retail grocery chains.
India
FSSAI organic certification alignment and domestic pulse processing infrastructure gaps create first-mover potential for isolate suppliers targeting urban protein fortification. Maharashtra and Gujarat food-tech hubs experiment with pea-dairy hybrid formulations for lactose-intolerant consumer segments. DGFT import tariff structures on protein isolates shape competitive dynamics between domestic and international ingredient sources.
Organic Pea Protein Market Competitive Environment
Global majors compete with regional champions across supply chain integration depth, with European processors leveraging proximity to EU regulatory frameworks and North American players capitalizing on prairie cultivation access. The vendor base stratifies into three tiers: vertically integrated farm-to-ingredient operators, specialist isolate purifiers, and diversified nutrition conglomerates blending pea proteins with complementary plant inputs. Dominant competitive moves include backward integration into certified organic acreage and strategic partnerships with extrusion technology providers for textured protein capabilities.
Among European integrated processors, Roquette Frères and Emsland Group exemplify the farm-to-isolate archetype through captive supply networks and continental milling infrastructure. Puris occupies a position representing North American vertical integration, while Glanbia plc sits within the diversified nutrition tier where pea isolates complement broader plant-protein portfolios. These three anchors illustrate how geographic cultivation access and regulatory compliance capabilities determine competitive positioning across the organic pea protein value chain.
| Leading Market Players |
|---|
| Roquette Frères |
| Puris |
| Ingredion Incorporated |
| Axiom Foods, Inc. |
| Glanbia plc |
| Emsland Group |
| The Scoular Company |
| Cosucra Groupe Warcoing SA |
| The Green Labs LLC |
| Others |
Value Chain & Pricing Dynamics
High-moisture extrusion maturation is simultaneously compressing textured protein production costs and concentrating supply among European processors with captive extrusion capacity. Wet-milling scale economies favor integrated operators who control certified organic acreage through direct farm partnerships in Germany and France.
Pricing Analysis
Carbon footprint documentation and third-party organic certification function as bundled warranty elements that isolate suppliers must include to access European retail procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates EFSA dossier-compliant isolate from conventional concentrate and whole flour grades. Pricing pressure stems from soy protein isolate substitution in cost-sensitive bakery applications where allergen-free claims carry less purchase influence. Mass-market beverage manufacturers exhibit highest price sensitivity; sports nutrition brands absorb certification premiums for rapid dispersibility performance.
Supply Chain Analysis
EU Green Deal local-content rules and Farm to Fork traceability mandates are reshaping sourcing patterns toward European-milled isolates with verified cultivation documentation. Supply concentration rests on Canada, Ukraine, and France as primary organic yellow pea cultivation zones. Raw material dependencies include certified seed stock, organic nitrogen fertilizers, and wet-milling enzymes. Single-source vulnerability runs through Canadian prairie weather exposure that disrupts non-integrated processors. Distribution runs through vertically integrated farm-to-ingredient operators who bypass commodity spot markets through long-term offtake contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic pea protein operates as a supply-constrained market where certified acreage expansion timelines prop isolate pricing. USDA three-year organic transition periods and EFSA equivalence verification create structural bottlenecks that sustain margin capture for incumbent processors.
For Market Incumbents: Extend backward integration into certified organic acreage through direct farm partnerships in Saskatchewan and Alberta to secure non-GMO pea streams against weather-driven yield volatility. Invest in high-moisture extrusion capacity to capture textured protein demand from plant-based meat manufacturers in Germany and the Netherlands. Prioritize EFSA novel food dossier investment over geographic expansion to defend formulation innovation timelines against regulatory approval delays. For New Entrants and Emerging Players: EU Green Deal carbon-border adjustment mechanism implementation in 2026 opens a window for early-compliant suppliers with verified supply chain transparency documentation. Target underpenetrated Indian functional foods through FSSAI organic certification alignment and urban protein fortification partnerships in Maharashtra and Gujarat food-tech hubs. Lead with precision fermentation hybrid formulations that combine pea isolates with fermentation-derived ingredients for next-generation dairy alternatives. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified nutrition conglomerates seeking plant-protein portfolio expansion. Long-term viability hinges on captive supply chain control rather than commodity trading margins. Monitor EFSA novel food dossier approval velocity as the inflection indicator for isolate supplier valuation multiples; accelerated approvals signal expanded use-case penetration in sports nutrition and infant-adjacent segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Acreage | Direct farm partnerships in Canadian prairie provinces secure non-GMO organic yellow pea supply against weather volatility. |
| High-Moisture Extrusion Capacity Buildout | European processors in Germany and France capture textured protein demand from plant-based meat manufacturers. |
| EFSA Novel Food Dossier Investment | Comprehensive toxicological characterization unlocks expanded extraction claims in sports nutrition and infant formula segments. |
| Carbon-Border Adjustment Compliance Program | Verified supply chain documentation secures preferential access as EU CBAM raises import barriers for non-verified chains. |
| Precision Fermentation Hybrid Formulation | Combining pea isolates with fermentation-derived ingredients enables superior mouthfeel in next-generation dairy alternatives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with wet-milling plant managers, organic certification officers, procurement leads at plant-based meat manufacturers, and sports nutrition formulation directors combined with secondary validation from USDA organic certification databases, EFSA novel food dossier registers, and EU customs import records. Bottom-up volume modeling triangulated against top-down market sizing from ingredient supplier revenue disclosures.
Product type granularity modeled isolate, textured, concentrate, and flour grades separately across application segments including meat alternatives, sports nutrition, beverages, snacks, and bakery. Geographic dimension captured country-level regulatory clusters under EU Green Deal, FDA allergen labeling, and FSSAI organic frameworks. CAGR derivation applied segment-specific growth differentials informed by extrusion technology adoption curves and clean-label procurement mandate penetration rates.
The model assumes a particular technology adoption path; alternative pathways for high-moisture extrusion scale-up would alter the outlook for textured protein volume distribution. Forecasts reflect assumptions regarding EFSA dossier approval timelines, organic acreage expansion rates, and carbon-border adjustment implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Soy Food Products Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
India Pea Protein Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
United States Textured Vegetable Protein Market