
 Fava Bean Protein Market | 2026-2036
Fava Bean Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Fava Bean Protein Market Analysis
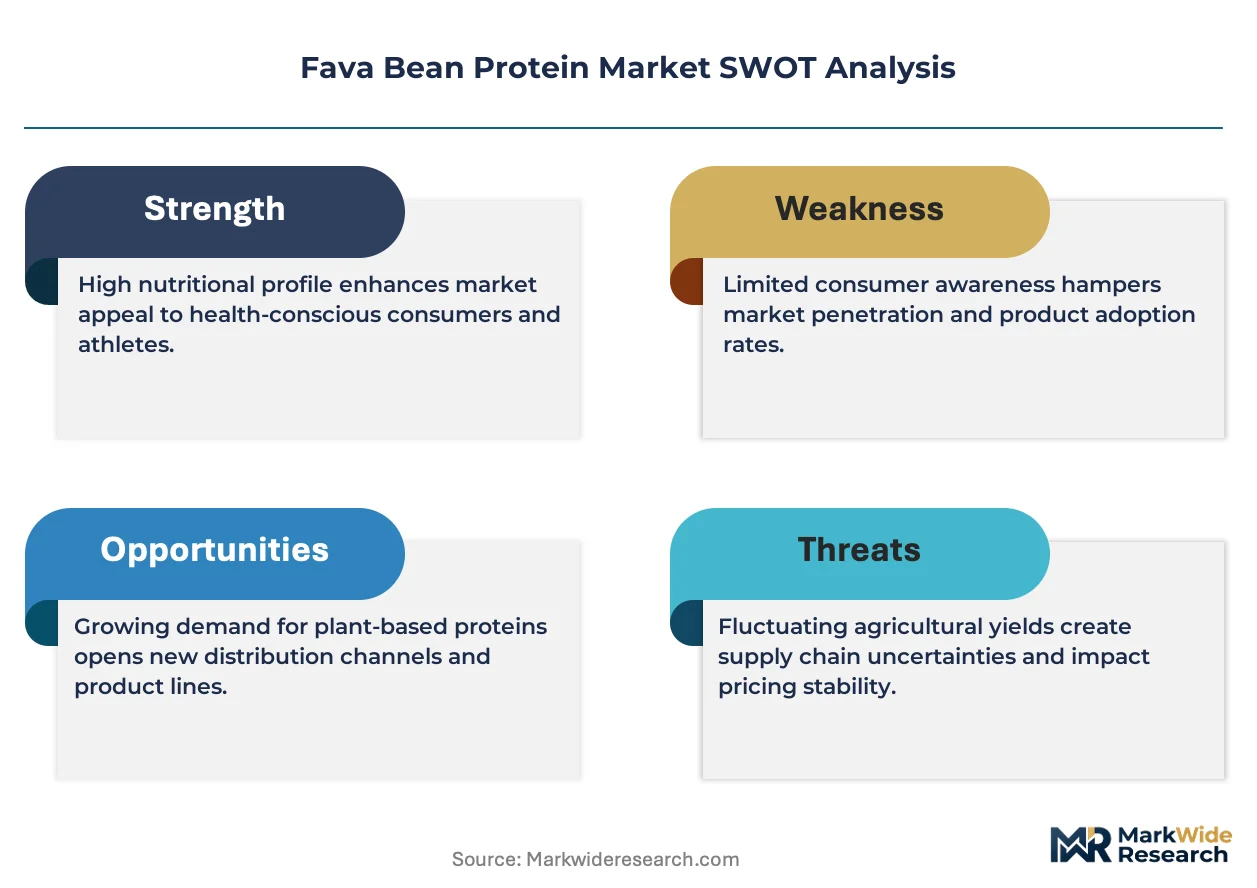
Project finance tied to sustainable agriculture is fragmenting competitive entry in fava bean protein, allowing smaller processors to secure acreage-linked credit without owning farmland. Roquette Frères leverages its European milling infrastructure to anchor supply security for isolate production. Cargill competes through backward integration into North American pulse origination. Puris Proteins differentiates via non-GMO identity preservation from farm to finished ingredient.
Fava bean protein denotes the proteinaceous fraction extracted from Vicia faba seeds, typically comprising 60-90% protein by dry weight depending on processing intensity, with residual starch and fiber removed through wet or dry fractionation to yield isolates, concentrates, or functional flours for food systems. Its primary commercial purpose centers on delivering emulsification, gelation, and water-binding functionality in plant-based formulations where allergen-free positioning relative to soy or wheat proteins commands formulation preference. Isolate commands the deepest margin pools due to minimum-protein thresholds required by meat-alternative extrusion processes, while concentrate grows fastest among bakery applications where moderate protein levels balance cost with nutritional claim eligibility. Flour retains volume leadership in animal feed compounding where protein content standardization matters less than bulk pricing.
The EU Green Deal and REACH frameworks govern carbon footprint disclosure and chemical safety for novel food proteins entering European formulations, compelling processors to document lifecycle emissions and allergenicity profiles before market access. FDA GRAS self-determination and USDA organic certification shape parallel pathways in the United States, where clean-label positioning requires third-party verification. Stakeholders must monitor how evolving protein-quality scoring methodologies by regulators recalibrate formulation premiums across isolate, concentrate, and flour grades.
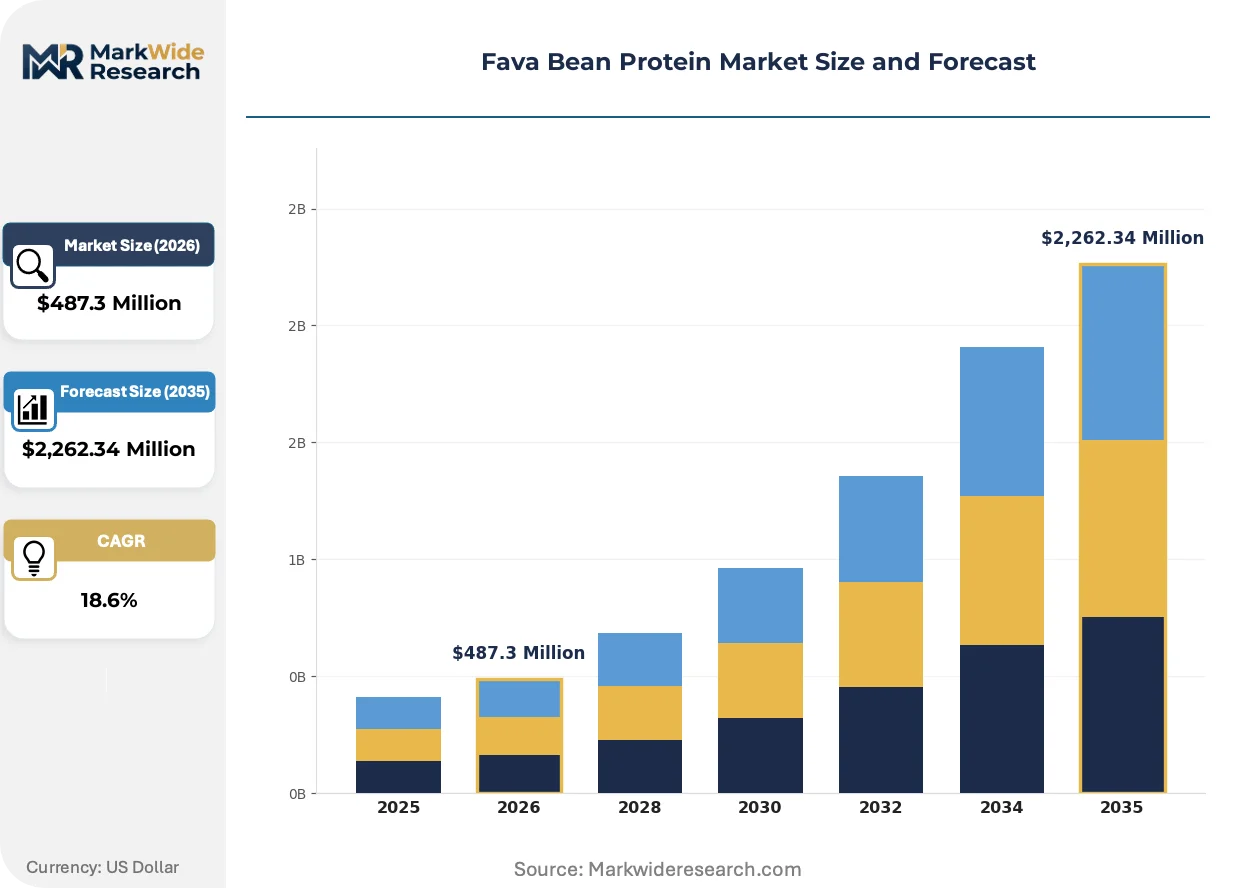
Market Dynamics
The EU Green Deal's carbon accounting mandates are restructuring ingredient procurement across European food manufacturing, forcing formulators to document lifecycle emissions and pivot toward low-carbon protein sources.
Growth Catalysts
- REACH compliance pressure:Chemical safety disclosure requirements under EU frameworks accelerate substitution of soy and wheat proteins with allergen-free fava bean isolates in clean-label formulations.
- Plant-based meat extrusion:Wet-fractionation advances enable 80%+ protein isolates that meet gelation thresholds for high-moisture meat analogues, pulling demand from Dutch ingredient distributors serving North European processors.
- Germany:Carbon border adjustments on imported food ingredients drive domestic manufacturers to source regionally processed fava bean protein with verified emissions documentation.
Market Restraints
- Input cost volatility:Fava bean acreage competes with wheat and rapeseed for rotation slots, exposing processors to commodity price swings in European agricultural futures markets.
- Supply concentration risk:Wet-milling infrastructure for isolate-grade production clusters in France and the Netherlands, creating single-source dependency for North European formulators.
- Technical limitation:Beany off-flavor compounds persist in standard concentrates, restricting application in neutral-tasting beverage systems without additional masking investments.
Strategic Opportunities
- Underpenetrated bakery applications:Moderate-protein concentrates qualify for nutritional claims in German and Austrian bread formulations where cost sensitivity limits isolate adoption.
- EU organic certification:Premium positioning for identity-preserved organic fava bean protein opens formulation slots in Scandinavian retail private-label programmes.
- Precision fermentation convergence:Hybrid formulations combining fava bean functional bases with microbial proteins enable texture profiles unreachable by either input alone.
Industry Challenges
- Skill scarcity in wet-fractionation engineering:European processors compete for chemical engineers experienced in aqueous protein extraction from oilseed and pulse matrices.
- Novel food dossier timelines:EFSA safety assessments for new fava bean protein variants extend 18-24 months, delaying commercial launch windows for isolate innovations.
- Legacy ERP integration:Farm-to-finished-ingredient traceability systems require middleware development to connect elevator receipt data with food manufacturer procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fava Bean Protein Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Flour, Whole Bean End User: Food Manufacturing, Dietary Supplements, Animal Feed, Bakery Application: Meat Alternatives, Protein Fortification, Snacks, Beverages Sales Channel: Online Retail, Supermarkets, Health Food Stores, Distributors |
| Companies Covered | Cargill, Ingredion, Roquette Frères, BI Nutraceuticals, GrainCorp, Puris Proteins, Prairie Fava, Vestkorn Milling, AGT Food and Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fava Bean Protein Market Emerging Trajectories
Digital traceability infrastructure and regulatory disclosure automation are compressing the gap between agricultural origination and finished ingredient certification, reshaping how protein processors validate sustainability claims.
Near-infrared spectroscopy coupled with blockchain-based provenance tracking is digitizing identity preservation from European farm cooperatives through to isolate production facilities. Dutch ingredient distributors now require spectroscopic protein-content verification at intake, compressing quality assurance cycles from weeks to hours and reducing disputed shipments.
CSRD sustainability reporting mandates force European food manufacturers to document Scope 3 emissions from agricultural inputs, compelling processors to deploy lifecycle assessment software that automates carbon footprint calculations per production batch. German meat-alternative brands are responding by contracting isolate suppliers with pre-verified emissions baselines.
Ingredient distributors in the Netherlands are consolidating procurement volumes through long-term offtake agreements with wet-milling facilities, displacing spot-market purchasing for North European formulators. This concentration enables volume-tier pricing but reduces formulation flexibility for mid-sized bakery and snack manufacturers seeking smaller minimum order quantities.
Fava Bean Protein Market Segmentation
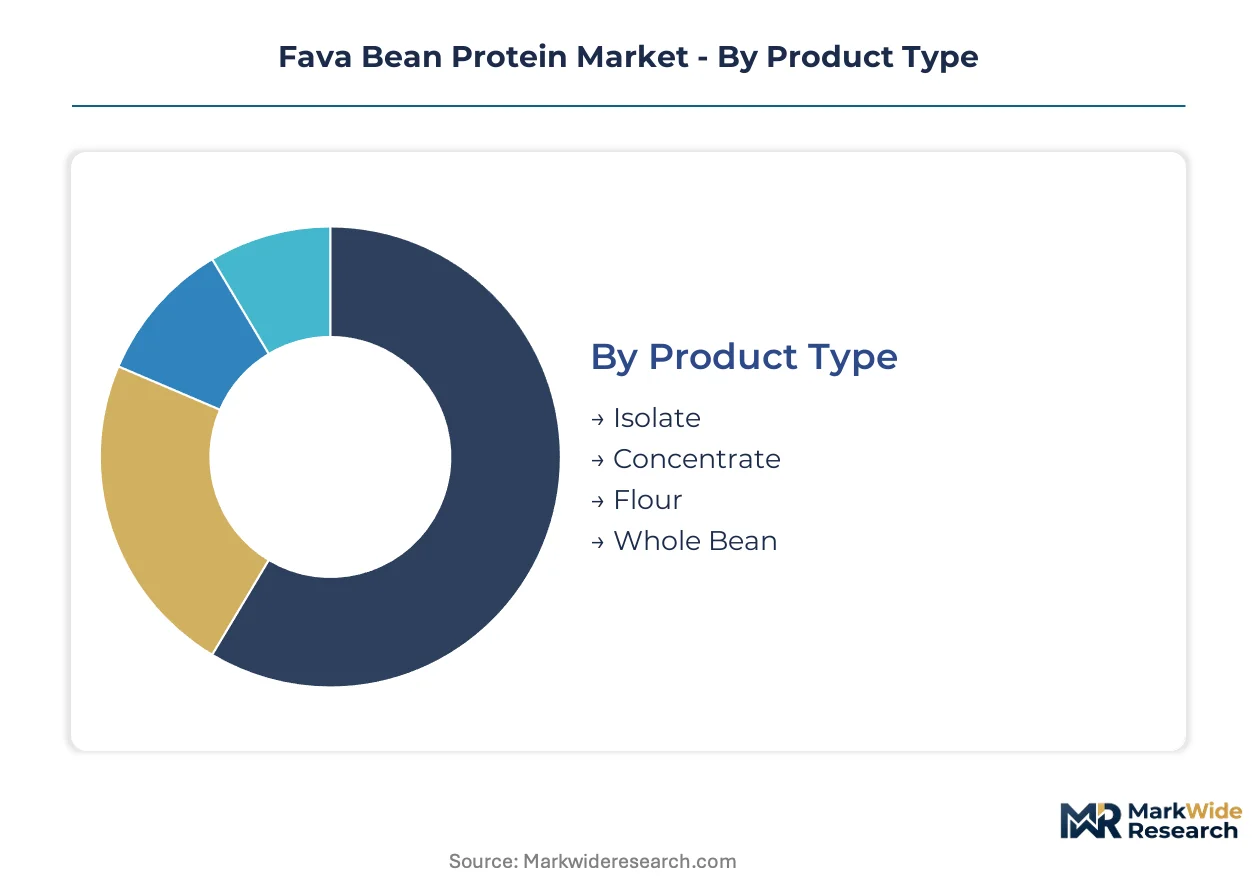
Fava bean protein segments diverge sharply by margin potential and technical specification. Isolate production demands wet-fractionation infrastructure that few processors control, while flour and whole bean channels compete on commodity pricing.
Product Type:
Cost tier separates the four product categories, with processing intensity directly determining protein purity thresholds and pricing power.
- Isolate:Delivers 80-90% protein content through aqueous extraction and membrane filtration. Dutch wet-milling facilities supply North European meat-alternative extruders who require gelation performance that lower grades cannot match. EFSA novel food dossiers and carbon accounting documentation add regulatory overhead that smaller processors cannot absorb.
- Concentrate:Achieves 60-70% protein through simpler dry or wet fractionation, retaining more starch and fiber. German bakery formulators favor this tier for nutritional claims in bread where cost sensitivity limits isolate adoption, though beany off-flavors restrict beverage applications without masking investments.
- Flour:Ground whole or dehulled beans yielding 25-40% protein serve animal feed compounders prioritizing bulk pricing over standardization.
- Whole Bean:Minimally processed seeds target niche foodservice and traditional cuisine markets with limited value-add capture.
Isolate commands the established base. The steepest expansion runs through Concentrate.
End User:
Application maturity varies dramatically across these four customer types, with regulatory exposure and formulation complexity shaping procurement patterns.
- Food Manufacturing:Plant-based meat producers in Germany and the Netherlands drive isolate demand for high-moisture extrusion. CSRD Scope 3 disclosure mandates force these manufacturers to verify emissions documentation from agricultural inputs through finished ingredient.
- Dietary Supplements:Powder and capsule formulators seek allergen-free positioning against soy and whey, though EFSA health claim restrictions limit marketing latitude in Europe.
- Animal Feed:Compounders purchase flour and whole bean for protein standardization in poultry and aquaculture rations, competing on commodity futures pricing.
- Bakery:Austrian and German bread producers adopt concentrates for nutritional fortification where moderate protein levels balance cost with claim eligibility.
Food Manufacturing anchors volume commitments. Dietary Supplements is climbing the fastest as clean-label positioning spreads.
Application:
Functional requirements dictate which product grades enter each use case, with texture and flavor neutrality determining formulation feasibility.
- Meat Alternatives:High-moisture extrusion demands isolates with precise gelation and water-binding profiles. Roquette Frères and specialized Dutch processors supply this segment through long-term offtake agreements.
- Protein Fortification:Beverage and dairy-alternative applications require flavor-masking investments to overcome beany notes in standard concentrates.
- Snacks:Extruded and baked formats tolerate lower protein purity, opening concentrate and flour adoption.
- Beverages:Neutral taste requirements restrict this channel to premium isolates with advanced debittering, limiting addressable volume.
Meat Alternatives holds the dominant share. Protein Fortification shows the steepest trajectory as hybrid formulations with microbial proteins emerge.
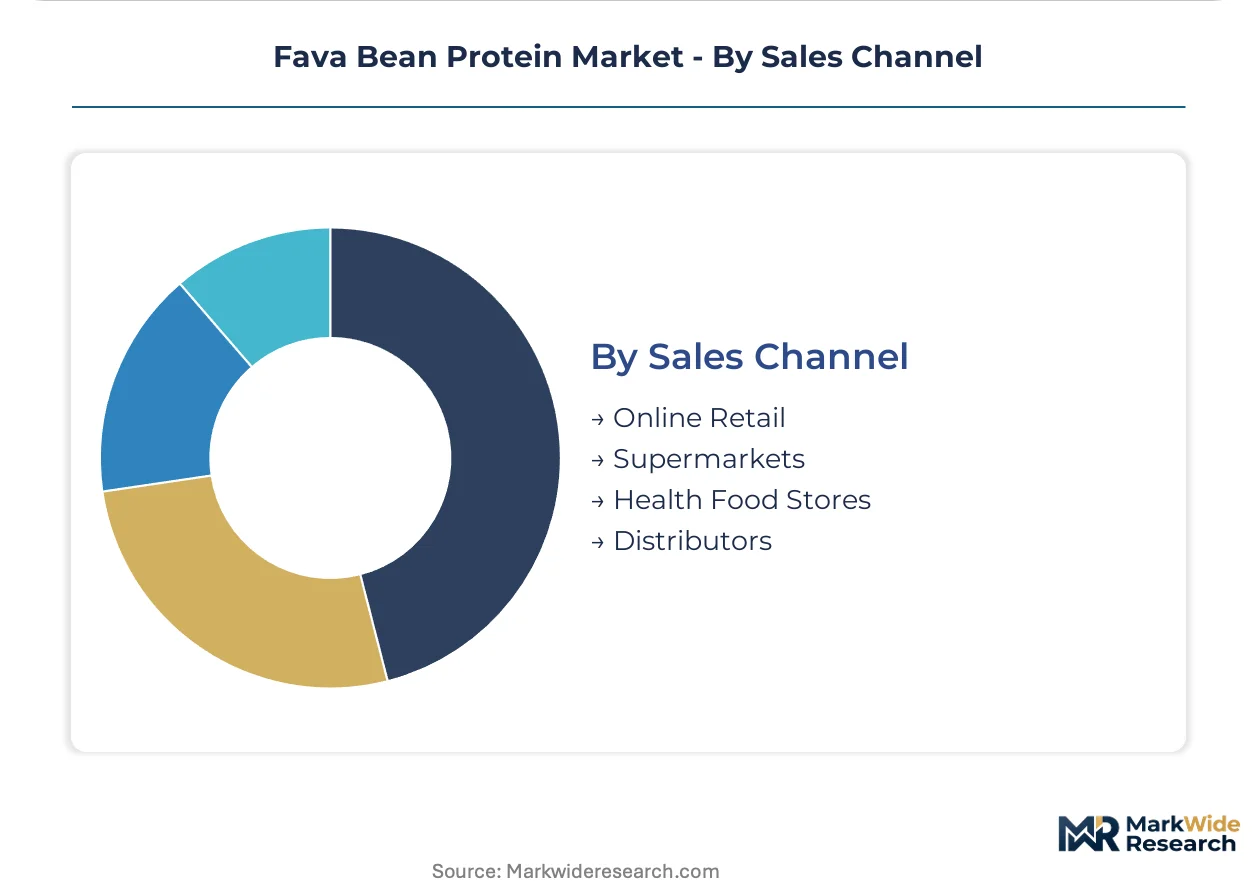
Sales Channel:
Customer scale and procurement sophistication determine channel selection, with institutional buyers consolidating volumes through specialized intermediaries.
- Distributors:Dutch ingredient distributors function as gatekeepers for North European formulators, consolidating procurement volumes and enforcing spectroscopic quality verification at intake.
- Online Retail:Direct-to-consumer protein powders and specialty ingredients reach supplement users and small foodservice operators.
- Supermarkets:Packaged finished goods containing fava bean protein appear in retail private-label programmes, particularly Scandinavian organic certification tiers.
- Health Food Stores:Niche positioning for non-GMO and organic identity-preserved products targets clean-label consumers.
Distributors control the established volume base. Online Retail is expanding most quickly as ingredient transparency tools proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon accounting mandates are redirecting procurement toward verified low-emission protein sources. Germany's meat-alternative manufacturers now require documented lifecycle emissions from agricultural inputs. Dutch ingredient distributors enforce spectroscopic quality verification at intake, compressing assurance cycles.
Germany
Plant-based meat extruders in Cologne and Berlin drive isolate demand for high-moisture analogue production. Carbon border adjustments on imported food ingredients force domestic manufacturers toward regionally processed fava bean protein with verified emissions documentation. Bavaria's agricultural cooperatives are contracting acreage for identity-preserved organic cultivation.
Netherlands
Ingredient distributors in Rotterdam and Wageningan function as procurement gatekeepers for North European formulators. REACH compliance pressure accelerates substitution of soy proteins with allergen-free isolates in clean-label formulations. Dutch wet-milling facilities cluster near port infrastructure, enabling efficient export logistics to Scandinavian markets.
France
Roquette Frères leverages established European milling infrastructure to anchor supply security for isolate-grade production. EFSA novel food dossier requirements extend safety assessment timelines for new protein variants. The Hauts-de-France region hosts specialized aqueous extraction facilities serving meat-alternative manufacturers.
United States
Puris Proteins and Cargill compete through backward integration into North American pulse origination. FDA GRAS self-determination and USDA organic certification shape parallel market access pathways. The Midwestern grain belt provides origination density for non-GMO identity preservation from farm to finished ingredient.
Canada
Prairie Fava exemplifies regional specialization in pulse protein extraction. Health Canada and PMRA frameworks govern novel food ingredient safety assessments. Saskatchewan's fava bean acreage expansion supports processor capacity investments for export-oriented isolate production.
Fava Bean Protein Market Vendor Landscape
On the supply side, the industry is consolidating around processors with captive wet-fractionation infrastructure and verified carbon accounting systems. Mid-sized specialists compete through identity-preserved organic certification and regional origination partnerships. Three archetypes dominate: multinational agribusinesses with backward integration into pulse origination, European wet-milling specialists with port-adjacent facilities, and North American non-GMO identity preservation operators. Competitive moves center on long-term offtake agreements with Dutch distributors and capacity expansion near major agricultural origination zones.
Within the multinational agribusiness tier, Cargill and Ingredion occupy positions anchored by North American grain origination networks and existing oilseed processing infrastructure. Roquette Frères exemplifies the European wet-milling specialist archetype, leveraging decades of aqueous extraction experience from starch and protein operations. Puris Proteins represents the identity-preservation specialist model, building market position through non-GMO verification systems from farm through finished ingredient. These three company types illustrate how capital intensity, regulatory compliance capability, and origination control separate competitive tiers in isolate-grade production.
| Leading Market Players |
|---|
| Cargill |
| Ingredion |
| Roquette Frères |
| BI Nutraceuticals |
| GrainCorp |
| Puris Proteins |
| Prairie Fava |
| Vestkorn Milling |
| AGT Food and Ingredients |
| Others |
Supply Flow & Price Mechanics
Dutch wet-milling infrastructure concentration funnels margin capture toward isolate-grade processors with aqueous extraction capabilities, while commodity flour channels compete on bulk tonnage without value-add premiums.
Pricing Analysis
Protein purity thresholds create the primary spread between product tiers, with EFSA novel food dossiers and carbon accounting documentation adding regulatory overhead that smaller processors cannot absorb. Three-tier pricing structure across premium isolate, standard concentrate, and economy flour levels reflects wet-fractionation intensity and certification burden. Cost compression in concentrate channels is intensifying because German bakery formulators prioritize nutritional claim eligibility over gelation performance. Animal feed compounders exhibit highest price sensitivity, while meat-alternative extruders in the Netherlands accept premium isolate pricing for verified emissions baselines.
Supply Chain Analysis
Fava bean acreage draws from France, the Netherlands, and Germany, where crop rotation competition with wheat and rapeseed exposes processors to commodity futures volatility. Wet-fractionation facilities rest on membrane filtration equipment, aqueous extraction chemicals, and energy-intensive drying infrastructure. Single-source vulnerability clusters around Rotterdam and Wageningan port-adjacent infrastructure serving North European formulators. Distribution runs through Dutch ingredient distributors consolidating procurement volumes and enforcing spectroscopic quality verification at intake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon border adjustments constitute a regulatory inflection that rewards processors with verified lifecycle emissions documentation and penalizes spot-market sourcing.
For Market Incumbents: Entrench supply security through backward integration into Bavarian and Saskatchewan acreage contracts, insulating against commodity price swings and rotation competition from cereal crops. Expand wet-fractionation capacity near Rotterdam port infrastructure to capture Dutch distributor consolidation. Prioritize CSRD-compliant traceability middleware connecting farm cooperatives to manufacturer procurement platforms. For New Entrants and Emerging Players: Build out organic identity-preserved supply chains for Scandinavian retail private-label programmes, where premium positioning offsets scale disadvantages. Target Austrian and German bakery concentrate applications, where cost sensitivity limits incumbent isolate dominance and beany off-flavor tolerance is higher than in beverages. Pursue direct-to-online retail channels with ingredient transparency tools that bypass distributor gatekeeper consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward wet-fractionation specialists with captive aqueous extraction infrastructure and EFSA novel food dossier capabilities, as regulatory barriers extend commercial launch timelines beyond capital-light competitors. Monitor EFSA safety assessment queue lengths as inflection indicators for isolate innovation velocity and first-mover premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acreage | Bavarian agricultural cooperatives contracting identity-preserved organic cultivation secures origination control. |
| Wet-Fractionation Capacity Expansion | Rotterdam port-adjacent facilities enable efficient export logistics to Scandinavian meat-alternative manufacturers. |
| CSRD Traceability Middleware | Farm-to-finished-ingredient systems connect elevator receipt data with German manufacturer procurement platforms. |
| Organic Certification Investment | Scandinavian retail private-label programmes demand identity-preserved documentation for premium positioning. |
| Hybrid Formulation Development | Precision fermentation convergence with fava bean functional bases enables texture profiles unreachable by single inputs. |
Methodological Framework
A standing panel of wet-fractionation plant managers, Dutch ingredient distributor procurement leads, German meat-alternative formulator R&D directors, and Bavarian agricultural cooperative supply planners provided ongoing calibration. Primary fieldwork combined with secondary validation from EU customs trade data, EFSA novel food dossier filings, SEC 10-K disclosures by listed processors, and CSRD sustainability reporting submissions. Bottom-up volume triangulation across isolate, concentrate, flour, and whole bean product tiers reconciled against top-down protein demand projections.
Scenario-bracketing anchored growth projections across the analysis window, with segmentation dimensions spanning protein purity grade, end-use application, and regional regulatory cluster. CAGRs derived from elasticity modeling of carbon accounting compliance pressure against substitution rates for soy and wheat proteins. Forecast inputs incorporated EU Green Deal implementation timelines and REACH chemical safety disclosure enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by North American non-GMO identity preservation operators would shift outcomes beyond modeled ranges. Cross-checking against EFSA novel food assessment queue lengths and Dutch distributor offtake agreement volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
South America Rice Protein Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Veggie Burger Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Low Fat Plant-Based Diet Market