
 Germany Plant Protein Market | 2026-2036
Germany Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Plant Protein Market Foresight
Precision fermentation and enzymatic extraction is reconfiguring how German manufacturers isolate functional proteins from legume and oilseed matrices. CHS Inc. leverages its North American origination network to supply non-GMO soy streams into German crushing facilities. BENEO anchors specialty chicory and rice protein applications through its Mannheim-based technical center. Kerry Group PLC competes on taste-masked protein systems for beverage and dairy analogue formulations.
Germany plant protein encompasses extracted, concentrated, or isolated proteinaceous fractions derived from pea, soy, rice, potato, hemp, and sunflower sources, typically achieving protein content between 50% and 90% dry weight depending on processing intensity, and serving primarily as functional nutrition inputs across food, supplement, and feed systems. Powder and isolate forms command the deepest margin pools due to their formulation flexibility and clean-label compatibility in sports nutrition and dairy analogue applications. Textured proteins from soy and pea sources are gaining share in meat alternative applications as extrusion technologies improve fibrous mouthfeel replication.
The European Food Safety Authority (EFSA) governs novel food approvals and protein-related health claims, while Germany's Federal Office of Consumer Protection and Food Safety (BVL) enforces national hygiene and labeling standards that directly shape product market access. REACH and the EU Farm to Fork Strategy impose upstream sustainability and chemical transparency obligations on ingredient importers and domestic processors alike. Stakeholders must monitor how Germany's transposition of the EU Deforestation Regulation reshapes supply chain documentation requirements for imported soy and palm-linked protein streams.
Market Dynamics
Precision fermentation platforms are reconfiguring protein isolation economics across German processing facilities, compressing extraction yields while tightening sustainability compliance thresholds under the EU Farm to Fork Strategy.
Growth Catalysts
- EU Farm to Fork Strategy:Germany's national implementation tightens carbon and chemical transparency benchmarks, forcing ingredient importers to document supply chain deforestation risks and accelerating certified protein adoption.
- Sports nutrition formulation:Beverage brands in Bavaria and North Rhine-Westphalia are accelerating pea and soy isolate purchases for taste-masked protein systems targeting endurance athletes.
- Extrusion technology maturation:Improved fibrous mouthfeel replication in textured pea and soy proteins is displacing conventional meat applications in foodservice contract manufacturing.
Market Restraints
- Input cost volatility:Non-GMO soybean origination costs fluctuate with North American harvest cycles, squeezing margin pools for German crushing facilities dependent on imported streams.
- Supply concentration risk:Chicory and rice protein specialty sourcing clusters around Mannheim-based technical centers, creating single-point vulnerability for functional ingredient supply.
- Regulatory friction:EFSA novel food approval timelines extend 18-24 months for enzymatic extraction methods, delaying market access for precision fermentation outputs.
Strategic Opportunities
- Underpenetrated feed applications:Pet nutrition and aquaculture sectors in Lower Saxony show minimal plant protein penetration, offering white space for potato and hemp protein fractions.
- Technology convergence:Combining enzymatic extraction with membrane filtration is enabling 90%+ protein isolates from sunflower and hemp matrices previously limited to 70% concentrates.
- Regulatory tailwind:Germany's transposition of the EU Deforestation Regulation creates first-mover advantage for domestic processors with documented sustainable sourcing.
Industry Challenges
- Skill gap in bioprocess engineering:German facilities face acute shortages of fermentation specialists capable of scaling precision platforms from pilot to commercial volumes.
- Capex intensity:Membrane filtration and chromatography infrastructure for high-purity isolates demands 40-60 million euro facility investments, constraining mid-tier processor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Plant Protein Market |
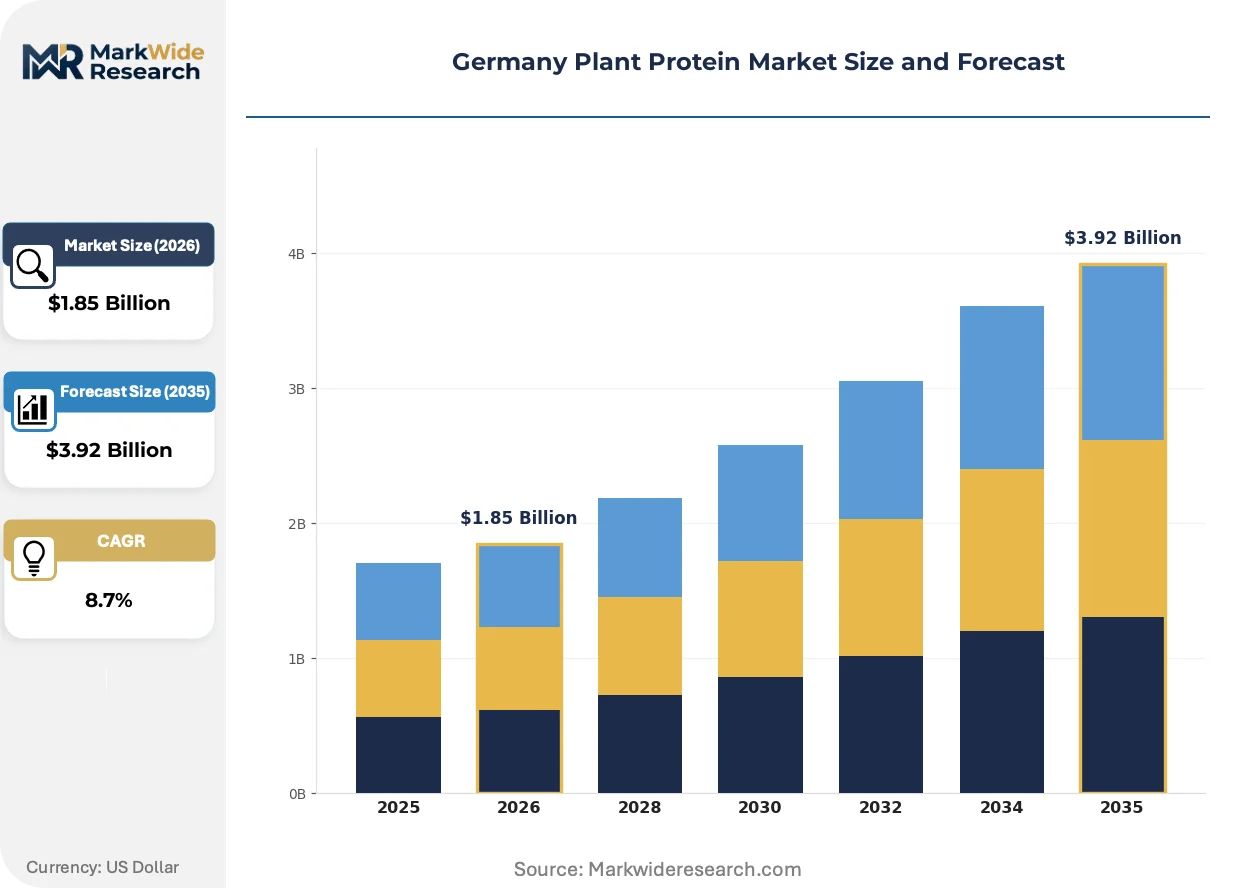
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source: Pea, Soy, Rice, Potato, Hemp, Sunflower Product Form: Powder, Isolate, Concentrate, Textured, Flakes Application: Sports Nutrition, Bakery, Beverages, Dairy Analogues, Meat Alternatives End User: Food Manufacturers, Dietary Supplement Companies, Animal Feed Producers, Cosmetic Brands |
| Companies Covered | CHS Inc., Lantmännen, Archer Daniels Midland Company, Crespel & Deiters, BENEO, Ingredion Incorporated, Wilmar International Ltd, Emsland Group, Kerry Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Plant Protein Market Shifts & Advancements
Protein extraction methodologies are bifurcating between legacy mechanical separation and advanced biotechnological platforms, with sustainability metrics increasingly determining equipment procurement decisions across German processing clusters.
Enzymatic extraction paired with precision fermentation is migrating from pilot-scale demonstration to commercial deployment. Specialty ingredient houses in Baden-Württemberg are retrofitting existing oilseed crushing lines with cell-culture capabilities. This migration from conventional solvent extraction is compressing water and energy intensity benchmarks while enabling novel protein structures unavailable through mechanical processing.
Germany's Federal Office of Consumer Protection and Food Safety (BVL) is enforcing stricter hygiene documentation under national transpositions of EU hygiene package regulations. Processing facilities must now validate allergen cross-contamination protocols for multi-protein lines. Dairy analogue manufacturers face the steepest compliance burden, reformulating production schedules to segregate soy, pea, and rice protein runs.
Direct procurement contracts between sports nutrition brands and crushing facilities are displacing traditional ingredient distributor networks. Bavarian formulation houses now source pea isolates through bilateral agreements with domestic processors rather than Pan-European traders. This channel compression is most visible in North Rhine-Westphalia, where contract manufacturers consolidate volumes to secure price stability and traceability documentation required by export markets.
Germany Plant Protein Market Segmentation
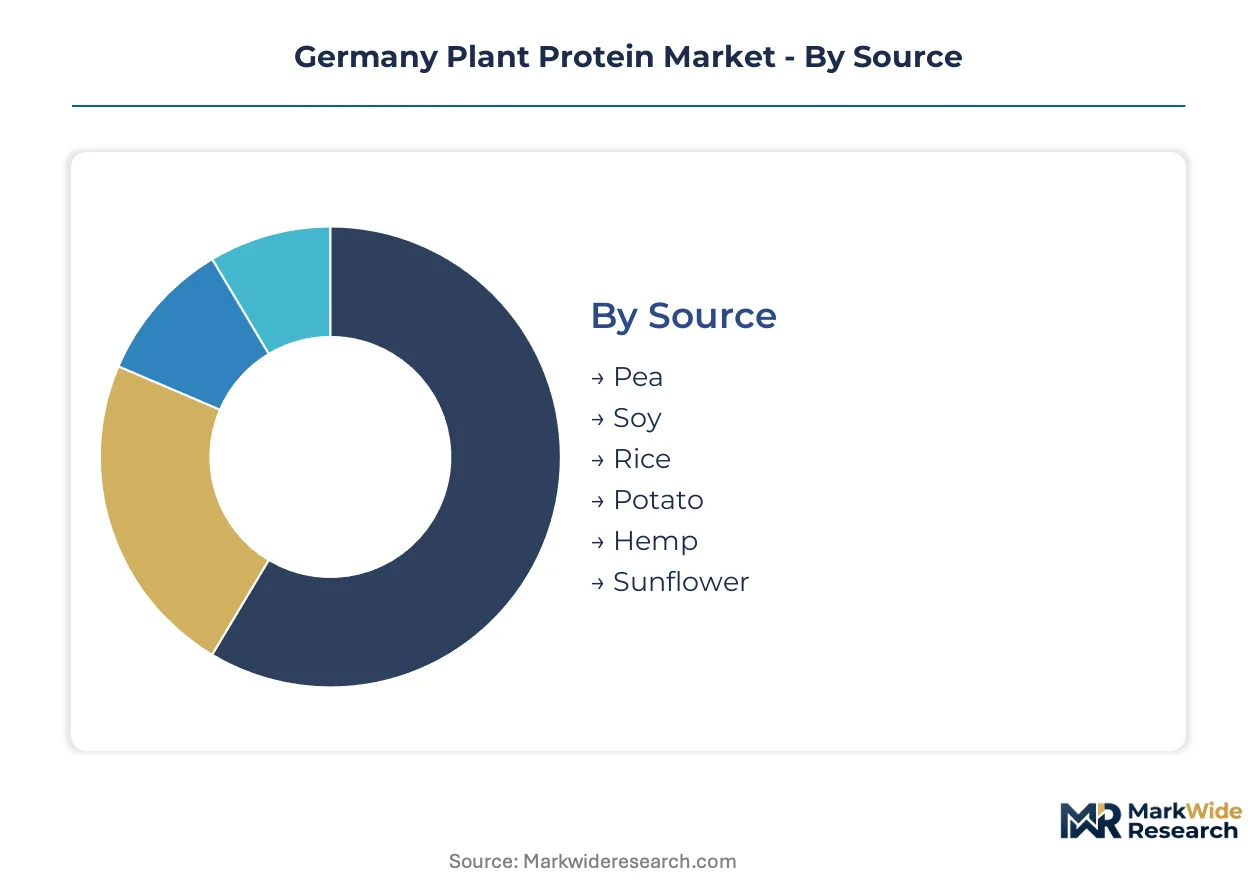
German plant protein procurement patterns diverge sharply across sourcing origins and formulation requirements. Technical service intensity varies by segment, with isolate grades demanding intensive application support while commodity concentrates require minimal post-sale engagement.
Source:
After-sales intensity peaks with novel protein streams requiring formulation troubleshooting, while legacy soy and pea categories run on standardized technical documentation.
- Pea:Isolates achieve 80-90% protein content through wet fractionation and membrane filtration. Bavarian sports nutrition brands in Munich and Nuremberg drive contract volumes for taste-masked systems. Yellow pea cultivars from Canadian Prairie origination dominate non-GMO supply.
- Soy:Defatted flakes and isolates retain functional gelling and emulsification properties. North Rhine-Westphalia crushing facilities in Cologne and Düsseldorf process imported North American beans for dairy analogue manufacturers. Non-GMO identity preservation adds 15-20% procurement overhead.
- Rice:Hypoallergenic protein concentrates from brown rice enzymatic extraction serve infant nutrition and sensitive digestive applications.
- Potato:Low-molecular-weight protein fractions from starch processing bystreams offer emulsification in gluten-free bakery.
- Hemp:Cold-pressed seed cakes yield 50% protein concentrates with omega fatty acid co-benefits for premium positioning.
- Sunflower:Dehulled kernel processing produces light-colored isolates for beverage clarity requirements.
Soy holds the largest share; momentum sits with pea as extrusion technology improves textural performance.
Product Form:
Margin architecture stratifies sharply across purity grades, with isolates commanding formulation premiums and textured forms competing on meat replacement functionality.
- Powder:Standardized 50-70% protein concentrates from spray-dried slurries serve bulk fortification. Animal feed producers in Lower Saxony purchase potato and hemp powders for pet nutrition applications. Price transparency through commodity exchanges limits supplier pricing power.
- Isolate:90%+ purity grades from chromatographic or membrane separation enable clean-label positioning. Beverage brands require solubility specifications below 50 micron particle distribution. Mannheim technical centers provide application-specific hydration protocols.
- Concentrate:Intermediate 70-85% protein grades balance cost and functionality for bakery and snack fortification.
- Textured:High-moisture extrusion creates fibrous structures replicating muscle tissue in meat alternatives.
- Flakes:Pre-hydrated, defatted soy flakes accelerate processing for traditional meat extenders.
Isolate captures the steepest margin expansion; textured forms gain share fastest through foodservice meat replacement contracts.
Application:
Volume concentration tracks regional manufacturing clusters, with Bavaria and North Rhine-Westphalia anchoring divergent end-use specializations.
- Sports Nutrition:Ready-to-drink beverages and powder blends demand rapid-digesting isolates with complete amino acid profiles. Cologne formulation houses specify leucine content above 8% for muscle protein synthesis claims.
- Bakery:Protein enrichment challenges gluten network development, requiring specialized hydration curves and reduced mixing intensities.
- Beverages:Suspension stability and heat stability specifications drive hydrocolloid-protein co-formulation complexity.
- Dairy Analogues:Fermented applications require specific gelation temperatures to replicate casein micelle behavior.
- Meat Alternatives:Whole-muscle replication demands directional fiber alignment through twin-screw extrusion parameter optimization.
Sports nutrition commands the deepest supplier relationships; meat alternatives show the steepest capacity expansion trajectory.
End User:
Procurement sophistication varies by sector maturity, with dietary supplement companies driving specification intensity and feed producers prioritizing cost optimization.
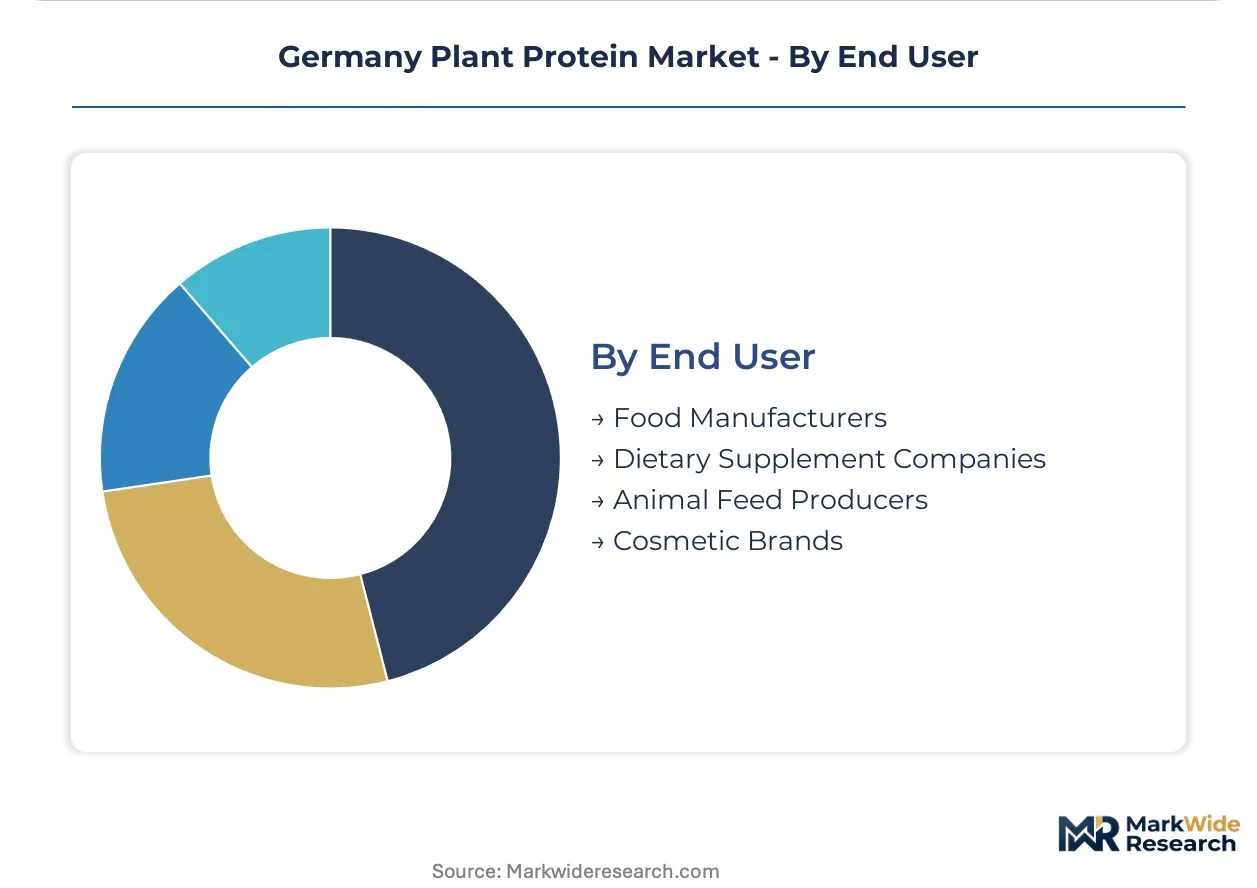
- Food Manufacturers:Integrated product development teams co-design protein systems with ingredient suppliers for specific texture targets.
- Dietary Supplement Companies:Third-party certification requirements for sport and organic claims necessitate extensive documentation and audit protocols.
- Animal Feed Producers:Aquaculture and pet nutrition sectors in Lower Saxony represent underpenetrated volume opportunity for alternative protein streams.
- Cosmetic Brands:Hydrolyzed protein fractions for hair and skin applications require low-molecular-weight specifications and heavy metal testing.
Food manufacturers represent the largest procurement volume; dietary supplement companies set the steepest quality and documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German plant protein procurement concentrates in food processing clusters where contract manufacturers serve sports nutrition brands and dairy analogue formulators with documented sustainability credentials.
Bavaria
Sports nutrition brands in Munich and Nuremberg drive isolate demand for taste-masked protein systems targeting endurance athletes. The BVL enforces national hygiene documentation for multi-protein production lines. Ingredient formulators in the Munich metropolitan area co-design hydration protocols with Mannheim technical centers.
North Rhine-Westphalia
Dairy analogue manufacturers in Cologne and Düsseldorf contract crushing facilities for defatted soy flakes with non-GMO identity preservation. REACH compliance obligations shape chemical transparency requirements for imported North American bean streams. Extrusion technology providers in the Ruhr industrial corridor refine fibrous mouthfeel replication for meat alternative applications.
Baden-Württemberg
Specialty ingredient houses retrofit oilseed crushing lines with precision fermentation capabilities. The EU Farm to Fork Strategy tightens carbon benchmarking for enzymatic extraction platforms. Bioprocess engineering talent shortages constrain pilot-to-commercial scaling in Stuttgart-area facilities.
Lower Saxony
Pet nutrition and aquaculture feed producers represent underpenetrated volume opportunity for potato and hemp protein fractions. National transposition of the EU Deforestation Regulation reshapes supply chain documentation for alternative protein imports. Starch processing bystream recovery operations in the Hanover region yield low-molecular-weight emulsification fractions.
Hesse
Cosmetic brands in Frankfurt specify hydrolyzed protein fractions for hair and skin applications requiring heavy metal testing protocols. EFSA novel food approval timelines extend market access delays for precision fermentation outputs. Rhein-Main logistics hubs consolidate distribution for Pan-European ingredient traders.
Germany Plant Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated agribusiness operators with origination networks anchor supply security for crushing facilities. Specialty ingredient houses with technical service capabilities capture formulation premiums in sports nutrition and dairy analogue segments. Mid-tier processors face margin compression from input cost volatility and capex barriers to high-purity isolate production. Dominant competitive moves include bilateral direct procurement contracts displacing distributor networks, and enzymatic extraction technology licensing partnerships.
Among North American-originated agribusiness operators, CHS Inc. exemplifies the supply-secured archetype through non-GMO soybean stream integration. Kerry Group PLC occupies a position within the formulation-specialist tier, anchoring taste-masked protein system development. BENEO represents the European technical-center model through its Mannheim-based specialty ingredient positioning. These three entities illustrate divergent strategic paths: upstream supply control, downstream formulation partnership, and regional technical service density.
| Leading Market Players |
|---|
| CHS Inc. |
| Lantmännen |
| Archer Daniels Midland Company |
| Crespel & Deiters |
| BENEO |
| Ingredion Incorporated |
| Wilmar International Ltd |
| Emsland Group |
| Kerry Group PLC |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp barge corridor anchors German plant protein logistics, with freight rate volatility from North Sea port congestion feeding directly into Bavarian crushing facility procurement costs and amplifying price spreads between commodity concentrates and certified isolates.
Pricing Analysis
Cost-plus contracts indexed to Euronext non-GMO soybean futures dominate German crushing facility offtake agreements, with premium-mid-economy pricing differentiation separating identity-preserved organic streams from conventional commodity grades. Certification tier and volume scale drive price spreads, with organic and EU Deforestation Regulation-compliant documentation adding procurement overhead. Cost compression in commodity concentrates intensifies as North American harvest volatility squeezes margin pools, while sports nutrition brands show least price sensitivity for taste-masked isolate systems.
Supply Chain Analysis
Canadian Prairie yellow pea origination and North American non-GMO soybean belts anchor German crushing facility feedstock, with enzymatic extraction inputs drawing from Mannheim-based specialty ingredient technical centers. Raw material dependencies center on defatted flakes, membrane filtration membranes, and chromatography resins. Single-source vulnerability concentrates around Mannheim chicory and rice protein clusters. Distribution runs through bilateral direct procurement contracts displacing Pan-European trader networks, with Bavarian formulation houses securing traceability documentation for export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in German plant protein markets as sports nutrition brands consolidate volumes through bilateral direct procurement, fragmenting traditional distributor networks and forcing mid-tier processors into price-tender relationships.
For Market Incumbents: Entrench supply security through backward integration into North American non-GMO origination networks, securing identity-preserved streams against EFSA novel food approval delays for precision fermentation substitutes. Add membrane filtration capacity in North Rhine-Westphalia to defend isolate margin pools from enzymatic extraction technology licensing entrants. For New Entrants and Emerging Players: Lower Saxony pet nutrition and aquaculture feed applications offer white-space volume opportunity with minimal incumbent technical service density. Target potato and hemp protein fractions for gluten-sensitive positioning, leveraging starch processing bystream recovery partnerships with Hanover-region operators for cost-advantaged feedstock access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation platform specialists with pilot-to-commercial scaling capabilities over legacy mechanical extraction assets. Five-to-ten year viability hinges on enzymatic extraction yield convergence with solvent-based benchmarks. Monitor EFSA novel food approval timeline compression as inflection signal for fermentation platform valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Commercial deployment of cell-culture platforms in Baden-Württemberg reduces water intensity versus legacy solvent extraction. |
| Backward Integration into Origination | Direct Canadian Prairie pea procurement contracts bypass Pan-European trader markups for Bavarian sports nutrition formulators. |
| EU Deforestation Regulation Compliance | Documented sustainable sourcing creates first-mover advantage for German processors exporting to regulated EU markets. |
| Membrane Filtration Capacity Addition | Chromatographic separation infrastructure in North Rhine-Westphalia enables 90%+ isolate purity for beverage clarity specifications. |
| Direct Procurement Channel Compression | Bilateral agreements between Cologne dairy analogue manufacturers and crushing facilities displace traditional ingredient distributors. |
Research Methodology
Cross-validation between primary interviews with crushing facility operations managers, sports nutrition brand procurement directors, and BVL regulatory compliance officers anchors the qualitative findings, with secondary validation drawing from EU Farm to Fork Strategy implementation documents, EFSA novel food approval databases, and German customs trade statistics. Bottom-up volume triangulation from facility-level capacity utilization converges with top-down demand modeling across application segments.
Calibration against historical price spreads between commodity concentrates and certified isolates informs the projection framework across the analysis window, with segmentation modeling spanning protein source, product form purity tier, application end-use, and regional manufacturing cluster. CAGRs derive from elasticity-adjusted demand curves incorporating EFSA approval timeline risk and enzymatic extraction yield improvement trajectories.
Practitioners should monitor North American harvest cycle volatility and EFSA novel food approval acceleration for early signals requiring forecast revision. Cross-checking against EU Deforestation Regulation implementation benchmarks and Euronext non-GMO futures price movements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Fish Market
Plant Based Food
India Pea Protein Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Vegan Asian Food Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Soy Protein Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Vegan Drink Mixes Market