
 Vegan Tortillas Market | 2026-2036
Vegan Tortillas Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Tortillas Market Analytics
USDA Organic certification is reorganizing supplier tiers in the vegan tortillas space, forcing ingredient traceability upgrades that smaller mills struggle to fund. GRUMA leverages its vertically integrated corn flour network to sustain cost advantages across North American retail channels. Siete Foods differentiates through grain-free formulations built on cassava and coconut flour bases. Mission Foods competes through refrigerated distribution scale that reaches food service accounts nationwide.
Vegan tortillas are thin, flexible flatbreads manufactured without animal-derived ingredients such as lard or whey, typically using vegetable oils, water, and nixtamalized corn or wheat flour as binding substrates, with shelf stability ranging from refrigerated seven-day windows to ambient six-month spans depending on preservative systems. Their primary commercial purpose is to serve as wrap and vessel substrates for prepared foods across retail and food service environments. Corn tortillas anchor volume in the product type dimension due to heritage authenticity and lower input costs, while gluten-free tortillas capture premium positioning as celiac and low-FODMAP diet adherence expands. The food service end user segment leads absolute consumption, though online retail in the distribution channel dimension posts the fastest route-to-consumer expansion as direct-to-pantry subscription models mature.
The FDA governs allergen labeling and facility sanitation standards that determine which co-manufacturers qualify for vegan production lines, while USDA Organic enforcement shapes premium tier access and price positioning. State-level cottage food laws in California and Texas create fragmented compliance landscapes for emerging brands entering regional retail. Stakeholders must monitor evolving plant-based protein fortification claims and the threshold at which regulators treat enhanced tortillas as functional foods rather than commodity bakery items.
Market Dynamics
USDA Organic enforcement is fragmenting supplier tiers by forcing traceability investments that smaller nixtamalization mills cannot finance, while FDA gluten-free labeling updates reshape co-manufacturer qualification protocols.
Growth Catalysts
- Plant-based menu mandates:Food service operators in California and Texas are expanding vegan wrap SKUs, driving bulk procurement contracts for corn and flour alternatives.
- REACH compliance alignment:European tortilla exporters adapting preservative formulations to meet ECHA chemical safety standards unlock premium retail placement in German and French supermarkets.
- Cassava flour processing:Novel extrusion technologies for grain-free bases reduce hydration variability, enabling consistent large-batch production previously limited to wheat formulations.
Market Restraints
- Organic corn input volatility:Drought cycles in Mexico's Sinaloa and Jalisco growing regions create price spikes that compress margins for certified organic lines.
- Refrigerated logistics concentration:Cold-chain distribution for seven-day shelf-life products depends on third-party networks concentrated in Texas and California, creating single-point vulnerability.
- Functional food threshold ambiguity:FDA has not clarified protein fortification levels that trigger nutritional supplement classification, freezing R&D pipelines for enhanced tortillas.
Strategic Opportunities
- Direct-to-pantry subscription models:Online retail channels bypass conventional grocery slotting fees, allowing emerging brands to build recurring revenue with celiac and low-FODMAP diet adherents.
- IRA clean manufacturing credits:US-based producers retrofitting nixtamalization facilities for energy efficiency capture federal incentives that offset organic certification compliance costs.
- Cross-laminated barrier films:Convergence of modified atmosphere packaging with compostable substrates extends ambient shelf life without synthetic preservatives, opening convenience store distribution.
Industry Challenges
- Nixtamalization expertise scarcity:Traditional lime-cooking knowledge required for authentic corn flavor profiles is concentrated among aging mill operators in Mexico and the US Southwest, constraining quality-scaled expansion.
- Multi-certification timeline compression:Simultaneous pursuit of USDA Organic, Non-GMO Project, and gluten-free validations creates 18-24 month product launch delays that miss seasonal menu windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Tortillas Market |
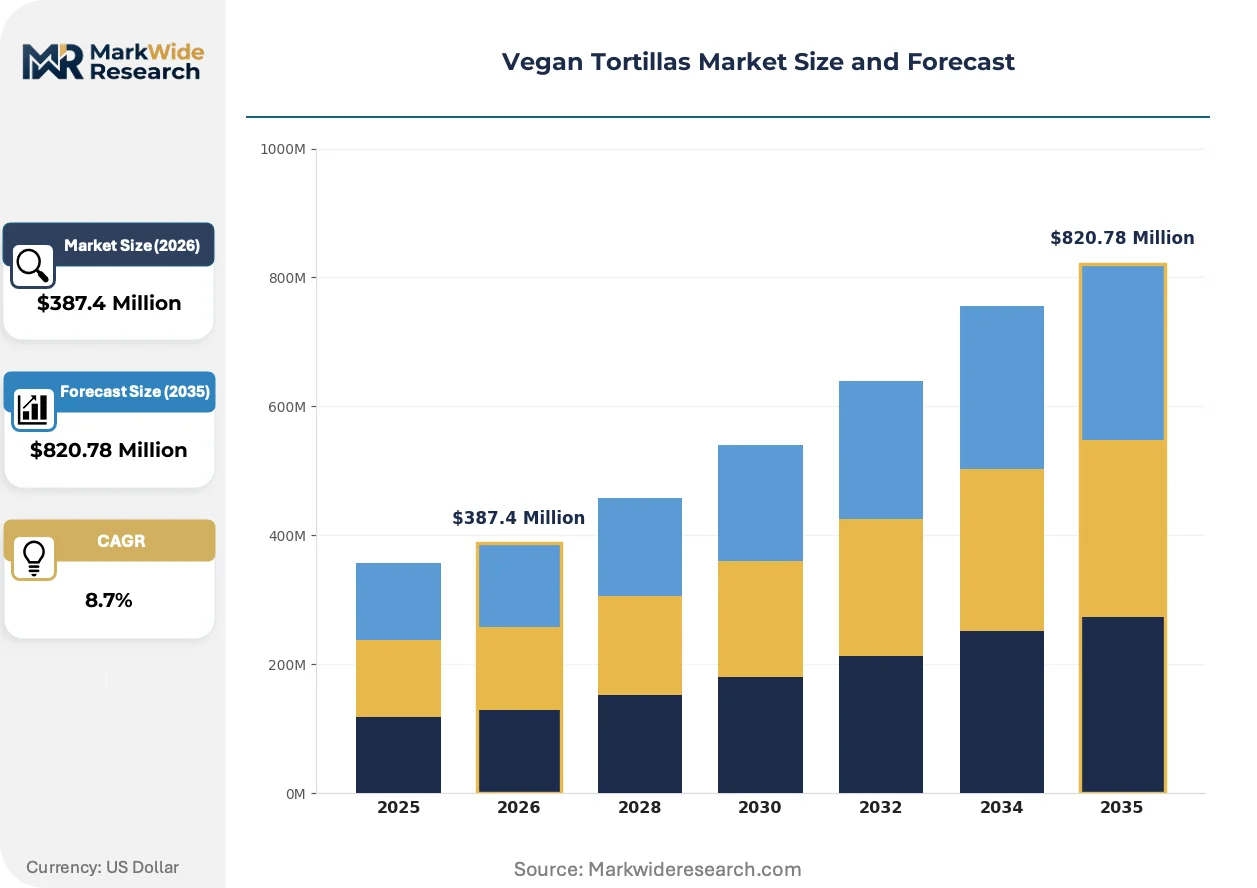
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $820.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour Tortillas, Corn Tortillas, Organic Tortillas, Gluten-Free Tortillas End User: Retail Consumers, Food Service, Food Manufacturers, Caterers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Plastic Wrap, Paper Bags, Biodegradable Packaging, Cartons |
| Companies Covered | GRUMA, Olé Mexican Foods, Old El Paso, Food for Life, Siete Foods, La Tortilla Factory, Rudi’s Bakery, BFree Foods, Mission Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Tortillas Market Evolving Landscape
Reformulation science is dissolving the boundary between commodity flatbreads and functional food categories, as ingredient technology and regulatory precision reshape what constitutes a tortilla.
High-pressure processing is decomposing the tradeoff between clean-label positioning and shelf stability. This non-thermal pasteurization method extends refrigerated windows without chemical preservatives. Food service distributors in Florida and Arizona are adopting HPP-treated lines for institutional accounts. The technology is decomposing conventional frozen-tortilla economics by enabling fresh-like texture at ambient distribution costs.
EU Green Deal farm-to-fork targets are tightening mycotoxin thresholds for imported corn masa. European importers now require third-party aflatoxin testing that US suppliers lacked infrastructure to provide. Mexican export-oriented mills are responding by vertically integrating into controlled-environment grain drying, shifting procurement away from open-air campo suppliers.
Subscription-based replenishment is capturing pantry-share from conventional grocery restocking. Direct-to-consumer platforms aggregate celiac, vegan, and low-FODMAP households into predictable demand pools. This pattern concentrates most visibly in coastal US metropolitan corridors where meal-kit penetration already trained consumers to scheduled ingredient delivery.
Vegan Tortillas Market Segmentation
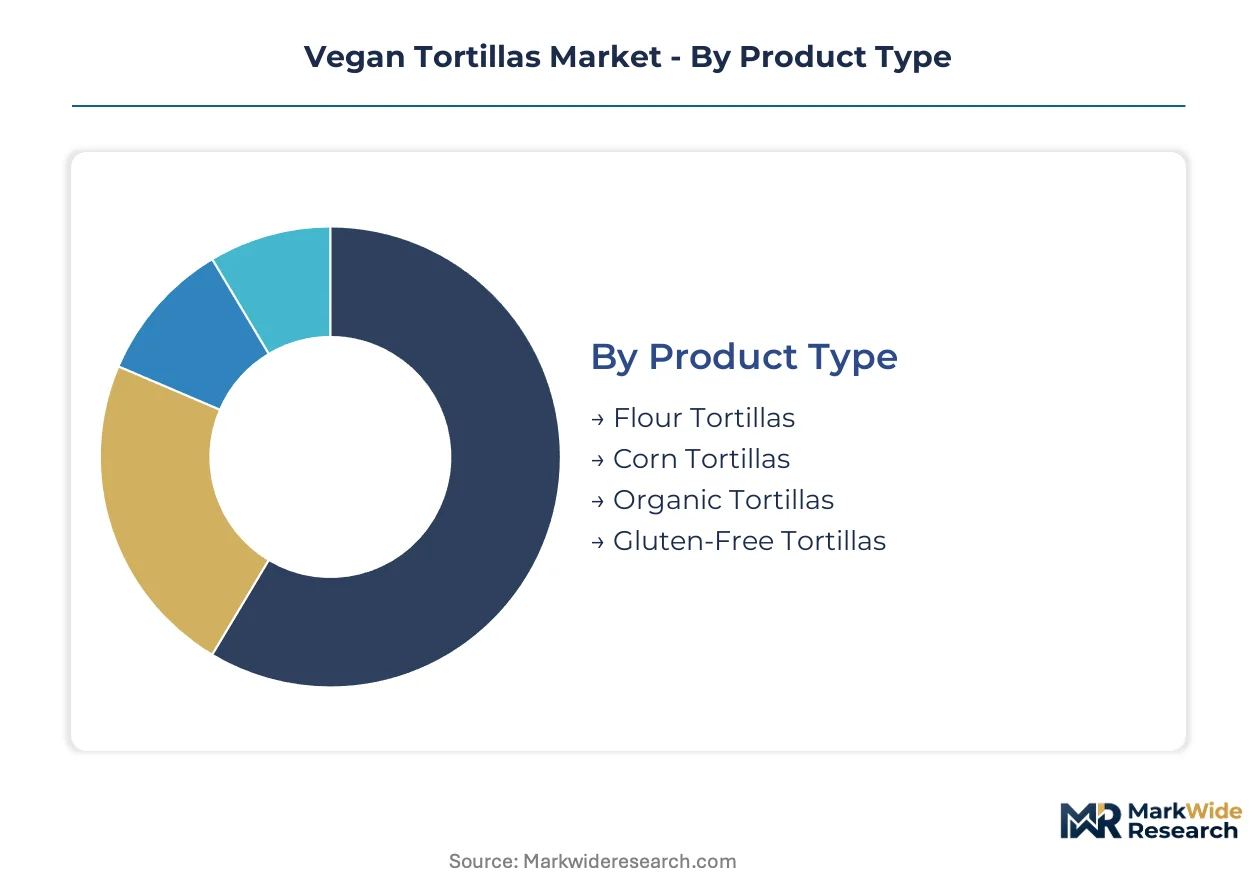
Segmentation in vegan tortillas reveals how certification requirements and distribution infrastructure reshape competitive access. Each dimension carries distinct regulatory burdens and margin structures that determine which producers can operate profitably at scale.
Product Type:
FDA gluten-free labeling thresholds and USDA Organic enforcement create divergent compliance costs across substrate categories, fragmenting supplier qualification tiers.
- Corn Tortillas:Nixtamalized masa formulations rely on lime-cooked corn flour with heritage authenticity driving food service procurement. Demand concentrates in Texas and California Mexican-inspired restaurant chains where labor cost pressures favor simple heating-and-serve workflows over scratch preparation.
- Gluten-Free Tortillas:Cassava, coconut, and rice flour bases require dedicated production lines to prevent cross-contamination under FDA allergen protocols. Celiac and low-FODMAP diet adherents in coastal US metropolitan corridors sustain premium pricing that offsets ingredient cost premiums.
- Flour Tortillas:Wheat-based formulations with vegetable oil shortening dominate volume retail through lower per-unit production costs.
- Organic Tortillas:Certified corn or wheat substrates face input volatility from Sinaloa and Jalisco drought cycles that compress margins.
Established volume favors corn tortillas; emerging adoption favors gluten-free tortillas.
End User:
Procurement scale and specification precision separate customer tiers, with institutional buyers imposing traceability requirements that filter supplier pools.
- Food Service:Multi-unit restaurant operators mandate bulk delivery schedules, refrigerated shelf-life guarantees, and lot-level traceability for menu allergen management. California and Texas plant-based menu expansion drives contract consolidation toward vertically integrated mills.
- Retail Consumers:Pantry stock-up patterns favor ambient-stable formats with extended dating, though subscription direct-to-pantry models are capturing recurring revenue from dietary-restricted households.
- Food Manufacturers:Frozen burrito and enchilada assemblers require consistent diameter and moisture specifications for automated wrapping equipment.
- Caterers:Event-based demand fluctuates seasonally, with preference for fresh-refrigerated formats over frozen alternatives.
Contract concentration favors food service; margin expansion favors retail consumers.
Distribution Channel:
Cold-chain availability and slotting fee structures determine which product formats reach which buyer segments.
- Supermarkets:Conventional grocery chains command placement fees that disadvantage emerging brands, though perimeter refrigerated cases offer visibility for fresh-positioned lines.
- Online Retail:Direct-to-consumer platforms bypass slotting economics, aggregating celiac, vegan, and low-FODMAP households into predictable demand pools with subscription replenishment.
- Specialty Stores:Natural and organic retailers prioritize USDA Organic and Non-GMO Project verification, creating premium positioning opportunities.
- Wholesale:Broadline distributors service institutional accounts with pallet-scale procurement and delivery logistics.
Absolute volume flows through supermarkets; steepest expansion trajectory belongs to online retail.
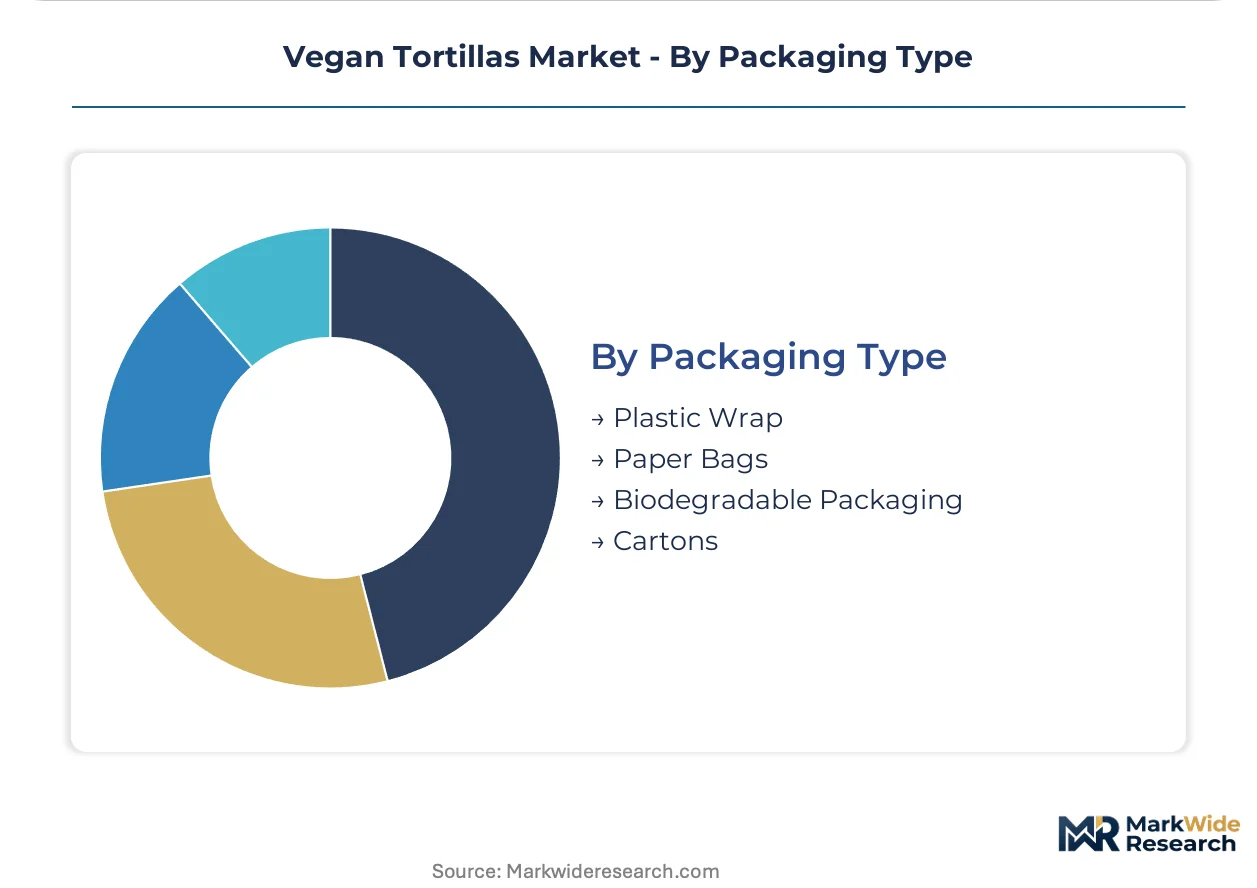
Packaging Type:
Shelf-life engineering and waste regulation compliance differentiate material choices across retail and food service applications.
- Plastic Wrap:Modified atmosphere barrier films dominate ambient retail, extending shelf stability without synthetic preservatives.
- Biodegradable Packaging:Compostable substrates align with EU Green Deal farm-to-fork targets and California waste reduction mandates, though moisture barrier performance lags conventional films.
- Paper Bags:Breathable formats suit short-dated fresh tortillas in bakery-style retail.
- Cartons:Rigid protection for premium positioned multi-packs in club and specialty channels.
Functional performance favors plastic wrap; regulatory alignment favors biodegradable packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA gluten-free labeling mandates and USDA Organic certification requirements are reshaping supplier qualification protocols across major demand centers. Mexico's nixtamalization heritage and the United States' plant-based menu expansion create divergent competitive dynamics. German and French retail channels impose EU Green Deal farm-to-fork compliance that filters import eligibility.
United States
California and Texas food service operators drive bulk procurement contracts as plant-based menu mandates expand across multi-unit restaurant chains. FDA facility sanitation standards determine which co-manufacturers qualify for dedicated vegan production lines, forcing ingredient traceability upgrades. Los Angeles and Austin metropolitan corridors concentrate subscription-based direct-to-pantry demand from celiac and low-FODMAP households.
Mexico
Sinaloa and Jalisco growing regions anchor organic corn supply for heritage-authentic masa formulations, though drought cycles create input price volatility. The country's national food safety regulator enforces mycotoxin thresholds that determine export eligibility to European markets. Mexico City Metro and Guadalajara industrial zones concentrate nixtamalization expertise among aging mill operators with traditional lime-cooking knowledge.
Germany
REACH compliance alignment unlocks premium retail placement for exporters adapting preservative formulations to ECHA chemical safety standards. EU Green Deal farm-to-fork targets tighten residue thresholds that reshape import sourcing from open-air campo suppliers. Berlin and Hamburg distribution hubs service expanding vegan wrap SKU penetration across food service accounts.
France
Supermarket perimeter refrigerated cases offer visibility for fresh-positioned lines as conventional grocery slotting fees disadvantage emerging brands. ANSM nutrition labeling requirements create compliance burdens for protein-fortified formulations approaching functional food thresholds. Paris and Lyon metropolitan areas concentrate demand for ambient-stable formats with extended dating in pantry stock-up patterns.
Canada
Health Canada allergen protocols shape co-manufacturer qualification for dedicated gluten-free production lines preventing cross-contamination. Provincial organic certification programs create fragmented compliance landscapes for emerging brands entering regional retail across Ontario and Quebec. Toronto and Vancouver coastal corridors concentrate online retail expansion as direct-to-consumer platforms bypass conventional grocery economics.
Vegan Tortillas Market Competitive Landscape
Player mix skews toward vertically integrated corn flour networks and grain-free formulation specialists. The vendor base separates into three qualification tiers: USDA Organic certified mills with traceable supply chains, refrigerated distribution scale operators serving food service accounts, and direct-to-consumer platforms aggregating dietary-restricted households. Strategic moves concentrate on backward integration into controlled-environment grain drying and cross-laminated barrier film packaging convergence.
Within the heritage-scale tier, GRUMA and Mission Foods represent vertically integrated archetypes with nixtamalization network coverage. Siete Foods exemplifies the grain-free specialist position built on cassava and coconut flour substrate innovation. These three anchors occupy positions that map to the certification-distribution-channel matrix: organic compliance, refrigerated logistics scale, and allergen-segmented formulation expertise respectively.
| Leading Market Players |
|---|
| GRUMA |
| Olé Mexican Foods |
| Old El Paso |
| Food for Life |
| Siete Foods |
| La Tortilla Factory |
| Rudi's Bakery |
| BFree Foods |
| Mission Foods |
| Others |
Value Network & Pricing Analysis
Cassava flour substitution for nixtamalized corn is redrawing procurement geography toward Southeast Asian starch processors while compressing heritage-authentic masa premiums. This input shift simultaneously loosens Mexico's grip on substrate supply and erodes the price umbrella that organic corn certifications once sustained.
Pricing Analysis
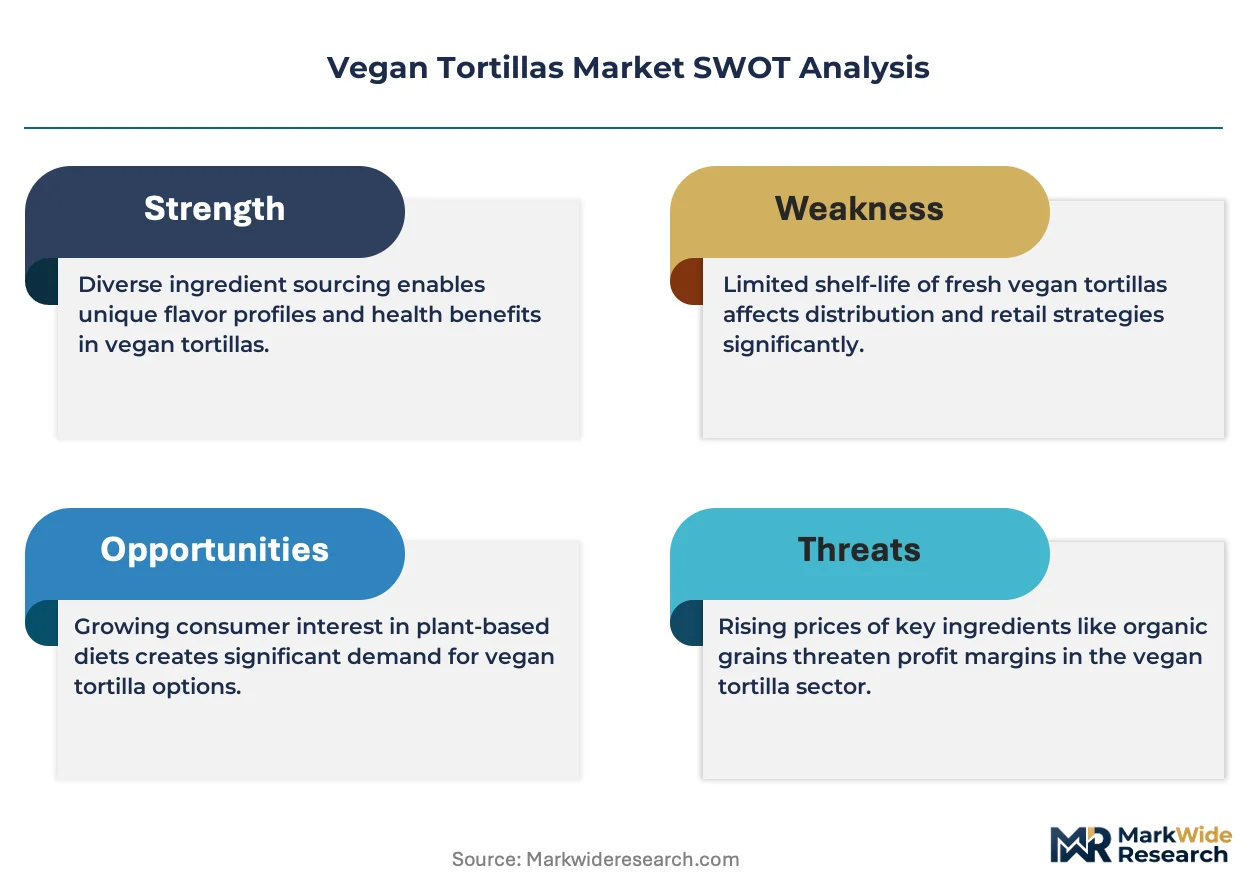
Certification level creates the primary spread, with USDA Organic and Non-GMO Project verification commanding 35-50% premiums over conventional lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by shelf-life format and traceability depth. Cost compression in refrigerated fresh segments is intensifying because cold-chain logistics operators are consolidating routes. Food service buyers exhibit lowest price sensitivity due to menu cost pass-through mechanics, while subscription direct-to-consumer households prioritize per-unit value over absolute spend.
Supply Chain Analysis
Inventory lead times for organic corn masa stretch 8-12 weeks during Sinaloa drought cycles, forcing buyers into forward-contracting positions. Raw material sourcing concentrates in Mexico, the United States, and Brazil, with nixtamalized flour drawing from heritage mill networks in Jalisco and Guanajuato. Single-source vulnerability sits with third-party refrigerated distribution networks concentrated in Texas and California. Distribution runs through broadline food service distributors for institutional accounts and direct-to-pantry platforms for dietary-restricted households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing adoption represents a technological inflection that collapses the clean-label-versus-shelf-stability tradeoff, enabling fresh-positioned products at ambient distribution economics.
For Market Incumbents: Secure nixtamalization expertise through apprenticeship programs and equipment modernization grants before aging mill operator retirements accelerate. Capture captive supply of controlled-environment grain drying infrastructure to buffer organic corn input volatility from Jalisco drought cycles. For New Entrants and Emerging Players: Subscription replenishment service gaps in the Midwest and Southeast coastal corridors offer white-space penetration where incumbents under-serve celiac and low-FODMAP households. Target online retail channel aggregation with direct-to-pantry subscription models that bypass conventional grocery slotting fees. For Investors and Strategic Acquirers: The market sits at a certification-consolidation phase that favors vertically integrated mills with USDA Organic and gluten-free protocol mastery. Long-term viability hinges on backward integration into grain drying and cross-laminated barrier film packaging. Watch FDA protein fortification threshold clarification as the signal for functional food category reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | HPP-treated lines decompose frozen-tortilla economics by enabling fresh-like texture at ambient costs. |
| Backward Integration into Grain Drying | Controlled-environment drying infrastructure buffers Sinaloa drought volatility for organic corn supply. |
| Direct-to-Pantry Subscription Launch | Bypasses conventional grocery slotting fees while aggregating celiac and low-FODMAP demand pools. |
| Cross-Laminated Barrier Film Convergence | Modified atmosphere packaging with compostable substrates extends ambient shelf life for convenience store distribution. |
| Multi-Certification Protocol Investment | Simultaneous USDA Organic and gluten-free validation unlocks premium tier access despite 18-24 month timelines. |
Research Methodology
Cross-validation between primary interviews with food service procurement directors, co-manufacturer operations managers, and retail category buyers anchors the qualitative findings. Secondary validation draws from FDA facility inspection databases, USDA organic certification registries, and customs import records for corn masa and cassava flour. Bottom-up demand modeling triangulates against top-down value chain estimates across product type, end user, and distribution channel dimensions.
Sensitivity analysis around organic corn price volatility and refrigerated logistics capacity constraints shapes the analytical framework. Segmentation dimensions span substrate category, shelf-life format, certification tier, and regional regulatory cluster. CAGR derivation incorporates historical volume trajectories, menu expansion rates at multi-unit restaurant chains, and subscription platform growth curves.
Material uncertainties — FDA protein fortification threshold rulings, EU Green Deal mycotoxin enforcement tightening, and Jalisco drought recurrence patterns — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification adoption curves and cold-chain infrastructure expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Margarine Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Global Textured Vegetable Protein Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Global Vegan Fast Foods Market