
 Vegan Food Market | 2026-2036
Vegan Food Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Food Market Analysis
Precision fermentation for dairy-identical proteins is tilting the ingredient technology stack away from conventional extrusion and toward microbial biomass systems. Beyond Meat sustains heavy capital deployment in fermentation infrastructure despite near-term margin compression. Danone S.A. anchors its European position through captive oat and soy processing networks that insulate input costs.
Vegan food comprises plant-derived or cell-cultured products formulated to replicate the sensory, nutritional, and functional properties of animal-based foods, typically achieving protein equivalence through extruded pea or fava bean isolates with lipid fractions from sunflower or algae oils. Dairy alternatives occupy the deepest margin pools due to premium pricing on barista-grade oat and fermented yogurt formats, while meat alternatives compete on manufacturing scale and refrigerated distribution density. Meal kits represent the fastest-growing application channel as subscription platforms bundle recipe-specific vegan portions with controlled portion economics.
The FDA governs labeling thresholds for plant-based milk claims in the United States, while EFSA evaluates novel protein safety dossiers that determine European market access timelines for fermentation-derived ingredients. REACH compliance shapes ingredient substitution patterns as formulators phase out certain emulsifiers and texture modifiers. Stakeholders must monitor how carbon border adjustments and evolving protein nomenclature standards reshape competitive access across North American and European retail gatekeepers.
Market Dynamics
Precision fermentation infrastructure is rewriting capital allocation patterns across the vegan food value chain, pulling investment away from extrusion-based protein processing toward microbial biomass systems that promise dairy-identical functional properties.
Growth Catalysts
- EU Green Deal carbon-labeling mandates:The Farm to Fork Strategy tightens disclosure requirements for food service procurement, forcing institutional buyers toward verified low-impact ingredient sourcing.
- Quick-service chain volume commitments:Major fast-food operators now anchor plant-based protein procurement through multi-year supply agreements that de-risk manufacturing scale-up.
- German retail shelf expansion:Refrigerated meat alternative facings in German supermarkets have outpaced neighboring markets, creating density that justifies dedicated cold-chain distribution investments.
Market Restraints
- Pea protein isolate cost volatility:Concentrated sourcing from Canadian and Chinese fractionation facilities exposes margins to crop yield fluctuations and freight rate spikes.
- EFSA novel protein safety dossiers:European market access for fermentation-derived ingredients faces extended evaluation timelines that delay revenue recognition for biotech-enabled entrants.
- Sunflower oil supply concentration:Black Sea region processing dominance creates input risk that reformulators cannot easily hedge through alternative lipid sourcing.
Strategic Opportunities
- Subscription meal kit penetration:Recipe-specific vegan portion bundling offers controlled unit economics that bypass retail slotting fee barriers.
- Barista-grade oat milk premiumization:Coffee shop channel partnerships unlock pricing power unavailable in commoditized retail milk alternative aisles.
- REACH-compliant emulsifier substitution:Phased texture modifier restrictions create formulation service opportunities for clean-label ingredient suppliers.
Industry Challenges
- Fermentation bioprocess engineering talent scarcity:Microbial strain optimization and bioreactor scale-up expertise concentrates in pharmaceutical and biofuel sectors, requiring cross-industry recruitment.
- Carbon border adjustment compliance complexity:Evolving scope 3 measurement standards demand supply chain traceability investments that mid-tier formulators struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Food Market |
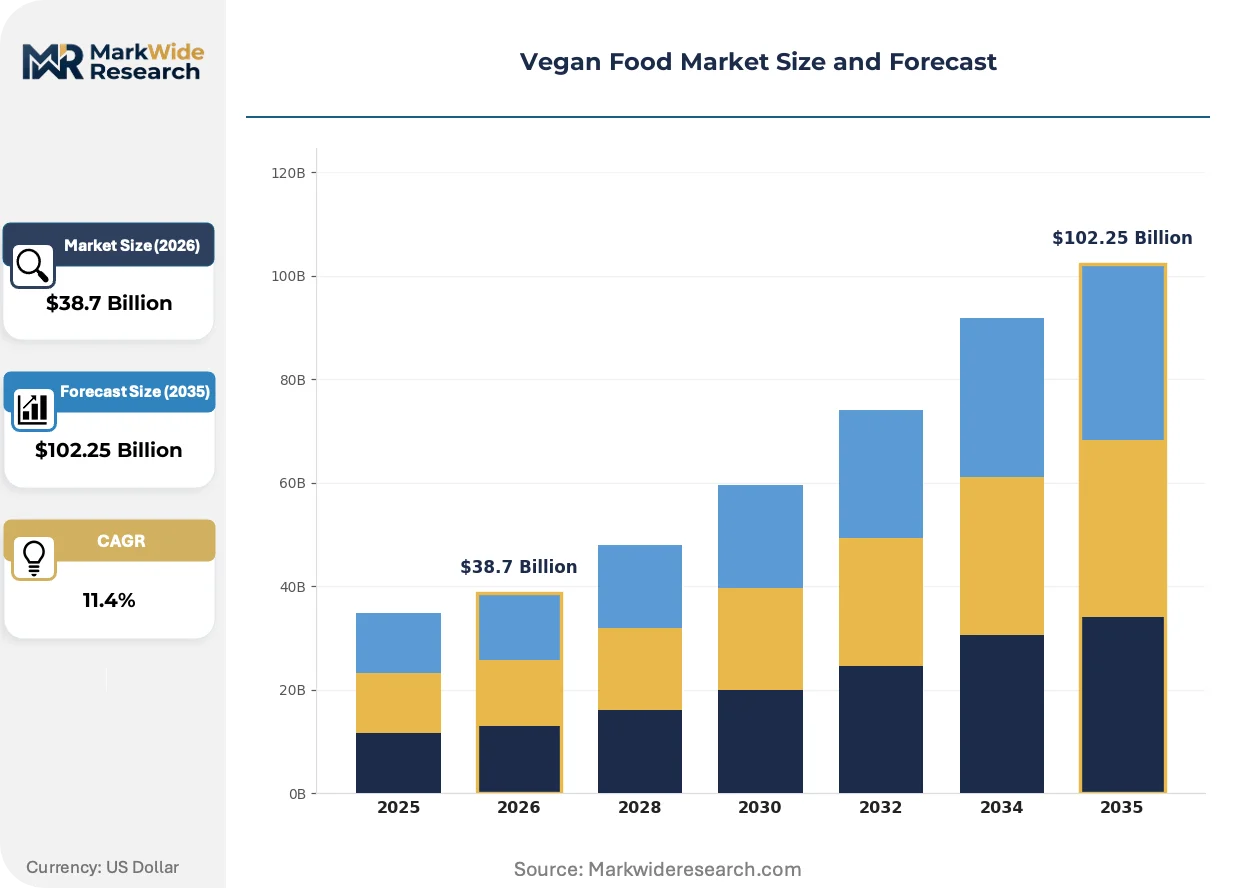
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Alternatives, Snacks, Desserts Application: Retail, Food Service, Online Sales, Meal Kits Ingredient Type: Legumes, Nuts, Grains, Vegetables Consumer Type: Health Conscious, Environmentally Conscious, Ethical Consumers, Others |
| Companies Covered | Beyond Meat, Quorn, Danone S.A., Amy's Kitchen, Inc., Eat Just, Conagra, Inc., Oatly, No Evil Foods, Hain Celestial Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Food Market Emerging Trajectories
Biotechnology-enabled ingredient platforms are compressing the functional gap between plant-derived and animal-derived proteins, while regulatory frameworks on both sides of the Atlantic rewrite the rules of market access and label claims.
Precision fermentation for whey-identical proteins is rendering obsolete conventional extrusion methods for achieving dairy-mimetic melt and stretch properties. Pizza and prepared foods manufacturers are accelerating adoption of these microbial-derived casein replacements. The shift is compressing R&D timelines for cheese alternative formulators while raising capital barriers for extrusion-dependent competitors.
EFSA's evolving novel food safety dossier requirements are extending European market access timelines for biomass-derived ingredients. Fermentation startups now face 18-24 month evaluation periods that delay commercial launch. Dairy alternative specialists with existing oat and soy processing networks are exploiting this friction to defend shelf position.
Food service operators are consolidating procurement through direct supplier partnerships that bypass traditional distribution intermediaries. Contract food management companies now negotiate plant-based protein supply agreements directly with ingredient technology firms. This disintermediation is most visible in German and Dutch institutional catering markets where volume concentration justifies dedicated logistics arrangements.
Vegan Food Market Segmentation
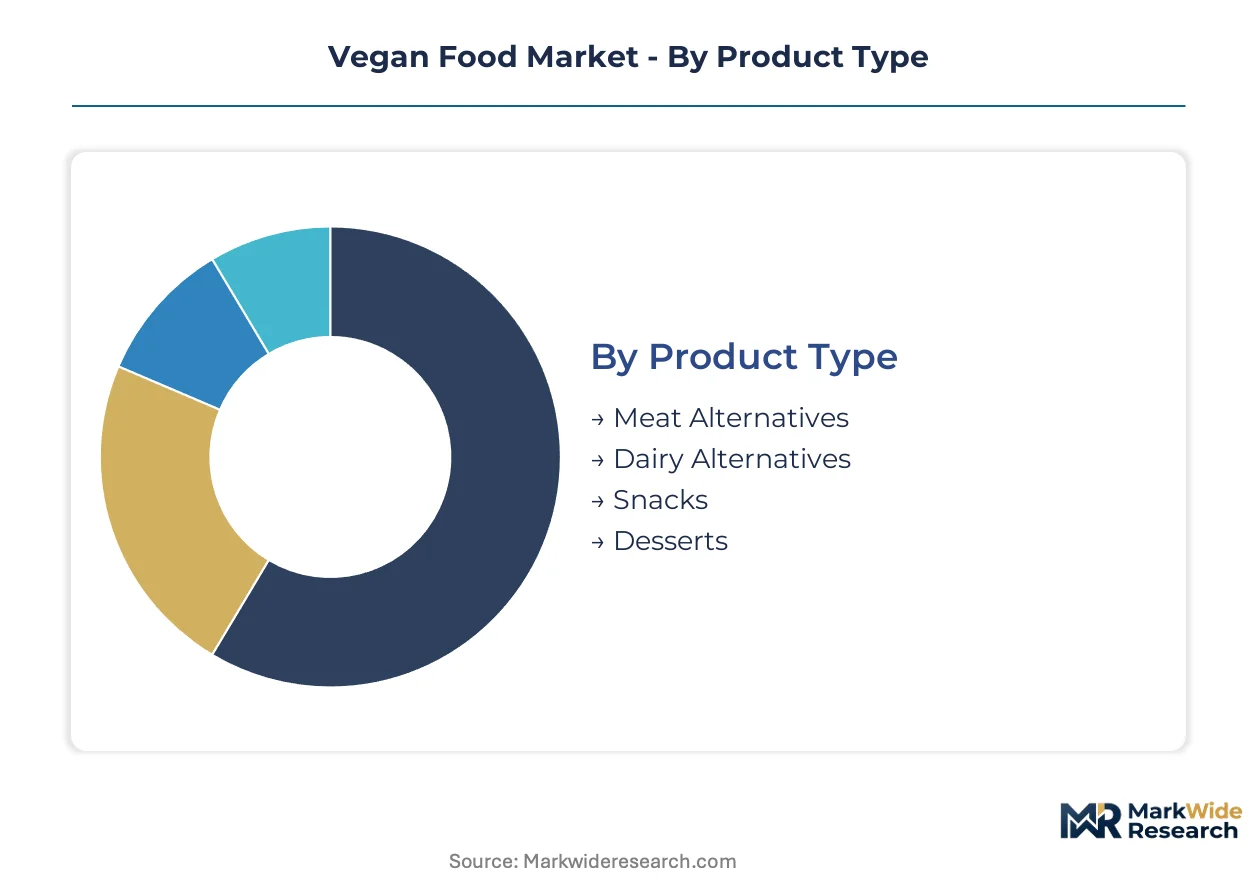
Segmentation in the vegan food market exposes divergent margin structures across product formats and procurement channels. Precision fermentation capabilities concentrate in dairy alternatives while extrusion scale dominates meat alternatives. Understanding these segment boundaries clarifies where capital deployment yields differentiated returns versus commoditized competition.
Product Type:
Cost tier separation defines competitive positioning across vegan food formats, with premium extraction technologies commanding pricing power unavailable to commodity processors.
- Meat Alternatives:Extruded pea and fava bean isolates form the protein base, with lipid fractions from sunflower or algae oils delivering juiciness and mouthfeel. German retail chains anchor volume procurement through dedicated refrigerated shelf space that justifies cold-chain infrastructure investment. EFSA novel protein dossiers delay fermentation-derived entrants, protecting incumbent extrusion-dependent suppliers.
- Dairy Alternatives:Oat and soy processing networks deliver barista-grade foaming properties and fermented yogurt textures that sustain premium pricing. Danone S.A.'s captive European processing insulates input costs while precision fermentation startups face 18-24 month regulatory timelines. Coffee shop channel partnerships unlock pricing unavailable in commoditized retail aisles.
- Snacks:Extruded puffs and protein bars leverage commodity pulse flours with clean-label seasoning profiles.
- Desserts:Coconut cream and cashew bases dominate frozen and refrigerated formats with limited functional differentiation.
Meat alternatives command the established base. The steepest expansion runs through dairy alternatives.
Application:
Procurement channel selection determines margin capture, with direct supplier partnerships displacing traditional distribution intermediaries in volume-concentrated segments.
- Retail:Slotting fees and shelf-facing negotiations dominate go-to-market economics, with German supermarkets expanding refrigerated meat alternative facings faster than neighboring markets. Retail gatekeepers demand carbon-labeling compliance that strains mid-tier formulator capabilities.
- Food Service:Quick-service chains anchor procurement through multi-year supply agreements that de-risk manufacturing scale-up. Contract food management companies in Dutch institutional catering markets negotiate directly with ingredient technology firms, bypassing distributors entirely.
- Online Sales:Direct-to-consumer platforms face last-mile cold-chain cost pressures that compress unit economics.
- Meal Kits:Recipe-specific portion bundling offers controlled economics that bypass retail slotting barriers.
Food service commands the established base. The steepest expansion runs through meal kits.
Ingredient Type:
Supply concentration geography shapes input cost volatility, with Black Sea sunflower oil dominance and Canadian pea protein fractionation creating unhedgeable exposure.
- Legumes:Pea protein isolate sourcing concentrates in Canadian and Chinese fractionation facilities, exposing margins to crop yield fluctuations and freight rate spikes. Fava bean protein gains traction as a regional alternative with lower allergenicity profiles.
- Nuts:Cashew and almond bases carry water-scarcity sourcing risks that carbon border adjustments increasingly price into European procurement decisions.
- Grains:Oat processing networks in Nordic countries deliver the beta-glucan viscosity profiles essential for barista-grade foaming.
- Vegetables:Mushroom-derived umami concentrates and jackfruit fibrous textures fill niche whole-food positioning segments with limited scale potential.
Legumes command the established base. The steepest expansion runs through grains.
Consumer Type:
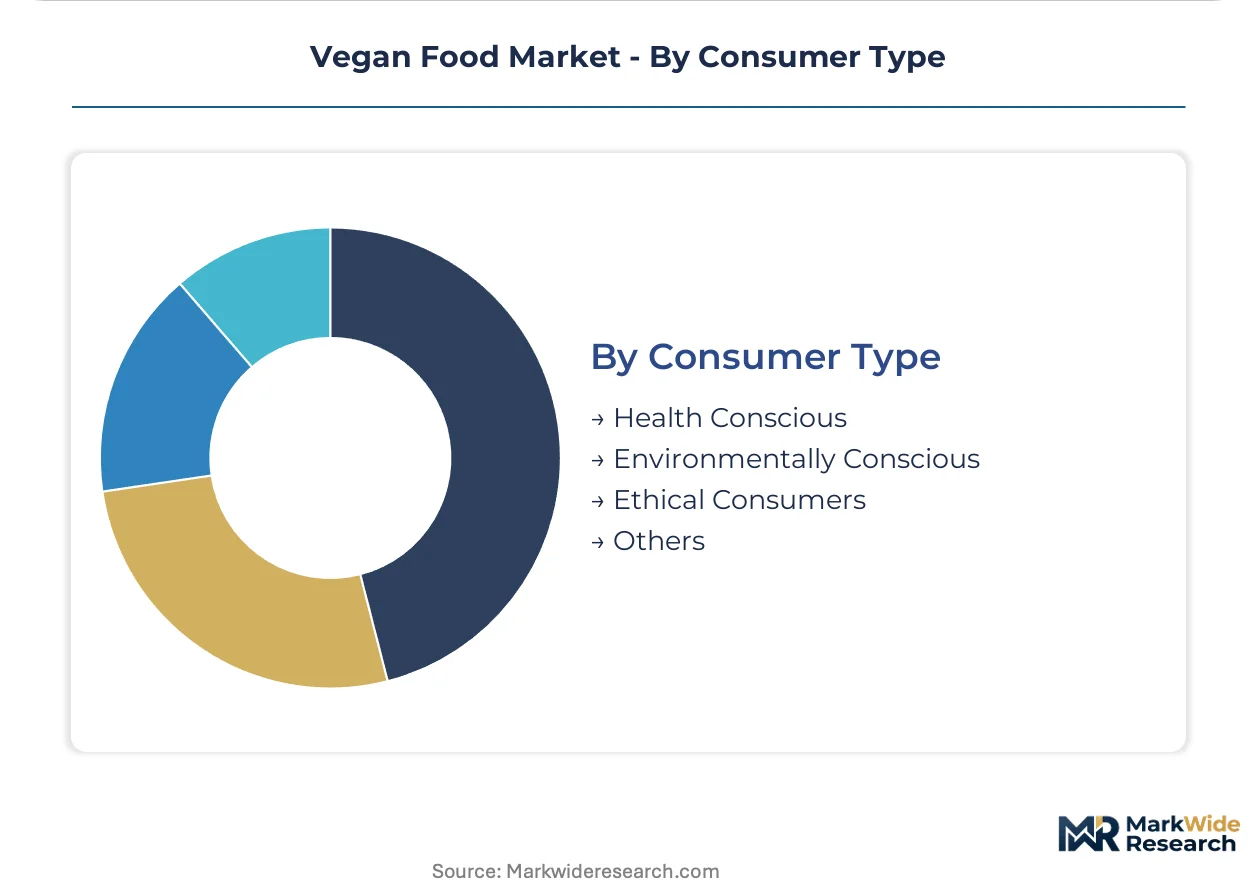
Purchase motivation segmentation reveals divergent willingness-to-pay for certification attributes, with health positioning commanding premiums unavailable to ethical framing alone.
- Health Conscious:Protein equivalence claims and clean-label ingredient lists drive purchase decisions, with fortified formats sustaining pricing power. FDA labeling thresholds for plant-based milk claims shape permissible positioning in the United States.
- Environmentally Conscious:Carbon footprint verification and EU Green Deal compliance documentation increasingly gate retail access, particularly for institutional procurement in Germany and the Netherlands.
- Ethical Consumers:Animal welfare certification carries limited pricing power in mass-market channels but sustains niche premium positioning.
- Others:Flexitarian trialists and allergen-avoidance shoppers drive occasional purchase with low loyalty and high price sensitivity.
Health conscious consumers command the established base. The steepest expansion runs through environmentally conscious segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian pea protein fractionators supply European formulators facing EU Green Deal carbon-labeling mandates. German retail chains anchor import demand through expanded refrigerated shelf commitments.
United States
Quick-service chains drive procurement volume through multi-year plant-based protein supply agreements. FDA labeling thresholds for plant-based milk claims shape permissible positioning in retail channels. California's precision fermentation clusters attract venture capital despite extended commercialization timelines.
Germany
Refrigerated meat alternative facings in supermarkets outpace neighboring markets, justifying dedicated cold-chain distribution investments. EU Green Deal Farm to Fork Strategy tightens carbon-labeling requirements for institutional procurement. Berlin's contract food management companies negotiate direct supplier partnerships that bypass traditional distributors.
Netherlands
Institutional catering markets concentrate volume sufficient for dedicated logistics arrangements with ingredient technology firms. EFSA novel protein safety dossiers extend evaluation timelines for fermentation-derived entrants. Wageningen's food technology research corridor anchors reformulation expertise for clean-label emulsifier substitution.
United Kingdom
Subscription meal kit platforms bundle recipe-specific vegan portions with controlled unit economics. REACH compliance shapes ingredient substitution patterns as formulators phase out restricted texture modifiers. London's coffee shop density sustains barista-grade oat milk premiumization unavailable in commoditized retail aisles.
China
Domestic oat processing capacity expands to meet coffee chain demand for foaming-grade formulations. SAMR oversight of novel food ingredients creates parallel regulatory pathways distinct from Western frameworks. Shanghai's food service procurement consolidation mirrors European direct-supplier partnership models.
Vegan Food Market Vendor Landscape
On the supply side, the industry is bifurcating between extrusion-dependent commodity processors and biotechnology-enabled precision fermentation specialists. Capital deployment patterns favor microbial biomass systems promising dairy-identical functional properties. Two strategic archetypes dominate: captive processing network operators and fermentation infrastructure builders. Competitive moves concentrate on strategic partnerships with food service operators and capacity expansion in barista-grade oat processing.
Within the biotechnology-enabled tier, Beyond Meat exemplifies fermentation infrastructure commitment despite near-term margin compression. Danone S.A. occupies a position as a captive network operator through European oat and soy processing assets. Oatly anchors the oat milk specialization vector with coffee channel partnerships that unlock pricing power.
| Leading Market Players |
|---|
| Beyond Meat |
| Quorn |
| Danone S.A. |
| Amy's Kitchen, Inc. |
| Eat Just |
| Conagra, Inc. |
| Oatly |
| No Evil Foods |
| Hain Celestial Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Canadian pea protein fractionation facilities anchor upstream concentration, directing margin pools toward European formulators with EU Green Deal-compliant carbon labeling and German retail chains with dedicated refrigerated shelf commitments.
Pricing Analysis
Extrusion-dependent commodity processors compete on per-unit transactional pricing while precision fermentation specialists command premium contract-based long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates barista-grade oat formulations from refrigerated meat alternatives and commodity snack formats. Cost compression in standard-tier extruded proteins is intensifying because Black Sea sunflower oil volatility and Canadian pea isolate freight spikes squeeze mid-tier formulators. Food service procurement teams show lowest price sensitivity due to multi-year volume commitments, while flexitarian retail trialists exhibit highest sensitivity with minimal brand loyalty.
Supply Chain Analysis
Contract manufacturing concentration rests with European oat processing specialists, North American extrusion-scale meat alternative producers, and emerging precision fermentation bioreactor operators. Raw material sourcing draws from Canadian pea protein fractionators, Chinese fava bean processors, and Nordic oat millers. Single-source vulnerability concentrates in Black Sea sunflower oil refining and EFSA novel protein dossier bottlenecks that delay fermentation-derived ingredient market access. Distribution runs through direct supplier partnerships with institutional catering operators in Germany and the Netherlands, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation infrastructure deployment represents a high-growth disruption justified by EU Green Deal carbon-labeling mandates that rewrite procurement specifications across European food service channels.
For Market Incumbents: Entrench position through captive oat and soy processing network expansion in Nordic countries, insulating input costs against commodity volatility. Accelerate barista-grade formulation R&D to defend margin pools against precision fermentation entrants facing 18-24 month EFSA evaluation timelines. Prioritize direct partnership negotiations with German contract food management companies to lock in volume commitments before fermentation-derived alternatives achieve commercial scale.
For New Entrants and Emerging Players: Pursue subscription meal kit channel penetration where controlled portion economics bypass retail slotting fee barriers. Target Dutch institutional catering markets with dedicated logistics arrangements that mirror established European direct-supplier partnership models. Lead with REACH-compliant clean-label emulsifier substitution services to capture reformulation demand from mid-tier processors phasing out restricted texture modifiers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation infrastructure builders facing extended commercialization timelines and near-term margin compression. Long-term viability over a multi-year horizon hinges on successful EFSA novel protein safety dossier navigation and food service procurement consolidation trends. Monitor German retail shelf expansion rates and quick-service chain plant-based protein commitment announcements as inflection indicators for manufacturing scale-up timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Infrastructure Buildout | Precision fermentation bioreactor capacity unlocks dairy-identical functional properties for cheese alternative formulators. |
| Direct Food Service Partnership | Bypassing distribution intermediaries with German institutional caterers secures multi-year volume commitments. |
| Clean-Label Emulsifier Substitution | REACH-compliant texture modifier reformulation captures mid-tier processor demand facing regulatory phase-outs. |
| Barista-Grade Oat Premiumization | Coffee shop channel partnerships unlock pricing power unavailable in commoditized retail milk alternative aisles. |
| Carbon-Labeling Compliance Investment | EU Green Deal Farm to Fork Strategy documentation gates access to institutional procurement in Germany and Netherlands. |
Methodological Framework
Operator-level perspectives from plant-based protein procurement managers at quick-service chains, category buyers at German retail chains, precision fermentation bioprocess engineers, and contract food management executives anchored the qualitative base. Secondary validation drew from EFSA novel food safety dossier filings, EU Green Deal regulatory documentation, SEC filings of publicly traded alternative protein companies, and Nielsen retail audit data for refrigerated meat alternative facings. Bottom-up volume modeling triangulated against top-down market sizing across ingredient technology tiers.
Scenario-bracketing framed the analytical approach across the analysis window, with base, upside, and downside cases reflecting differential precision fermentation commercialization timelines and EFSA regulatory clearance trajectories. Segmentation dimensions modeled included product type, application channel, ingredient source, and consumer motivation archetype. CAGRs derived from unit volume projections calibrated to food service procurement commitment announcements and retail shelf expansion data. Industry-specific inputs incorporated oat processing capacity utilization rates and pea protein isolate spot price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price cycles, freight rate trajectories, or carbon border adjustment implementation schedules would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA evaluation period durations and quick-service chain volume commitment conversion rates. Quarterly review of German refrigerated meat alternative shelf facings, EFSA novel protein dossier submission volumes, and precision fermentation venture capital deployment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Vegan Flavor Market