
 Enzyme-Based Plant Protein Market | 2026-2036
Enzyme-Based Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Enzyme-Based Plant Protein Market Analytics
Software-defined formulation services is consolidating around enzyme-substrate optimization platforms that let buyers customize protein functionality without owning bioreactor assets. Novozymes A/S dominates microbial enzyme supply for plant protein hydrolysis across Scandinavian and North American facilities. DSM sustains integrated positions from strain development through finished isolates, leveraging long-standing partnerships with European food manufacturers. Kerry Group competes through flavor-masking technologies that pair with its enzyme-treated protein portfolio, addressing persistent taste challenges in pea and fava applications.
Enzyme-based plant protein denotes protein fractions extracted from legumes, oilseeds, or cereals through controlled enzymatic hydrolysis, typically achieving degree of hydrolysis values between 5% and 20% to modulate solubility, emulsification, and digestibility for food and nutritional applications. The process employs proteases such as subtilisin or papain under pH- and temperature-controlled conditions to cleave peptide bonds without denaturing amino acid profiles, yielding ingredients with enhanced bioaccessibility for sports nutrition and clinical nutrition products. Isolates command margin concentration due to protein content exceeding 90% and premium positioning in dietary supplement brands, while hydrolysates represent the fastest-growing product type as manufacturers seek faster-absorbing protein for active nutrition and medical foods. Food and beverages anchors volume demand through meat analogs and dairy alternatives, though nutritional supplements is accelerating most sharply as enzyme-treated proteins displace conventional whey in clean-label positioning.
Regulators including the FDA, EFSA, and EMA shape market access through divergent protein content claim thresholds and novel food approval pathways for enzymatically modified ingredients. The FDA's Generally Recognized as Safe notification process and EFSA's novel food assessments create asymmetric timelines for ingredient commercialization, while EMA oversight of medical foods and clinical nutrition products opens premium segments for hydrolysate-grade materials. Stakeholders must monitor evolving amino acid scoring methodologies and digestibility certification standards, as these technical criteria increasingly determine procurement specifications and pricing power across end-use categories.
Market Dynamics
Precision fermentation platforms are compressing capital requirements for enzymatic hydrolysis, allowing mid-scale food manufacturers to bypass bioreactor ownership and source functionality-as-a-service from specialized enzyme houses.
Growth Catalysts
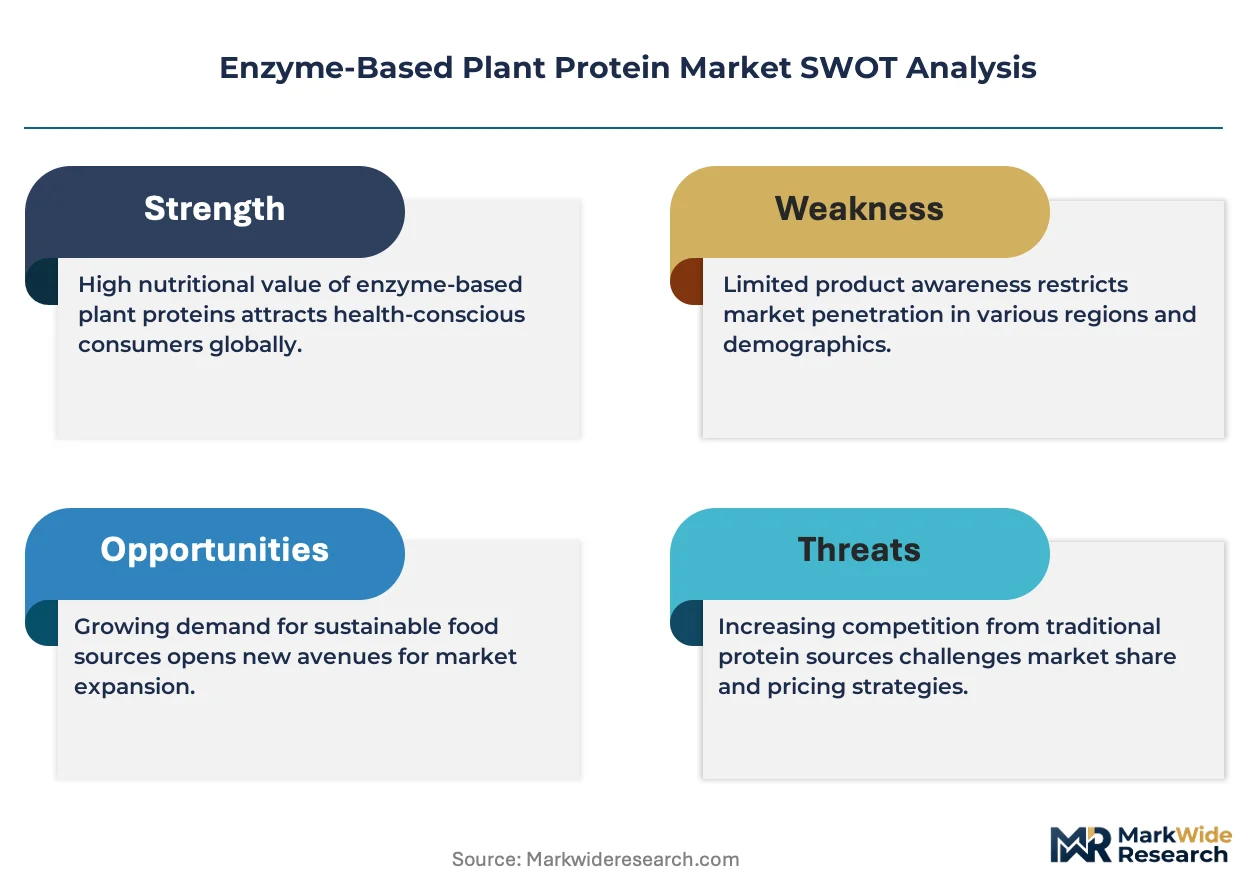
- Clean-label protein substitution:Sports nutrition brands in Germany and the Netherlands are displacing conventional whey with enzymatically treated pea and fava hydrolysates to meet EU Green Deal-aligned sustainability claims.
- Precision fermentation maturation:Advances in strain engineering are cutting protease production costs and expanding availability of substrate-specific enzymes for oilseed and cereal protein extraction.
- FDA labeling pathway clarity:The agency's updated Generally Recognized as Safe notification framework for enzymatically modified plant proteins is accelerating commercialization timelines for meat-alternative formulators.
Market Restraints
- Feedstock cost volatility:Pea and fava protein isolate prices fluctuate with Canadian and Australian pulse harvest cycles, compressing margins for hydrolysate producers locked into annual supply contracts.
- Enzyme supply concentration:Microbial protease production clusters in Danish and Dutch fermentation facilities, creating single-source vulnerability for North American hydrolysis operations.
- Digestibility certification friction:Divergent amino acid scoring methodologies between EFSA and FDA create reformulation costs for brands seeking dual-market approval.
Strategic Opportunities
- Medical nutrition white space:EMA's expanded medical food category definitions create premium positioning for hydrolysate-grade materials targeting clinical nutrition and post-surgical recovery segments.
- Industrial bakery integration:Enzyme-treated cereal proteins with controlled degree of hydrolysis are penetrating functional bread and pastry applications in France and Italy as egg replacement accelerates.
- Software-defined formulation convergence:Cloud-based enzyme-substrate optimization platforms paired with rapid prototyping services let brands customize solubility and emulsification profiles without captive bioprocessing assets.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise and enzymology PhD pipelines are concentrated in Copenhagen and Wageningen clusters, limiting facility expansion in secondary markets.
- Dual certification timeline compression:Parallel FDA GRAS and EFSA novel food submissions require dedicated regulatory affairs capacity that strains mid-cap ingredient houses.
- Flavor-masking integration complexity:Bitter peptide sequences in high-DH hydrolysates demand sophisticated taste modulation that outpaces current in-house sensory science capabilities at many plant protein specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enzyme-Based Plant Protein Market |
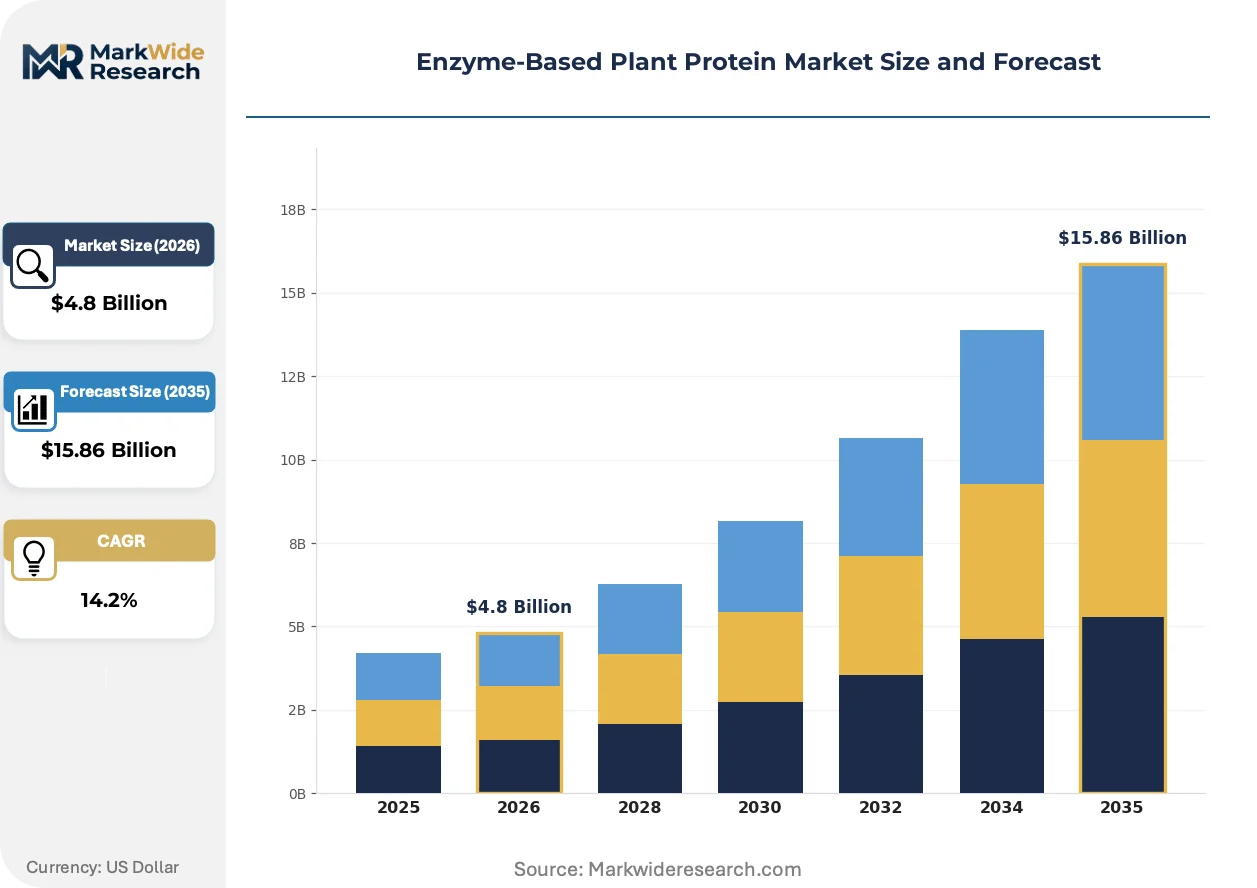
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Isolates, Textured Protein, Hydrolysates Application: Food & Beverages, Nutritional Supplements, Animal Feed, Pharmaceuticals Delivery Mode: Powder, Liquid, Granules, Tablets End User: Food Manufacturers, Dietary Supplement Brands, Animal Feed Producers, Health Food Stores |
| Companies Covered | Archer Daniels Midland Company, Cargill, Kerry Group, DuPont de Nemours, Novozymes A/S, DSM, Roquette Frères, Tate & Lyle, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzyme-Based Plant Protein Market Evolving Landscape
Enzymatic process control is shifting from batch optimization toward real-time substrate monitoring and adaptive hydrolysis, compressing development cycles for functional protein ingredients.
Immobilized enzyme reactor technology is modularizing plant protein hydrolysis by enabling continuous-flow processing with reduced enzyme consumption and tighter degree-of-hydrolysis control. Mid-scale meat-alternative manufacturers in Germany and the Netherlands are adopting these systems to avoid capital-intensive batch bioreactor investments. The technology is modularizing service-based supply arrangements where enzyme houses retain asset ownership and charge per-kilogram functionality fees.
EFSA's evolving novel food assessment criteria for enzymatically modified proteins are tightening toxicological data requirements for ingredients exceeding 20% degree of hydrolysis. The regulation is forcing reformulation strategies among hydrolysate suppliers targeting medical nutrition and infant food adjacent applications. Scandinavian and Dutch ingredient houses are responding by front-loading clinical digestibility studies to preempt regulatory delays.
Ingredient procurement is fragmenting as large food manufacturers diversify beyond single-source enzyme-treated protein supply toward multi-vendor functionality benchmarking. The shift is compressing supplier switching cycles from multi-year contracts to 18-month performance-based agreements with technical service bundles. This pattern is most visible in North American sports nutrition and active lifestyle brands where formulation agility outweighs volume pricing concessions.
Enzyme-Based Plant Protein Market Segmentation
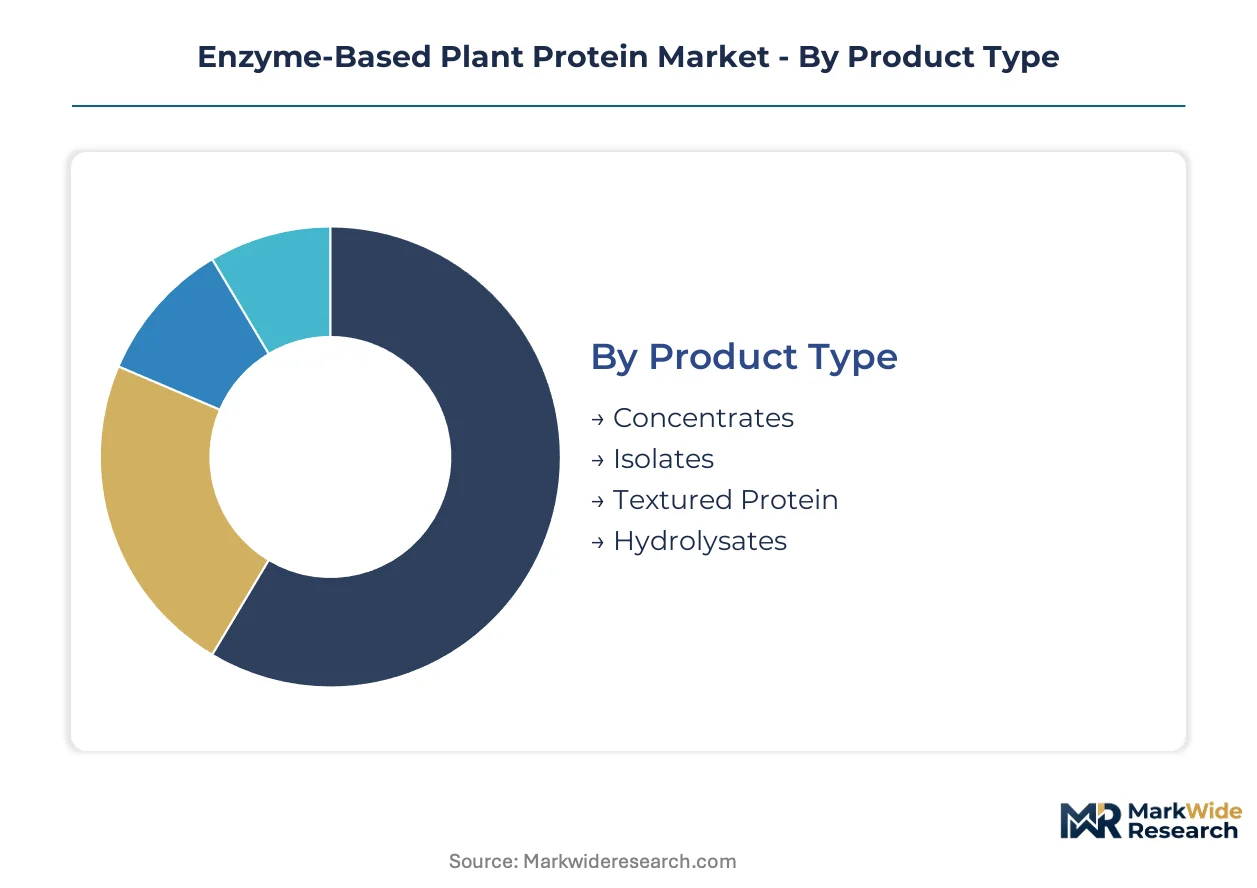
Segmentation in enzyme-based plant proteins tracks how hydrolysis depth, formulation format, and buyer sophistication stratify procurement patterns. Manufacturers configure enzymatic treatment intensity and delivery systems around end-use performance specifications rather than commodity protein sourcing.
Product Type:
Purchasing decisions pivot on protein purity thresholds versus solubility requirements, with margin structures widening as degree-of-hydrolysis precision increases.
- Isolates:Protein fractions exceeding 90% purity command premium positioning in dietary supplement brands and clinical nutrition products. German sports nutrition manufacturers specify isolates for clean-label positioning where amino acid completeness outweighs cost sensitivity.
- Hydrolysates:Partially cleaved peptides achieving 5-20% degree of hydrolysis deliver accelerated absorption kinetics for post-workout and medical food applications. Dutch and Scandinavian brands are displacing conventional whey with enzymatically treated pea and fava hydrolysates to meet EU Green Deal-aligned sustainability claims.
- Concentrates:Lower-purity fractions retain native protein structures with minimal enzymatic intervention, serving cost-sensitive meat-alternative formulators.
- Textured Protein:Extruded and enzyme-modified fractions replicate muscle fiber architecture for plant-based meat applications.
Isolates lead on scale; hydrolysates lead on momentum.
Application:
Volume concentration follows reformulation cycles in mature food categories, while value expansion tracks regulatory pathway openings in regulated nutrition segments.
- Food & Beverages:Industrial bakeries and meat-alternative manufacturers integrate enzyme-treated proteins for functional properties including emulsification, water binding, and Maillard reactivity. French and Italian industrial bakeries are adopting enzyme-treated cereal proteins with controlled degree of hydrolysis as egg replacement accelerates.
- Nutritional Supplements:Powder and ready-to-drink formulations targeting active nutrition and clinical recovery displace conventional dairy proteins. EMA's expanded medical food category definitions create premium positioning for hydrolysate-grade materials targeting post-surgical recovery segments.
- Animal Feed:Enzyme-treated oilseed meals improve amino acid bioavailability for aquaculture and pet nutrition applications.
- Pharmaceuticals:Peptide fractions with documented digestibility profiles enter enteral nutrition and therapeutic food formulations.
Food & Beverages anchors volume procurement; Nutritional Supplements is climbing the fastest on pricing power.
Delivery Mode:
Format selection reflects manufacturing infrastructure compatibility and shelf-stability requirements across ambient, refrigerated, and frozen supply chains.
- Powder:Spray-dried hydrolysates and isolates dominate bulk ingredient procurement for sports nutrition and food manufacturing. Powder formats offer lowest unit logistics costs and longest ambient stability for international sourcing.
- Liquid:Ready-to-use protein solutions reduce reconstitution steps for beverage manufacturers and clinical feeding applications.
- Granules:Agglomerated particles improve dispersibility in instant beverage and dry-mix applications.
- Tablets:Compressed formats serve dietary supplement brands targeting convenience-positioned consumer segments.
Powder leads on scale; liquid is gaining share fastest on formulation agility.
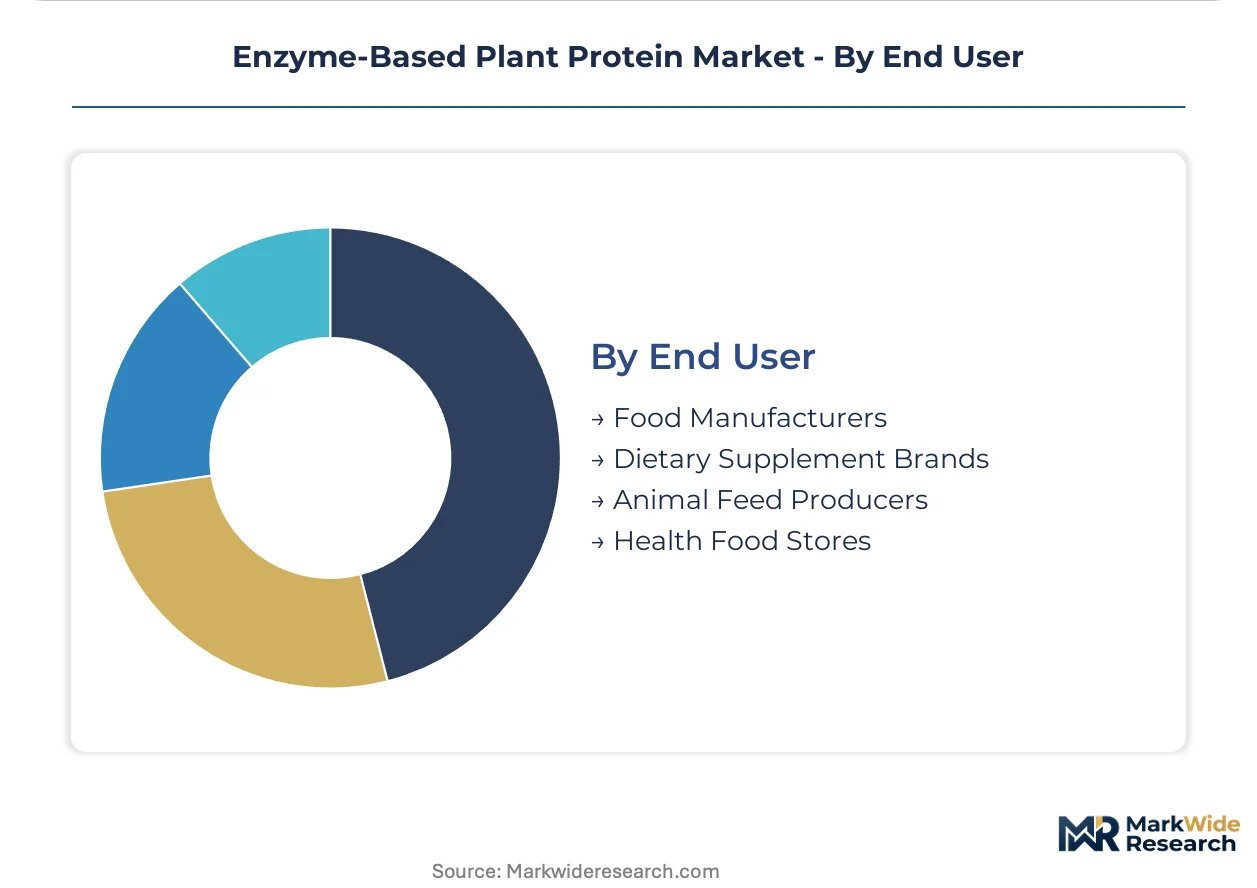
End User:
Technical service intensity and contract structure vary sharply between formulation-capable manufacturers and specification-driven brands.
- Food Manufacturers:Industrial meat-alternative and bakery operations require customized solubility and emulsification profiles with dedicated application support. Mid-scale manufacturers are adopting software-defined formulation services to customize protein functionality without owning bioreactor assets.
- Dietary Supplement Brands:Clean-label positioning and amino acid scoring certification drive premium sourcing for sports and active nutrition products.
- Animal Feed Producers:Cost-optimized procurement of enzyme-treated meals focuses on digestibility metrics and mycotoxin control.
- Health Food Stores:Private-label and branded finished goods retailers specify finished protein products with consumer-facing sustainability credentials.
Food Manufacturers lead on scale; Dietary Supplement Brands lead on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial bakeries and sports nutrition brands are integrating hydrolysates at scale, while the United States is redirecting capital toward enzymatic hydrolysis platforms under updated FDA labeling pathways.
Germany
Industrial bakeries and sports nutrition brands drive hydrolysate procurement for functional food lines and clean-label meat alternatives. The EU Green Deal accelerates sustainability-aligned sourcing mandates for enzymatically treated proteins. Cologne and Hamburg host formulation clusters where manufacturers benchmark multi-vendor enzyme-substrate platforms.
United States
Meat-alternative formulators expand procurement of enzyme-treated soy and pea isolates amid precision fermentation advances. The FDA's updated Generally Recognized as Safe notification framework compresses commercialization timelines for modified plant proteins. Chicago and Minneapolis-St. Paul concentrate mid-scale food manufacturers adopting software-defined formulation services.
Netherlands
Sports nutrition brands displace conventional whey with enzymatically treated pea and fava hydrolysates for EU sustainability compliance. EFSA novel food assessments shape toxicological data requirements for high-degree-of-hydrolysis ingredients. Wageningen anchors bioprocess engineering talent pipelines and fermentation scale-up expertise.
France
Industrial bakeries adopt enzyme-treated cereal proteins with controlled degree of hydrolysis as egg replacement accelerates in functional bread and pastry applications. REACH compliance frameworks influence enzyme house operational protocols for substrate-specific proteases. Lyon and Paris basin manufacturing corridors integrate rapid prototyping services for customized solubility profiles.
Canada
Pulse harvest cycles from prairie provinces directly feed into North American hydrolysate production, though feedstock cost volatility compresses margins for producers locked into annual supply contracts. Health Canada and PMRA oversight of novel food ingredients creates parallel certification pathways. Saskatchewan and Manitoba agricultural processing hubs link to Danish and Dutch fermentation facilities for microbial protease supply.
Enzyme-Based Plant Protein Market Competitive Landscape
Top-tier vendors anchor microbial enzyme supply and integrated strain-to-isolate platforms, while mid-scale specialists compete through flavor-masking technologies and software-defined formulation services. The vendor base stratifies across fermentation asset owners, application technology providers, and cloud-based optimization platforms. Three archetypes dominate: integrated ingredient houses controlling strain development through finished isolates; enzyme houses retaining bioreactor ownership and charging functionality-as-a-service; and sensory science specialists pairing taste modulation with protein portfolios. Competitive moves concentrate on strategic partnerships for regulatory dual-certification capacity and geographic expansion into medical nutrition segments.
Among Danish and Dutch fermentation specialists, Novozymes A/S and DSM exemplify integrated platform strategies spanning microbial enzyme supply through finished isolate production. Kerry Group occupies a position within the application-technology tier, representing specialists that pair enzymatic treatment with sensory science capabilities. These three anchors illustrate how competitive positioning stratifies between asset-heavy fermentation ownership and service-based formulation partnerships.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Kerry Group |
| DuPont de Nemours |
| Novozymes A/S |
| DSM |
| Roquette Frères |
| Tate & Lyle |
| Ingredion |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up enzyme houses in Denmark and the Netherlands are consolidating fermentation assets, tightening supply discipline while compressing price floors for North American buyers locked into annual offtake agreements. This ownership concentration feeds directly into pricing power asymmetries between microbial protease suppliers and mid-scale hydrolysis operators.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for enzyme-treated isolates as modular immobilized-reactor deployments expand service-based supply. Pricing stratifies across premium hydrolysate grades for medical nutrition, standard isolates for sports supplements, and economy concentrates for meat-alternative bulk buyers. Cost compression in the economy tier is intensifying because Canadian pulse harvest volatility transmits directly into feedstock contracts. Dietary supplement brands exhibit least price sensitivity due to clean-label premium positioning, while industrial bakeries negotiate aggressively on volume.
Supply Chain Analysis
Freight cost escalation on trans-Atlantic enzyme shipments is forcing North American hydrolysis operations to absorb margin compression or pass through to contract customers. Supply concentrates in Denmark, the Netherlands, and Germany for microbial protease fermentation, while Canada and Australia anchor pea and fava protein isolate feedstock. The chain draws from single-source vulnerability in Danish fermentation facilities, substrate price volatility in prairie province pulse harvests, and regulatory divergence between FDA GRAS and EFSA novel food pathways. Distribution runs through specialized ingredient distributors with technical service capabilities, bypassing commodity chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as precision fermentation maturation sustains enzymatic hydrolysis cost reduction across the projection horizon.
For Market Incumbents: Anticipate flavor-masking technology consolidation as bitter peptide sequences in high-DH hydrolysates outpace in-house sensory capabilities at plant protein specialists. Defend margin position by deepening captive protease supply through backward integration into strain development partnerships, and by front-loading clinical digestibility studies to preempt EFSA toxicological data requirements for medical nutrition positioning. For New Entrants and Emerging Players: The gap between premium hydrolysate pricing for clinical nutrition and economy concentrate rates for meat alternatives opens white-space targeting. Medical nutrition applications in post-surgical recovery segments remain underpenetrated relative to sports nutrition saturation. Enter through software-defined formulation services that let mid-scale brands customize solubility profiles without bioreactor ownership, bypassing capital barriers that protect incumbents. For Investors and Strategic Acquirers: Food manufacturers with stranded meat-alternative capacity are the most active acquirer in this space, seeking enzymatic treatment capabilities to pivot formulation pipelines. Long-term viability hinges on regulatory dual-certification capacity as FDA and EFSA pathways diverge on novel food assessments. Watch for EMA medical food category expansion signals as inflection indicators for hydrolysate-grade material premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive protease supply reduces single-source dependency on Danish fermentation clusters. |
| Regulatory Dual-Certification Investment | Parallel FDA GRAS and EFSA novel food submissions unlock premium medical nutrition positioning. |
| Software-Defined Formulation Platform Launch | Cloud-based enzyme-substrate optimization lets brands customize functionality without bioreactor assets. |
| Flavor-Masking Technology Acquisition | Sensory science capabilities address bitter peptide challenges in high-DH hydrolysate applications. |
| Medical Nutrition Segment Expansion | EMA category definitions for clinical foods open premium pricing for hydrolysate-grade materials. |
Research Methodology
Direct dialogue with fermentation plant managers, enzyme house technical directors, sports nutrition procurement leads, and EFSA regulatory affairs specialists grounded qualitative findings, cross-checked against customs data on protease imports, FDA GRAS notification filings, EFSA novel food registers, and European industrial bakery production statistics. Bottom-up volume estimates from individual facility capacities reconciled with top-down market sizing from trade association disclosures.
Top-down macroeconomic drivers and bottom-up segment trajectories converged across the analysis window. The framework modeled product type splits, application demand clusters, delivery mode logistics costs, and end-user technical service intensity. CAGRs derived from weighted average of historical growth patterns and forward-looking capacity announcements. Forecast inputs included precision fermentation cost curves and evolving amino acid scoring methodology adoption.
Caveats apply where EFSA toxicological data requirement tightening or FDA labeling pathway revisions could materially shift the outlook for high-DH hydrolysate commercialization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Germany Soy Protein Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Soy Protein Market