
 Vegan Steak Market | 2026-2036
Vegan Steak Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Steak Market Analytics
Market Context with Strategic Players
Food technologist shortages in extrusion and mycoprotein processing is unwinding capacity expansion timelines across the sector. Beyond Meat leverages its integrated manufacturing footprint to sustain shelf-space negotiations with major retail chains. Impossible Foods anchors its position through heme fermentation expertise that differentiates sensory profiles from commodity alternatives. Amy's Kitchen competes via certified organic supply chains that command premium placement in natural grocery channels.
Technical Definition and Structural Segments
Vegan steak comprises structured plant protein products engineered to replicate the fibrous texture, umami profile, and visual appearance of conventional beef cuts, typically achieving moisture content of 50-70% through high-moisture extrusion or shear-cell processing. These products serve commercial foodservice and retail channels seeking protein alternatives with comparable cook yields and menu versatility to animal-derived cuts. Pea protein formulations currently lead volume due to allergen positioning and neutral flavor bases, while wheat gluten segments retain cost advantages in European and Asian manufacturing. Smoked product types capture expanding margin pools as flavor-forward positioning commands price premiums in specialty retail and premium foodservice accounts.
Regulatory Framework and Outlook
The FDA and USDA share oversight of plant-based meat labeling in the United States, while the EU's EFSA and national regulators enforce Novel Food authorizations for emerging protein ingredients and restrict dairy-associated terminology under existing agricultural designations. REACH compliance in Europe and evolving state-level labeling statutes in the US create fragmented compliance burdens that favor multi-jurisdictional regulatory teams. Stakeholders must monitor pending precision fermentation approvals and carbon accounting standards that will reshape ingredient sourcing decisions and clean-label positioning strategies.
Market Dynamics
High-moisture extrusion technology is compressing production costs and enabling texture parity with conventional beef cuts, fundamentally altering how manufacturers compete on sensory performance rather than price alone.
Growth Catalysts
- EU Green Deal protein targets:Mandatory sustainable protein quotas in institutional foodservice across Germany, the Netherlands, and Denmark are creating guaranteed offtake volumes for certified plant-based suppliers.
- Shear-cell processing:This emerging texturization method eliminates extrusion energy costs while producing aligned fiber structures that match beef chew profiles, attracting equipment investment from European processors.
- Foodservice operator consolidation:Large contract caterers in the United Kingdom and United States are standardizing plant-based menu percentages, generating predictable procurement pipelines for approved vegan steak SKUs.
Market Restraints
- Pea protein supply concentration:Over 70% of food-grade pea protein isolate originates from Canadian and French processors, creating input cost volatility when harvest yields fluctuate.
- EFSA Novel Food timelines:Emerging mycoprotein and precision fermentation ingredients face 18-24 month safety evaluation windows that delay product launches and tie up R&D capital.
- Conventional beef price compression:Cattle cycle lows in Brazil and Australian export surges are narrowing the retail price gap that vegan steak requires for mainstream penetration.
Strategic Opportunities
- Carbon labeling mandates:France's upcoming compulsory environmental scoring on packaged foods creates first-mover advantage for suppliers with verified lifecycle data and low-carbon ingredient sourcing.
- QSR breakfast daypart expansion:Quick-service chains are adding plant-based protein to morning menus, opening a channel previously dominated by pork and poultry alternatives with lower texture requirements.
- Hybrid retail-foodservice models:Ghost kitchen operators and meal-kit platforms in urban United States markets are building dedicated vegan protein categories that bypass traditional retail slotting barriers.
Industry Challenges
- Extrusion technician scarcity:Food science programs produce fewer specialists in high-moisture extrusion parameter optimization than equipment manufacturers require for commissioning new production lines.
- Dual certification complexity:Simultaneous organic and non-GMO verification across USDA National Organic Program and Non-GMO Project standards extends qualification timelines by 8-14 months.
- Co-manufacturer capacity constraints:Qualified toll processors with validated allergen segregation protocols for soy-free and gluten-free runs command premium rates and 6-9 month lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Steak Market |
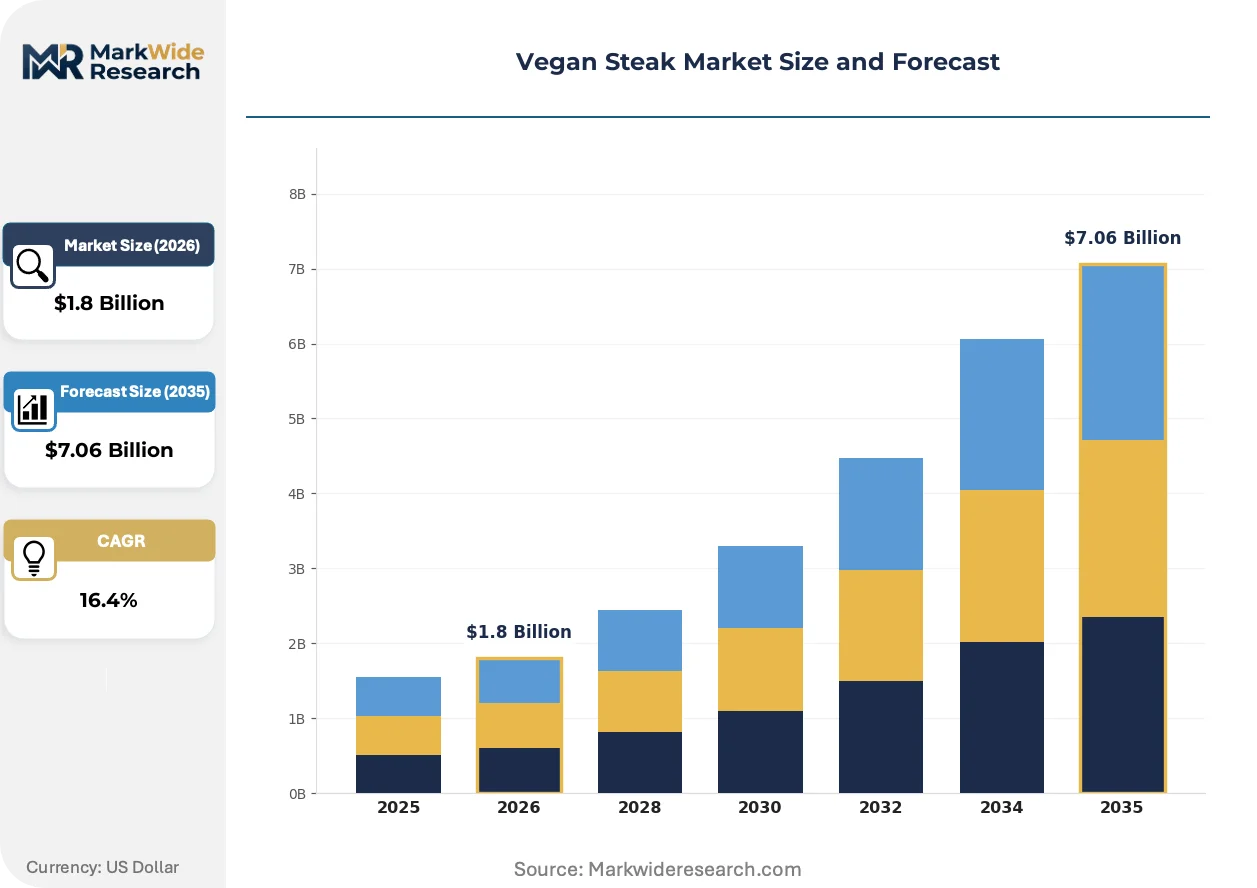
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grilled, Sautéed, Smoked, Marinated Protein Source: Pea Protein, Soy Protein, Wheat Gluten, Lentils Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Foodservice Consumer Segment: Vegans, Vegetarians, Flexitarians, Health-Conscious Consumers |
| Companies Covered | Beyond Meat, Impossible Foods, Danone, The Archer Daniels Midland Company, Gardein, Amy's Kitchen, Daiya Foods, Field Roast, Maple Leaf Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Steak Market Evolving Landscape
Texture engineering and regulatory disclosure requirements are converging to reshape how vegan steak manufacturers differentiate and how buyers evaluate product claims across retail and foodservice channels.
Precision fermentation of heme proteins is decomposing the sensory gap between plant-based and animal-derived beef by replicating the catalytic chemistry that drives Maillard browning and bloody juiciness. Premium burger chains and steakhouse concepts are piloting these formulations in limited menus to test consumer acceptance of fermented ingredients. This biotechnology is decomposing the historical trade-off between clean-label positioning and performance parity that constrained earlier generation products.
REACH chemical safety registrations in Europe are expanding scope to cover novel protein extraction solvents and processing aids, requiring manufacturers to submit toxicity dossiers for substances previously treated as food-grade. The compliance burden falls most heavily on Asian ingredient suppliers exporting to European markets, who must now maintain European-based regulatory affairs functions or cede market position to domestic producers.
Menu engineering teams at full-service restaurants are rotating protein sourcing decisions into quarterly reviews rather than annual contract cycles, compressing supplier evaluation windows and rewarding agile manufacturers with reformulation capabilities. This pattern concentrates purchasing power with operators who can guarantee texture consistency across batch variations. The United States coastal metropolitan markets exhibit the shortest switching cycles, with some chains testing three to four vegan steak suppliers simultaneously across regional locations.
Vegan Steak Market Segmentation
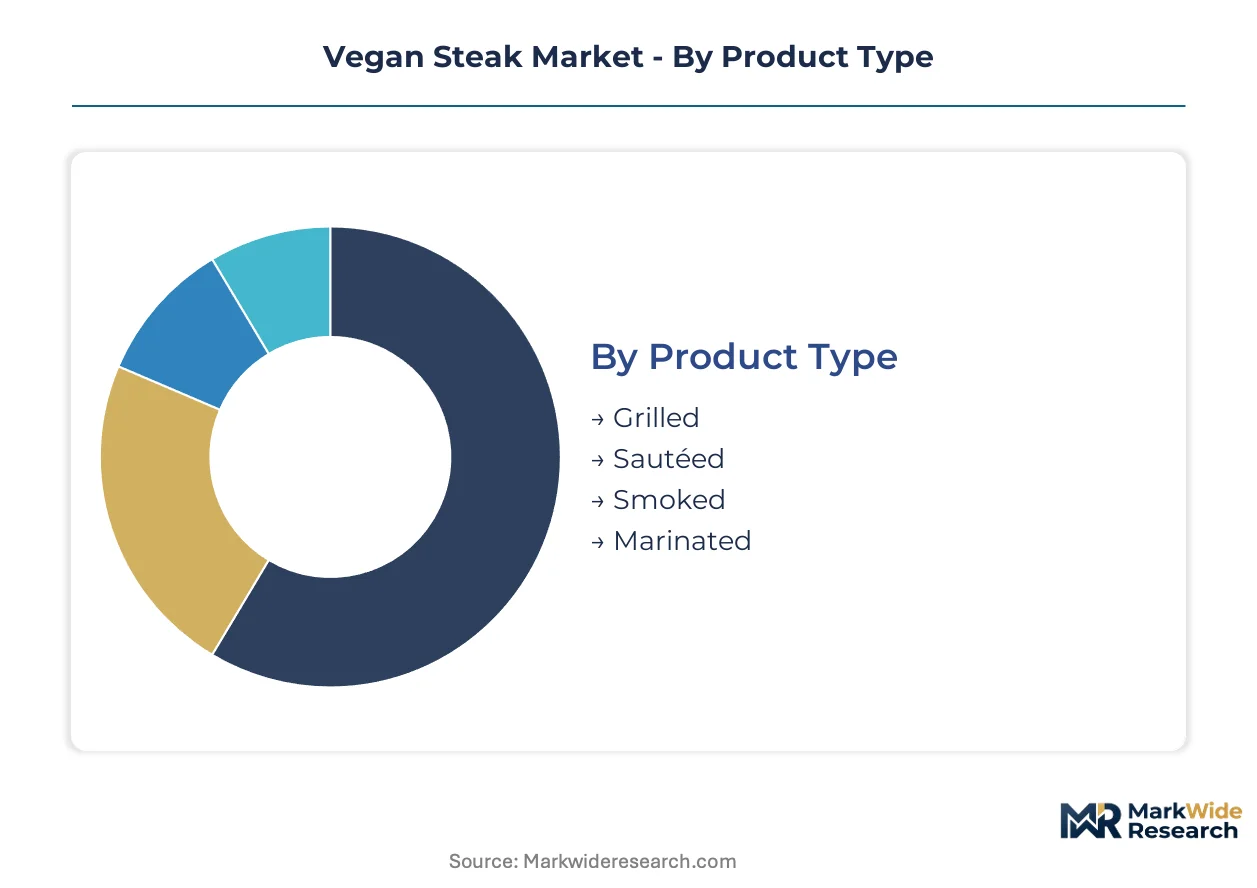
Channel mix determines which vegan steak formulations achieve scale. Product texture requirements differ sharply between retail shelf-stable packs and foodservice back-of-house operations, driving divergent R&D investment patterns across manufacturers.
Product Type:
Grilled and sautéed variants dominate retail freezer cases, while smoked and marinated cuts penetrate premium foodservice accounts with higher margin structures.
- Grilled:High-heat seared surfaces replicate char marks through caramelized plant protein crusts. German and United States retail chains stock these as center-plate protein alternatives with mainstream visual appeal.
- Sautéed:Pan-ready strips and medallions prioritize rapid cook times and sauce adhesion. United Kingdom contract caterers specify these for institutional meal programs requiring predictable portion control.
- Smoked:Cold-smoked or liquid-smoke infused products command specialty retail placement. Premium pricing reflects extended production cycles and hardwood sourcing.
- Marinated:Pre-seasoned cuts reduce kitchen labor for foodservice operators. Mediterranean and Asian flavor profiles target ethnic menu integration.
By volume, grilled products lead retail distribution. By growth pace, smoked variants are climbing fastest in premium channels.
Protein Source:
Cost tiers separate commodity inputs from allergen-positioned premium ingredients, with supply concentration in Canada and France shaping procurement strategies.
- Pea Protein:Neutral flavor bases and allergen-free positioning drive formulation adoption. High-moisture extrusion of pea isolates achieves 50-70% moisture content matching beef chew profiles.
- Soy Protein:Mature supply infrastructure and lowest unit costs sustain volume leadership in Asian manufacturing. Textured soy concentrate remains the default for economy-tier retail SKUs.
- Wheat Gluten:European processors exploit regional wheat abundance for cost-advantaged production. Seitan-derived products dominate German and Dutch natural food channels.
- Lentils:Emerging whole-food positioning appeals to clean-label seekers. Limited commercial scale constrains current foodservice penetration.
Pea protein commands the steepest expansion trajectory as allergen concerns reshape formulation decisions. Soy retains volume leadership through established supply chains.
Distribution Channel:
Customer type fragmentation requires distinct packaging formats, with foodservice demanding bulk frozen cases and retail prioritizing single-serve visibility.
- Supermarkets:Mass-market penetration depends on refrigerated meat-alternative aisle placement. United States chains negotiate slotting fees against comparable beef price points.
- Health Food Stores:Certified organic and non-GMO verification gates entry. These channels absorb premium pricing for transparent supply chain claims.
- Online Retailers:Direct-to-consumer subscription models bypass retail margin stacking. Frozen fulfillment infrastructure limits geographic reach to urban clusters.
- Foodservice:Contract caterers and QSR chains drive procurement consolidation. Menu versatility requirements favor products with multiple cook-method compatibility.
Foodservice channels are expanding most quickly as operator consolidation creates volume commitments. Supermarkets retain the largest absolute throughput.
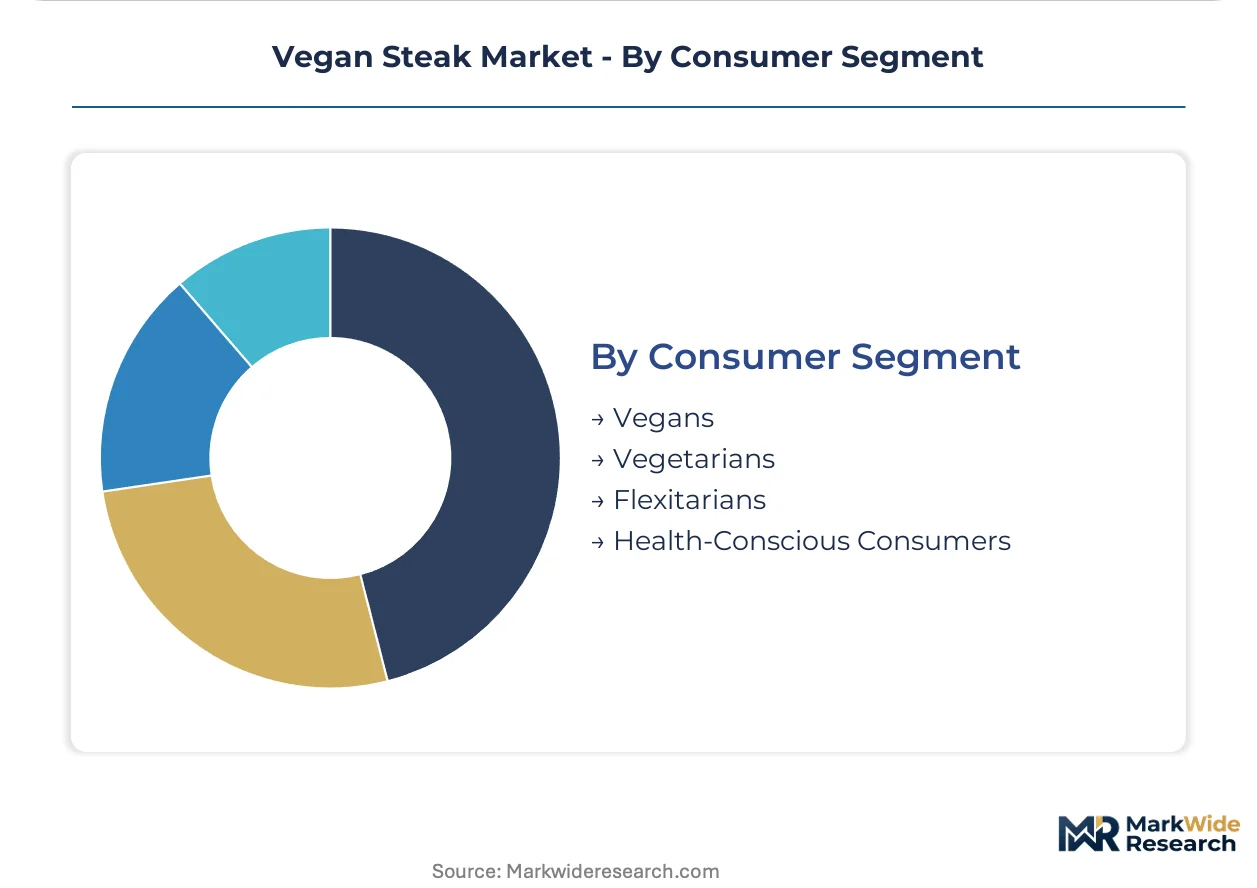
Consumer Segment:
Maturity gradients separate entrenched dietary adherents from experimental purchasers, with flexitarians presenting the largest addressable expansion pool.
- Vegans:Core demand base with zero cross-purchase to animal proteins. Loyalty programs and ethical sourcing certifications sustain retention.
- Vegetarians:Long-standing category participants seeking improved texture parity. Willingness to pay premiums for sensory advances exceeds vegan cohorts.
- Flexitarians:Periodic meat reducers driving mainstream volume growth. Purchase frequency responds to price competitiveness versus conventional beef.
- Health-Conscious Consumers:Cholesterol and saturated fat avoidance motivates trial. Clean-label ingredient lists outweigh environmental claims for this segment.
Flexitarians represent the fastest-growing consumer pool by absolute numbers. Vegans provide the most predictable repeat purchase rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA and USDA jointly oversee plant-based meat labeling standards in the United States, establishing the regulatory baseline that shapes commercialization timelines across major producing nations.
United States
California and New York Metro anchor foodservice adoption as contract caterers standardize plant-based menu percentages. The FDA maintains jurisdiction over ingredient safety declarations while USDA handles labeling integrity for simulated meat products. Beyond Meat leverages its integrated manufacturing footprint to sustain shelf-space negotiations with Kroger and Whole Foods Market in Los Angeles and Austin.
Germany
Berlin and Hamburg drive retail penetration through dedicated vegan protein aisles in REWE and Edeka chains. The EU Green Deal mandates sustainable protein quotas in institutional foodservice across federal states. High-moisture extrusion equipment manufacturers cluster in Bavaria to serve regional processors expanding capacity for export markets.
United Kingdom
London and Manchester concentrate QSR pilot programs testing precision-fermented heme formulations in limited breakfast menus. The Food Standards Agency enforces Novel Food authorizations for emerging protein ingredients with 18-24 month evaluation windows. Contract caterers in the Southeast standardize quarterly supplier reviews that compress procurement decision cycles.
France
Paris and Lyon command premium placement for smoked and marinated variants in specialty retail channels. ANSM enforces REACH compliance expansions covering novel protein extraction solvents and processing aids. The upcoming compulsory environmental scoring on packaged foods creates first-mover positioning for suppliers with verified lifecycle data.
Netherlands
Amsterdam and Rotterdam host shear-cell processing equipment trials that eliminate extrusion energy costs while producing aligned fiber structures. EFSA maintains Novel Food safety evaluation protocols that delay mycoprotein product launches. Wageningen University anchors research partnerships linking food technologist training to commercial processor demands.
Vegan Steak Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages separating extrusion-capable manufacturers from ingredient suppliers. The upper tier commands retail slotting fees through captive manufacturing footprints. Three archetypes define competitive positioning: biotechnology specialists leveraging fermentation differentiation, integrated protein processors controlling supply chains from isolate to finished cut, and organic-certified kitchen brands serving natural grocery channels. Capacity expansion and strategic partnerships dominate competitive moves as equipment commissioning delays stretch timelines.
Within the biotechnology tier, Impossible Foods occupies a position exemplifying heme fermentation expertise that differentiates sensory profiles. Among integrated processors, Beyond Meat and Maple Leaf Foods represent scale-driven archetypes with manufacturing footprints spanning multiple jurisdictions. Amy's Kitchen anchors the certified-organic specialist segment, commanding premium placement through transparent supply chain claims that satisfy natural channel gatekeepers.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Danone |
| The Archer Daniels Midland Company |
| Gardein |
| Amy's Kitchen |
| Daiya Foods |
| Field Roast |
| Maple Leaf Foods |
| Others |
Value Network & Pricing Analysis
EU Green Deal protein quotas gate both supplier qualification and price differentiation, forcing manufacturers to absorb certification costs while institutional buyers leverage mandated volume commitments to compress contract rates.
Pricing Analysis
Retail price spreads between German and United States markets exceed transport-cost differentials, signaling regional brand-premium capture. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and protein source concentration. Cost compression in economy tiers is intensifying because Brazilian and Australian beef export surges narrow the price gap required for mainstream penetration. Flexitarian consumers exhibit highest price sensitivity, while vegan adherents accept premiums for ethical sourcing verification.
Supply Chain Analysis
Strategic stockpiling of Canadian and French pea protein isolate dominates inventory strategy, with processors building 4-6 month buffers against harvest-yield volatility rather than pursuing just-in-time procurement. Supply concentrates in Canada, France, and China for protein isolates, with extrusion equipment manufacturing anchored in Germany and the Netherlands. Raw material dependencies center on pea and wheat gluten inputs, with mycoprotein fermentation feedstocks emerging as a secondary tier. Single-source vulnerability in Canadian pea protein processing creates structural exposure to climate-driven harvest failures. Distribution runs through frozen cold-chain logistics serving retail freezer cases and foodservice bulk frozen cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against precision-fermented cultivated meat, which threatens to leapfrog plant-based texture parity while claiming superior environmental credentials.
For Market Incumbents: Consolidate extrusion capacity through backward integration into high-moisture equipment manufacturing, reducing commissioning delays that currently stretch 12-18 months. Lock in multi-year offtake agreements with Canadian and French pea protein processors before cultivated meat achieves regulatory approval and diverts institutional procurement budgets.
For New Entrants and Emerging Players: Lead with smoked and marinated premium variants in French and German specialty retail, where flavor-forward positioning commands price premiums and established players underindex. Bypass supermarket slotting-fee barriers through direct-to-consumer subscription models in United States urban clusters, leveraging frozen fulfillment infrastructure partnerships.
For Investors and Strategic Acquirers: EFSA precision fermentation approvals reshape the acquisition landscape by determining which ingredient platforms achieve commercial scale versus regulatory limbo. Position for 5-10 year horizon by targeting shear-cell processing equipment manufacturers and mycoprotein fermentation specialists with validated safety dossiers. Watch carbon labeling mandate adoption rates in France as the signal for when environmental scoring becomes a procurement gate across broader European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Shear-Cell Processing Equipment Investment | Eliminates extrusion energy costs while achieving beef-comparable fiber alignment for European processors. |
| Precision Fermentation Heme Partnership | Secures exclusive access to Maillard-reactive proteins that differentiate sensory profiles from commodity alternatives. |
| Dual Certification Program (Organic + Non-GMO) | Opens natural grocery channel placement commanding 15-25% retail price premiums over conventional SKUs. |
| Institutional Foodservice Contract Consolidation | Captures guaranteed offtake volumes from EU Green Deal-mandated sustainable protein quotas in Germany and Netherlands. |
| Carbon Lifecycle Data Verification | Positions suppliers for France's compulsory environmental scoring and emerging procurement gates across European markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with food technologists, extrusion equipment manufacturers, contract catering procurement directors, and retail category buyers; and secondary validation through EFSA Novel Food submission databases, EU Green Deal policy documentation, USDA plant-based meat labeling guidance, and customs trade records for pea protein isolate flows. Bottom-up triangulation cross-checked manufacturer capacity announcements against equipment order backlogs, while top-down analysis reconciled institutional procurement mandates with retail scanner data patterns.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, protein source, distribution channel, and consumer segment, with regional regulatory clusters treated as distinct adoption curves. CAGRs were derived from segmented growth rate analysis rather than single-point extrapolation. Forecast inputs incorporated extrusion technician training pipeline data, EFSA evaluation timeline distributions, and cattle cycle price projections affecting conventional beef competitive positioning.
Forecasts assume regulatory continuity in FDA-USDA labeling jurisdiction and EFSA Novel Food protocols; material policy shifts would require re-modeling. Specific risks that could revise trajectories include accelerated precision fermentation approvals, abrupt pea protein harvest failures, or state-level labeling restrictions in the United States. Revision becomes warranted when cultivated meat cost curves cross threshold parity with plant-based alternatives in foodservice procurement evaluations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Vegan Food Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Plant-Based Diet Market