
 Europe Dried Mushroom Market | 2026-2036
Europe Dried Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dried Mushroom Market Insights
Restaurant group procurement across France and Italy is expanding as a concentrated buyer force, consolidating annual contracts with preferred suppliers. Scelta Mushrooms leverages its Belgian processing infrastructure to anchor supply relationships with these foodservice chains. Monaghan Mushrooms competes through integrated growing and drying operations across Ireland and the UK. Biofungi GmbH specializes in organic-certified shiitake cultivation, differentiating its portfolio for German retail buyers demanding EMAS-validated environmental credentials.
Europe dried mushrooms comprise dehydrated fungal fruiting bodies preserved through air-drying, freeze-drying, or vacuum microwave methods, typically reducing moisture content below 10 percent to inhibit microbial degradation and extend shelf stability for commercial ingredient use. Shiitake varieties dominate industrial volumes due to standardized umami profiles suited to food processing applications, while porcini commands premium positioning in specialty retail channels across Southern Europe. The nutraceuticals application segment records accelerating interest as polysaccharide extraction for immune-support formulations gains traction among supplement manufacturers. Online distribution channels occupy the fastest-growing position, though supermarkets sustain the largest revenue pool through established private-label programs.
EMA food-contact material guidelines, EU Organic Regulation 2018/848, and national pesticide residue frameworks under EFSA coordination collectively shape product standards and market access conditions for dried mushroom imports and intra-EU trade. REACH compliance requirements for processing additives and packaging materials add compliance layers that favor established suppliers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving organic certification thresholds and emerging novel food applications for mycelium-derived ingredients to anticipate competitive repositioning requirements.
Market Dynamics
The EU's Farm to Fork Strategy under the European Green Deal is compressing pesticide residue thresholds and mandating organic cultivation certification, forcing suppliers to restructure drying operations around EMAS-validated environmental credentials and EU Organic Regulation 2018/848 compliance.
Growth Catalysts
- EU Organic Regulation 2018/848:Mandatory organic certification thresholds are redirecting procurement budgets toward certified suppliers, expanding contract volumes for EMAS-validated processors in Germany and Poland.
- Ready-meal manufacturing:Food processing manufacturers across Germany and Poland are scaling procurement of dried porcini and shiitake varieties for soup, sauce, and pasta formulations.
- Polysaccharide extraction:Nutraceutical manufacturers are accelerating demand for shiitake-derived beta-glucans for immune-support supplement formulations.
Market Restraints
- Input cost volatility:Natural gas and electricity price instability in Germany and Italy directly impacts thermal drying economics, compressing margins for air-drying operators.
- Supply concentration risk:Wild porcini harvesting concentrates in specific forest zones across Italy and France, exposing buyers to weather-dependent yield fluctuations.
- Substitution threat:Liquid umami concentrates and yeast extracts are displacing dried mushroom powders in cost-sensitive industrial flavor applications.
Strategic Opportunities
- Eastern European cultivation expansion:Poland and Romania offer underdeveloped organic mushroom farming capacity with lower land and labor costs for shiitake substrate operations.
- Online direct-to-chef distribution:Specialty e-commerce platforms are bypassing traditional wholesale tiers to connect dried porcini suppliers directly with restaurant kitchens.
- Novel food pathway:Mycelium-derived ingredients under EFSA novel food assessment are opening extraction applications beyond traditional fruiting body products.
Industry Challenges
- Certification timeline compression:EU Organic Regulation 2018/848 conversion periods and EMAS validation cycles extend supplier onboarding to 18-24 months, constraining rapid capacity scaling.
- Freeze-drying capex intensity:Vacuum freeze-drying equipment requires substantial capital deployment, limiting adoption among mid-sized Polish and Romanian processors.
- Regulatory affairs capacity scarcity:REACH compliance for packaging materials and EFSA coordination for residue testing demand specialized personnel that smaller suppliers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dried Mushroom Market |
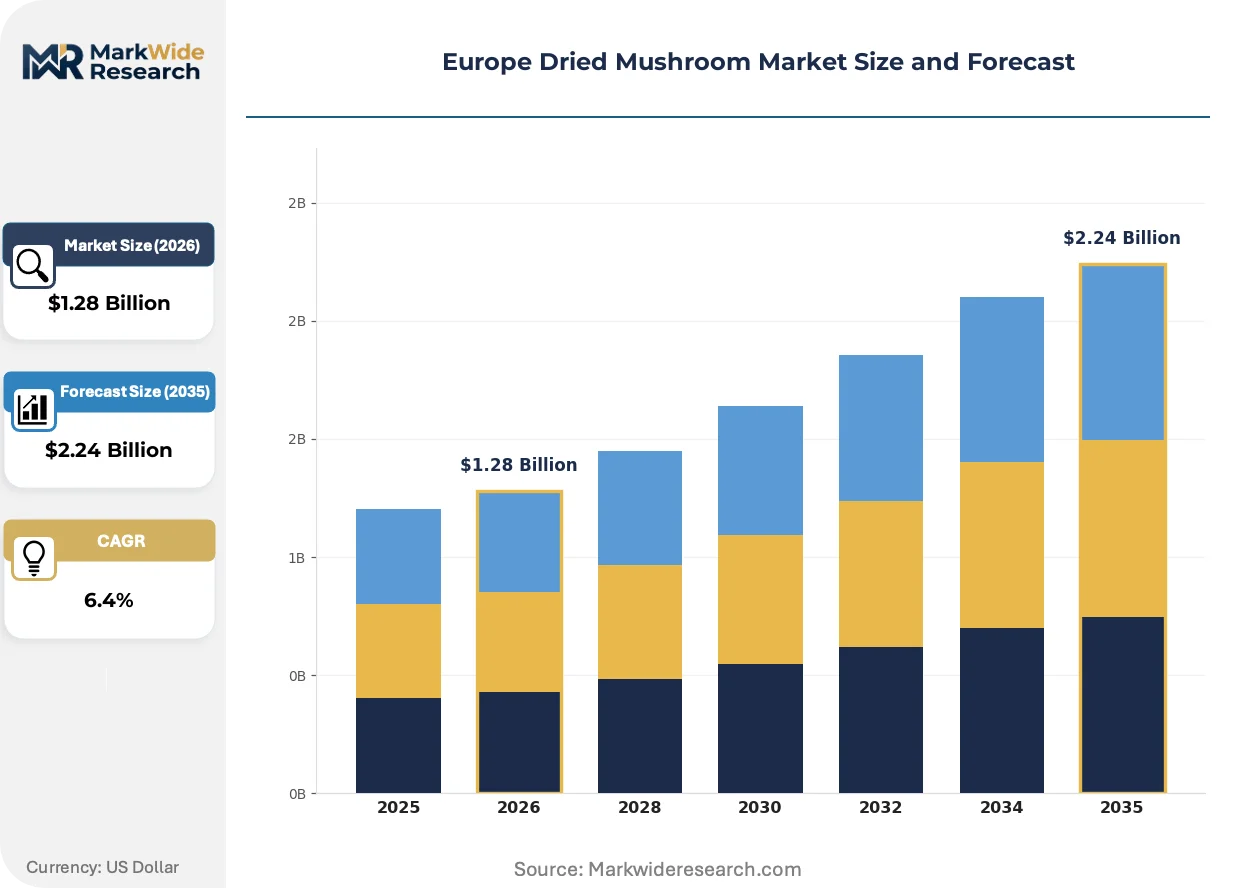
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shiitake, Porcini, Chanterelle, Morel Application: Culinary, Food Processing, Nutraceuticals, Snacks Distribution Channel: Online, Supermarkets, Food Retailers, Specialty Stores Customer Type: Households, Restaurants, Hotels, Caterers |
| Companies Covered | Greenyard, Scelta Mushrooms, Banken Champignons B.V., OKECHAMP S.A., The Mushroom Company, Fresh Mushroom Europe, Sabarot, Biofungi GmbH, Monaghan Mushrooms, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dried Mushroom Market Trends and Innovations
Processing technology convergence and procurement model evolution are restructuring competitive positioning across European dried mushroom supply chains. Suppliers are racing to differentiate through certification stacking and extraction capabilities.
Freeze-drying technology is overtaking conventional air-drying for premium porcini and shiitake destined for restaurant and retail channels. French and Italian specialty buyers are adopting vacuum freeze-dried products at accelerating rates due to superior rehydration performance and volatile compound retention. This technology is overtaking thermal methods in the premium tier, compressing air-drying margins and forcing equipment upgrades among established suppliers.
EMA food-contact material guidelines and REACH compliance requirements for processing additives are tightening documentation burdens across packaging and drying aid categories. Industrial consequence includes mandatory migration testing for plastic films and desiccant packets, extending quality assurance cycles. German retail private-label programs are most affected, responding by consolidating supplier bases toward integrated processors with captive laboratory capacity.
Annual contract consolidation is concentrating buyer power among French and Italian restaurant chains, displacing spot-market purchasing for core dried mushroom varieties. Foodservice procurement teams are centralizing supplier relationships and demanding volume-commitment pricing structures. This shift is most visible across Paris and Milan metropolitan restaurant group headquarters, where preferred supplier lists have narrowed to three-to-four certified organic processors.
Europe Dried Mushroom Market Segmentation
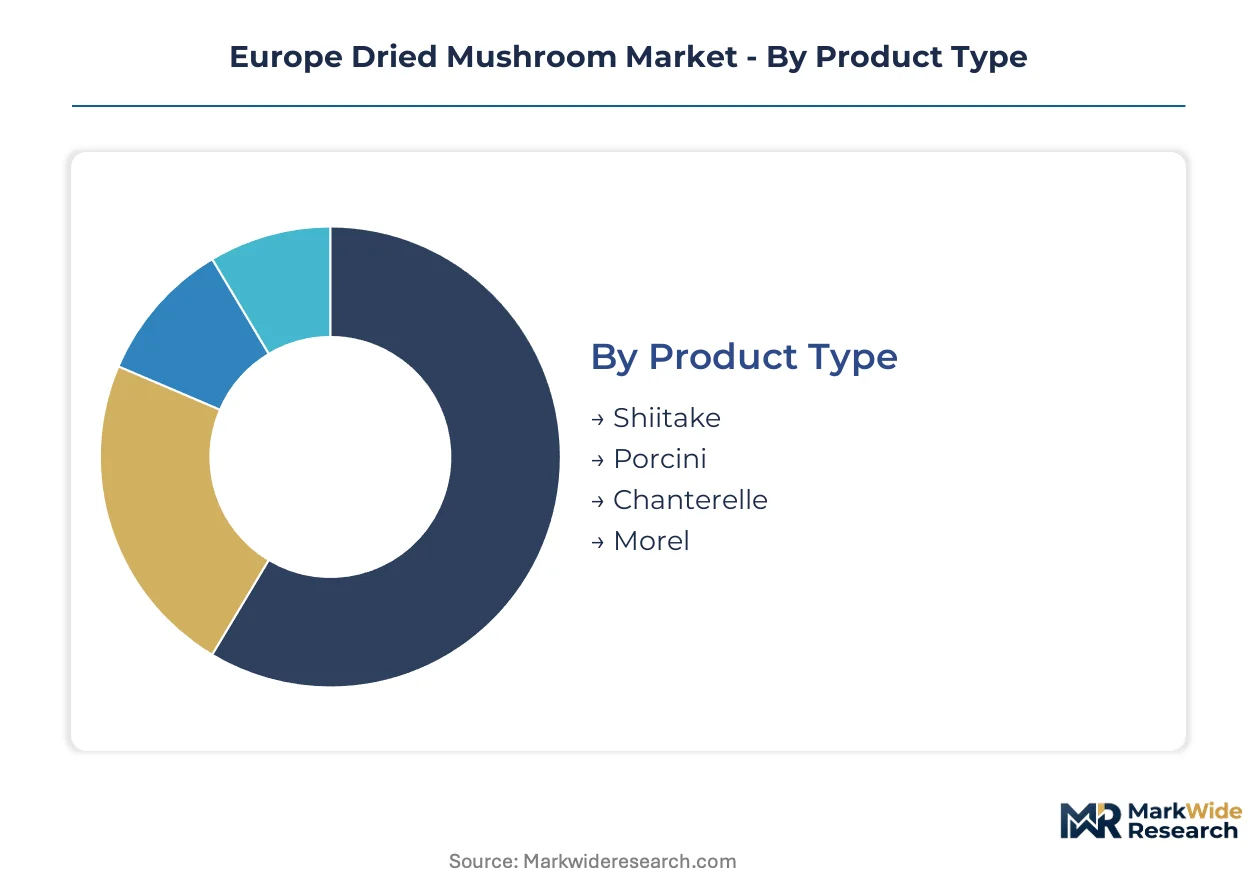
Segmentation reveals how capital requirements, certification tiers, and channel economics fragment procurement strategies across European dried mushroom supply chains. Buyers optimize sourcing differently by product chemistry, end-use specification, and regulatory exposure.
Product Type:
Freeze-drying and vacuum microwave infrastructure demands diverge sharply across fungal varieties, with porcini requiring the most specialized handling due to volatile compound sensitivity.
- Shiitake:Standardized umami profiles from Lentinula edodes fruiting bodies suit industrial-scale extraction and food processing applications. German and Polish ready-meal manufacturers concentrate procurement here for soup and sauce formulations, driven by consistent polysaccharide yields and shorter cultivation cycles.
- Porcini:Boletus edulis specimens demand gentle dehydration protocols to preserve aromatic terpenoids and justify premium positioning. Italian and French restaurant chains anchor demand, though wild harvest concentration in specific forest zones exposes supply to weather-dependent yield fluctuations.
- Chanterelle:Cantharellus cibarius varieties occupy mid-tier retail positioning with moderate rehydration performance.
- Morel:Morchella species command niche gastronomic applications with limited commercial cultivation and heavy reliance on seasonal foraging.
Most installed capacity flows through shiitake operations. Expansion is steepest in porcini freeze-drying for premium foodservice channels.
Application:
Margin structures diverge by downstream processing intensity, with extraction-grade specifications commanding stricter contamination controls than whole-product culinary uses.
- Culinary:Whole dried fruiting bodies and coarse powders for restaurant rehydration and home cooking applications concentrate in Italian and French metropolitan foodservice procurement.
- Food Processing:Standardized particle sizes and moisture specifications for industrial soup, sauce, and pasta manufacturing drive volume demand across German and Polish processing facilities.
- Nutraceuticals:Beta-glucan extraction for immune-support supplements requires pharmaceutical-grade substrate control and EFSA-coordinated residue testing protocols.
- Snacks:Seasoned dried mushroom crisps occupy emerging retail positioning with lighter regulatory burdens than extraction applications.
Food processing absorbs the largest raw material volumes. Nutraceuticals extraction represents the fastest-growing trajectory as polysaccharide research accelerates.
Distribution Channel:
Channel selection determines certification documentation requirements, with direct online sales demanding lighter traceability infrastructure than supermarket private-label programs.
- Online:Direct-to-chef platforms and specialty e-commerce bypass wholesale tiers, connecting Romanian and Polish suppliers with Paris and Milan restaurant kitchens.
- Supermarkets:German retail private-label programs dominate revenue concentration, requiring EMAS-validated environmental credentials and REACH-compliant packaging documentation.
- Food Retailers:Mid-tier grocery channels across France and Italy emphasize organic certification stacking for shelf positioning.
- Specialty Stores:Gourmet delicatessens and ethnic food shops concentrate porcini and morel sales with educated staff and premium pricing tolerance.
Supermarket channels move the highest absolute volumes. Online distribution is gaining share fastest among independent restaurant procurement teams.
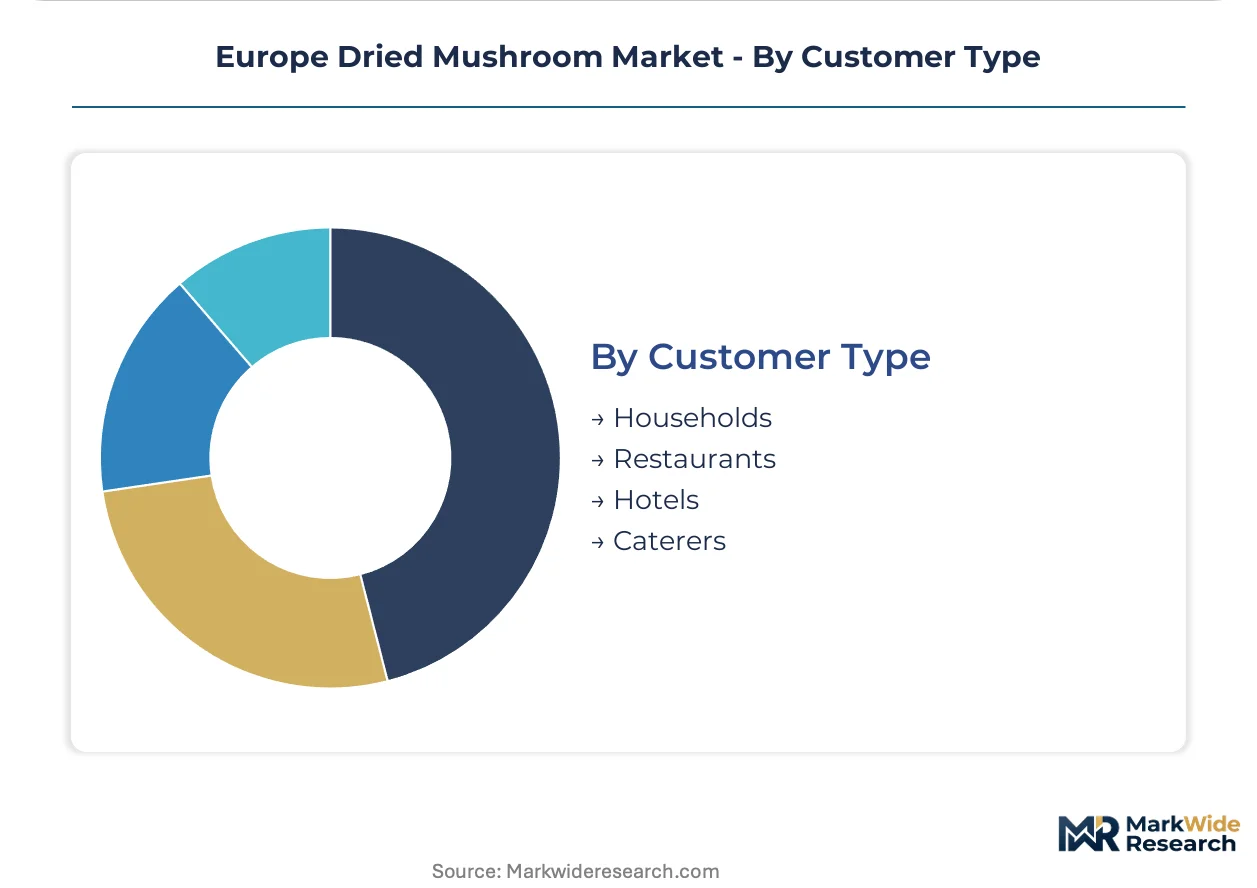
Customer Type:
Contract structures vary by buyer scale, with hotel and catering groups demanding annual volume commitments that exclude smaller spot-market suppliers.
- Households:Retail package sizes and resealable formats dominate, with German consumers showing strongest organic certification preference.
- Restaurants:French and Italian restaurant group procurement teams centralize supplier relationships and narrow preferred vendor lists to three-to-four certified organic processors.
- Hotels:Hospitality procurement across Alpine and Mediterranean resort regions emphasizes consistent supply security over price minimization.
- Caterers:Event and institutional foodservice operators prioritize cost-efficient shiitake powders for large-batch preparation.
Restaurant procurement consolidates fastest. Hotel channel expansion is steepest in organic-certified supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more procurement volume than France, yet Italian buyers command steeper premiums for wild-harvested porcini. The EU Green Deal's Farm to Fork Strategy tightens pesticide thresholds uniformly, but national enforcement patterns create divergent compliance burdens across member states.
Germany
Ready-meal manufacturers in Lower Saxony and Bavaria drive shiitake procurement for soup and sauce formulations. EMAS-validated environmental credentials now gate access to supermarket private-label programs under the EU Organic Regulation 2018/848. Berlin-Brandenburg hosts the densest cluster of certified organic drying operations, where processors retrofit air-drying lines to meet compressed conversion timelines.
France
Restaurant group procurement in Paris and Lyon consolidates annual contracts around freeze-dried porcini with superior rehydration performance. ANSM coordination with EFSA on residue testing protocols extends quality assurance cycles for imported specimens. The Auvergne-Rhône-Alpes region anchors wild chanterelle harvesting networks, though climate variability compresses seasonal yield windows.
Italy
Specialty retailers in Milan and Rome sustain premium positioning for dried porcini with aromatic terpenoid preservation. Domestic organic certification under EU Regulation 2018/848 overlaps with traditional DOP geographical indications, creating stacked documentation requirements. Piedmont and Tuscany concentrate small-scale freeze-drying capacity serving direct-to-chef distribution channels.
Poland
Food processing manufacturers scale shiitake procurement for industrial pasta and sauce applications at cost-efficient volumes. Lower land and labor costs attract substrate cultivation expansion, though EMAS validation cycles delay organic certification by 18-24 months. The Mazovia region clusters mid-sized drying operations upgrading from thermal to vacuum microwave methods.
Belgium
Cross-border processing infrastructure near Antwerp and Ghent serves French and German buyers with consolidated logistics. REACH compliance for packaging materials and desiccant migration testing concentrates regulatory affairs capacity among integrated operators. Flemish organic certification bodies coordinate with Dutch and German counterparts on mutual recognition protocols.
Europe Dried Mushroom Market Competitive Landscape
Benelux producers anchor one tier; Irish and UK specialists hold integrated growing-drying positions. The supplier base fragments across certification tiers rather than scale tiers, with EMAS-validated organic processors commanding contract premiums over conventional operators. Three archetypes dominate: integrated cultivator-processors, specialized drying tollers, and extraction-grade nutraceutical suppliers. Consolidation pressures favor backward integration into substrate cultivation and captive laboratory capacity for REACH documentation.
Within the integrated cultivation tier, Monaghan Mushrooms and Biofungi GmbH exemplify divergent geographic and certification strategies. Scelta Mushrooms occupies a position bridging Belgian processing infrastructure with French and Italian foodservice relationships. Greenyard represents scale-driven diversification across fresh and preserved mushroom categories. Banken Champignons B.V. and OKECHAMP S.A. sit within the specialized drying and distribution archetype, serving private-label and industrial formulation demand.
| Leading Market Players |
|---|
| Greenyard |
| Scelta Mushrooms |
| Banken Champignons B.V. |
| OKECHAMP S.A. |
| The Mushroom Company |
| Fresh Mushroom Europe |
| Sabarot |
| Biofungi GmbH |
| Monaghan Mushrooms |
| Others |
Pricing and Supply Chain Analysis
French and Italian restaurant group procurement teams command contract premiums through concentrated annual volumes, anchoring a pricing model where EMAS-validated organic certification gates access to preferred supplier lists and justifies 15-30 percent spreads over conventional dried mushroom tiers.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for shiitake powders while freeze-drying infrastructure scarcity preserves premiums for porcini. Three-tier pricing structure across premium freeze-dried, standard air-dried organic, and economy conventional tiers separates buyers by rehydration performance requirements and certification stacking. Pricing pressure stems from natural gas cost volatility compressing thermal drying margins in Germany and Italy. Food processing manufacturers in Poland exhibit highest price sensitivity, while Milan and Paris restaurant groups absorb premiums for aromatic compound retention.
Supply Chain Analysis
Road freight costs from Eastern European cultivation zones to Benelux processing hubs anchor logistics economics, with diesel price fluctuations passing through to landed costs. Wild porcini harvests concentrate in Piedmont and Tuscany forests, while shiitake substrate operations cluster in Poland and Romania. Supply chains draw from seasonal foraging networks, synthetic substrate production, and imported dried specimens. Single-source vulnerability runs through Italian wild harvest weather dependence. Distribution runs through Antwerp-Ghent cross-border consolidation points serving French and German buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe dried mushrooms rests on freeze-drying technology diffusion lowering premium-tier production costs and organic certification premiums widening as EU Farm to Fork thresholds tighten.
For Market Incumbents: Acquire vacuum freeze-drying equipment lines to anchor premium porcini positioning against air-drying competitors. Secure EMAS-validated organic certification ahead of EU Organic Regulation 2018/848 conversion deadline compression. Build captive laboratory capacity for REACH-compliant packaging migration testing to defend supermarket private-label relationships against integrated processors. For New Entrants and Emerging Players: The premium-economy price gap in shiitake powders opens white-space entry for mid-tier vacuum microwave processors serving Polish ready-meal manufacturers. Target direct-to-chef e-commerce channels in Paris and Milan bypassing wholesale markups. Pursue organic substrate cultivation in Romanian counties with 18-24 month certification runway to capture German retail procurement shifts. For Investors and Strategic Acquirers: Food processing conglomerates with ready-meal divisions are the most active acquirer in this space, seeking backward integration into stable shiitake supply. Five-to-ten year viability favors integrated cultivator-processors with captive drying infrastructure and regulatory affairs capacity. Monitor EFSA novel food pathway approvals for mycelium-derived ingredients as inflection signal for extraction-grade supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Captures premium pricing from French and Italian restaurant chains demanding superior rehydration. |
| Organic Certification Investment | Gates access to German supermarket private-label programs under EU Organic Regulation 2018/848. |
| Direct-to-Chef E-Commerce Launch | Bypasses wholesale tiers connecting Polish suppliers with Paris and Milan restaurant kitchens. |
| Backward Integration into Substrate Cultivation | Secures cost-efficient shiitake supply for industrial powder production in Romania and Poland. |
| REACH-Compliant Packaging Development | Mandatory migration testing for plastic films retains German retail relationships against competitors. |
Research Methodology
Direct dialogue with dried mushroom processors, organic certification body auditors, restaurant group procurement directors, and German supermarket private-label managers grounded qualitative findings. Secondary validation drew from EU Organic Regulation 2018/848 implementation documents, EFSA pesticide residue monitoring reports, ECHA REACH guidance on food-contact materials, and customs trade data for dried fungal product categories. Bottom-up procurement volume estimates triangulated against top-down market sizing across the analysis window.
Bottom-up modeling segmented volume and value by product type, application, distribution channel, and customer archetype across the projection horizon. CAGRs derived from polynomial trend fitting to historical procurement patterns and regulatory timeline impacts. Forecast inputs included EMAS validation cycle durations, freeze-drying equipment deployment pipelines, and novel food assessment queue positions at EFSA.
Caveats apply where natural gas price volatility, wild harvest weather shocks, or EFSA novel food timeline extensions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Argentina Lime Market