
 Veggie Burger Market | 2026-2036
Veggie Burger Market Size, Share, and Industry Trends Forecast 2026-2036
Veggie Burger Market Outlook
Modular bundling of frozen patties with dedicated sauce sachets and brioche bun pairings is pivoting how households purchase veggie burgers, collapsing the meal-assembly decision into a single basket. Beyond Meat leverages its direct-to-foodservice channel control to anchor premium placement in quick-service restaurant chains. MorningStar Farms sustains retail dominance through broad frozen-aisle distribution and legacy brand recognition. Impossible Foods differentiates via heme-based flavor chemistry that narrows the sensory gap with conventional beef.
A veggie burger comprises a formed, cookable patty manufactured from plant proteins, binders, and lipid systems engineered to replicate the texture, moisture retention, and Maillard browning of ground meat during thermal processing; extrusion and high-moisture extrusion remain the dominant production methods for achieving fibrous, muscle-like mouthfeel. The fresh segment captures expanding refrigerated case space in supermarkets as consumers prioritize shorter ingredient lists and minimal processing. Online retailers represent the fastest-growing distribution channel, though foodservice retains the deepest volume concentration through bulk procurement contracts with institutional buyers. Black bean and quinoa base ingredients command premium positioning, while lentil formulations occupy the value tier in private-label portfolios.
The FDA oversees plant-based protein labeling standards in the United States, while the EU Green Deal and F-Gas Regulation shape agricultural input sustainability requirements for European supply chains. EFSA novel food assessments govern approval timelines for emerging protein sources such as fermented mycoprotein and precision-fermented dairy analogs. Stakeholders must monitor regulatory divergence between jurisdictions on cell-cultured versus plant-based nomenclature, as classification decisions will determine shelf placement, tax treatment, and eligibility for public procurement programs in institutional feeding.
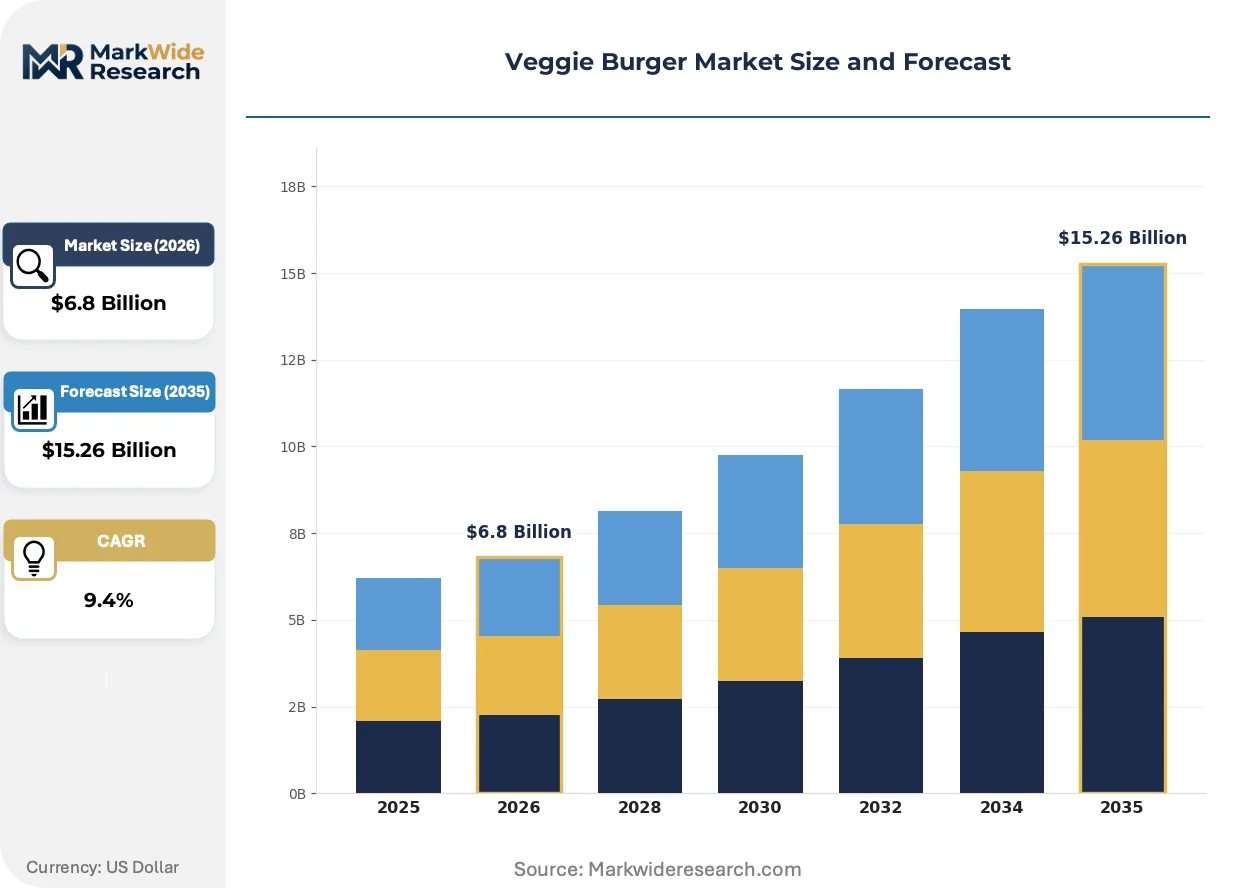
Market Dynamics
High-moisture extrusion technology is collapsing the cost gap between fibrous plant-protein textures and conventional ground meat, forcing capital retooling across mid-tier processors while concentrating production among equipment-scale leaders.
Growth Catalysts
- EU Green Deal agricultural incentives:Carbon-credit frameworks for regenerative pea and fava bean farming are expanding raw-material availability for European extrusion facilities.
- Quick-service restaurant procurement:Bulk supply contracts from institutional foodservice buyers are anchoring volume commitments that justify dedicated plant-protein production lines.
- Pea-protein texturization advances:Novel shear-cell processing is reducing energy inputs by half compared to traditional twin-screw extrusion.
Market Restraints
- Canola oil price volatility:Lipid system costs swing with biofuel diversion demand, compressing margin predictability for value-tier patty formulations.
- Midwest US protein isolate concentration:Three suppliers control over seventy percent of North American pea-protein concentrate capacity, creating single-source vulnerability.
- EFSA novel food timelines:Fermented mycoprotein and precision-fermented fat approvals face eighteen-to-thirty-six-month assessment windows that freeze product pipeline launches.
Strategic Opportunities
- Refrigerated fresh-format penetration:German supermarket chains demonstrate that chilled case placement commands price premiums over frozen alternatives.
- Direct-to-consumer subscription channels:Bundled meal-kit delivery is capturing trial-resistant households bypassing retail frozen-aisle clutter.
- US FDA labeling clarity:Updated protein-content disclosure rules favor products with complete amino-acid profiles, advantaging multi-source formulations.
Industry Challenges
- Extrusion engineering talent scarcity:Few food-science programs train operators in rheology control for high-moisture protein systems, inflating specialist compensation.
- Co-manufacturer qualification timelines:Brand owners face nine-to-fourteen-month audits to secure capacity at certified allergen-free facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veggie Burger Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Fresh, Cooked, Ready-to-Eat Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Foodservice Base Ingredient: Black Bean, Quinoa, Lentil, Chickpea Consumer Segment: Vegetarians, Vegans, Flexitarians, Health-Conscious Consumers |
| Companies Covered | MorningStar Farms, Archer Daniels Midland, Actual Veggies, Glanbia, Ingredion, Beyond Meat, Boca Burger (Kraft Heinz), Roquette Frères, Impossible Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veggie Burger Market Strategic Shifts
Product development priorities are pivoting from taste replication toward clean-label simplicity, with shorter ingredient lists and recognizable whole-food components displacing highly processed isolates in premium positioning.
High-moisture extrusion is rewriting the technical economics of fibrous mouthfeel. Foodservice manufacturers in Germany and the Netherlands are adopting second-generation shear-cell equipment at replacement-cycle pace. This compression of capital requirements per output ton is enabling mid-scale regional processors to challenge legacy frozen-patty suppliers on texture parity.
The F-Gas Regulation is phasing down hydrofluorocarbon use in European freezing and cold-chain infrastructure. Industrial refrigeration retrofits are absorbing capital that might otherwise expand production capacity. Frozen-format suppliers with captive renewable-powered cold storage are securing preferential shelf placement from sustainability-scoring retailers.
Flexitarian households are fragmenting purchase occasions across multiple protein types rather than committing to single-brand loyalty. Grocery retailers in the United Kingdom are responding with modular meal-solution displays that cross-merchandise plant-based patties with artisan buns and condiment sachets. This basket-building strategy captures higher ring values than isolated frozen-aisle placement.
Veggie Burger Market Segmentation
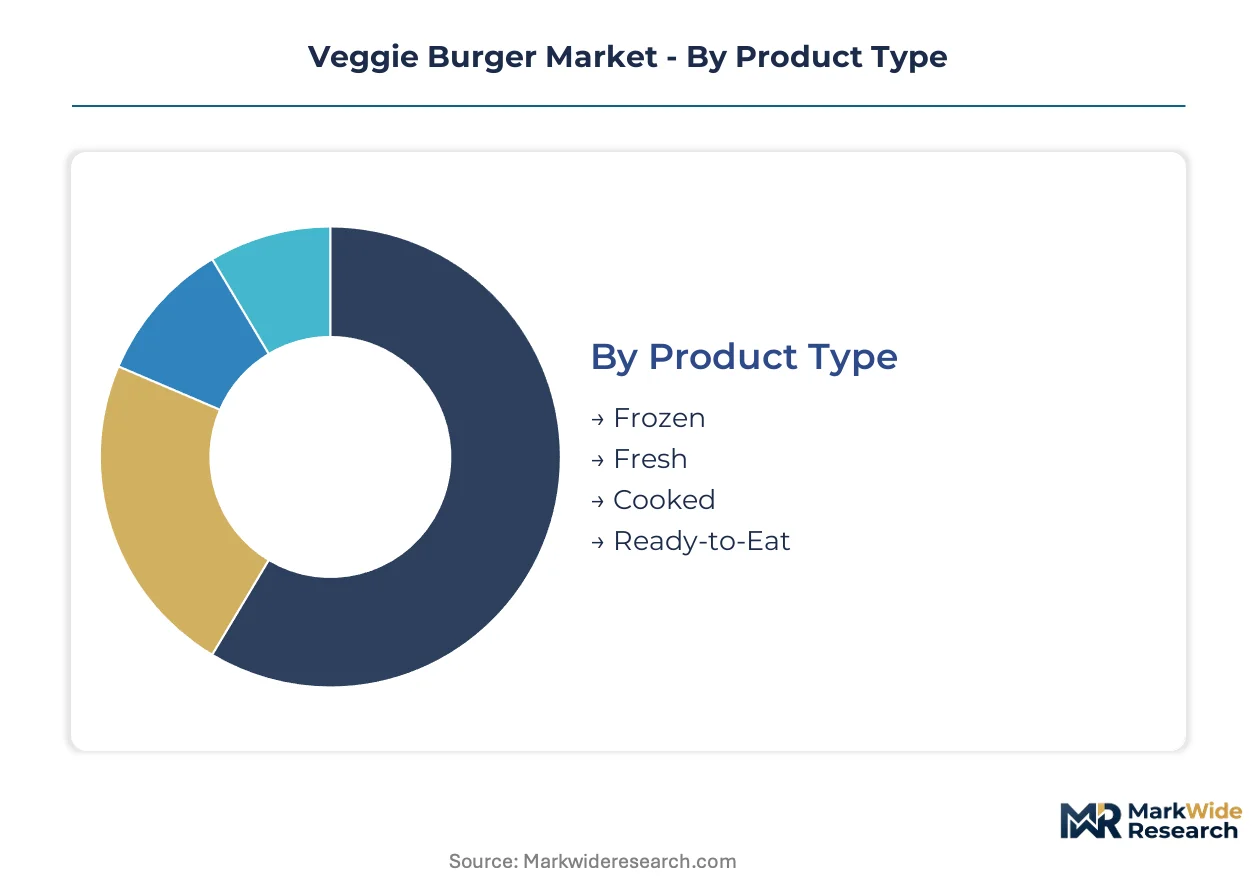
Segmentation in the veggie burger market reveals how formulation choices, temperature state, and purchase context reshape margin structures and brand positioning. Each axis carries distinct technical requirements and regulatory exposure that determine competitive viability.
Product Type:
Thermal stability and moisture retention specifications define manufacturing investment and shelf-life economics across format categories.
- Frozen:Blast-frozen patties formulated for six-to-twelve-month stability dominate volume throughput in North American retail. Quick-service restaurant procurement contracts anchor production scale for extruded-fiber formats with Maillard-reactive surfaces.
- Fresh:Refrigerated patties with fourteen-to-twenty-one-day shelf life command price premiums in German supermarket chains where clean-label ingredient lists drive household penetration. Shorter distribution radii from production sites constrain geographic expansion.
- Cooked:Pre-grilled or pan-seared patties packaged under modified atmosphere reduce home-preparation friction for time-constrained households. Foodservice grab-and-go programs in UK convenience retail represent primary offtake.
- Ready-to-Eat:Fully assembled sandwiches or meal kits with integrated condiment sachets collapse decision friction for trial-resistant consumers. Direct-to-consumer subscription channels capture this segment's steepest expansion trajectory.
Mature deployment sits with frozen formats. Newer deployment is concentrated in fresh refrigerated cases.
Distribution Channel:
Channel selection determines margin capture, temperature infrastructure requirements, and exposure to private-label competition.
- Supermarkets:Refrigerated case placement in German chains demonstrates premium pricing power over frozen-aisle alternatives. Shelf-space negotiations favor multi-SKU suppliers with dedicated plant-protein production lines.
- Convenience Stores:Grab-and-go cooked patties target urban commuters with limited meal-preparation time. UK retailers cross-merchandise with artisan buns to build basket value.
- Online Retailers:Frozen-format subscription boxes bypass retail clutter for flexitarian households. Cold-chain logistics investments and renewable-powered warehousing secure sustainability-scoring placement.
- Foodservice:Bulk procurement contracts with institutional buyers anchor volume concentration. Dedicated allergen-free co-manufacturer capacity requires nine-to-fourteen-month qualification timelines.
Volume gravity centers on foodservice procurement. Margin expansion is climbing the fastest in online subscription channels.
Base Ingredient:
Protein source selection governs amino-acid completeness, allergen labeling, and agricultural input sustainability credentials.
- Black Bean:Whole-bean formulations with visible particulate texture signal minimal processing to clean-label seekers. Premium positioning in US natural-channel retail reflects shorter ingredient declarations.
- Quinoa:Complete protein profile satisfies FDA disclosure rules favoring multi-source amino-acid compositions. Andean supply chains face climate volatility affecting concentrate availability.
- Lentil:Cost-efficient formulations occupy value-tier positioning in European private-label portfolios. EU Green Deal carbon-credit frameworks for regenerative farming expand raw-material access.
- Chickpea:Neutral flavor base accommodates diverse seasoning profiles across Mediterranean and Middle Eastern product lines. EFSA novel food assessments for fermented protein variants extend pipeline timelines.
Commercial maturity clusters around black bean and lentil formulations. Emerging deployment is concentrating in quinoa-based complete-protein systems.
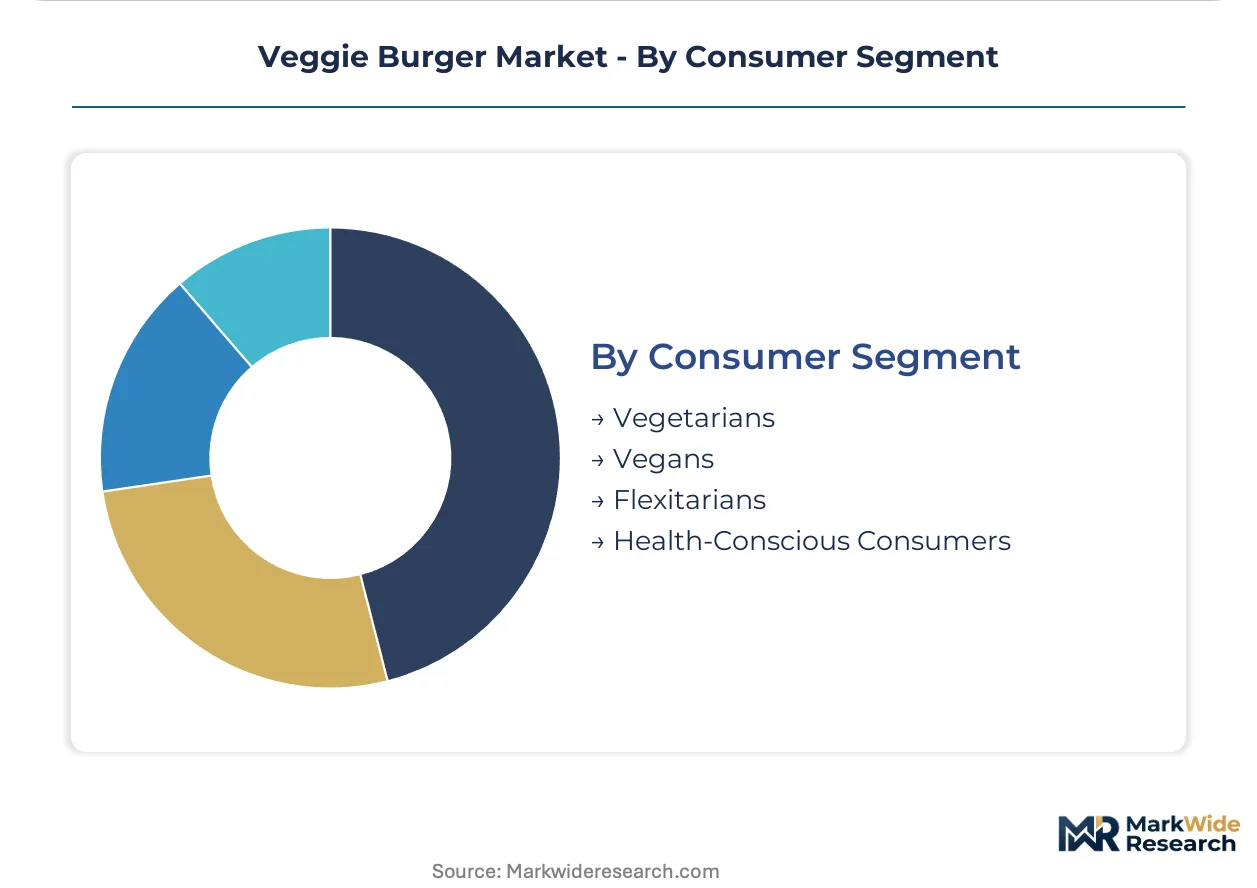
Consumer Segment:
Dietary identity and health motivation determine price sensitivity, trial willingness, and brand loyalty patterns.
- Vegetarians:Longstanding meat-avoidance drives consistent purchase frequency but lower per-occasion spending than emerging segments. Loyalty concentrates with legacy frozen-aisle brands.
- Vegans:Strict exclusion criteria demand certified allergen-free production facilities and absence of cross-contamination risk. Nine-to-fourteen-month co-manufacturer audits create supply bottlenecks.
- Flexitarians:Protein-type fragmentation across multiple purchase occasions reduces single-brand commitment. German and UK retailers respond with modular meal-solution displays.
- Health-Conscious Consumers:Shorter ingredient lists and recognizable whole-food components displace highly processed isolates in premium positioning. Pea-protein texturization advances enable sensory parity with conventional beef.
Established demand resides with vegetarian households. Fastest share gains are materializing among flexitarian protein-agnostic purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the Netherlands and Belgium concentrate European extrusion equipment manufacturing, drawing pea-protein processors seeking tariff-advantaged supply chain nodes.
Germany
Refrigerated fresh-format patties command supermarket price premiums unmatched elsewhere in Europe. EU Green Deal carbon-credit frameworks subsidize regenerative fava bean farming in Lower Saxony. Berlin-Brandenburg hosts shear-cell equipment R&D clusters advancing second-generation extrusion technology.
United States
Quick-service restaurant procurement contracts anchor North American volume concentration. FDA updated protein-content disclosure rules favor multi-source amino-acid formulations. Midwest protein isolate suppliers in Minnesota and North Dakota face single-source vulnerability scrutiny from brand owners.
United Kingdom
Flexitarian households fragment purchases across multiple protein types, reducing brand loyalty. F-Gas Regulation compliance costs absorb capital that might expand frozen-format production capacity. London and Southeast England retailers pioneer modular meal-solution displays cross-merchandising patties with artisan buns.
Netherlands
Shear-cell processing equipment manufacturers cluster near Eindhoven, reducing energy inputs versus traditional extrusion. REACH chemical safety standards govern binder and lipid additive approvals. Rotterdam's port infrastructure handles bulk pea-protein concentrate imports for European extrusion facilities.
Canada
Prairie Provinces pea farming expands under federal agricultural diversification programs. Health Canada novel food assessments parallel FDA timelines for fermented protein ingredients. Ontario and Quebec foodservice distributors negotiate bulk procurement contracts with institutional buyers.
Veggie Burger Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation, distribution, and temperature-state segments. The vendor base separates into three strategic archetypes: legacy frozen-aisle brands with broad retail penetration, technology-driven startups with proprietary extrusion or flavor chemistry, and ingredient suppliers backward integrated into finished patty production. Competitive moves concentrate on co-manufacturer capacity qualification and refrigerated case space negotiation with supermarket chains.
Among pure-play plant-protein specialists, Beyond Meat and Impossible Foods exemplify technology-differentiated positioning, while MorningStar Farms anchors legacy frozen-aisle dominance through distribution scale. Ingredient suppliers such as Roquette Frères occupy upstream control positions supplying pea-protein concentrates to finished goods manufacturers.
| Leading Market Players |
|---|
| MorningStar Farms |
| Archer Daniels Midland |
| Actual Veggies |
| Glanbia |
| Ingredion |
| Beyond Meat |
| Boca Burger (Kraft Heinz) |
| Roquette Frères |
| Impossible Foods |
| Others |
Value Chain & Pricing Dynamics
Captive pea-protein concentrate production in Minnesota and North Dakota anchors both supply security and pricing power for North American finished-goods manufacturers, while European extrusion facilities draw tariff-advantaged supply chain positioning from Netherlands-Belgium free-trade zones.
Pricing Analysis
Short lead-time premiums for fresh refrigerated patties versus frozen spot inventory discounts define the dominant pricing structure across German and US retail channels. Three-tier pricing structure across premium fresh-format, standard frozen, and economy private-label tiers separates clean-label positioning from commodity volume plays. Cost compression in value-tier lentil formulations is intensifying because canola oil price volatility feeds into lipid system expenses. Flexitarian households in UK modular meal-solution displays show least price sensitivity, while institutional foodservice buyers negotiating bulk procurement contracts exhibit highest elasticity.
Supply Chain Analysis
Nine-to-fourteen-month co-manufacturer qualification timelines for certified allergen-free facilities gate capacity access and concentrate production among pre-qualified processors. Geographic supply concentration clusters in the United States, Germany, and the Netherlands, with shear-cell equipment R&D in Berlin-Brandenburg and Eindhoven reducing energy inputs versus traditional extrusion. Raw material dependencies center on pea-protein concentrates, canola-derived lipid systems, and regenerative fava bean inputs under EU Green Deal frameworks. Single-source vulnerability from three Midwest US suppliers controlling over seventy percent of North American pea-protein concentrate capacity represents the dominant structural risk. Distribution runs through foodservice bulk contracts anchoring volume, with online subscription channels capturing fastest margin expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive pea-protein concentrate production has become the decisive upstream lever as Midwest supply concentration exposes brand owners to single-source vulnerability and input cost volatility.
For Market Incumbents: Anticipate shear-cell equipment replacement cycles in Germany and the Netherlands by securing second-generation extrusion capacity before regional processors achieve texture parity. Defend refrigerated case positioning in German supermarket chains through exclusive shelf-space negotiations that lock out emerging fresh-format competitors. Prioritize nine-to-fourteen-month co-manufacturer audit completion to secure allergen-free capacity ahead of vegan segment demand inflection.
For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the lowest customer-acquisition friction for trial-resistant flexitarian households bypassing retail frozen-aisle clutter. Target UK modular meal-solution displays where cross-merchandising with artisan buns builds basket value without requiring legacy frozen-aisle slotting fees. Penetrate German fresh-format refrigerated cases through clean-label whole-bean formulations signaling minimal processing to health-conscious consumers.
For Investors and Strategic Acquirers: Exit pathways concentrate in technology-differentiated pure-plays with proprietary extrusion or heme-based flavor chemistry assets rather than undifferentiated private-label manufacturers. Long-term viability over the next decade hinges on securing positions in shear-cell equipment scale or multi-source amino-acid formulation IP. Watch for FDA labeling clarity on protein-content disclosure rules as the inflection signal advantaging complete-protein quinoa and pea formulations over single-source isolates.
| Strategic Initiative | Industry Significance |
|---|---|
| Shear-Cell Equipment Scale-Up | Second-generation extrusion in Germany and Netherlands halves energy inputs versus traditional twin-screw systems. |
| Refrigerated Fresh-Format Expansion | German supermarket chains demonstrate chilled case placement commands sustained price premiums over frozen alternatives. |
| Direct-to-Consumer Channel Launch | Subscription meal-kit delivery captures trial-resistant flexitarian households avoiding retail frozen-aisle congestion. |
| Co-Manufacturer Qualification Acceleration | Nine-to-fourteen-month allergen-free facility audits create bottlenecks for vegan-certified production capacity. |
| Multi-Source Protein Formulation Investment | FDA updated disclosure rules favor complete amino-acid profiles advantaging quinoa and blended isolates. |
Study Parameters
Independent corroboration across extrusion equipment manufacturers, pea-protein concentrate suppliers, and quick-service restaurant procurement directors underwrites the qualitative findings in this study. Primary interviews with plant-protein R&D heads, supermarket category buyers, foodservice distribution executives, and co-manufacturer operations managers combined with secondary validation from FDA guidance documents, EFSA novel food assessment records, EU Green Deal agricultural incentive filings, and trade customs data on pea-protein concentrate flows. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Comparable historical reference periods spanning pre-pandemic baseline through post-regulatory-shift intervals anchored the forecast window across the analysis window. The analytical framework modeled segmentation across product type, distribution channel, base ingredient, and consumer dietary identity dimensions. CAGRs derived from fitted growth curves incorporating pea-protein texturization technology adoption rates, flexitarian household penetration patterns, and refrigerated case space expansion trajectories in German and UK retail.
The model holds under stable EU Green Deal agricultural incentive continuity and FDA labeling guidance permanence; deviation in EFSA novel food assessment timelines or Midwest pea-protein supply disruption would shift volume and value trajectories. Forecasts reflect assumptions on shear-cell equipment adoption curves and flexitarian purchase-occasion fragmentation. A model refresh is warranted upon material change in F-Gas Regulation compliance costs affecting European cold-chain infrastructure investment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Vegan Food Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Plant-Based Butter Market
Plant Based Food
Plant-Based Margarine Market