
 Walnut-Based Spreads Market | 2026-2036
Walnut-Based Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Walnut-Based Spreads Market Analytics
California's walnut processing corridor is reconfiguring capacity toward value-added spread production. Artisana Organics leverages certified organic sourcing to anchor premium positioning across North American natural food channels. Meridian Foods sustains private-label manufacturing scale that competes on cost with conventional nut butter alternatives. Crazy Go Nuts LLC differentiates through roasted walnut formulations that occupy specialty retail shelf space.
Walnut-based spreads consist of ground walnut kernels emulsified with oils and stabilizers to achieve spreadable consistency, typically containing 85-95% walnut content by weight and serving as functional alternatives to peanut butter in allergen-sensitive applications. Organic Spread commands margin concentration through certification premiums, while Chocolate Spread segments attract household purchasers seeking indulgence-positioned alternatives. Health Food Store channels lead distribution value capture, though Online Retail is expanding fastest among direct-to-consumer subscription models targeting specialty diet adherents.
FDA food labeling requirements and USDA organic certification standards govern ingredient disclosure and production claims across the United States, while EFSA nutrition and health claims regulation shapes permissible marketing language in European markets. The EU Deforestation Regulation imposes traceability burdens on walnut sourcing that filter through to finished spread compliance costs. Stakeholders must monitor evolving allergen threshold policies and clean-label certification fragmentation to preserve market access across diverging regulatory environments.
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandates are compressing procurement timelines for walnut-based spread manufacturers, forcing upstream traceability investments that reshape competitive cost structures across organic and conventional product tiers.
Growth Catalysts
- Clean-label certification premiums:USDA organic and EU organic seals command shelf space allocation in North American and European health food channels, pulling formulation investment toward additive-free recipes.
- Allergen-sensitive institutional procurement:K-12 school nutrition programs and corporate cafeteria operators are expanding walnut spread adoption as peanut-free zone compliance intensifies across the United States.
- Bakery menu integration:Artisan bread producers in Germany and France are developing walnut spread pairings that elevate positioning in premium retail and foodservice segments.
Market Restraints
- Walnut input cost volatility:California drought cycles and Central Asian supply disruptions create raw material price instability that compresses margin predictability for spread manufacturers.
- Single-origin sourcing concentration:Dependence on California's Central Valley for bulk kernel supply exposes processors to climate-induced yield shocks and water rights litigation.
- Technical shelf-life limitations:High polyunsaturated fat content in walnut oil accelerates rancidity compared to peanut or almond alternatives, constraining ambient distribution reach.
Strategic Opportunities
- Underpenetrated South Korean functional food channel:Seoul-based wellness retailers are expanding nut butter assortments, creating first-mover positioning for walnut spreads with cognitive health positioning.
- EU Deforestation Regulation traceability infrastructure:Early compliance investments unlock preferential supplier status with EU-based private-label buyers facing 2025 due diligence deadlines.
- Direct-to-consumer subscription models:Online retail platforms enable recurring revenue capture among specialty diet adherents seeking customizable flavor and texture profiles.
Industry Challenges
- Clean-label formulation expertise scarcity:Food technologists capable of stabilizing high-oil emulsions without synthetic additives command premium compensation that strains mid-tier manufacturer budgets.
- Organic certification timeline compression:USDA organic and EU organic conversion periods for new walnut orchards create multi-year supply gaps that outpace demand growth in premium segments.
- Legacy equipment reconfiguration costs:Conventional nut butter processing lines require capital-intensive modification to handle walnut's softer kernel structure and higher oil migration rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walnut-Based Spreads Market |
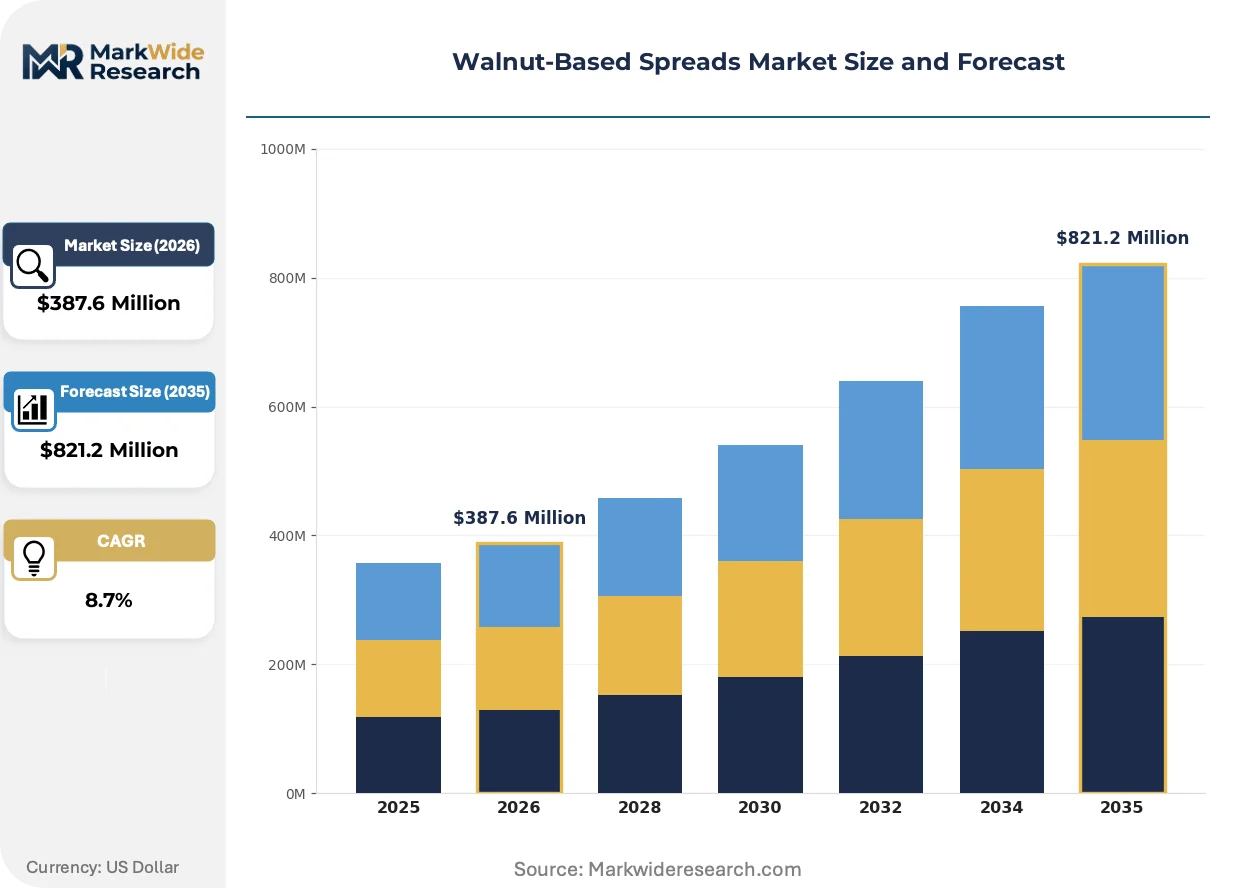
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Spread, Chocolate Spread, Flavored Spread, Creamy Spread Form: Jar, Tub, Pouch, Squeeze Bottle Distribution Channel: Online Retail, Supermarket, Specialty Store, Health Food Store End User: Households, Foodservice, Bakeries, Cafes |
| Companies Covered | Artisana Organics, The Nutty Gourmet Inc, Walnutter, Nutcessity Ltd, Crazy Go Nuts LLC, Nuts 'N More, Meridian Foods, Nut Butter International, Manna Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walnut-Based Spreads Market Evolving Landscape
Digital traceability infrastructure is penetrating walnut-based spread supply chains, compressing verification timelines while enabling real-time compliance documentation for deforestation-free sourcing mandates.
Blockchain-enabled provenance tracking is digitizing kernel-to-jar documentation for EU-bound shipments, allowing German and French importers to satisfy EUDR due diligence requirements with automated audit trails. Large organic distributors are adopting these systems fastest, pressuring mid-tier suppliers to absorb platform subscription costs or lose shelf access. The technology is digitizing procurement risk assessment, shifting supplier selection criteria toward data interoperability rather than price alone.
EFSA nutrition and health claims regulation is tightening permissible marketing language for walnut spreads positioned as cardiovascular or cognitive function aids, forcing reformulation toward compositional thresholds that qualify for approved claims. Manufacturers targeting European households must now anchor messaging on verifiable nutrient profiles rather than general wellness positioning. Organic Spread segments face the steepest compliance burden, as premium pricing depends on differentiated health narratives that regulatory scrutiny now constrains.
Health food store buyers are consolidating supplier relationships around vertically integrated producers capable of delivering simultaneous organic certification, allergen-free production lines, and private-label co-packing services. This procurement compression displaces fragmented vendor bases that previously served regional natural food cooperatives. California-based processors with captive orchard operations and in-house roasting capacity are capturing disproportionate shelf space expansion in this channel.
Walnut-Based Spreads Market Segmentation
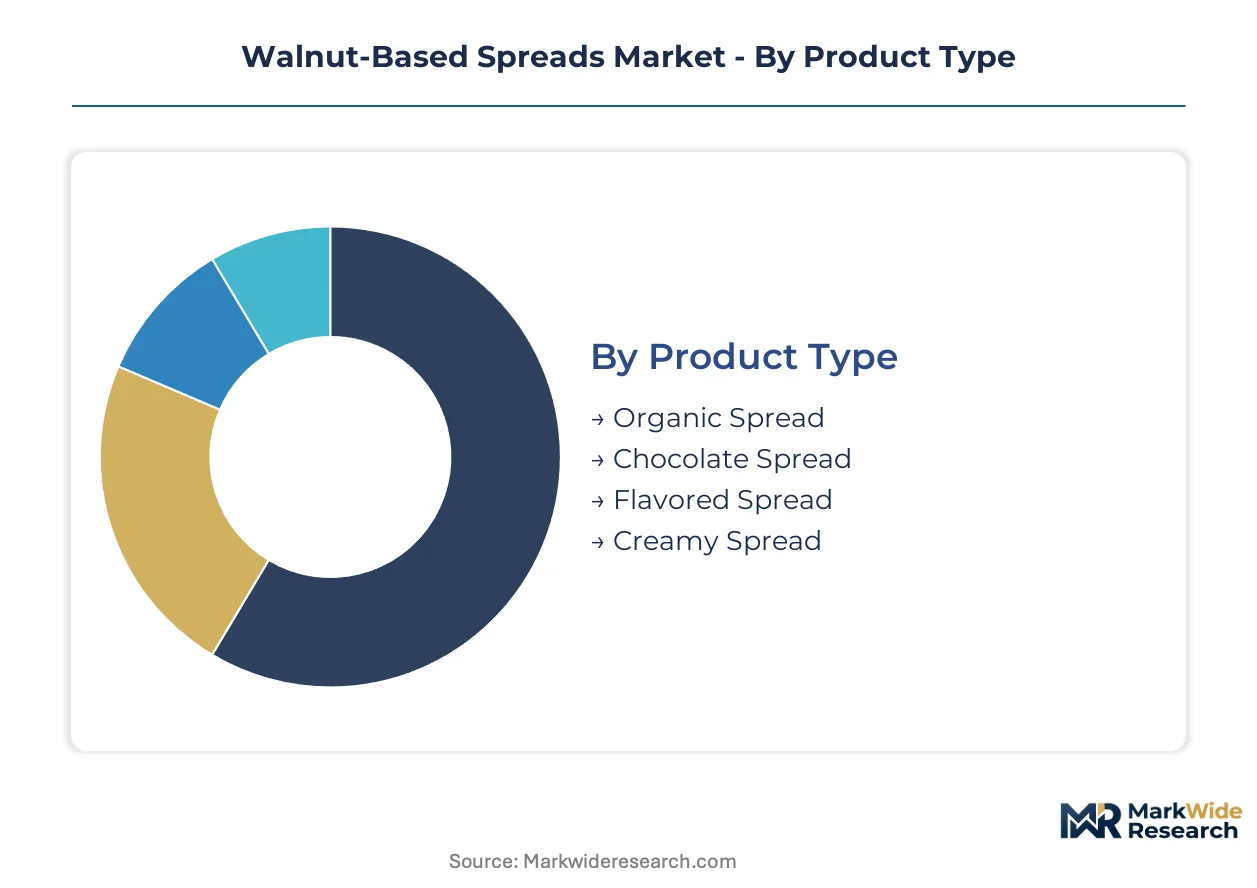
Walnut-based spreads segment across formulation sophistication, packaging convenience, channel accessibility, and end-use application intensity. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Mature organic certification tiers coexist with emerging indulgence-positioned formats in this category.
- Organic Spread:USDA and EU organic seals command certification premiums across North American natural food channels and German health food distribution networks. Clean-label formulation requirements intensify procurement scrutiny toward deforestation-free kernel sourcing under EU Green Deal mandates.
- Chocolate Spread:Cocoa-walnut emulsions target household purchasers seeking allergen-friendly indulgence alternatives to hazelnut-based competitors. German and French artisan bakery pairings are elevating positioning in premium retail segments.
- Flavored Spread:Cinnamon, vanilla, and maple variants occupy specialty retail shelf space with seasonal rotation strategies.
- Creamy Spread:Ultra-smooth milling profiles compete for peanut butter displacement in K-12 institutional procurement.
Organic Spread retains volume leadership; Chocolate Spread holds the steepest expansion curve.
Form:
Cost tier stratification separates premium glass packaging from economy flexible formats in this dimension.
- Jar:Standard glass containers dominate health food store shelves with resealability and premium aesthetic signaling. California-based processors with captive orchard operations favor this format for organic line extensions targeting natural food cooperatives.
- Tub:Wide-mouth plastic containers serve foodservice bulk procurement and bakery ingredient staging with portion-control efficiency.
- Pouch:Lightweight flexible packaging reduces freight costs for direct-to-consumer subscription models and outdoor recreation channels.
- Squeeze Bottle:Controlled-dispense formats target household convenience seekers and institutional cafeteria lines with reduced cross-contamination risk.
Jar formats retain volume leadership; Pouch configurations gain share fastest among online retail subscription channels.
Distribution Channel:
Customer type concentration varies sharply between transaction-focused mass retail and relationship-driven specialty channels.
- Online Retail:Direct-to-consumer platforms enable recurring revenue capture among specialty diet adherents seeking customizable flavor profiles. Subscription models are compressing customer acquisition costs while building defensible loyalty among allergen-sensitive households.
- Supermarket:Conventional grocery shelf space requires slotting fee investments that favor private-label manufacturers with Meridian Foods-scale production economics.
- Specialty Store:Curated assortments in Seoul-based wellness retailers and European organic chains reward provenance storytelling and blockchain-enabled traceability documentation.
- Health Food Store:Vertically integrated producers with simultaneous organic certification and allergen-free production lines capture disproportionate shelf space expansion in this channel.
Health Food Store channels retain value capture leadership; Online Retail climbs the fastest among direct-to-consumer models.
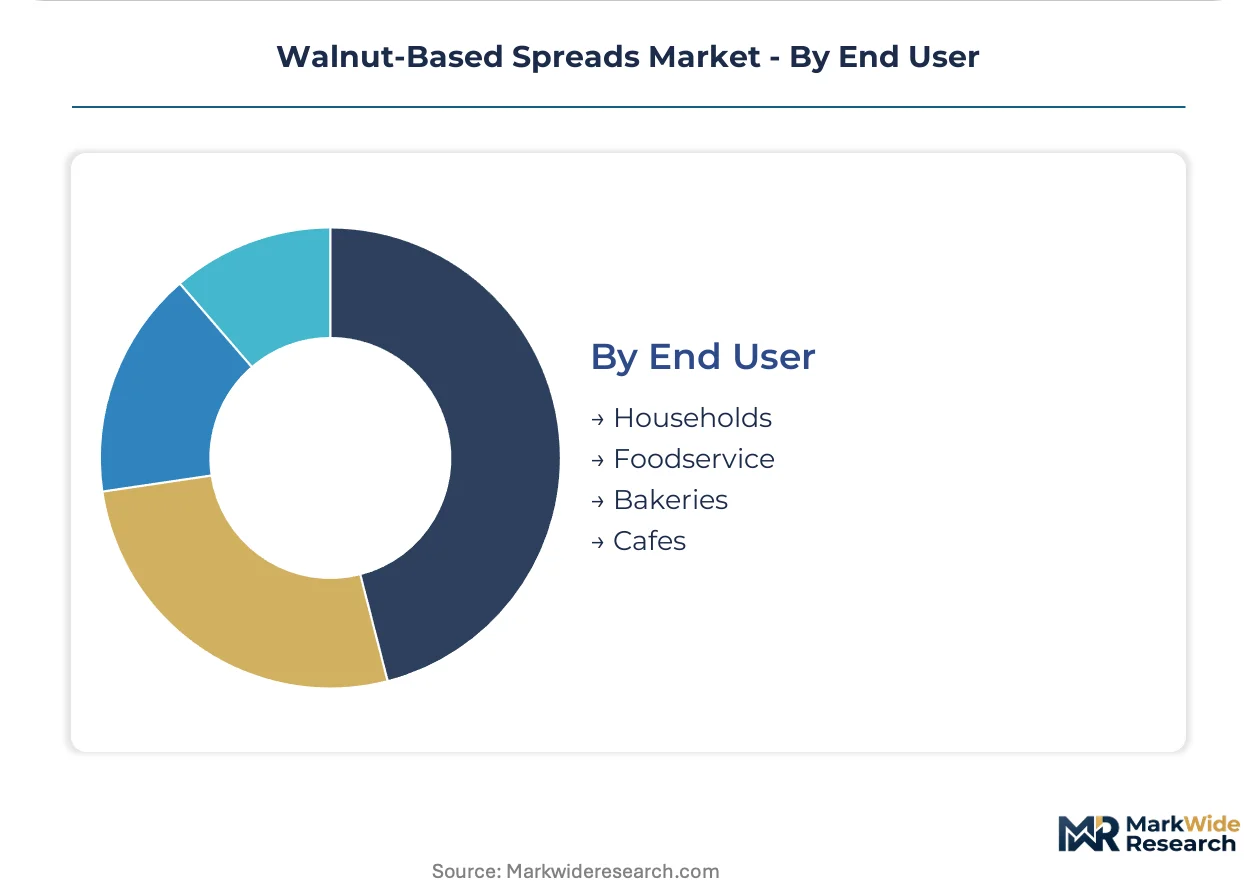
End User:
Application intensity separates high-volume ingredient buyers from discretionary household purchasers.
- Households:Retail-packaged consumption drives recurring purchase cycles with brand loyalty formation around allergen safety and clean-label positioning. German and French households demonstrate premium willingness-to-pay for organic certification seals.
- Foodservice:Institutional cafeteria operators expand walnut spread adoption as peanut-free zone compliance intensifies across United States K-12 nutrition programs.
- Bakeries:Artisan bread producers in Germany develop walnut spread pairings that elevate premium retail positioning.
- Cafes:Menu integration accelerates as clean-label ingredient sourcing intensifies across European coffeehouse chains.
Households retain volume leadership; Foodservice applications demonstrate the steepest procurement expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household consumption in Germany favors organic-certified spreads for breakfast applications, while South Korean demand clusters around functional positioning for cognitive health. The United States splits between institutional peanut-free procurement and premium natural food retail. France and Australia demonstrate divergent channel mixes, with French bakery integration and Australian outdoor recreation pouches.
United States
K-12 school nutrition programs and corporate cafeteria operators drive institutional procurement of allergen-free alternatives. FDA food labeling requirements and USDA organic certification standards govern ingredient disclosure and production claims. California's Central Valley processing corridor reconfigures capacity toward value-added spread production with captive orchard operations.
Germany
Artisan bread producers and health food distribution channels concentrate demand for premium organic positioning. EU Green Deal deforestation-free supply chain mandates reshape procurement standards through EUDR due diligence requirements. The food manufacturing cluster in Baden-Württemberg anchors specialized organic walnut spread distribution.
France
Bakery menu integration and household indulgence positioning elevate chocolate-walnut emulsion formats. EFSA nutrition and health claims regulation constrains permissible marketing language for cardiovascular positioning. Paris-based artisan retail channels reward blockchain-enabled traceability documentation from vertically integrated suppliers.
South Korea
Seoul-based wellness retailers expand nut butter assortments for cognitive health-seeking consumers. The country's national food safety regulator enforces strict import documentation for tree nut products. The Seoul Capital Area concentrates functional food channel development for first-mover walnut spread positioning.
Australia
Outdoor recreation and direct-to-consumer subscription channels favor lightweight pouch formats for portability. The country's national food standards code governs allergen labeling and organic certification equivalence. Sydney and Melbourne health food retail clusters drive demand for clean-label certified alternatives.
Walnut-Based Spreads Market Competitive Landscape
Capability concentration sits with vertically integrated orchard-processor hybrids; scale advantage sits with private-label contract manufacturers. The vendor base stratifies across three tiers: premium organic specialists with captive sourcing, mid-tier private-label producers with co-packing flexibility, and niche flavor innovators with limited distribution. Strategic moves center on backward integration into walnut cultivation and EUDR compliance infrastructure investment.
Within the premium organic tier, Artisana Organics exemplifies certification-anchored positioning across North American natural food channels. Meridian Foods occupies the private-label manufacturing archetype with scale economics competing against conventional nut butter alternatives. Crazy Go Nuts LLC represents specialty retail differentiation through roasted formulation profiles.
| Leading Market Players |
|---|
| Artisana Organics |
| The Nutty Gourmet Inc |
| Walnutter |
| Nutcessity Ltd |
| Crazy Go Nuts LLC |
| Nuts 'N More |
| Meridian Foods |
| Nut Butter International |
| Manna Organics |
| Others |
Value Network & Pricing Analysis
California's Central Valley freight corridor carries kernel shipments to processing facilities where supply concentration among captive orchard operators amplifies pricing power for organic-certified output while compressing margins for conventional spot purchasers.
Pricing Analysis
Long-term offtake contracts between California processors and German health food distributors anchor premium organic pricing, while spot market transactions for conventional kernels expose smaller manufacturers to drought-induced volatility. Certification grade and volume scale separate premium USDA organic seals from economy private-label positioning. Cost compression in mid-tier conventional spreads intensifies as Meridian Foods-scale producers leverage co-packing scale. Institutional K-12 buyers demonstrate highest price sensitivity; Seoul-based wellness retailers show lowest.
Supply Chain Analysis
The EU Deforestation Regulation's traceability mandates restrict kernel flows from non-compliant Central Asian origins, forcing procurement shifts toward documented California and French sources. Walnut kernel supply draws from California, Chile, and Uzbekistan with organic conversion creating multi-year availability gaps. Single-source vulnerability concentrates in California's drought-exposed Central Valley. Distribution runs through health food store channels with online retail subscription models expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated health food store chains that vertically integrate procurement around simultaneous organic certification and allergen-free production capabilities.
For Market Incumbents: Entrench defensible positioning through backward integration into captive walnut cultivation and EUDR-compliant traceability infrastructure. Artisana Organics exemplifies certification-anchored channel control that emerging private-label competitors cannot replicate. Climate-induced yield volatility in California represents the primary margin threat requiring diversified sourcing geography. For New Entrants and Emerging Players: Establish a beachhead in Seoul's functional food channel where cognitive health positioning remains underdeveloped for walnut spreads. South Korean import documentation complexity deters incumbent resource allocation. Direct-to-consumer subscription models offer lowest customer acquisition friction for allergen-sensitive household penetration. For Investors and Strategic Acquirers: Orchard-processor hybrids with in-house roasting capacity and blockchain-enabled provenance systems represent the most defensible acquisition archetype. Long-term viability hinges on EUDR compliance infrastructure amortization across premium European private-label contracts. Watch for EU Green Deal enforcement intensity as inflection indicator for traceability premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Captive kernel supply secures margin control against California drought cycles and EUDR traceability mandates. |
| Blockchain-Enabled Provenance Implementation | Automated audit trails satisfy German and French importer due diligence requirements under EU Deforestation Regulation. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture among allergen-sensitive households reduces slotting fee dependence in conventional retail. |
| Clean-Label Formulation R&D Investment | Additive-free emulsion stabilization addresses health food store buyer consolidation around certification-anchored suppliers. |
| South Korean Market Entry Partnership | Seoul-based wellness retailer relationships unlock first-mover positioning in cognitive health-functional nut butter positioning. |
Research Methodology
Initial hypotheses were tested against primary input from walnut processing plant managers, health food store category buyers, organic certification auditors, and European import compliance specialists and refined through secondary validation against USDA organic certification databases, EU Deforestation Regulation implementation guidance, FDA food labeling guidance documents, and California agricultural production statistics. Bottom-up volume modeling triangulated against top-down category expenditure analysis.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, distribution channel, end-use application, and regional regulatory cluster. CAGRs were derived from iterative reconciliation of historical growth patterns with forward-looking procurement expansion indicators. Forecast inputs incorporated organic orchard conversion timelines, EUDR compliance cost pass-through assumptions, and K-12 institutional procurement policy trajectories.
Sensitivities concentrate around California drought severity, EU Green Deal enforcement intensity, and organic certification supply gap duration. Cross-checking against USDA National Agricultural Statistics Service walnut production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
Pecans Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Strawberry Seed Oil Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Global Peanut Meal Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Bambara Beans Market