
 Asia-Pacific Low Fat Sausage Market | 2026-2036
Asia-Pacific Low Fat Sausage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Low Fat Sausage Market Insights
Australian pork processing capacity is restructuring as regional producers adapt to lean-meat specifications demanded by export buyers. NH Foods Ltd. leverages integrated cold-chain infrastructure across Japan and Southeast Asia to maintain freshness standards for reduced-fat formulations. WH Group Limited anchors volume through its vertically controlled hog farming and slaughtering operations in China. Venkys (India) Limited competes in poultry-based low-fat variants, capitalizing on India's expanding quick-service restaurant networks.
Asia-Pacific low fat sausage denotes emulsified or coarsely ground meat products containing substantially reduced lipid content, typically achieved through mechanical separation, lean-trim selection, or fat-replacer incorporation such as dietary fiber or modified starch, manufactured for shelf-stable or chilled distribution. The product serves retail and food service buyers seeking protein options aligned with cardiovascular health guidance. Pork-based formulations dominate current volume given established processing infrastructure and consumer familiarity across East Asian markets. Chicken and turkey segments represent faster-expanding categories as white-meat preference strengthens in India, Southeast Asia, and younger Chinese demographics. Food service applications command margin concentration due to contract-based procurement and specification-driven volume commitments from chain operators.
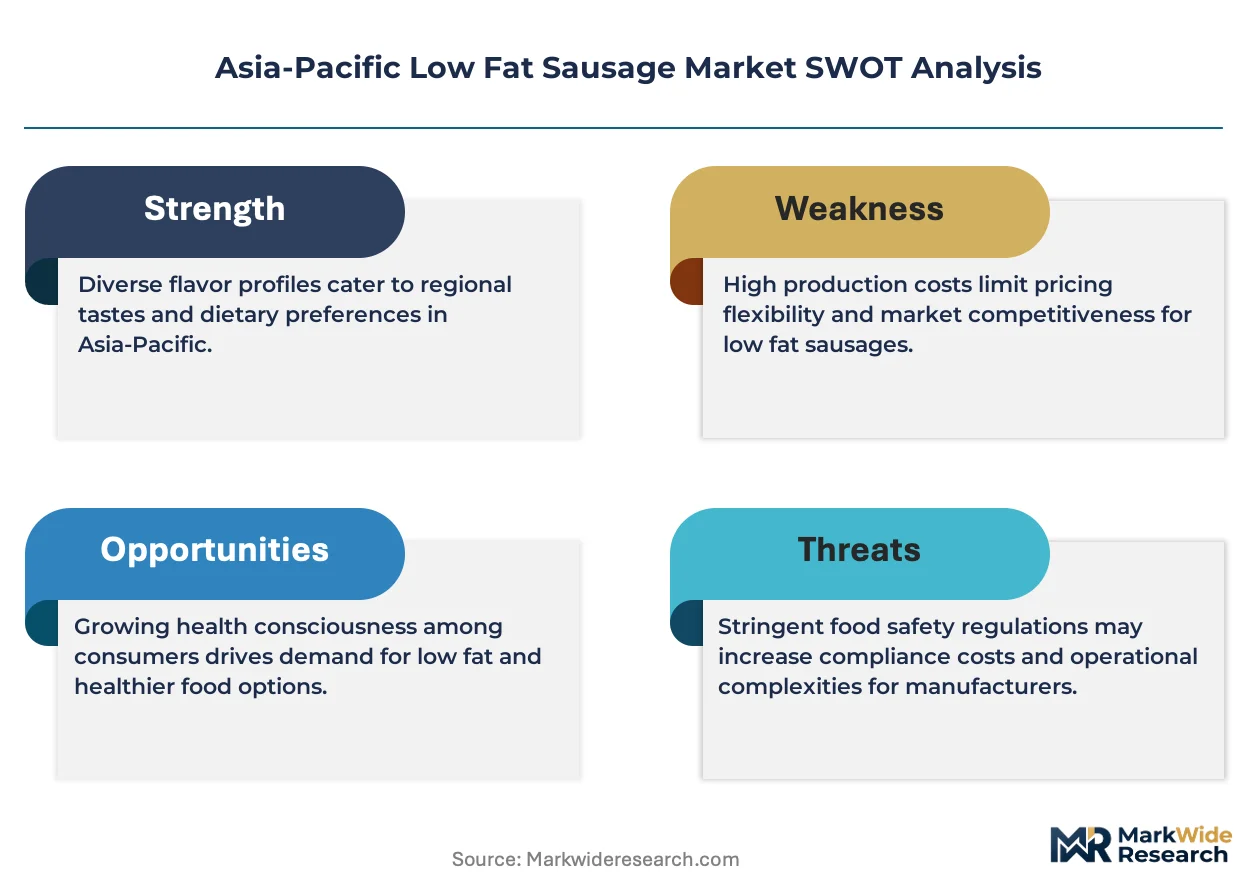
Japan's Ministry of Health, Labour and Welfare enforces strict labeling for processed meat fat content under Food Sanitation Act provisions, while China's SAMR administers national food safety standards GB 2726 for cooked meat products including maximum fat thresholds. Australia's FSANZ mandates nutrition panel disclosure that shapes retailer assortment decisions. Stakeholders must monitor evolving clean-label enforcement and alternative protein competition as determinants of formulation investment priorities.
Market Dynamics
China's SAMR enforcement of GB 2726 fat-content thresholds is compressing formulation margins while forcing processor consolidation across East Asian markets. This regulatory pressure is reshaping competitive positioning as smaller abattoirs exit and integrated operators capture contract volumes from premium retail chains.
Growth Catalysts
- Clean-label mandates:Japan's METI-led disclosure initiatives are accelerating retailer assortment shifts toward reduced-fat processed meat portfolios. Supermarket buyers now specify maximum lipid thresholds in procurement contracts.
- Quick-service restaurant expansion:India's QSR networks are standardizing poultry-based low-fat sausage specifications across franchise locations. This creates specification-driven demand for white-meat processors.
- Mechanical separation technology:Advanced lean-recovery systems are enabling cost-competitive fat reduction without texture degradation. Food service operators are adopting these formulations for menu reformulation.
Market Restraints
- Feed grain volatility:Corn and soybean meal price swings directly compress hog farming margins. WH Group's captive breeding operations partially buffer this exposure.
- Cold-chain infrastructure gaps:Southeast Asian markets outside Thailand and Vietnam lack consistent chilled distribution. Shelf-stable formulations dominate despite inferior texture profiles.
- Alternative protein substitution:Plant-based sausage analogs from domestic startups are capturing trial purchases in urban Chinese premium retail. Taste-price gaps remain the limiting factor.
Strategic Opportunities
- Indonesia's underpenetrated modern trade:Convenience store chains in Jakarta and Surabaya are expanding refrigerated sections. Local poultry processors can secure first-mover positioning before multinational entry.
- E-commerce direct-to-consumer channels:Freshippo and JD Fresh are building private-label low-fat sausage portfolios. Platform data enables rapid flavor iteration against regional preference maps.
- Australia-ASEAN trade integration:Reduced tariff schedules under RCEP implementation are opening chilled pork export pathways. Queensland processors can leverage FSANZ certification for premium positioning.
Industry Challenges
- Reformulation talent scarcity:Food technologists skilled in fat-replacer integration (dietary fiber, modified starch) command premium compensation. Universities in China and India lag in applied meat science curricula.
- Dual certification timelines:Exporters seeking Japan PMDA and China SAMR approvals simultaneously face conflicting documentation requirements. Parallel track submissions extend time-to-revenue by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Low Fat Sausage Market |
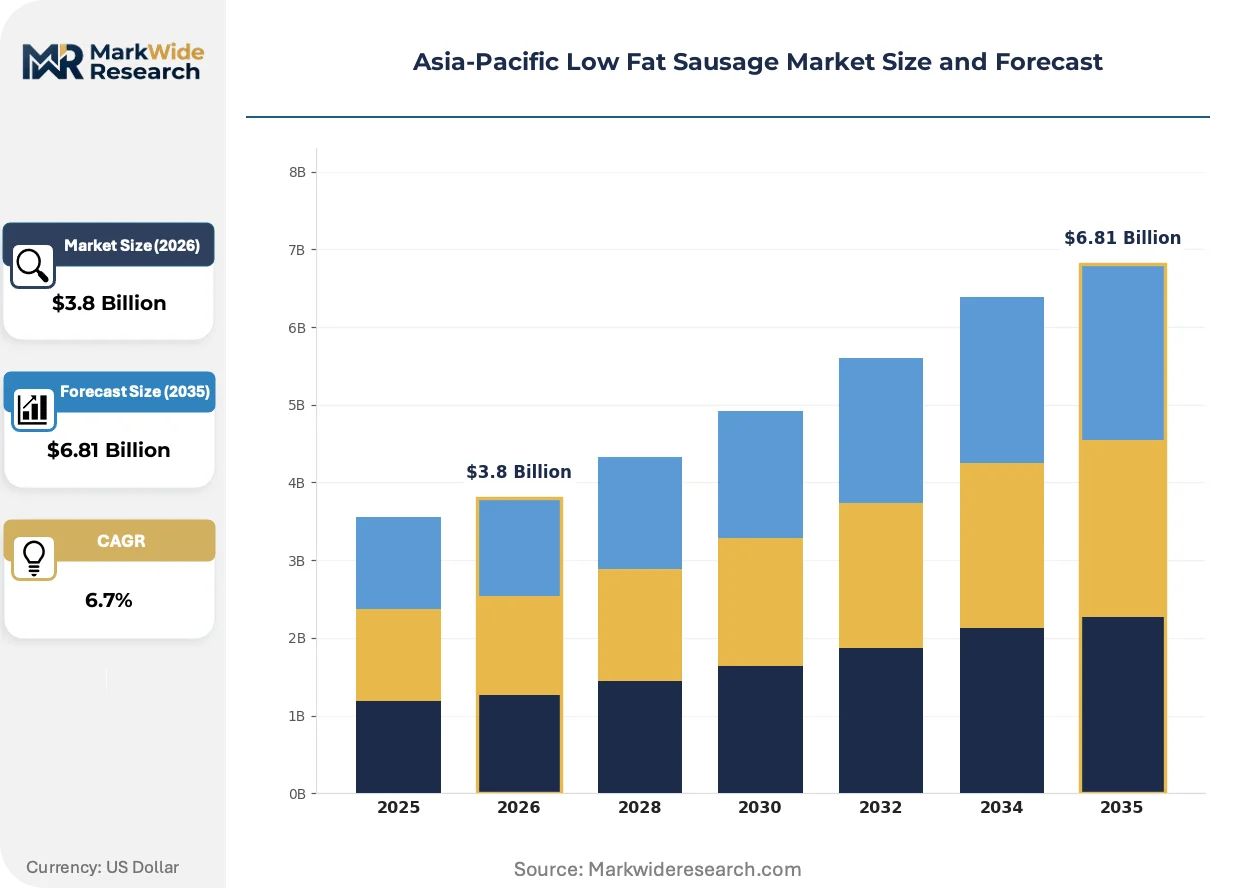
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork, Chicken, Turkey, Beef Application: Retail, Food Service, Snacks, Catering Packaging Type: Boxes, Pouches, Vacuum Sealed, Chubs End User: Households, Restaurants, Cafés, Institutions |
| Companies Covered | NH Foods Ltd., Itoham Foods Inc., Venkys (India) Limited, Suguna Foods Pvt. Ltd., Yurun Group Ltd., WH Group Limited, Nestlé S.A., Cargill, Incorporated, Tyson Foods, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Low Fat Sausage Market Trends and Innovations
Formulation science and distribution infrastructure are converging to redefine what constitutes acceptable texture and shelf life in reduced-fat processed meat. These developments are compressing the performance gap between premium chilled and mass-market shelf-stable segments.
Microencapsulated omega-3 oil systems are unifying cardiovascular health positioning with sensory acceptance in low-fat emulsions. Japanese food service chains are piloting these formulations in bento and convenience meal applications. The technology is enabling premium pricing for products previously confined to standard tiers.
China's GB 2760 food additive standard revisions are tightening permitted preservative categories for cooked meat products. Processors are accelerating clean-label fermentation-based preservation research. Premium retail channels in Shanghai and Beijing are responding with accelerated SKU rotation toward additive-minimized lines.
Urban Chinese households are consolidating protein purchases around trusted domestic brands with visible supply chain transparency. Traditional wet market channels are losing share to supermarket and e-commerce platforms with batch-traceability features. This behavior shift concentrates most visibly in tier-one cities where food safety incidents remain salient in consumer memory.
Asia-Pacific Low Fat Sausage Market Segmentation
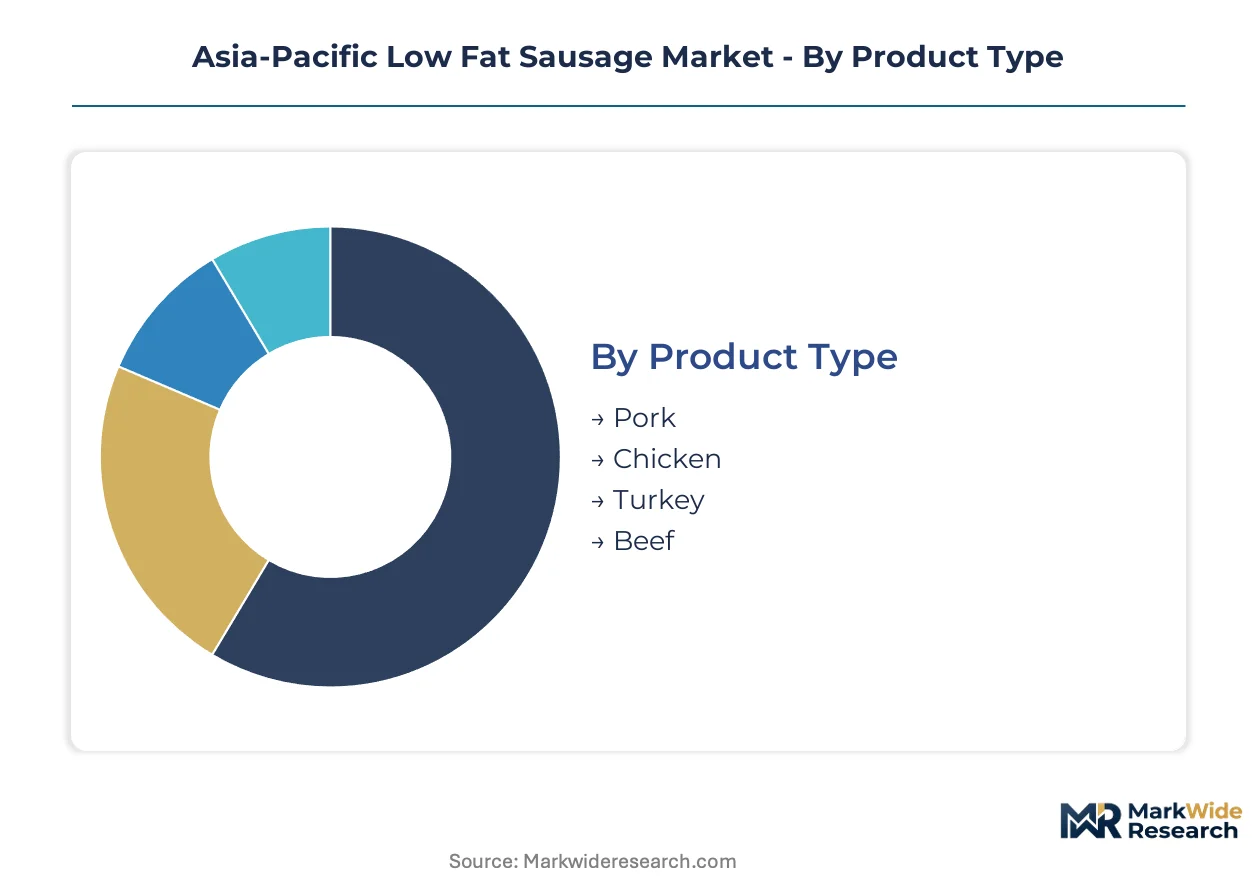
Segmentation in Asia-Pacific low fat sausage markets reflects divergent buyer priorities across protein sources, distribution channels, and consumption occasions. Procurement specifications vary sharply between retail chains demanding clean-label compliance and food service operators optimizing cost-per-portion metrics.
Product Type:
Protein selection drives formulation investment, shelf-life requirements, and margin structure across processing facilities.
- Pork:Dominates current volume through established abattoir infrastructure and consumer familiarity across East Asian markets. China's vertically integrated hog farming operations anchor supply security for premium retail channels in tier-one cities.
- Chicken:White-meat preference strengthens among younger demographics in India and Southeast Asia. Quick-service restaurant chains in Jakarta and Bangalore are standardizing poultry-based specifications for menu reformulation.
- Turkey:Niche positioning in health-conscious urban households seeking leaner alternatives to traditional pork formulations.
- Beef:Premium tier applications in Australian and Japanese markets where grass-fed certification commands price differentiation.
Volume sits with pork; growth tilts toward chicken.
Application:
Channel selection determines packaging requirements, cold-chain investment, and regulatory compliance burden.
- Retail:Supermarket and e-commerce platforms specify batch-traceability features and additive-minimized formulations. Freshippo and JD Fresh are building private-label portfolios with rapid flavor iteration capabilities.
- Food Service:Contract-based procurement from chain operators drives specification-driven volume commitments. Japanese convenience meal applications are piloting microencapsulated omega-3 systems for cardiovascular health positioning.
- Snacks:Shelf-stable formulations dominate Southeast Asian markets outside Thailand and Vietnam due to chilled distribution gaps.
- Catering:Institutional buyers in Australian education and healthcare sectors prioritize FSANZ-certified nutrition panel disclosure.
Margin concentrates in food service; retail channels are expanding fastest.
Packaging Type:
Packaging technology directly shapes shelf-life extension, transportation economics, and consumer perception of freshness.
- Vacuum Sealed:Premium retail channels in Shanghai and Beijing require modified atmosphere systems for chilled distribution. The technology enables 21-day shelf life without preservative reliance.
- Chubs:Food service operators favor bulk formats for portion-control efficiency in high-volume kitchen environments. Australian processors leverage these for RCEP-exported chilled pork.
- Boxes:Standard corrugated formats dominate shelf-stable export corridors with longer transit times.
- Pouches:Flexible packaging gains traction in Indonesian convenience store chains expanding refrigerated sections.
Technology investment clusters in vacuum systems; pouch formats are gaining share fastest.
End User:
Final consumption context dictates portion sizing, preparation method, and health-claim relevance.
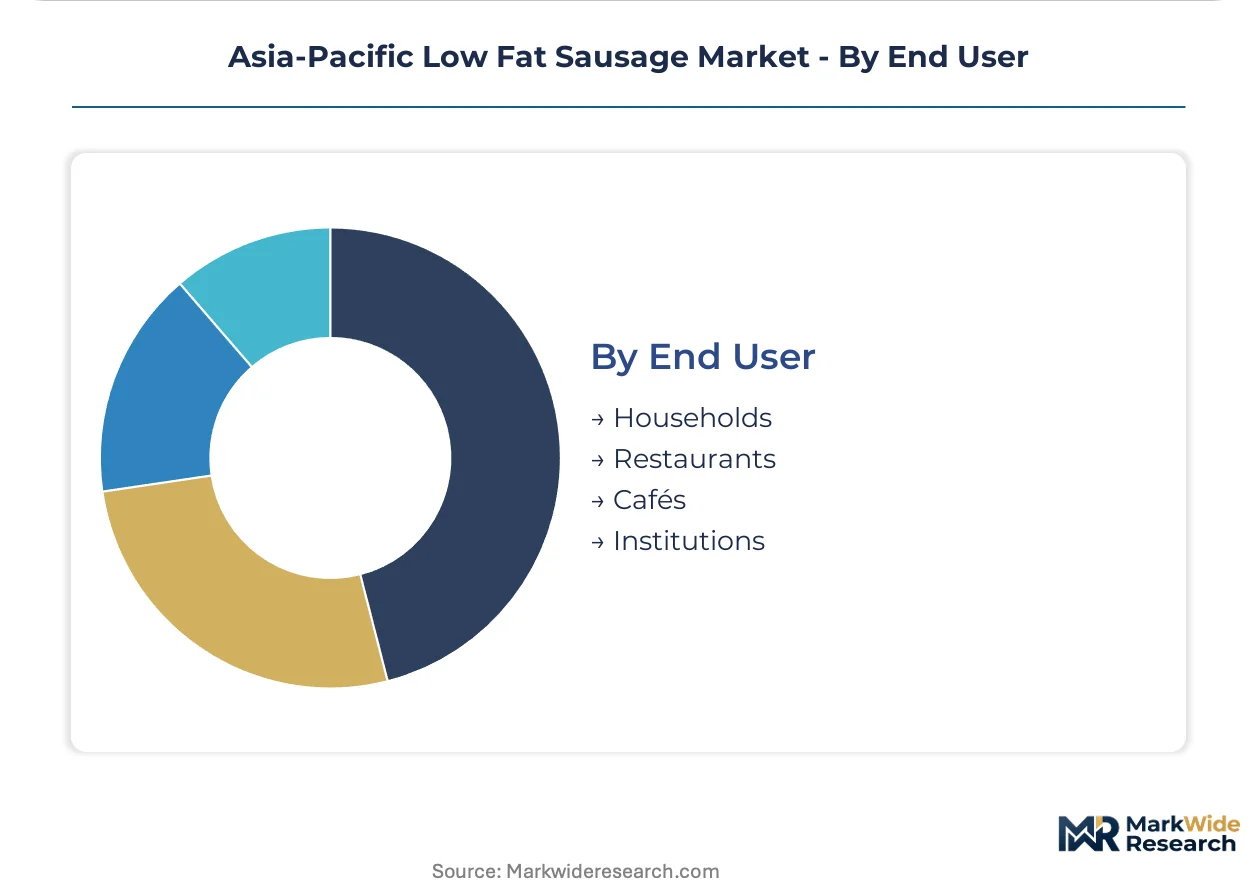
- Households:Urban Chinese consumers are consolidating purchases around trusted domestic brands with visible supply chain transparency. Tier-one city behavior shifts most visibly toward supermarket and e-commerce platforms.
- Restaurants:Chain operators in India's QSR networks are standardizing low-fat sausage specifications across franchise locations.
- Cafés:Limited-service formats in Japanese metropolitan areas incorporate reduced-fat processed meat into breakfast and convenience meal offerings.
- Institutions:Healthcare and education facilities in Australia mandate strict fat-content thresholds aligned with cardiovascular health guidance.
Procurement volume aggregates in restaurants; household channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed grain belts across the Indo-Gangetic Plain and North China Plain anchor regional hog and poultry supply chains for reduced-fat sausage production. Urban consumption clusters concentrate in coastal megacities where cold-chain infrastructure enables chilled distribution of lean-meat formulations.
China
Vertically integrated hog farming operations in Henan and Sichuan provinces supply lean-trim raw material to processors serving tier-one retail channels. SAMR's GB 2726 enforcement is compressing margins and accelerating abattoir consolidation. Shanghai and Beijing supermarket buyers now mandate batch-traceability features and additive-minimized formulations in procurement contracts.
Japan
Convenience meal operators in Tokyo and Osaka are piloting microencapsulated omega-3 systems for cardiovascular health positioning in bento applications. METI-led clean-label disclosure initiatives are tightening fat-content labeling requirements under Food Sanitation Act provisions. Kanto and Kansai industrial corridors host advanced emulsion technology facilities serving domestic food service chains.
India
Quick-service restaurant networks in Bangalore and Mumbai are standardizing poultry-based low-fat sausage specifications across franchise locations. FSSAI processed food regulations are tightening preservative disclosure requirements for retail-packaged meat products. Maharashtra and Karnataka poultry processing clusters are expanding capacity to serve specification-driven QSR procurement.
Australia
Queensland and New South Wales pork processors are leveraging FSANZ certification for premium positioning in ASEAN export corridors under RCEP tariff reductions. Healthcare and education institutional buyers mandate strict fat-content thresholds aligned with cardiovascular health guidance. Sydney and Melbourne retail channels are consolidating purchases around brands with visible supply chain transparency.
Indonesia
Convenience store chains in Jakarta and Surabaya are expanding refrigerated sections for chilled poultry sausage distribution. The country's national food safety regulator is tightening processed meat labeling requirements for modern trade channels. Local poultry processors in Java are securing first-mover positioning before multinational entry into underpenetrated segments.
Asia-Pacific Low Fat Sausage Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label and alternative protein adjacencies. The vendor base clusters around three maturity tiers: multinational meatpackers with captive raw material supply, domestic integrated processors controlling regional distribution, and specialist white-meat operators serving QSR networks. Dominant competitive moves include backward integration into hog farming and strategic partnerships with e-commerce platforms for direct-to-consumer channel access.
Among Japanese integrated meat processors, NH Foods Ltd. and Itoham Foods Inc. exemplify the cold-chain logistics archetype spanning manufacturing and distribution infrastructure. WH Group Limited occupies a position representing the vertically integrated Chinese operator model with upstream control over breeding and slaughtering operations. Venkys (India) Limited anchors the poultry-specialist tier serving quick-service restaurant procurement networks across South Asian markets.
| Leading Market Players |
|---|
| NH Foods Ltd. |
| Itoham Foods Inc. |
| Venkys (India) Limited |
| Suguna Foods Pvt. Ltd. |
| Yurun Group Ltd. |
| WH Group Limited |
| Nestlé S.A. |
| Cargill, Incorporated |
| Tyson Foods, Inc. |
| Others |
Pricing and Supply Chain Analysis
Food service procurement concentration in Japanese convenience meal chains and Chinese QSR networks anchors contract-based pricing with volume-commitment structures. Premium retail channels in Shanghai and Jakarta negotiate additive-minimized formulations at three-tier pricing stratification across premium, standard, and economy certification levels.
Pricing Analysis
Warranty and freshness-guarantee bundling separate premium vacuum-sealed chilled products from unbundled shelf-stable economy tiers. Pricing stratifies across premium, standard, and economy tiers based on cold-chain certification and lean-meat percentage disclosure. Cost compression in standard-tier pork formulations is intensifying because of feed grain volatility and SAMR compliance investment. Quick-service restaurant chains exhibit highest price sensitivity; healthcare institutional buyers show least sensitivity due to mandated nutritional thresholds.
Supply Chain Analysis
Workforce availability constraints in China's Henan processing corridors and Vietnam's Mekong Delta poultry clusters are elevating automation investment requirements. Manufacturing concentrates in China, Thailand, and Australia, with raw material flows drawing from North China Plain hog farming and Indo-Gangetic poultry belts. Supply chain risk centers on single-source vulnerability for microencapsulated omega-3 oil systems. Distribution runs through integrated cold-chain operators serving supermarket and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where upstream hog farming control and downstream e-commerce platform access determine margin capture. Players are pursuing captive breeding operations to buffer feed cost volatility and secure lean-trim supply.
For Market Incumbents: Deepen backward integration into hog farming operations in Sichuan and Henan provinces to secure lean-trim raw material against feed grain price swings. Accelerate clean-label fermentation-based preservation R&D to preempt GB 2760 additive restrictions. Capture e-commerce platform partnerships with Freshippo and JD Fresh before multinational entrants establish private-label positioning.
For New Entrants and Emerging Players: Launch via direct-to-consumer channels targeting tier-two Chinese cities where supermarket cold-chain expansion outpaces incumbent brand presence. Exploit white-space opportunity in Indonesian convenience store refrigerated sections before NH Foods and Itoham establish local production. Pursue poultry-based formulations for Indian QSR networks where Venkys and Suguna have not yet standardized specifications.
For Investors and Strategic Acquirers: The window for entry favors mid-cap processors with existing SAMR or PMDA certification infrastructure and visible supply chain traceability systems. Long-term viability hinges on regulatory compliance capability rather than scale alone. Watch for GB 2726 enforcement acceleration as the signal triggering consolidation-driven valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hog Farming | WH Group's captive breeding operations in Henan buffer feed cost volatility for lean-trim supply security. |
| Clean-Label Fermentation R&D | Processors accelerating additive-minimized preservation research respond to GB 2760 standard revisions. |
| E-Commerce Platform Partnership | Freshippo and JD Fresh private-label portfolios enable rapid flavor iteration against regional preference maps. |
| Dual Certification Investment | Parallel Japan PMDA and China SAMR approval tracks extend time-to-revenue but secure premium channel access. |
| Microencapsulated Omega-3 Adoption | Japanese convenience meal operators pilot cardiovascular health positioning for premium bento tier pricing. |
Research Methodology
Multi-period observation of GB standard enforcement patterns, cold-chain infrastructure buildout rates, and QSR procurement specification changes anchored the trend analysis, supplemented by interviews with meat processing plant managers, supermarket category buyers, food service procurement directors, and regulatory affairs specialists at SAMR and PMDA. Secondary validation drew from customs trade databases, SEC 10-K filings of listed meatpackers, FSANZ nutrition disclosure records, and FSSAI processed food registration data. Bottom-up facility capacity assessments and top-down consumption surveys were triangulated against channel shipment data.
Segment-weighting approaches modeled protein source, distribution channel, and packaging technology dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections incorporating feed grain price scenarios and regulatory compliance cost curves. Industry-specific forecast inputs included hog farming margin compression indices and convenience store refrigerated section expansion rates in Southeast Asian markets.
Feed grain price spikes, accelerated SAMR enforcement timelines, and alternative protein substitution velocity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about cold-chain infrastructure buildout and clean-label adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Brazil Meat Products Market
Meat Products
China Processed Meat Market
Meat Products
Animal Protein Market
Meat Products
Pork Flavors Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Bacon Slicers Market
Meat Products
Meat-Based FPP Market
Meat Products
Beef Extract Market
Meat Products
Organic Pork Market
Meat Products
Organic Meat Market
Meat Products
Middle East Edible Meat Market
Meat Products
Low-Fat Chorizo Market
Meat Products
India Animal Protein Market
Meat Products
Beef Jerky Market
Meat Products
Beef Bone Broth Market
Meat Products
Europe Animal Protein Market