
 Vegan Spaghetti Market | 2026-2036
Vegan Spaghetti Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Spaghetti Market Analytics
EU Green Deal carbon-accounting rules for food imports is restructuring the cost-of-entry calculus for new vegan spaghetti entrants. Barilla Group leverages its Italian milling infrastructure to sustain competitive sourcing of chickpea and lentil flours. Banza LLC anchors its position through R&D intensity in legume-protein extrusion technology. Explore Cuisine differentiates via gluten-free quinoa-based formulations that command premium shelf placement in North American retailers.
Vegan spaghetti denotes durum-wheat-free pasta manufactured from legume, pseudocereal, or vegetable flours, typically extruded at 40-60°C to preserve protein integrity and achieve al dente texture. The product serves consumers eliminating gluten, animal derivatives, or refined carbohydrates from their diets. Chickpea formulations lead volume due to neutral flavor profiles and protein density exceeding 20 grams per serving. Online Stores represent the fastest-growing distribution channel, capturing Health Enthusiasts through subscription models and direct-to-consumer nutrition transparency. Eco-friendly Packaging commands disproportionate margin pools as sustainability-motivated buyers accept price premiums for compostable materials.
EFSA governs novel-food approvals for emerging protein sources entering European vegan pasta formulations. FDA labeling requirements for gluten-free claims shape product positioning and packaging compliance in the United States. USDA organic certification and EU Green Deal farm-to-fork targets collectively elevate input costs while restricting supplier pools for certified manufacturers. Stakeholders must monitor evolving protein-adulteration testing protocols and carbon-border adjustment mechanisms that will determine which ingredient sources retain cost competitiveness.
Market Dynamics
The EU Green Deal carbon-accounting rules for food imports are restructuring ingredient sourcing economics, forcing manufacturers to relocate milling operations or absorb border-adjustment costs that erode margin structures for non-compliant suppliers.
Growth Catalysts
- Legume-protein extrusion advances:Cold-extrusion technology operating at 40-60°C preserves protein integrity while achieving al dente texture, expanding addressable demand among Health Enthusiasts seeking functional nutrition.
- EU Green Deal farm-to-fork targets:Mandatory sustainability disclosures and carbon-border adjustments favor domestic European pulse processors over imported wheat alternatives, accelerating regional supply chain reconfiguration.
- Health Enthusiast segment expansion:Subscription-based direct-to-consumer models capture recurring revenue from buyers prioritizing nutrition transparency and compostable packaging premiums.
Market Restraints
- Input cost volatility:Chickpea and lentil flour prices fluctuate with pulse crop yields in Canada and Australia, compressing gross margins for manufacturers lacking long-term supply contracts.
- Supply concentration risk:Italian milling infrastructure dominates premium legume flour processing, creating geographic single-point vulnerability for brands dependent on Emilia-Romagna production clusters.
- EFSA novel-food approval timelines:Emerging protein sources such as fava bean or lupin formulations face 18-24 month regulatory review periods, delaying product launches and freezing R&D amortization schedules.
Strategic Opportunities
- Underpenetrated German retail:Discounter channel penetration for vegan spaghetti remains below Italian levels, creating shelf-space expansion potential for brands achieving Rewe or Edeka listings.
- Quinoa-pasta convergence:Gluten-free pseudocereal formulations command 35-40% price premiums in North American natural retailers, attracting investment in Andean sourcing infrastructure.
- Compostable packaging mandates:France's AGEC law and similar extended producer responsibility frameworks in Belgium accelerate demand for cellulose-based barrier films that extend shelf life without petroleum inputs.
Industry Challenges
- Protein-adulteration detection capability gaps:Laboratories capable of verifying legume-protein authenticity against cheaper wheat dilution remain scarce outside Milan and Rotterdam, stretching quality assurance timelines.
- Extrusion equipment retrofit costs:Legacy durum-wheat pasta lines require $2-4 million capital outlays for temperature-control modifications to process high-fiber legume doughs without die blockage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Spaghetti Market |
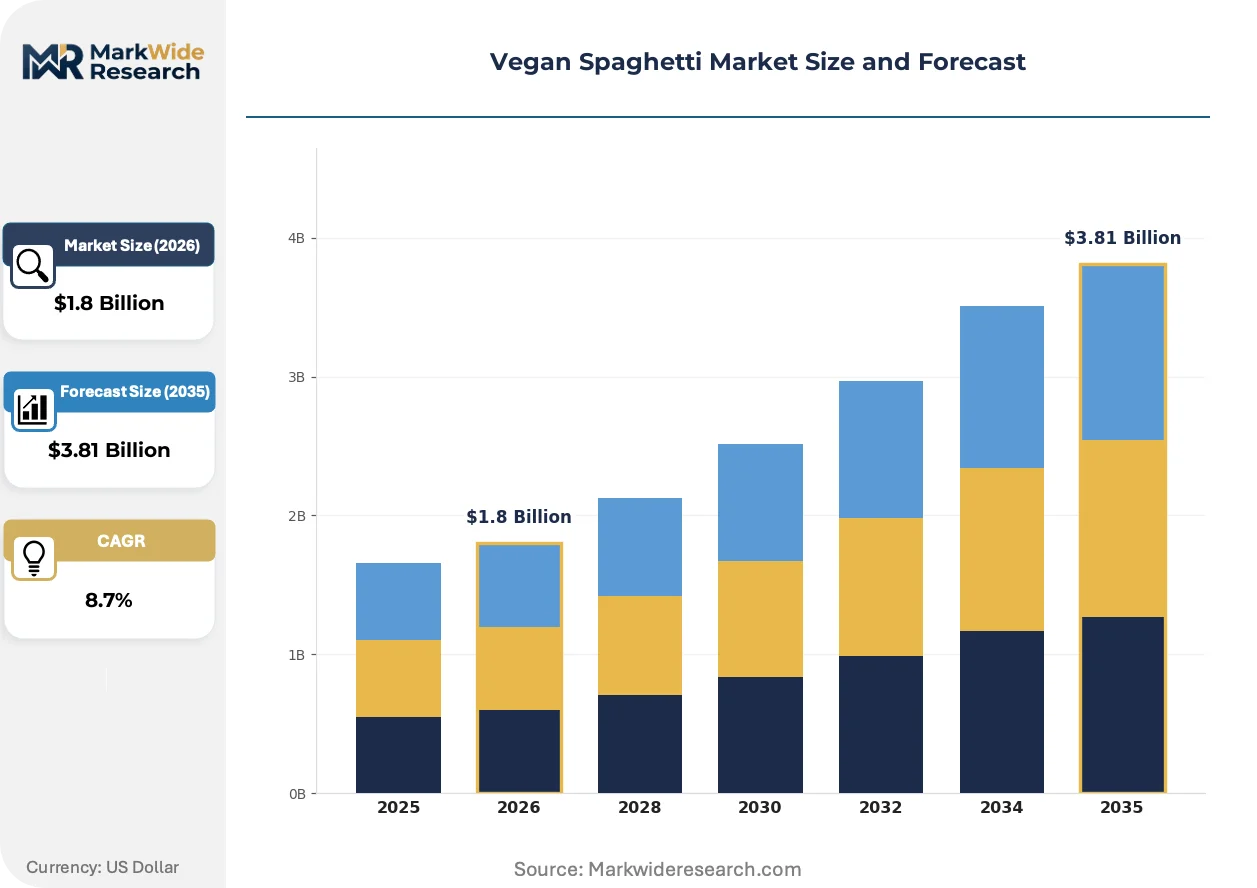
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, Lentil, Chickpea, Quinoa Distribution Channel: Supermarkets, Online Stores, Health Food Stores, Specialty Retailers Packaging Type: Box, Bag, Bulk, Eco-friendly Packaging End User: Vegetarians, Vegans, Health Enthusiasts, Culinary Professionals |
| Companies Covered | Barilla Group, Banza LLC, Explore Cuisine, Tolerant Foods, Jovial Foods Inc., De Cecco, Nestlé S.A., Ancient Harvest, Seggiano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Spaghetti Market Evolving Landscape
Ingredient sourcing transparency and processing technology convergence are compressing traditional competitive moats, enabling new entrants to challenge established pasta manufacturers through novel protein formats and direct distribution bypass.
Low-temperature extrusion is consolidating control over texture and protein retention in premium vegan spaghetti manufacturing. Health Enthusiasts and clinical nutrition buyers are adopting these formulations faster than conventional gluten-free alternatives. This technology is consolidating market share among R&D-intensive producers capable of precise temperature modulation, marginalizing brands reliant on modified starch workarounds.
REACH chemical compliance and EU Green Deal carbon-border mechanisms are tightening input documentation requirements for European vegan pasta manufacturers. Suppliers must now provide full lifecycle emissions data for chickpea and lentil flours entering EU processing facilities. Italian producers with vertically integrated domestic pulse supply chains are responding fastest, while importers face cost disadvantages from third-country verification burdens.
Subscription-based replenishment models are displacing conventional retail stocking patterns among Health Enthusiast buyers. Direct-to-consumer channels capture recurring revenue through personalized nutrition dashboards and auto-ship algorithms. This behavioral shift concentrates most visibly in United States metropolitan markets, where Thrive Market and specialty platforms aggregate demand for certified organic and carbon-neutral pasta alternatives.
Vegan Spaghetti Market Segmentation
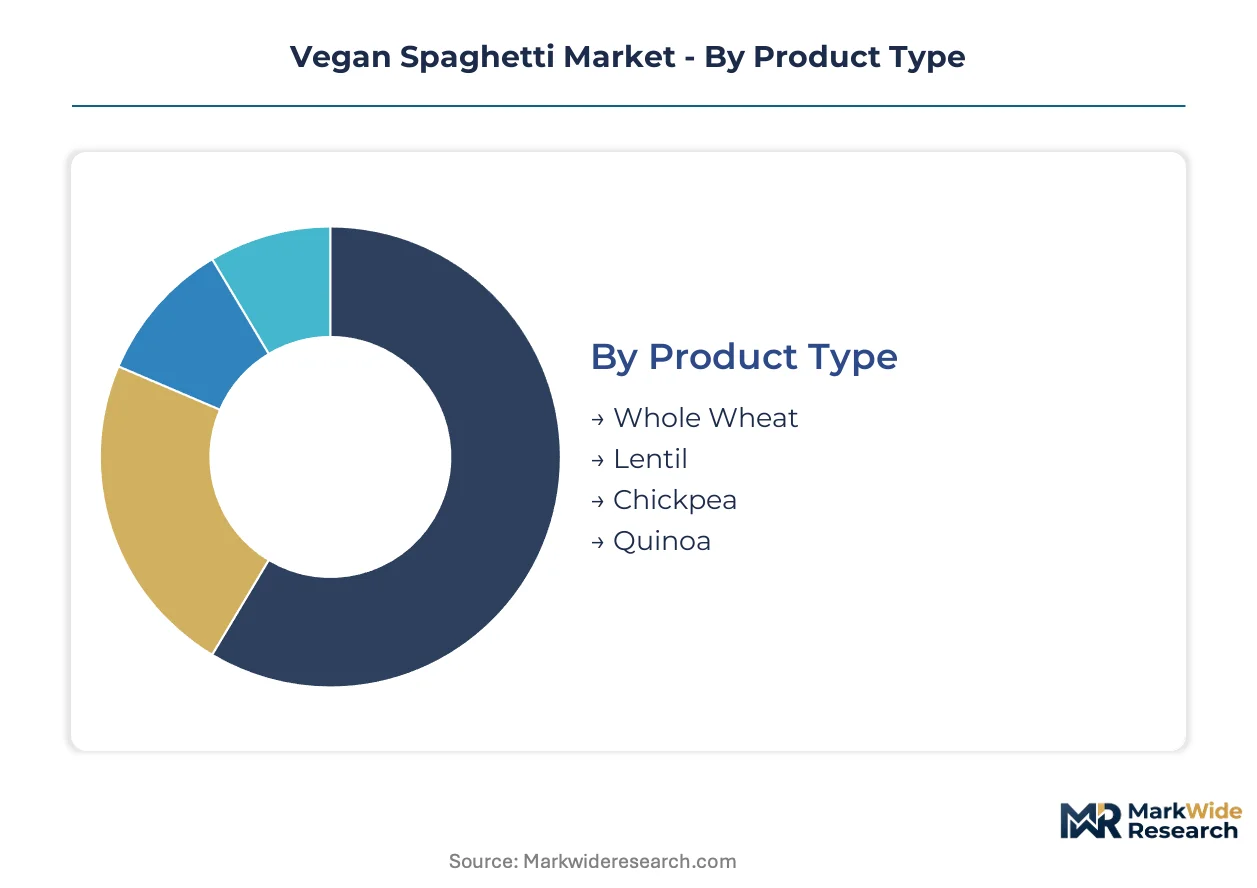
Vegan spaghetti manufacturers align production configurations against distinct demand profiles. Ingredient sourcing, channel economics, and end-use requirements fragment the addressable market into specialized supply streams.
Product Type:
Ingredient concentration in Emilia-Romagna milling clusters shapes competitive positioning across formulations.
- Chickpea:Neutral flavor and protein density exceeding 20 grams per serving anchor volume leadership. Health Enthusiasts in Italy and North America drive recurring purchases through subscription platforms.
- Lentil:Red and green lentil varieties offer distinct color differentiation for retail shelf visibility. German discounters and French natural-food chains are expanding SKU counts for this format.
- Quinoa:Pseudocereal formulations command premium placement in gluten-free aisles of US natural retailers.
- Whole Wheat:Durum-free wheat alternatives serve transition buyers reducing refined carbohydrate intake.
Chickpea absorbs the bulk of installed capacity; quinoa is expanding most quickly.
Distribution Channel:
Channel cost structures stratify margin capture between high-touch specialty formats and automated replenishment models.
- Online Stores:Direct-to-consumer platforms aggregate Health Enthusiast demand through auto-ship algorithms and nutrition transparency dashboards. Subscription retention rates exceed conventional grocery repurchase cycles.
- Supermarkets:Mass-market penetration depends on slotting fee negotiations and certified organic shelf placement in Italy and Germany.
- Health Food Stores:Staff-assisted purchasing environments favor premium positioning and sampling programs for novel legume blends.
- Specialty Retailers:Italian gastronomia and North American Italian-import shops sustain artisanal small-batch distribution.
Supermarkets absorb the bulk of installed capacity; online stores are climbing the fastest.
Packaging Type:
Extended producer responsibility mandates in France and Belgium are accelerating material substitution timelines.
- Eco-friendly Packaging:Cellulose-based barrier films and compostable materials capture sustainability-motivated buyer premiums. France's AGEC law and Belgian EPR frameworks mandate phase-out of petroleum-derived films.
- Box:Recyclable paperboard dominates conventional retail with established supply chain infrastructure.
- Bag:Flexible packaging reduces shipping cube for e-commerce fulfillment.
- Bulk:Food-service and zero-waste retail formats in German and Dutch metropolitan markets favor dispenser systems.
Box absorbs the bulk of installed capacity; eco-friendly packaging is gaining share fastest.
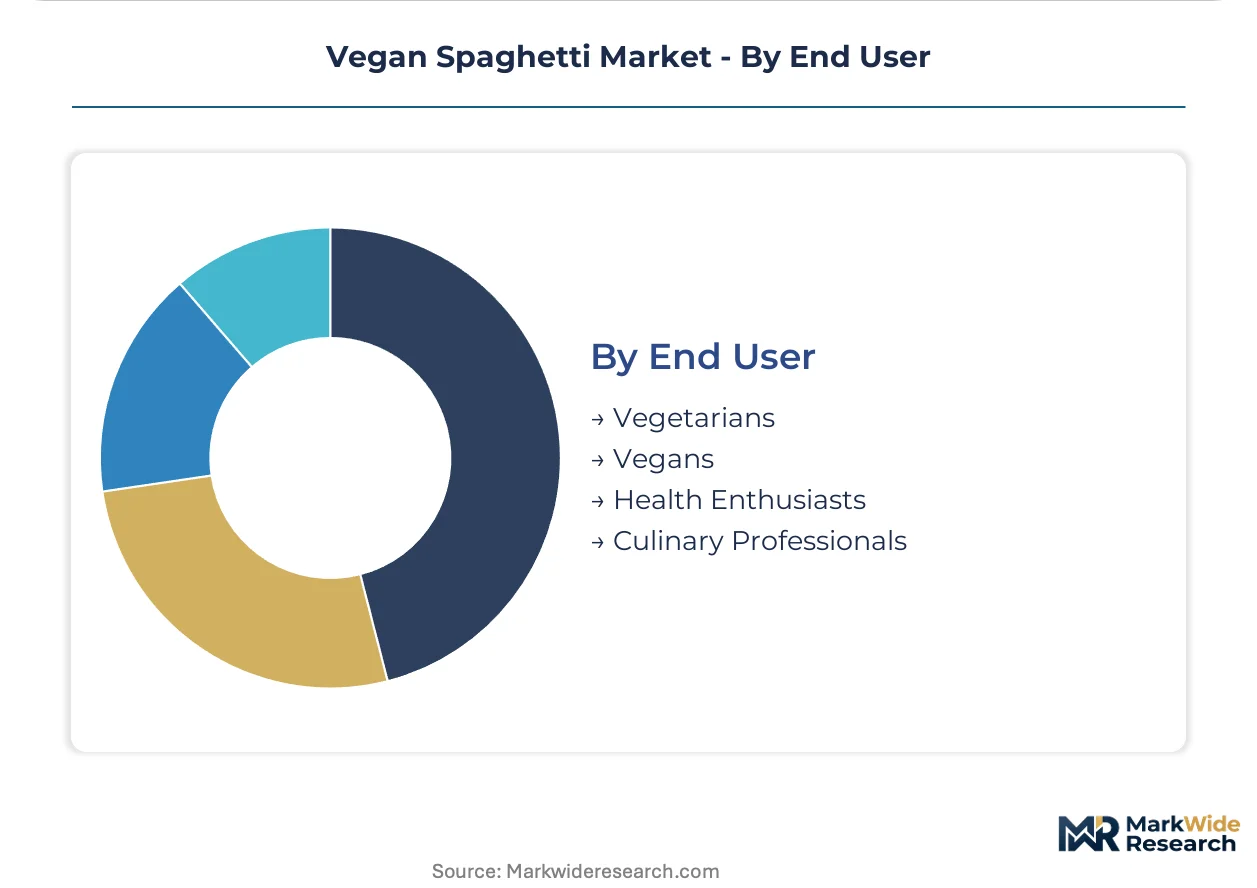
End User:
Buyer motivation intensity determines price elasticity and certification requirements across consumption occasions.
- Health Enthusiasts:Macro-tracking and functional nutrition priorities drive subscription adoption and protein-density screening. This segment accepts 25-35% premiums for cold-extruded formulations with preserved amino acid profiles.
- Vegans:Ethical consumption frameworks prioritize supply chain transparency and carbon-neutral certification.
- Vegetarians:Flexitarian transition states favor blended formulations reducing animal protein without full elimination.
- Culinary Professionals:Restaurant and catering procurement emphasizes consistent cook times and sauce adhesion properties for high-volume service.
Health Enthusiasts absorb the bulk of installed capacity; vegans are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian Health Enthusiasts and culinary traditionalists concentrate demand for legume-based pasta alternatives, while German retail modernization and North American subscription commerce reshape distribution economics across national boundaries.
Italy
Emilia-Romagna milling clusters process the majority of European chickpea and lentil flours for premium extrusion. The EU Green Deal farm-to-fork targets mandate carbon footprint disclosures for pulse processors supplying domestic manufacturers. Parma and Modena facilities are retrofitting cold-extrusion lines to preserve protein integrity in al dente formulations.
Germany
Discounter channel penetration for vegan spaghetti trails Italian levels, creating shelf-space expansion opportunities at Rewe and Edeka banners. The country's national food regulator enforces strict organic certification standards under EU organic regulations. Berlin and Hamburg metropolitan areas are piloting zero-waste bulk dispenser systems for compostable-packaged alternatives.
United States
Subscription-based direct-to-consumer platforms capture Health Enthusiast demand through auto-ship algorithms and nutrition transparency dashboards. FDA labeling requirements for gluten-free claims shape product positioning and packaging compliance across state lines. Thrive Market and specialty platforms in California and New York Metro markets aggregate demand for certified organic and carbon-neutral pasta alternatives.
France
Sustainability-motivated buyers accept price premiums for compostable materials under AGEC law extended producer responsibility frameworks. The national environmental agency mandates phase-out timelines for petroleum-derived barrier films in food packaging. Lyon and Paris natural-food chains are expanding SKU counts for lentil-based color-differentiated formulations.
Canada
Pulse crop yields in Saskatchewan and Manitoba influence chickpea flour price volatility for North American manufacturers. The country's national food inspection agency enforces organic certification and import documentation for legume-based products. Toronto and Vancouver metropolitan markets favor gluten-free quinoa formulations commanding premium placement in natural retailers.
Vegan Spaghetti Market Competitive Landscape
Italian producers anchor one tier through vertically integrated milling infrastructure and heritage brand equity; North American specialists hold another through R&D intensity in extrusion technology and direct-to-consumer channel capture. The vendor base stratifies across three tiers: multinational food conglomerates with diversified pasta portfolios, mid-cap legume-protein specialists, and artisanal regional mills. Two dominant competitive moves are reshaping positioning: strategic partnerships between pulse processors and extrusion equipment vendors, and geographic expansion into underpenetrated German discounter channels.
Within the heritage Italian tier, Barilla Group and De Cecco exemplify established milling infrastructure leverage. Among North American legume-protein specialists, Banza LLC and Explore Cuisine occupy positions defined by cold-extrusion R&D investment and premium formulation differentiation. These five entities collectively represent the competitive archetypes—heritage infrastructure, technology-intensive specialization, and pseudocereal premium positioning—that structure margin capture across distribution channels.
| Leading Market Players |
|---|
| Barilla Group |
| Banza LLC |
| Explore Cuisine |
| Tolerant Foods |
| Jovial Foods Inc. |
| De Cecco |
| Nestlé S.A. |
| Ancient Harvest |
| Seggiano |
| Others |
Value Network & Pricing Analysis
Premium-cold-extruded and commodity-heat-processed tier divergence splits margin capture between Italian heritage mills and import-reliant challengers, with EU Green Deal carbon-border adjustments amplifying price spreads as domestic pulse processors gain cost advantages over third-country flour sources.
Pricing Analysis
Volume concentrates in chickpea formulations sold through supermarkets at commodity-equivalent price points, while margin pools accrue to cold-extruded quinoa and lentil variants commanding 25-35% premiums in health food stores and subscription channels. Price differentiation rests on certification grade—USDA organic and EU Green Deal farm-to-fork compliance—and extrusion technology sophistication. Pricing pressure stems from Canadian and Australian pulse crop yield volatility compressing input costs for non-contracted manufacturers. Health Enthusiasts exhibit lowest price sensitivity, accepting premiums for preserved amino acid profiles, while transition buyers in mass retail remain highly elastic.
Supply Chain Analysis
Single-source vulnerability sits with Emilia-Romagna milling clusters, where Italian infrastructure processes the majority of European legume flours for premium extrusion. Raw material dependencies center on Canadian and Australian chickpea harvests, Andean quinoa sourcing, and domestic Italian lentil production. Supply chain risk manifests as geographic concentration exposure—disruption to Parma or Modena facilities would cascade through European premium pasta manufacturing. Distribution runs through three channels: direct-to-consumer subscription platforms capturing Health Enthusiast loyalty, German and Italian supermarket chains demanding slotting fee negotiations, and North American natural retailers prioritizing gluten-free aisle placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal carbon-accounting framework erects a compliance moat that favors domestic European pulse processors with verified supply chain documentation, marginalizing importers unable to absorb third-country verification burdens.
For Market Incumbents: Hedge against Emilia-Romagna concentration risk by securing long-term supply contracts with Canadian and Australian pulse growers before carbon-border adjustments fully phase in. Invest in cold-extrusion capacity additions at secondary Italian facilities to preserve protein-integrity advantages against emerging R&D-intensive North American specialists. Defensive priority rests on locking discounter shelf space in underpenetrated German retail before mid-cap legume-protein specialists achieve Rewe or Edeka listings. For New Entrants and Emerging Players: EU Green Deal farm-to-fork targets in Europe open a window for domestic pulse processors with vertically integrated carbon-neutral certification to capture margin pools from import-dependent competitors. White-space targets include German discounter channels where vegan spaghetti penetration trails Italian levels, and French metropolitan bulk dispenser formats under AGEC law mandates. Go-to-market angle should emphasize compostable packaging compliance ahead of petroleum-derived film phase-outs. For Investors and Strategic Acquirers: Re-rating potential sits with R&D-intensive extrusion technology specialists given cold-extrusion patent portfolios consolidating texture and protein retention advantages. Long-term viability favors producers with captive Italian milling infrastructure or secured Andean quinoa sourcing agreements. Signal to monitor: EFSA novel-food approval timelines for fava bean and lupin formulations, which would unlock new protein-source diversification and compress incumbent chickpea-dominant positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Extrusion Capacity Expansion | Preserves protein integrity in al dente formulations for Health Enthusiast premium capture. |
| Backward Integration into Pulse Processing | Secures EU Green Deal carbon-accounting compliance against border-adjustment cost erosion. |
| Compostable Packaging Transition | Aligns with France's AGEC law mandates and Belgian EPR frameworks ahead of enforcement deadlines. |
| Direct-to-Consumer Channel Buildout | Captures recurring subscription revenue through auto-ship algorithms and nutrition transparency dashboards. |
| EFSA Novel-Food Approval Investment | Unlocks fava bean and lupin formulation launches currently frozen by 18-24 month regulatory review periods. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extrusion equipment engineers, pulse procurement managers at pasta manufacturers, sustainability compliance officers, and retail category buyers at German discounters and North American natural-food chains. EFSA novel-food approval databases, EU Green Deal implementation directives, FDA gluten-free labeling guidance, and USDA organic certification records provided regulatory boundary conditions. Bottom-up volume estimates from ingredient sourcing flows reconciled against top-down category expenditure data from retail audit providers.
Data-stream reconciliation across production capacity filings, import-export documentation, and channel shipment records informed the analytical framework. Segmentation dimensions modeled include ingredient type, distribution channel, packaging format, and end-user motivation intensity. CAGRs derived from trend extrapolation of pulse crop yield patterns, extrusion technology adoption curves, and regulatory compliance cost trajectories. Industry-specific inputs incorporated EFSA approval pipeline status and carbon-border adjustment implementation phases.
The model assumes a particular technology adoption path; alternative pathways for low-temperature extrusion scale-up would alter the outlook if equipment retrofit costs decline faster than projected. Forecasts reflect assumptions about EU Green Deal enforcement consistency and pulse crop yield stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Vegan Flour Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Asia-Pacific Pea Protein Market