
 Indonesia Plant-Based Food and Beverages Market | 2026-2036
Indonesia Plant-Based Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Plant-Based Food and Beverages Market Foresight
Single-serve portioning and trial-size bundling is recalibrating how Indonesian consumers experiment with plant-based products without committing to full-price formats. Oatly Group leverages its oat milk specialization to anchor premium positioning in Jakarta's café channel. Green Rebel Foods competes through localized taste profiles that dominate the meat substitute segment in domestic food service.
Indonesia plant-based food and beverages encompass protein-rich formulations derived from soy, coconut, oat, and tropical legumes, processed through extrusion, fermentation, or enzymatic conversion to replicate conventional dairy and meat sensory properties for human consumption. The product type dimension shows dairy alternatives sustaining the broadest consumer penetration while meat substitutes capture accelerating food service interest. Distribution channel dynamics reveal online retail extending fastest in tier-one cities, though supermarkets still control the majority of volume throughput across the archipelago.
BPOM's food safety registration requirements and Indonesia's mandatory halal certification under the Halal Product Assurance Law shape formulation decisions and import timelines for multinational suppliers. The Ministry of Health's front-of-pack labeling rules and nutrient content claims further constrain how brands position protein fortification and health benefits. Stakeholders must monitor regulatory harmonization between national halal mandates and evolving ASEAN food standards to anticipate compliance cost trajectories and first-mover certification advantages.
Market Dynamics
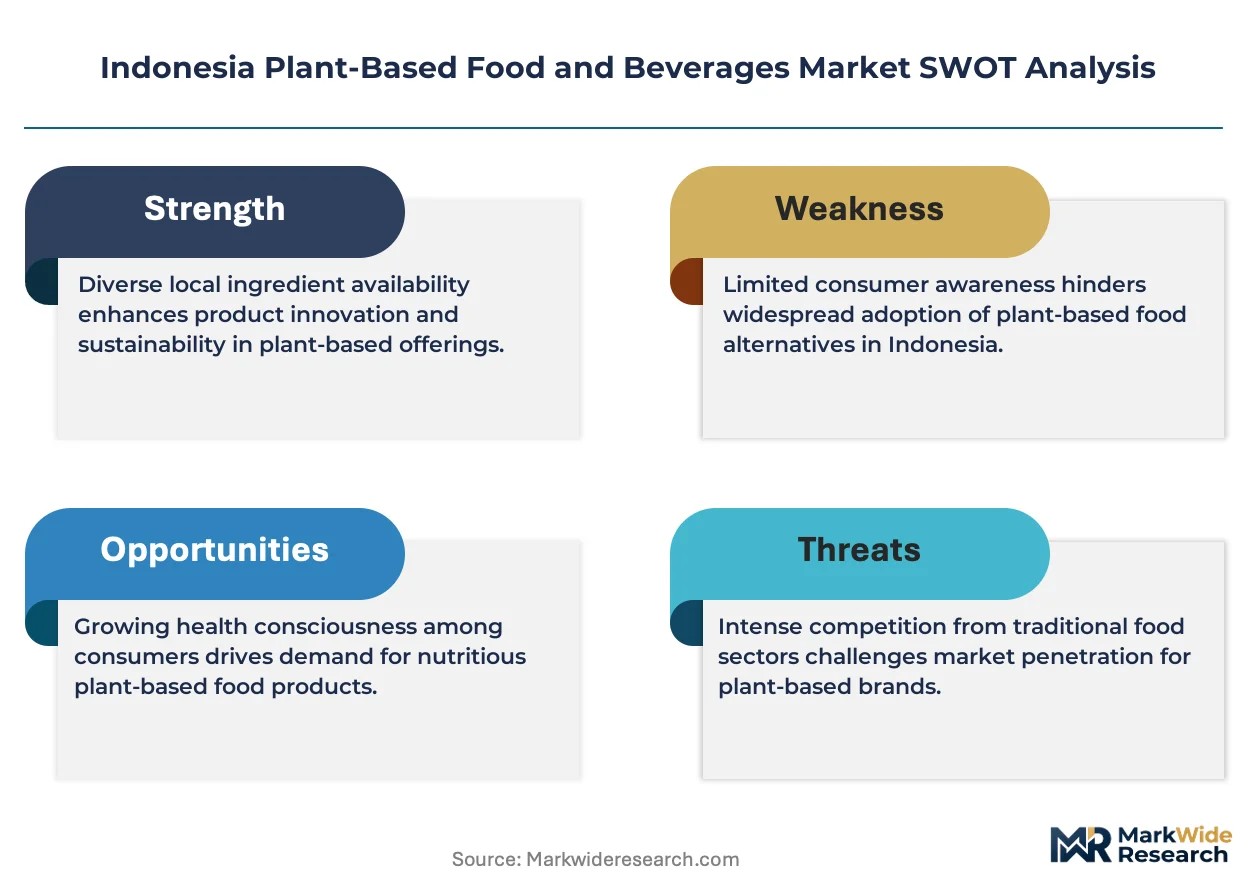
BPOM's halal certification mandates and the Ministry of Health's front-of-pack labeling rules are compressing formulation timelines and forcing domestic reformulation investments across Indonesia's plant-based sector. These regulatory pressures intersect with Java's urban demand concentration to reshape competitive positioning.
Growth Catalysts
- Halal Product Assurance Law:Mandatory halal certification under BPOM pathways creates first-mover advantages for compliant domestic producers while raising import barriers for multinational entrants.
- Jakarta-Bali food service corridor:Café and restaurant operators in these metropolitan clusters are expanding plant-based menu penetration, normalizing trial among middle-class consumers.
- Fermentation-based protein platforms:Enzymatic conversion technologies for tropical legumes are reducing sensory gaps between plant-based and conventional meat textures.
Market Restraints
- Coconut milk input volatility:Raw material costs for Indonesia's dominant plant-based dairy feedstock fluctuate with weather patterns and competing export demand.
- Import dependency for specialized equipment:Extrusion and fermentation infrastructure concentrates among European and East Asian suppliers, extending lead times for capacity expansion.
- BPOM registration timelines:Novel ingredient approvals for protein fortification and enzymatic processing face extended safety review periods.
Strategic Opportunities
- Eastern Indonesia archipelago penetration:Modern retail and food service infrastructure in Sulawesi and Papua remain underdeveloped relative to Java's saturation.
- Quick-commerce channel expansion:Instant delivery platforms in Surabaya and Bandung are creating new trial-size distribution nodes for single-serve formats.
- ASEAN regulatory harmonization:Convergence between Indonesia's halal mandates and emerging regional standards could streamline cross-border certification for export-oriented producers.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise bridging traditional Indonesian taste profiles with extrusion and fermentation processes remains concentrated in Jakarta.
- Dual certification complexity:Simultaneous BPOM safety registration and MUI halal approval creates parallel compliance workflows that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Plant-Based Food and Beverages Market |
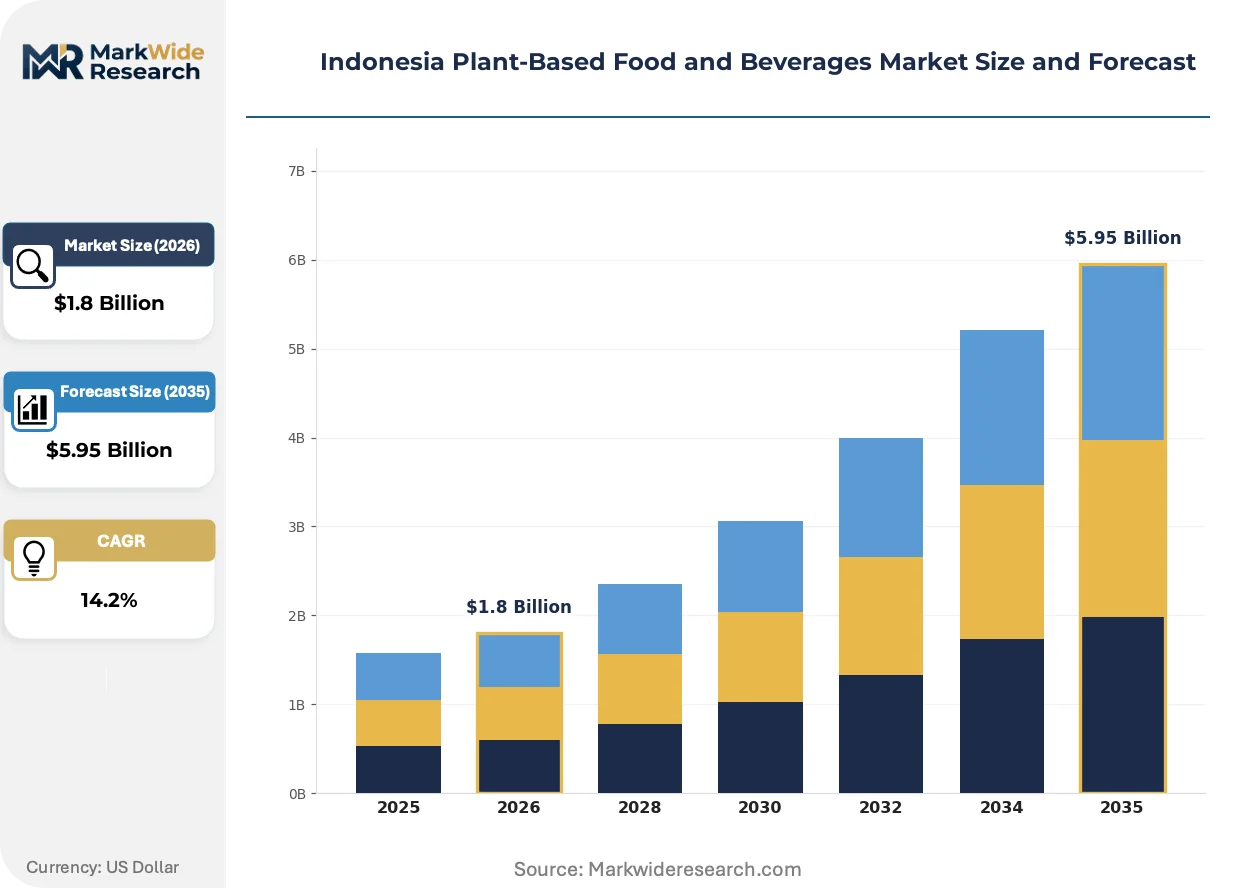
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Protein, Dairy Alternatives, Meat Substitutes, Snacks End User: Retail Consumers, Food Service, Health-Conscious Consumers, Vegan Consumers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Application: Food Products, Beverages, Nutritional Supplements, Culinary Uses |
| Companies Covered | PepsiCo Inc., Oatly Group, Nestlé S.A., Unilever Indonesia, Beyond Meat, Green Rebel Foods, The Kraft Heinz Company, Meatless Kingdom, Danone S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Plant-Based Food and Beverages Market Shifts & Advancements
Fermentation and enzymatic processing platforms are overtaking conventional extrusion as the dominant technological trajectory in Indonesia's plant-based protein sector. These advances compress sensory gaps while opening new formulation possibilities for tropical feedstocks.
High-moisture extrusion systems for meat analog texture replication are overtaking dry extrusion methods in Indonesian food service manufacturing. Major processors in Bekasi and Tangerang industrial zones are retrofitting production lines to accommodate wet extrusion parameters. This technology shift is overtaking legacy equipment investments and forcing supplier consolidation among machinery providers.
Indonesia's Ministry of Health front-of-pack nutrient labeling rules are tightening disclosure requirements for protein content claims and sodium thresholds. Manufacturers must reformulate legacy products to maintain permissible health positioning on packaging. The dairy alternatives segment faces the steepest compliance burden given its reliance on fortification messaging.
Single-serve trial formats distributed through quick-commerce and convenience retail are displacing traditional supermarket bulk purchasing for first-time plant-based buyers. Young professionals in Jakarta's satellite cities are driving this behavioral shift through instant delivery app usage. This pattern concentrates in Java's tier-one urban corridors where digital payment penetration and delivery density enable impulse trial economics.
Indonesia Plant-Based Food and Beverages Market Segmentation
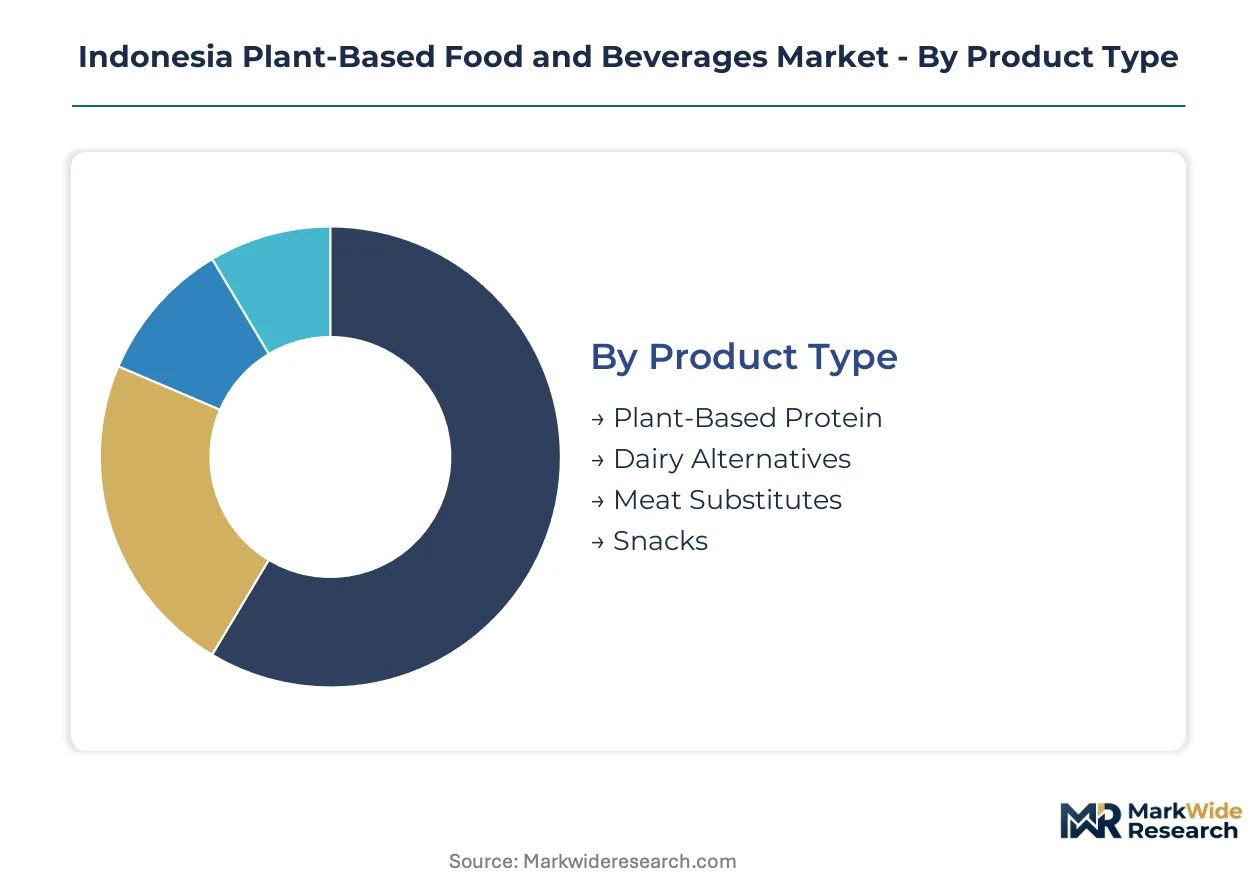
Segmentation in Indonesia's plant-based sector reveals how formulation complexity and certification requirements fragment commercial pathways. Product architecture, end-user sophistication, and channel infrastructure each impose distinct operational constraints on market entry.
Product Type:
Customization intensity varies sharply across this category, from commodity-adjacent dairy alternatives to precision-engineered meat substitutes demanding extrusion expertise.
- Dairy Alternatives:Coconut and oat-based beverages dominate shelf presence through enzymatic processing that stabilizes emulsions for tropical climates. Demand clusters in Jakarta's café corridor where barista-grade foamability commands premium positioning.
- Meat Substitutes:High-moisture extrusion of soy and tropical legumes replicates fibrous textures for food service applications. Bekasi and Tangerang processors are retrofitting lines to capture contract manufacturing volumes from expanding quick-service chains.
- Plant-Based Protein:Concentrated isolates serve ingredient supply roles for fortified foods and nutritional applications.
- Snacks:Extruded and baked formats target impulse trial through convenience retail placement.
Most installed capacity flows through Dairy Alternatives. Expansion is steepest in Meat Substitutes.
End User:
Cost-to-serve economics separate mass-market retail from specialized food service accounts with diverging certification and technical support requirements.
- Food Service:Restaurant and café operators in Jakarta-Bali metropolitan clusters drive volume through menu normalization and procurement consolidation. Contract terms increasingly mandate BPOM-registered suppliers with verified halal documentation.
- Retail Consumers:Supermarket shoppers in Java's urban corridor purchase bulk formats for household consumption, with purchase decisions heavily influenced by front-of-pack labeling compliance.
- Health-Conscious Consumers:Middle-class professionals seeking protein fortification and clean-label positioning.
- Vegan Consumers:Ideologically motivated buyers with zero-tolerance requirements for cross-contamination protocols.
Food Service captures the majority of current revenue. Health-Conscious Consumers are gaining share fastest.
Distribution Channel:
Volume throughput concentrates where modern retail infrastructure meets digital payment penetration, creating divergent growth trajectories across Indonesia's archipelago.
- Supermarkets:Hypermarket and supermarket chains in Java control the bulk of national volume through established supplier relationships and promotional slotting fees. Shelf space allocation favors BPOM-registered brands with MUI halal certification.
- Online Retail:Instant delivery platforms in Surabaya and Bandung enable single-serve trial economics that bypass traditional bulk purchasing patterns. Quick-commerce density in satellite cities is reshaping first-time buyer acquisition.
- Specialty Stores:Health food retailers serving concentrated vegan and allergen-sensitive demand pockets.
- Convenience Stores:Impulse-oriented formats for ready-to-drink beverages and snack applications.
Supermarkets retain the largest installed throughput base. Online Retail shows the steepest expansion trajectory.
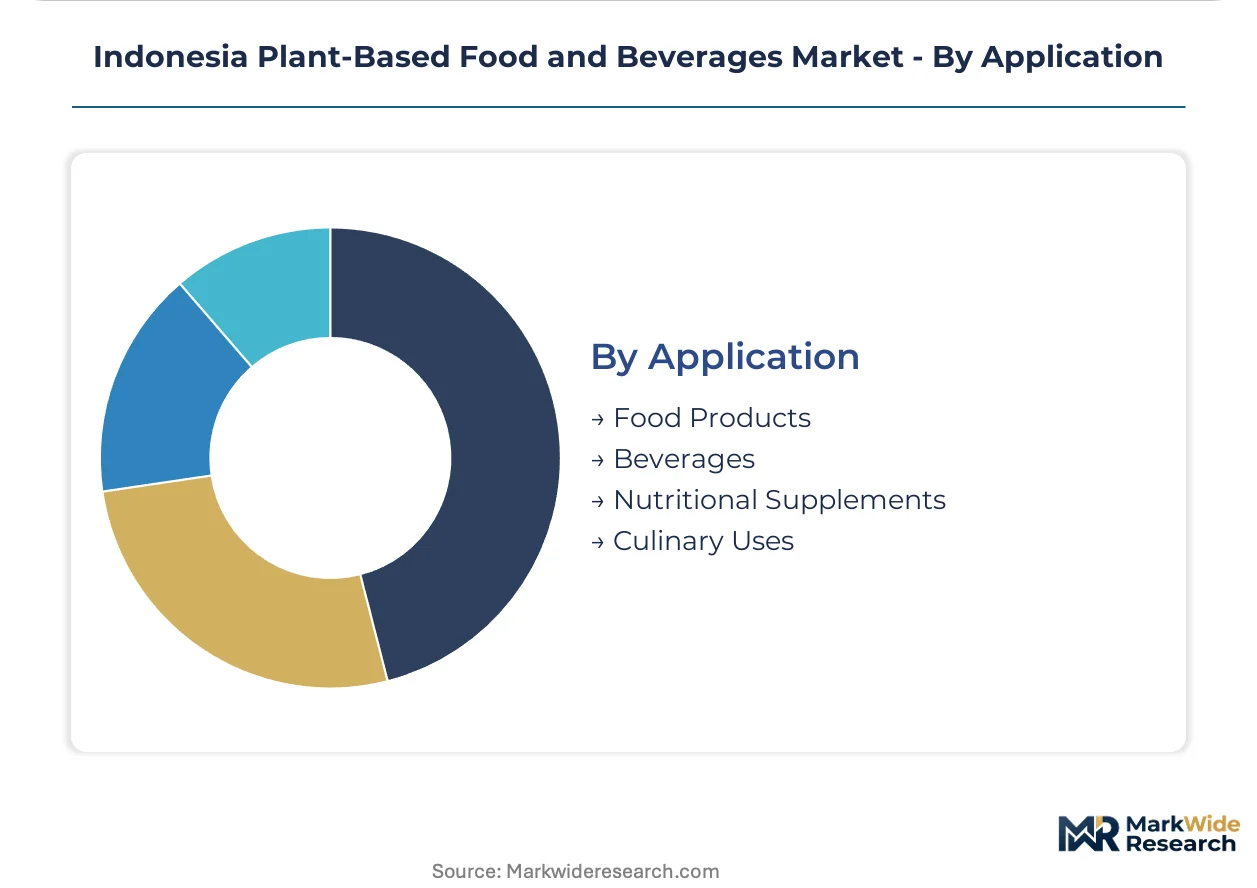
Application:
Margin structures diverge between finished consumer goods and ingredient supply roles, with regulatory burden scaling inversely to processing depth.
- Food Products:Finished plant-based meals and analogs for direct consumption. Manufacturing concentrates in Java's industrial zones where cold chain infrastructure supports perishable distribution.
- Beverages:Ready-to-drink and barista-grade formats for café and home consumption. Oat milk specialization has created distinct premium tiers based on foam stability and mouthfeel engineering.
- Nutritional Supplements:Protein powders and fortified formulations for fitness and clinical nutrition segments.
- Culinary Uses:Ingredient formats for food manufacturing and institutional kitchen applications.
Food Products absorb most production capacity. Beverages are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's plant-based sector emerged from Java's soy-processing heritage dating to Dutch colonial mills, then scaled through 1990s industrialization in Greater Jakarta. Today's geographic pattern concentrates capacity and demand across five distinct sub-regions.
Greater Jakarta
Jakarta's café corridor drives premium oat milk consumption through barista-grade foamability requirements. BPOM's centralized registration office accelerates halal certification timelines for domestic applicants. Bekasi and Tangerang industrial zones host high-moisture extrusion retrofitting for meat analog contract manufacturing.
West Java
Bandung's quick-commerce density enables single-serve trial economics through instant delivery platforms. The Ministry of Health's front-of-pack labeling enforcement concentrates inspection resources in this manufacturing hub. Cimahi and surrounding districts supply coconut milk feedstock to dairy alternative processors.
East Java
Surabaya's middle-class professionals generate accelerating demand for protein-fortified beverages. Provincial health offices coordinate with BPOM on novel ingredient safety reviews. Gresik industrial estates attract fermentation-based protein investments from domestic food conglomerates.
Bali
Tourism-dependent food service operators normalize plant-based menu penetration for international visitors. Regional halal certification offices process MUI approvals for imported specialty ingredients. Denpasar and Seminyak restaurant clusters drive premium positioning for meat substitute trials.
Eastern Archipelago
Sulawesi and Papua present underdeveloped modern retail infrastructure relative to Java's saturation. BPOM's decentralized registration creates extended timelines for novel product approvals in remote provinces. Makassar serves as the primary distribution node for inter-island logistics.
Indonesia Plant-Based Food and Beverages Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and formulation complexity. The vendor base stratifies between multinational entrants with established halal documentation and domestic specialists with localized taste profiles. Three archetypes dominate: oat milk specialists, tropical legume processors, and diversified food conglomerates. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure BPOM registration and MUI halal approval.
Within the specialization tier, Oatly Group and Green Rebel Foods exemplify divergent positioning strategies. Oatly Group anchors premium oat milk positioning through Jakarta's café channel. Green Rebel Foods occupies a position within the meat substitute segment through localized taste engineering. Nestlé S.A. and Unilever Indonesia represent diversified conglomerates leveraging existing distribution infrastructure and halal certification workflows. PepsiCo Inc. and Danone S.A. sit within the beverage-focused multinational tier, while Beyond Meat and The Kraft Heinz Company exemplify import-dependent positioning subject to BPOM registration timelines. Domestic specialists including Meatless Kingdom compete through accelerated certification pathways and tropical feedstock proximity.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Oatly Group |
| Nestlé S.A. |
| Unilever Indonesia |
| Beyond Meat |
| Green Rebel Foods |
| The Kraft Heinz Company |
| Meatless Kingdom |
| Danone S.A. |
| Others |
Supply & Pricing Matrix
High-moisture extrusion retrofitting in Bekasi and Tangerang industrial zones compresses unit economics for meat analog production while concentrating formulation expertise among a handful of domestic processors. This technological shift simultaneously elevates capital requirements for new entrants and tightens margin structures across the Java manufacturing corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates barista-grade oat milk formulations from commodity coconut beverages and private-label substitutes. Price differentiation rests on BPOM registration status and MUI halal certification tier, with unregistered imports trading at steep discounts. Pricing pressure stems from coconut milk input volatility driven by competing export demand and weather disruption. Food service operators in Jakarta's café corridor exhibit the lowest price sensitivity, while retail consumers in satellite cities prioritize economy-tier formats.
Supply Chain Analysis
Dual-sourcing requirements from multinational food service chains mandate that domestic processors qualify multiple tropical legume suppliers across Indonesia, Vietnam, and Thailand to mitigate crop failure risk. Raw material dependencies center on coconut milk, oat protein isolates, and specialized extrusion equipment from European and East Asian manufacturers. Supply chain risk concentrates in single-source vulnerability for high-moisture extrusion machinery where lead times extend unpredictably. Distribution runs through Java's supermarket networks for bulk volume, with quick-commerce platforms capturing trial-size growth in Surabaya and Bandung.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's plant-based sector functions as a regulatory compounder where the Halal Product Assurance Law's mandatory certification timeline compresses competitive windows and elevates compliant domestic producers above import-dependent rivals.
For Market Incumbents: To counter fermentation-based protein platforms from emerging domestic specialists, Nestlé and Unilever should deepen backward integration into tropical legume processing in East Java while accelerating MUI halal approval workflows for novel ingredient portfolios. Priority investment targets high-moisture extrusion capacity expansion in Gresik industrial estates to capture contract manufacturing volumes from expanding quick-service chains.
For New Entrants and Emerging Players: Quick-commerce channel penetration in Surabaya and Bandung offers the most penetrable route for single-serve trial formats without confronting entrenched supermarket slotting fee structures. White-space targets include protein-fortified beverages for East Java's health-conscious professionals and localized meat substitute formulations for Bali's tourism-dependent food service operators. Go-to-market execution should anchor on instant delivery platform partnerships rather than traditional distributor networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among domestic specialists with accelerated BPOM registration pathways and captive tropical feedstock supply. Long-term viability over the projection horizon favors processors with demonstrated dual certification execution and fermentation technology capabilities. The signal to watch is MUI halal approval velocity for novel enzymatic processing methods as an inflection indicator for competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | BPOM-MUI parallel workflow investment compresses product launch timelines against import-dependent rivals. |
| Fermentation Platform Development | Enzymatic conversion capabilities for tropical legumes reduce sensory gaps and open premium positioning. |
| Quick-Commerce Channel Partnership | Instant delivery density in Surabaya and Bandung enables impulse trial economics for single-serve formats. |
| Backward Integration into Feedstock | Captive coconut and tropical legume supply insulates margin structures from raw material volatility. |
| Food Service Contract Manufacturing | High-moisture extrusion capacity in Java's industrial zones captures volumes from expanding quick-service chains. |
Research Methodology
Direct dialogue with food technologists at Bekasi and Tangerang processors, BPOM registration specialists, MUI halal certification officers, and procurement leads at Jakarta café chains grounded qualitative assessment in operational reality. Secondary validation drew from BPOM food safety filings, Ministry of Health labeling enforcement records, supermarket promotional data, and quick-commerce platform transaction disclosures. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Bottom-up segmentation analysis modeled volume and value trajectories across product type, end user sophistication, distribution channel infrastructure, and application depth throughout the forecast period. Analytical frameworks incorporated protein fortification claim compliance costs, halal certification timeline distributions, and extrusion capacity utilization rates as industry-specific forecast inputs. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion patterns.
The model assumes a particular technology adoption path; alternative pathways for fermentation-based protein platforms would alter the outlook if enzymatic conversion achieves cost parity faster than projected. Forecasts reflect assumptions about BPOM registration efficiency and MUI halal approval standardization that regulatory delays or policy reversals could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Vegan Dips Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Europe Plant-Based Seafood Market