
 North America Textured Vegetable Protein Market | 2026-2036
North America Textured Vegetable Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Textured Vegetable Protein Market Analytics
Buyer consolidation among North American food manufacturers is repositioning procurement leverage toward large-scale textured vegetable protein contracts. Cargill leverages its integrated oilseed processing network to secure feedstock advantages across the Upper Midwest. Archer Daniels Midland Company anchors its position through fermentation and extrusion technology investments in Decatur, Illinois. PURIS differentiates via non-GMO pea protein supply chains that bypass conventional soybean commodity volatility.
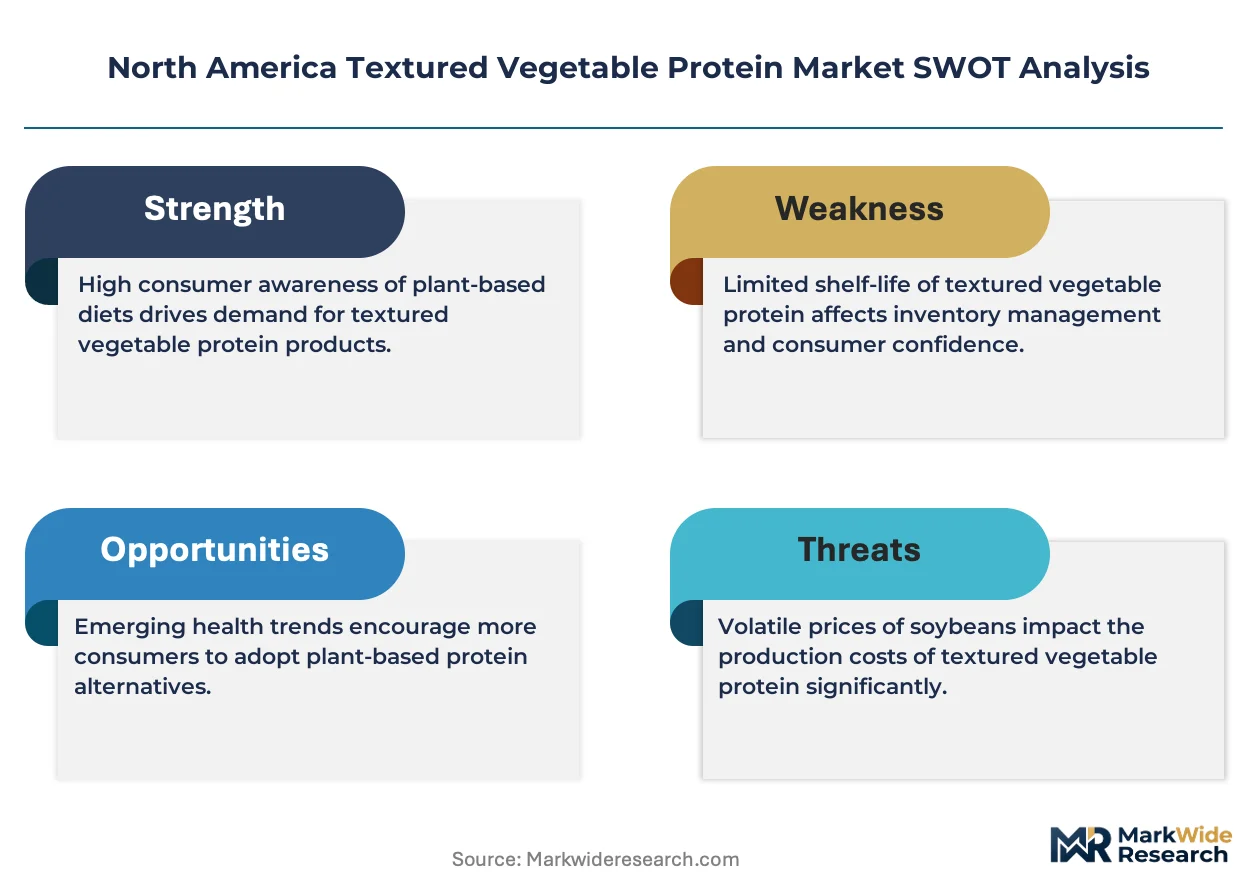
Textured vegetable protein refers to defatted and extruded plant protein isolates, typically processed at moisture levels of 25-35% through thermoplastic extrusion to yield fibrous structures that mimic meat chewiness. The material serves primarily as a functional extender or primary matrix in commercial meat analog production. Soy protein retains the dominant share of extrusion capacity due to decades of infrastructure amortization, though pea protein claims the fastest expansion trajectory as food manufacturers seek allergen-friendly formulations. Meat alternatives command the deepest margin pools among application segments, while snack foods represent a volume growth corridor as extruded protein crisps penetrate convenience retail channels.
The FDA governs protein content claims and allergen labeling under the Food Allergen Labeling and Consumer Protection Act, directly shaping formulation decisions for cross-contamination-sensitive buyers. USDA Food Safety and Inspection Service oversight of plant-based meat labeling creates compliance friction that advantages suppliers with established regulatory affairs capabilities. Health Canada and PMRA coordinate on novel food ingredient assessments, adding a bilateral dimension for cross-border ingredient flows. Stakeholders must monitor how pending protein fortification standards in school nutrition programs could redirect institutional procurement specifications toward specific amino acid profiles.
Market Dynamics
Buyer consolidation among North American food manufacturers is concentrating procurement leverage toward large-scale textured vegetable protein contracts. Cargill leverages its integrated oilseed processing network to secure feedstock advantages across the Upper Midwest. Archer Daniels Midland Company anchors its position through fermentation and extrusion technology investments in Decatur, Illinois. PURIS differentiates via non-GMO pea protein supply chains that bypass conventional soybean commodity volatility.
Growth Catalysts
- USDA Food Safety and Inspection Service plant-based meat labeling oversight:Established regulatory affairs capabilities create compliance advantages for incumbent suppliers serving cross-border ingredient flows.
- Midwest agricultural processing corridor infrastructure:Soy and pea protein extraction facilities cluster in Iowa, Illinois, and Minnesota, reducing logistics costs for regional formulators.
- High-moisture extrusion technology maturation:Thermoplastic extrusion at 25-35% moisture levels now yields fibrous structures that replicate meat chewiness in commercial meat analog production.
Market Restraints
- Soybean commodity price volatility:Defatted soy protein isolate feedstock costs fluctuate with global oilseed markets, compressing margin stability for extrusion-dependent processors.
- Upper Midwest supply concentration:Overreliance on Iowa-Illinois soybean crushing infrastructure creates geographic risk exposure to weather-driven crop yield variability.
- FDA allergen labeling requirements:The Food Allergen Labeling and Consumer Protection Act mandates cross-contamination controls that increase formulation complexity for multi-protein facilities.
Strategic Opportunities
- Canadian Prairie pea protein expansion:Manitoba and Saskatchewan pulse processing infrastructure remains underdeveloped relative to soybean capacity, offering first-mover positioning for allergen-friendly supply chains.
- School nutrition program protein fortification standards:Pending USDA amendments to institutional procurement specifications could redirect amino acid profile requirements toward complete plant proteins.
- Convenience retail extruded protein crisps:Snack food manufacturers are adopting textured vegetable protein as a volume growth corridor separate from meat alternative margins.
Industry Challenges
- Extrusion operator skill scarcity:Thermoplastic extrusion requires specialized process engineering expertise that outpaces technical training program output in the Upper Midwest.
- Health Canada novel food ingredient assessment timelines:Bilateral cross-border ingredient flows face PMRA coordination delays that extend product launch cycles for Canadian market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Textured Vegetable Protein Market |
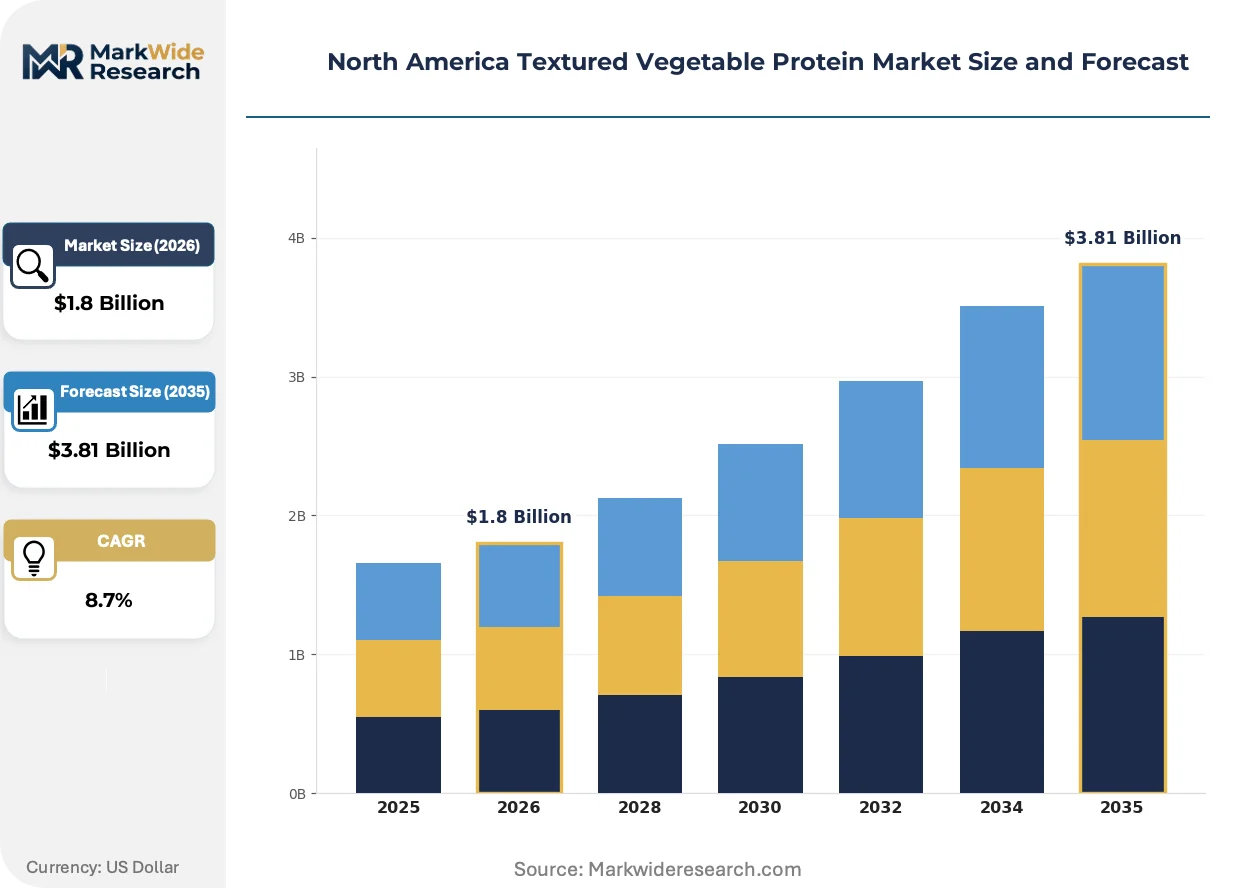
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein, Pea Protein, Wheat Protein, Others Application: Meat Alternatives, Snack Foods, Dairy Alternatives, Bakery Products Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales End User: Restaurants, Food Manufacturers, Grocery Chains, Health-conscious Consumers |
| Companies Covered | Cargill, Archer Daniels Midland Company, Ingredion, Roquette Freres, Bunge Limited, The Scoular Company, PURIS, Axiom Foods, MGP, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Textured Vegetable Protein Market Evolving Landscape
High-moisture extrusion systems are rewriting the technical specifications that separate commodity protein isolates from premium meat analog ingredients. Food manufacturers now specify fibrousness metrics rather than protein content alone.
Shear cell technology is rewriting the capital intensity requirements for meat texture replication. Mid-scale food manufacturers in Texas and California are adopting these systems to bypass multi-million dollar twin-screw extrusion investments. The technology is rewriting competitive positioning by enabling regional production rather than Midwest-centralized supply.
FDA updated guidance on labeling plant-derived proteins is clarifying compliance pathways for ingredient suppliers. The industrial consequence is reduced regulatory friction for cross-contamination-sensitive buyers. Meat alternative formulators in Illinois and California are responding by consolidating supplier relationships with established regulatory affairs capabilities.
Direct procurement contracts between protein extractors and retail foodservice chains are displacing traditional ingredient distributor networks. Large QSR chains in the United States now negotiate amino acid specification contracts directly with PURIS and similar suppliers. This pattern is most visible in the Southwest where regional restaurant groups bypass national distribution for pea protein isolates.
North America Textured Vegetable Protein Market Segmentation
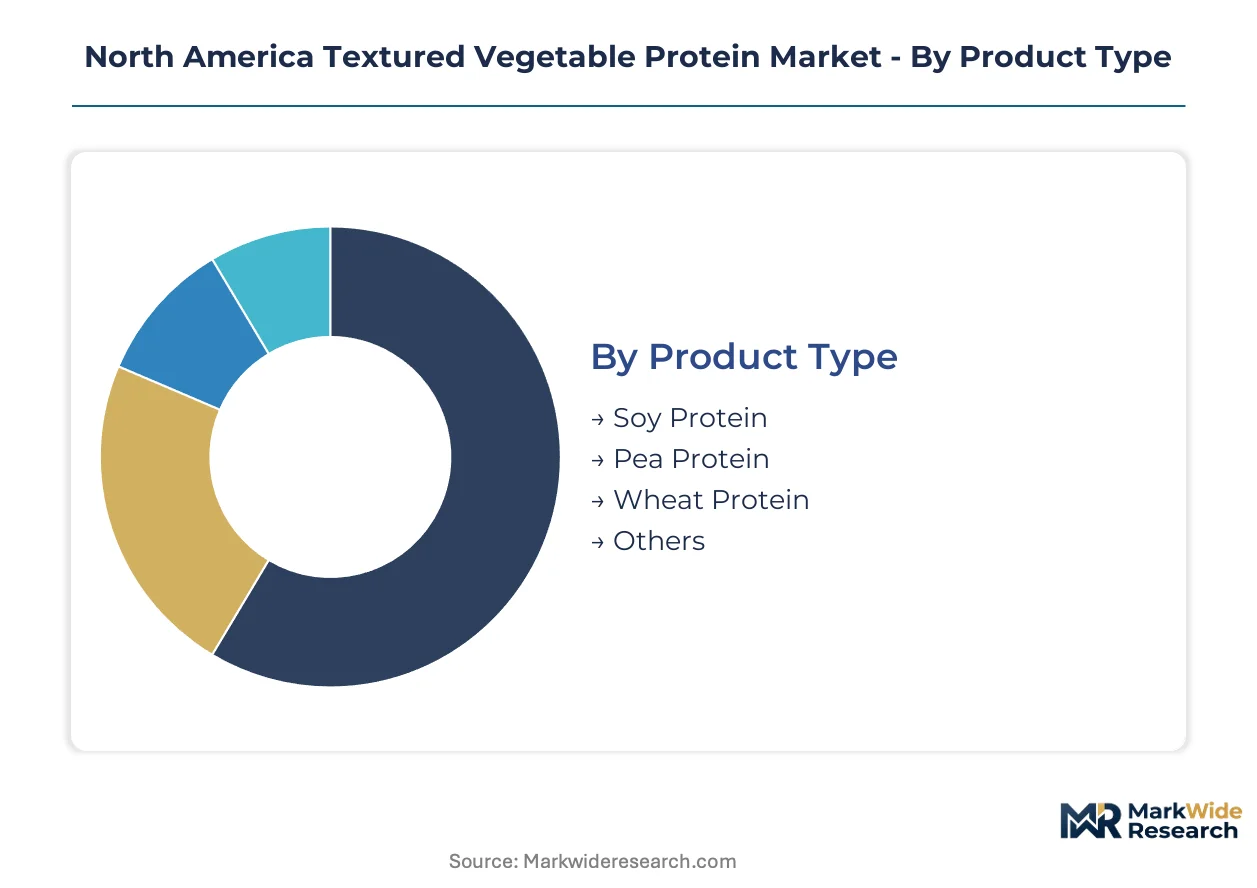
Segmentation in the textured vegetable protein market reveals how supply chain configuration and end-use specifications reshape procurement patterns. Protein type determines feedstock geography and extrusion economics, while application segments impose distinct functional requirements on fiber structure and moisture retention.
Product Type:
Supply concentration in the Upper Midwest soybean crushing corridor dominates protein isolate availability and pricing dynamics.
- Soy Protein:Defatted soy protein isolate processed through twin-screw extrusion at 25-35% moisture levels yields the fibrous matrices required for commercial meat analogs. Iowa and Illinois crushing facilities supply North American formulators with established allergen management protocols under FDA Food Allergen Labeling and Consumer Protection Act requirements.
- Pea Protein:Non-GMO yellow pea isolates bypass soybean commodity volatility through Canadian Prairie sourcing. PURIS and similar suppliers anchor supply chains in Minnesota and Manitoba, targeting allergen-sensitive buyers with complete amino acid profiles.
- Wheat Protein:Vital wheat gluten provides elastic texture in bakery and seitan applications, sourced from Kansas and North Dakota milling corridors.
- Others:Fava bean and lentil proteins emerge from Saskatchewan pulse processing trials for specialized nutrition formulations.
Soy protein absorbs the bulk of installed capacity; pea protein is expanding most quickly.
Application:
Margin structures diverge sharply between premium meat analog formulations and high-volume snack extrusion.
- Meat Alternatives:High-moisture extrusion systems replicate meat chewiness through controlled thermoplastic deformation. Food manufacturers in California and Illinois specify fibrousness metrics and water-holding capacity for burger and sausage matrices.
- Snack Foods:Extruded protein crisps penetrate convenience retail channels with lower barrier-to-entry equipment requirements. Texas and Arizona manufacturers adopt shear cell technology to bypass multi-million dollar extrusion investments.
- Dairy Alternatives:Textured proteins provide body and mouthfeel in plant-based cheese and yogurt analogs.
- Bakery Products:Wheat and pea protein isolates fortify bread and pastry applications with enhanced protein content claims.
Meat alternatives command the deepest margin pools; snack foods represent the steepest volume expansion trajectory.
Distribution Channel:
Direct procurement contracts are displacing traditional ingredient distributor networks for large-scale buyers.
- Online Retail:E-commerce platforms serve health-conscious consumers and small-batch formulators with specialized isolate grades and smaller minimum order quantities.
- Supermarkets:Mass retail channels move commodity-grade textured vegetable protein for home cooking applications.
- Health Food Stores:Premium non-GMO and organic certified proteins target allergen-aware households in coastal urban markets.
- Direct Sales:Large QSR chains negotiate amino acid specification contracts directly with protein extractors, bypassing national distribution networks.
Direct sales capture the largest contract values; online retail is climbing the fastest among emerging channels.
End User:
Buyer consolidation among North American food manufacturers concentrates procurement leverage toward multi-year supply agreements.
- Food Manufacturers:Cargill, Archer Daniels Midland, and mid-scale extrusion operators in Illinois and Iowa anchor demand for industrial-grade isolates with consistent specification tolerances.
- Restaurants:Regional restaurant groups in the Southwest negotiate direct pea protein procurement for menu development.
- Grocery Chains:Private label meat alternative programs drive volume contracts with established regulatory affairs capabilities.
- Health-conscious Consumers:Direct-to-consumer brands target home cooks with rehydratable textured vegetable protein chunks and crumbles.
Food manufacturers absorb the bulk of procurement volume; restaurants are gaining share fastest through direct sourcing relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean crushing corridors in Iowa and Illinois anchor North American textured vegetable protein supply, with pea protein extraction expanding across Minnesota and the Canadian Prairies. Regional procurement patterns track feedstock geography and extrusion infrastructure density.
United States
Midwestern food manufacturers in Decatur, Illinois and Cedar Rapids, Iowa drive demand for high-moisture extrusion systems that replicate meat fibrousness. The FDA's Food Allergen Labeling and Consumer Protection Act shapes formulation decisions for cross-contamination-sensitive buyers. California and Texas formulators adopt shear cell technology to bypass centralized Midwest supply chains.
Canada
Manitoba and Saskatchewan pulse processors expand yellow pea isolate capacity to serve allergen-friendly formulation trends. Health Canada and PMRA coordinate novel food ingredient assessments that extend product launch timelines for cross-border ingredient flows. Prairie protein extraction infrastructure remains underdeveloped relative to soybean capacity, attracting first-mover investment.
Mexico
QSR chains and retail foodservice operators in Mexico City Metro and Nuevo León negotiate direct procurement contracts with North American protein extractors. Mexican food safety regulators align with FDA guidance on plant-derived protein labeling to facilitate import compliance. Bajío Region food manufacturers pilot extruded protein applications for domestic snack markets.
North America Textured Vegetable Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty non-GMO and organic certification positioning. The vendor base clusters around integrated agribusiness conglomerates with captive oilseed processing networks and mid-scale pea protein specialists with regional sourcing advantages. Three archetypes dominate: upstream-integrated crushers with extrusion capabilities, pea protein specialists with Prairie supply chains, and ingredient distributors with regulatory affairs infrastructure. Competitive moves concentrate on backward integration into protein isolate production and direct contracting relationships with large QSR chains.
Among upstream-integrated agribusinesses, Cargill and Archer Daniels Midland Company anchor the standard tier through Midwest oilseed processing networks and extrusion technology investments. PURIS occupies a distinct position within the specialty tier, exemplifying non-GMO pea protein supply chain differentiation that bypasses conventional soybean commodity volatility. These three entities represent the structural tension between scale-driven crushing economics and specialty protein premium positioning.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Ingredion |
| Roquette Freres |
| Bunge Limited |
| The Scoular Company |
| PURIS |
| Axiom Foods |
| MGP |
| Others |
Value Network & Pricing Analysis
Chicago Board of Trade soybean futures cascade through defatted protein isolate pricing, compressing margin tiers as commodity volatility transmits from Iowa crushing facilities to extrusion-dependent processors across the Upper Midwest.
Pricing Analysis
Regulatory compliance bundling separates premium-tier suppliers with established FDA Food Allergen Labeling and Consumer Protection Act protocols from unbundled economy grades lacking cross-contamination documentation. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with large QSR chains capturing standard-tier discounts through direct amino acid specification contracts. Cost compression in economy-tier commodity isolates is intensifying because soybean feedstock volatility transmits directly from CBOT futures into processor margins. Food manufacturers with multi-protein facilities demonstrate highest price sensitivity due to formulation complexity overhead, while specialized meat alternative formulators absorb premium pricing for documented allergen controls.
Supply Chain Analysis
Regional distribution centers in Decatur, Illinois and Cedar Rapids, Iowa anchor hub-and-spoke patterns serving extrusion facilities across the Midwest agricultural processing corridor. Supply concentrates in the United States and Canada, with raw material dependencies on Iowa-Illinois soybean crushing, Minnesota pea protein extraction, and Manitoba pulse processing infrastructure. Single-source vulnerability in Upper Midwest soybean crushing infrastructure creates geographic risk exposure to weather-driven crop yield variability. Distribution runs through direct procurement contracts between protein extractors and retail foodservice chains, displacing traditional ingredient distributor networks for large-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extrusion operator skill scarcity across the Upper Midwest props pricing power for incumbent processors with captive technical training pipelines.
For Market Incumbents: To counter shear cell technology disruption from Texas and California regional producers, anchor market position through backward integration into Canadian Prairie pea protein extraction capacity and deepen regulatory affairs infrastructure for cross-border Health Canada coordination. For New Entrants and Emerging Players: E-commerce platforms for health-conscious consumers and small-batch formulators offer the most penetrable entry vector, targeting allergen-aware households in coastal urban markets with specialized isolate grades and smaller minimum order quantities as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale pea protein specialists with Prairie supply chain positioning in Manitoba and Saskatchewan; the inflection signal to watch is USDA amendment timing for school nutrition program protein fortification standards that would redirect institutional procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Captures premium meat analog margins as PURIS and ADM scale fibrousness-metric specifications. |
| Canadian Prairie Pea Protein Backward Integration | Secures non-GMO supply chains bypassing soybean commodity volatility for allergen-friendly formulations. |
| Direct QSR Chain Supply Agreements | Displaces distributor networks as Southwest restaurant groups negotiate amino acid specification contracts. |
| Regulatory Affairs Infrastructure Investment | Reduces compliance friction for FDA Food Allergen Labeling and Consumer Protection Act cross-contamination controls. |
| Shear Cell Technology Regional Deployment | Enables Texas and California production bypassing Midwest-centralized supply chain concentration. |
Research Methodology
Document review covered FDA guidance documents, USDA Food Safety and Inspection Service labeling directives, Health Canada novel food assessments, and SEC 10-K filings from integrated agribusiness conglomerates, complemented by interviews with extrusion process engineers, procurement leads at North American food manufacturers, regulatory affairs specialists, and QSR chain supply chain directors. Secondary validation drew from trade association publications, customs records for cross-border ingredient flows, and agricultural commodity exchange data. Bottom-up capacity utilization estimates triangulated against top-down market sizing from protein isolate production volumes.
Cross-referencing historical extrusion capacity deployment patterns against panel input from equipment manufacturers and ingredient formulators anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include protein type, application segment, distribution channel, and end-user procurement scale, with CAGRs derived from capacity expansion announcements and feedstock price trajectory assumptions. Industry-specific forecast inputs incorporated high-moisture extrusion technology maturation curves and shear cell adoption rates in regional production clusters.
The model holds under stable regulatory interpretation of plant-derived protein labeling; deviation in FDA or Health Canada novel food assessment timelines would shift cross-border ingredient flow assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
Veggie Burger Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Tempeh Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Plant-Based Wafer Biscuits Market
Plant Based Food
Insoluble Pea Protein Market