
 Plant-Based Snacks Market | 2026-2036
Plant-Based Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Snacks Market Intelligence
The European Union's Farm to Fork strategy, which promotes sustainable food systems, is broadening the addressable market for plant-based alternatives. Nestlé leverages its extensive distribution network to introduce plant-based snack options across global retail channels. Kellanova competes through brand recognition in the crackers and bars segments, adapting its portfolio to new ingredient sources. Conagra Brands differentiates with its focus on frozen and savory snack innovations.
Plant-based snacks are food products formulated exclusively from non-animal sources, including fruits, vegetables, legumes, nuts, and grains. Processing often involves extrusion, baking, or dehydration to achieve specific textures and shelf stability without animal-derived additives. Pea protein and chickpea are gaining share as primary ingredient sources, displacing traditional soy in certain applications. Within product types, plant-based jerky and functional bars represent high-margin categories, while chips and crackers command the largest volume.
Labeling and allergen regulations from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern product marketing claims. In China, GB standards for food additives and contaminants set strict parameters for market entry and product formulation. Navigating the patchwork of international food safety and labeling laws remains a critical competency for manufacturers seeking to expand their geographic footprint.
Market Dynamics
The central force shaping the market is the consumer demand for healthier, sustainable food options clashing with a fragmented global regulatory environment. This creates operational friction for brands attempting to scale internationally while meeting divergent labeling and ingredient standards.
Growth Catalysts
- EU Regulatory Frameworks:The European Union's Farm to Fork strategy encourages sustainable food production and consumption, creating a favorable policy environment and expanding the market for plant-based snacks that align with its goals.
- Flexitarian Consumer Base:A growing cohort of flexitarian consumers in developed economies, particularly the United States and Germany, is seeking plant-based snacks as a partial replacement for animal products without full dietary conversion.
- Ingredient Innovation:The commercialization of novel protein sources, such as pea protein and chickpea flour, provides alternatives to soy and enables the development of new product textures and nutritional profiles in snacks.
Market Restraints
- Input Cost Volatility:The price of key ingredients like pea protein isolate can be volatile and significantly higher than traditional commodity inputs, creating cost pressure for manufacturers and impacting final retail prices.
- Regulatory Patchwork:Navigating the disparate food safety and labeling regulations from bodies like the FDA, EFSA, and China's SAMR increases compliance costs and complicates market entry for brands seeking a global footprint.
- Sensory Parity Challenges:Achieving taste and texture parity with traditional animal-based snacks, particularly in categories like jerky and cheese-flavored crisps, remains a significant technical hurdle that can limit broader consumer adoption.
Strategic Opportunities
- Geographic Expansion:Untapped demand in urban centers across Southeast Asia and Latin America presents a significant growth opportunity as incomes rise and Western dietary patterns gain influence.
- Functional Snack Development:There is a market white space for snacks fortified with functional ingredients like probiotics, adaptogens, or extra fiber, appealing to health-conscious consumers seeking benefits beyond basic nutrition.
- Channel Diversification:Expansion into non-traditional retail channels, including corporate micro-markets, healthcare facilities, and travel hubs, offers new avenues to reach consumers outside of conventional grocery stores.
Industry Challenges
- Supply Chain Scalability:The supply chains for emerging ingredients like fava bean and chickpea protein are not yet scaled to meet potential mass-market demand, creating bottlenecks and risks for manufacturers.
- Allergen Management Complexity:Managing cross-contamination risks for common allergens such as nuts, soy, and gluten in multi-product facilities requires stringent operational protocols and investment, governed by FDA and EFSA rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Snacks Market |
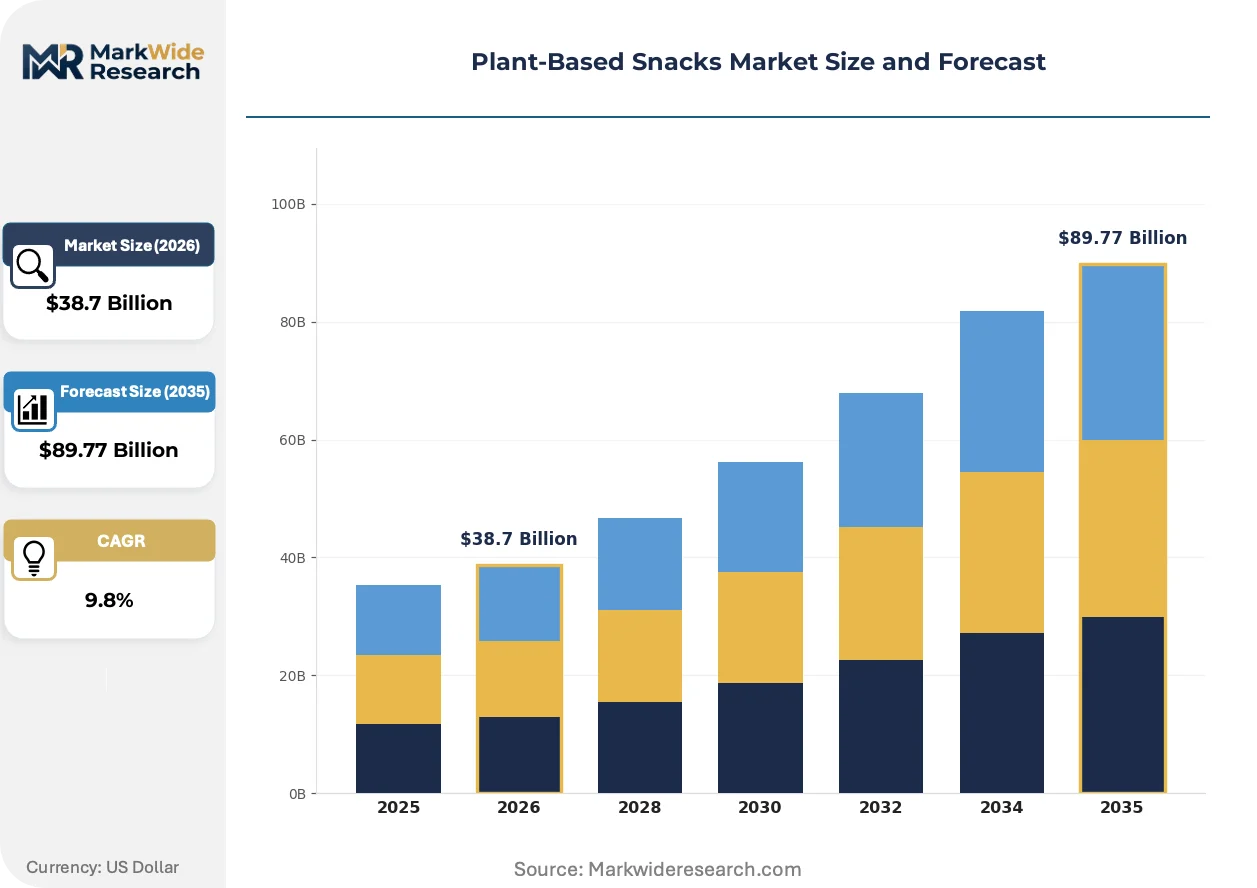
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $89.77 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Bars, Crackers, Nuts & Seeds, Popcorn, Jerky Ingredient Source: Pea Protein, Soy, Chickpea, Lentil, Rice, Quinoa Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Convenience Stores, Specialty Stores, Direct-to-Consumer Consumer Demographic: Vegans, Flexitarians, Health-Conscious Adults, Athletes, Millennials, Parents |
| Companies Covered | The Hain Celestial Group, Kraft Heinz, Nestlé, Amy’s Kitchen, General Mills, Kellanova, Maple Leaf Foods, Good Eat’n, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Snacks Market Strategic Shifts & Innovations
The market's evolution is defined by the intersection of food science, which is unlocking new ingredient possibilities, and shifting consumer ethics around health and sustainability. These forces are compelling brands to innovate beyond simple plant-based formulations toward cleaner labels and enhanced functionality.
Advanced extrusion and protein isolation techniques are being adopted by food technologists to replicate the fibrous textures of animal-based products. Food and beverage manufacturers are rapidly integrating these methods to expand their portfolios beyond basic chips and bars into more complex snack formats. This technology is modularizing product development, allowing formulators to interchange protein bases like pea or fava bean with different flavor systems to rapidly launch customized products for niche consumer segments.
European Union regulations promoting front-of-pack nutrition labeling (FOPNL), such as the Nutri-Score system, are directly influencing product design. This pressure forces manufacturers to reformulate products by lowering sodium, sugar, and saturated fat to achieve a more favorable score. The functional bars and savory snacks categories are most affected, spurring investment in alternative sweeteners and processing techniques that preserve taste while improving the nutritional profile.
A distinct behavioral shift toward "clean label" purchasing is gaining momentum, with consumers actively scrutinizing ingredient lists for simple, recognizable components. This trend disrupts legacy CPG models that rely on artificial additives for flavor and shelf stability, creating an opening for brands that emphasize minimal processing. This purchasing pattern is most pronounced among consumers in North America and Europe, shaping both e-commerce and physical retail assortments.
Plant-Based Snacks Market Segmentation
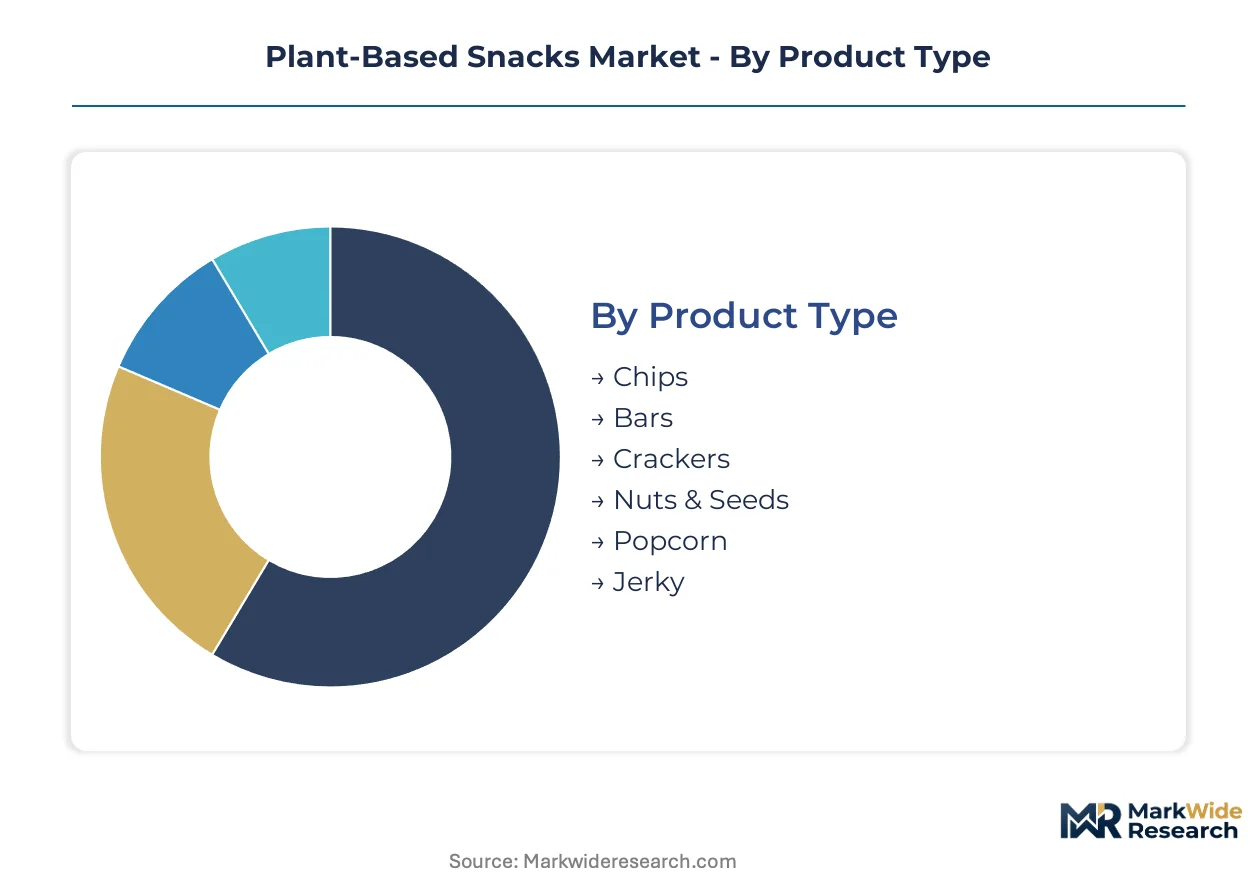
The segmentation of the plant-based snacks market provides a granular view of consumer preferences, ingredient innovation, and strategic distribution avenues. Understanding these distinct segments helps manufacturers tailor product development and market entry strategies to specific consumer needs and operational realities.
Product Type:
Buyers of plant-based snacks often prioritize specific product formats based on consumption occasion, nutritional goals, and texture preferences.
- Chips:These are typically thin slices of vegetables or legumes, often baked or dehydrated, offering a crunchy texture for savory snacking occasions. Demand concentrates in developed markets like the United States, driven by consumer preference for familiar snack formats with a healthier profile.
- Bars:Formulated with various plant proteins, nuts, and seeds, these products provide convenient, nutrient-dense options for on-the-go consumption or meal replacement. Functional bars fortified with adaptogens or probiotics are gaining traction among health-conscious consumers in Europe.
- Crackers:These baked, savory items serve as a versatile base for spreads or as standalone snacks, often made from ancient grains or legume flours.
- Nuts & Seeds:Minimally processed almonds, cashews, pumpkin seeds, and sunflower seeds offer natural protein and healthy fats.
- Popcorn:Air-popped or oil-popped corn kernels provide a light, whole-grain snack, often flavored with plant-based seasonings.
- Jerky:Plant-based jerky replicates the chewy texture of traditional meat jerky, typically using mushrooms, soy, or jackfruit as a base.
Chips lead volumes today; plant-based jerky is gaining share fastest.
Ingredient Source:
Supply chain dynamics and consumer perceptions of ingredient quality heavily influence the sourcing strategies for plant-based snack manufacturers.
- Pea Protein:This ingredient is extracted from yellow peas, offering a complete protein profile and a neutral flavor, making it versatile for various snack applications. Its commercialization is expanding rapidly in North America as an alternative to soy, appealing to allergen-sensitive consumers.
- Chickpea:Chickpea flour and protein are increasingly used for their nutritional value, mild flavor, and ability to create desirable textures in baked goods and extruded snacks. European Union manufacturers are integrating chickpea into crackers and crisps for its sustainable cultivation profile.
- Soy:A traditional and cost-effective plant protein, soy remains a staple in many plant-based snack formulations due to its functional properties.
- Lentil:Lentil flour provides a nutrient-dense base for crisps and puffs, contributing fiber and protein to snack products.
- Rice:Rice protein and rice flour are utilized for their hypoallergenic properties and ability to create light, crispy textures in snacks.
- Quinoa:This ancient grain is valued for its complete protein content and is incorporated into bars and baked snacks for added nutrition.
Soy remains a foundational ingredient; pea protein is experiencing the most rapid expansion.
Distribution Channel:
Effective customer access strategies determine market penetration for plant-based snack brands across diverse retail environments.
- Supermarkets & Hypermarkets:These large-format stores offer extensive shelf space and broad consumer reach, serving as the primary channel for mass-market plant-based snack distribution. Consumers in Germany frequently purchase new plant-based snack innovations from these large retail formats.
- Online Retailers:E-commerce platforms provide convenience and a wide selection, enabling niche brands to reach consumers directly and facilitating subscription models for recurring purchases. This channel is critical for new product launches in the United States, offering direct consumer feedback.
- Convenience Stores:These smaller retail outlets cater to immediate consumption needs, stocking single-serve plant-based snacks for on-the-go consumers.
- Specialty Stores:Health food stores and organic markets offer curated selections of premium and artisan plant-based snacks, appealing to discerning consumers.
- Direct-to-Consumer:Brands leverage their own websites to sell products directly, fostering brand loyalty and collecting valuable customer data.
Supermarkets and hypermarkets maintain the largest footprint; online retailers are expanding most quickly.
Consumer Demographic:
Purchasing motivations and lifestyle choices significantly segment the consumer base for plant-based snacks.
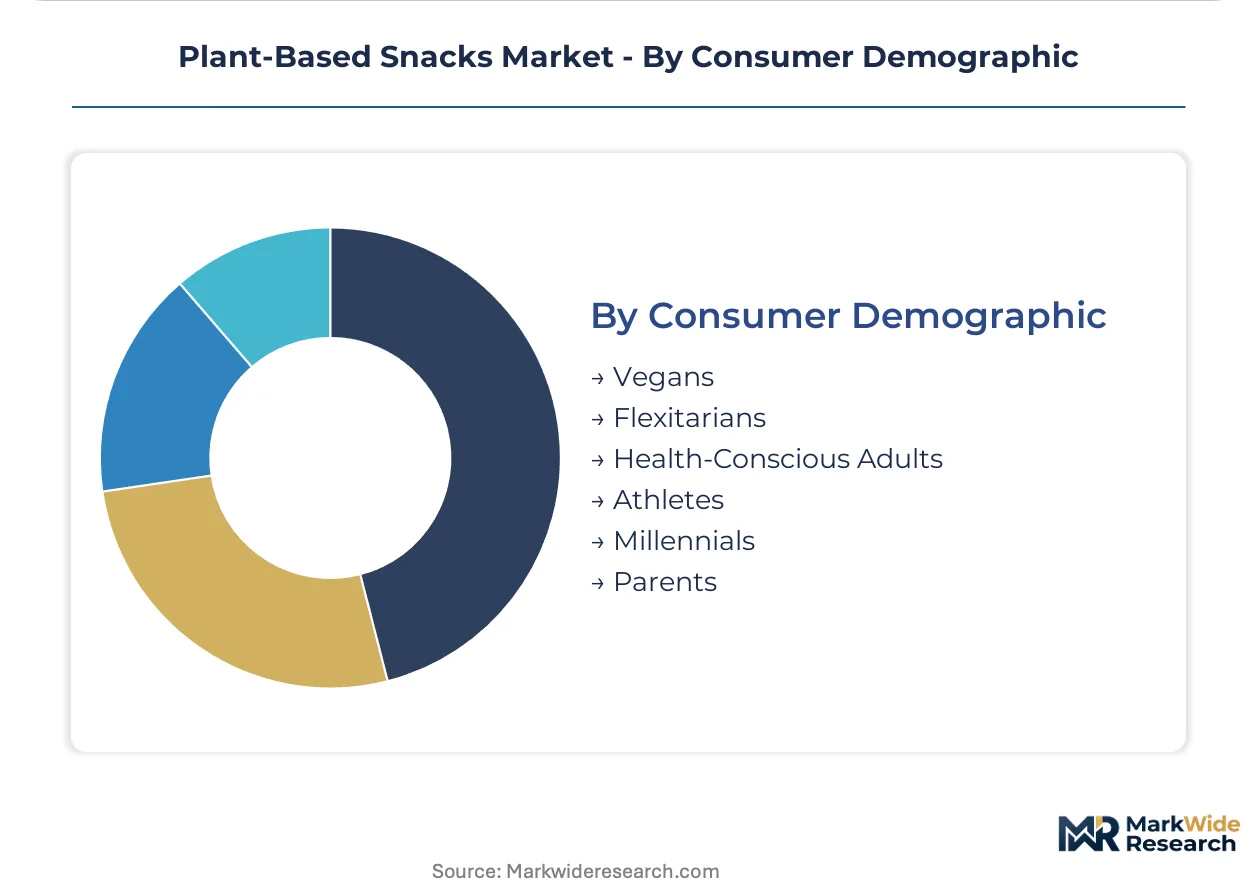
- Flexitarians:This group consciously reduces animal product consumption without fully eliminating it, seeking plant-based snacks as healthier alternatives within their existing diets. Flexitarian consumers in the United States represent a significant growth catalyst for the broader plant-based category.
- Health-Conscious Adults:Individuals prioritizing nutritional benefits, clean labels, and functional ingredients drive demand for plant-based snacks that align with their wellness goals. This demographic actively scrutinizes ingredient lists, particularly in urban centers across Europe.
- Vegans:Strict plant-based consumers require products free from all animal-derived ingredients, driving demand for certified vegan snack options.
- Athletes:Individuals engaged in regular physical activity seek plant-based snacks for protein recovery and sustained energy without animal products.
- Millennials:This generation demonstrates a strong preference for sustainable, ethically sourced, and health-oriented food choices.
- Parents:Parents seek nutritious, allergen-friendly plant-based snack options for their children, focusing on simple ingredients.
Health-conscious adults represent the largest segment; flexitarians exhibit the most dynamic purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plant-based snacks market first gained significant traction and scaled within Western economies, driven by evolving dietary preferences and health consciousness. Early innovation in product formulation and consumer acceptance primarily occurred in developed nations. This foundational growth established a blueprint for global expansion, influencing diverse regional markets.
United States
Demand for healthier alternatives and flexitarian diets drives consumption across American households. The U.S. Food and Drug Administration (FDA) regulates labeling and allergen claims, ensuring consumer safety and product transparency. California's Silicon Valley and major urban centers like New York City showcase significant innovation in plant-based food startups and product launches.
Germany
Flexitarian consumer bases and strong sustainability initiatives propel plant-based snack adoption across German retail channels. The European Union's Farm to Fork strategy directly influences product development and marketing efforts, encouraging sustainable sourcing. Berlin's vibrant startup ecosystem and major retail chains frequently introduce new plant-based snack innovations to the market.
China
Rising disposable incomes and Western dietary influences contribute to expanding demand for convenient plant-based snacks within China. China's GB standards for food additives and contaminants set strict market entry parameters for international manufacturers. Urban centers like Shanghai and Beijing are experiencing increased availability of diverse plant-based snack options in supermarkets and online platforms.
India
Health awareness and traditional vegetarian diets create a natural affinity for plant-based options among Indian consumers. The Food Safety and Standards Authority of India (FSSAI) governs food product standards and labeling, ensuring compliance. Bengaluru's tech hub and Mumbai's metropolitan areas see a growing demand for convenient, nutritious plant-based snacks.
Canada
Consumer interest in sustainable and allergen-friendly food choices fuels plant-based snack market expansion across Canadian provinces. Health Canada regulates food labeling and nutritional claims, impacting product formulation and marketing messages. Toronto and Vancouver serve as key distribution hubs, introducing diverse plant-based snack brands to the broader Canadian market.
Plant-Based Snacks Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and brand differentiation in the plant-based snacks market. This market exhibits a tiered structure, with established food conglomerates competing against agile, specialized plant-based brands. Strategic archetypes include large CPG companies leveraging existing distribution, niche innovators focusing on functional ingredients, and ingredient suppliers vertically integrating into finished products. Dominant competitive moves involve portfolio diversification into new plant-based formats and strategic partnerships for ingredient sourcing and technology transfer.
At the scale-driven end, Nestlé exemplifies large multinational corporations leveraging extensive distribution networks to introduce plant-based snack options globally, reflecting broad market reach. Kellanova represents established consumer packaged goods companies adapting their existing brand recognition in crackers and bars to new plant-based ingredient sources, maintaining consumer familiarity. Conagra Brands further illustrates the strategy of differentiating through innovation, particularly in frozen and savory plant-based snack formats, appealing to evolving taste preferences. These companies collectively shape the competitive dynamics through their varied approaches to market penetration and product development.
| Leading Market Players |
|---|
| The Hain Celestial Group |
| Kraft Heinz |
| Nestlé |
| Amy’s Kitchen |
| General Mills |
| Kellanova |
| Maple Leaf Foods |
| Good Eat’n |
| Conagra Brands |
| Others |
Cost & Logistics Intelligence
Vertical integration into ingredient processing anchors both supply security and pricing power for large plant-based snack manufacturers. This strategic choice influences both the cost structure and the final retail price points across diverse product categories.
Pricing Analysis
Tiered pricing stratifies across premium, standard, and economy levels for plant-based snacks. Brand premium for functional bars and the quality grade of novel protein sources drive significant price differentiation. Input cost volatility, particularly for pea protein isolate, creates upward pressure on manufacturing expenses. Health-conscious adults demonstrate lower price sensitivity for products with clean labels, while volume-driven consumers of chips exhibit higher price sensitivity.
Supply Chain Analysis
Mass market distribution through supermarkets and hypermarkets characterizes the downstream supply chain for plant-based snacks. Geographic supply concentration for key ingredients includes North America for pea protein and the European Union for chickpea. Raw material dependencies center on pea protein, chickpea, and soy. Supply chain scalability for emerging ingredients like fava bean protein presents a structural risk. Online retailers also form a critical distribution channel for niche brands and new product launches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant-based snacks market signals a late-cycle quality story, driven by consumer demand for cleaner labels and enhanced functionality. This shift prioritizes ingredient transparency and nutritional benefits over basic plant-based claims.
For Market Incumbents:Deepen vertical integration into novel protein sourcing to mitigate input cost volatility and secure supply for mass-market offerings. Diversify product portfolios into functional snack categories, leveraging existing distribution networks to counter the threat from agile niche innovators. Invest in R&D for advanced protein processing techniques, aiming for superior taste and texture parity with traditional snacks. Focus on achieving favorable Nutri-Score ratings in Europe through reformulation efforts.
For New Entrants and Emerging Players:The European Union's Farm to Fork strategy in Europe opens a window for specialized brands focusing on sustainable and nutritionally superior plant-based snacks. Target the market white space for functional snacks fortified with adaptogens or probiotics, appealing to health-conscious adults in urban centers. Focus geographic expansion on underpenetrated urban centers in Southeast Asia. A direct-to-consumer model with subscription options offers a viable go-to-market angle for building brand loyalty.
For Investors and Strategic Acquirers:Roll-up economics work for specialized plant-based snack brands because structural fragmentation across ingredients and niche product types creates consolidation opportunities. The market offers strong long-term viability, anchored by persistent health and sustainability trends. Identify acquisition targets that possess proprietary ingredient technology or strong clean label appeal. Sustained growth in functional bar and plant-based jerky categories serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Ingredient R&D | Develops proprietary protein sources for taste and texture parity, reducing reliance on volatile commodities. |
| Channel Diversification into Micro-Markets | Expands reach beyond traditional retail, capturing on-the-go consumers in corporate and healthcare settings. |
| Sustainable Sourcing Certification | Appeals to ethically-driven consumers, enhancing brand reputation and market differentiation in Europe. |
| Functional Snack Portfolio Expansion | Addresses demand from health-conscious consumers seeking benefits beyond basic nutrition, increasing average transaction value. |
| Localized Product Formulation | Adapts snack profiles to regional taste preferences and regulatory standards, facilitating market entry in Asia. |
Research Approach
Direct dialogue with R&D specialists, supply chain managers, retail category buyers, and food technologists informed primary insights. This primary research was validated against secondary data sources, including FDA filings, EFSA reports, industry association publications, and financial reports of major CPG companies. A blend of bottom-up and top-down triangulation ensured data accuracy.
The quantitative model produced volume and value projections across the analysis window, integrating market dynamics and historical performance. Segmentation dimensions modeled included product type, ingredient source, distribution channel, and consumer demographic. Compound annual growth rates were derived from regression analysis of historical data and projected growth drivers, incorporating inputs like pea protein price volatility and flexitarian consumer base expansion.
Revisions become necessary when significant shifts in consumer dietary preferences, regulatory landscapes, or ingredient supply chain stability materialize. Forecasts reflect underlying assumptions regarding technological advancements and market acceptance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Snacks Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Seafood Snacks Market
Snacks
Germany Snack Bar Market
Snacks
Vegan Snacks Market
Snacks
Packaged Rice Snacks Market
Snacks
UAE Snack Bar Market
Snacks
Gluten Free Snacks Market
Snacks
Spain Snack Bar Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
US Potato Chips Market
Snacks
South Africa Snack Bar Market
Snacks
RTE Popcorn Market
Snacks
Trail Mix Market
Snacks
North America Baked Chips Market