
 Europe Plant-Based Food Market | 2026-2036
Europe Plant-Based Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plant-Based Food Market Intelligence
Food service buyers is rotating toward flexitarian consumers as the dominant demand archetype in Europe, overtaking traditional vegetarian segments in volume contribution. Oatly Group AB leverages its Nordic manufacturing base to sustain oat-milk dominance across retail and café channels. Danone SA anchors its European position through fermented plant-based yogurt and specialized nutrition formats. Nestlé SA extends its portfolio breadth across frozen meals and shelf-stable alternatives, competing on scale and distribution density.
Europe plant-based food comprises formulated products derived from isolated or whole-plant proteins, lipid systems, and stabilizer matrices designed to replicate the sensory and nutritional profiles of animal-derived foods, with protein content typically ranging from ten to twenty grams per serving and processing temperatures controlled to prevent off-flavor development in legume bases. These products serve commercial food manufacturing, food service procurement, and direct retail consumption as lower-environmental-impact alternatives to conventional animal agriculture. Dairy alternatives lead current revenue pools given oat and almond milk penetration in refrigerated cases, while meat alternatives represent the fastest-expanding category as extrusion and shear-cell technologies improve texture fidelity. Pea protein isolates are displacing soy in premium formulations amid allergen-labeling preferences and non-GMO positioning strategies.
The EU Green Deal and Farm to Fork Strategy mandate carbon-footprint disclosure and sustainable sourcing benchmarks that reshape ingredient procurement and product-labeling requirements for market access. EFSA evaluates novel protein safety claims and nutrient-bioavailability data, influencing which formulations achieve health-positioning approval on packaging. REACH compliance governs extraction solvents and processing aids used in protein isolation, adding compliance layers for ingredient suppliers. Stakeholders must monitor evolving protein-origin traceability rules and carbon-border adjustment mechanisms to secure formulation continuity and retail listing security.
Market Dynamics
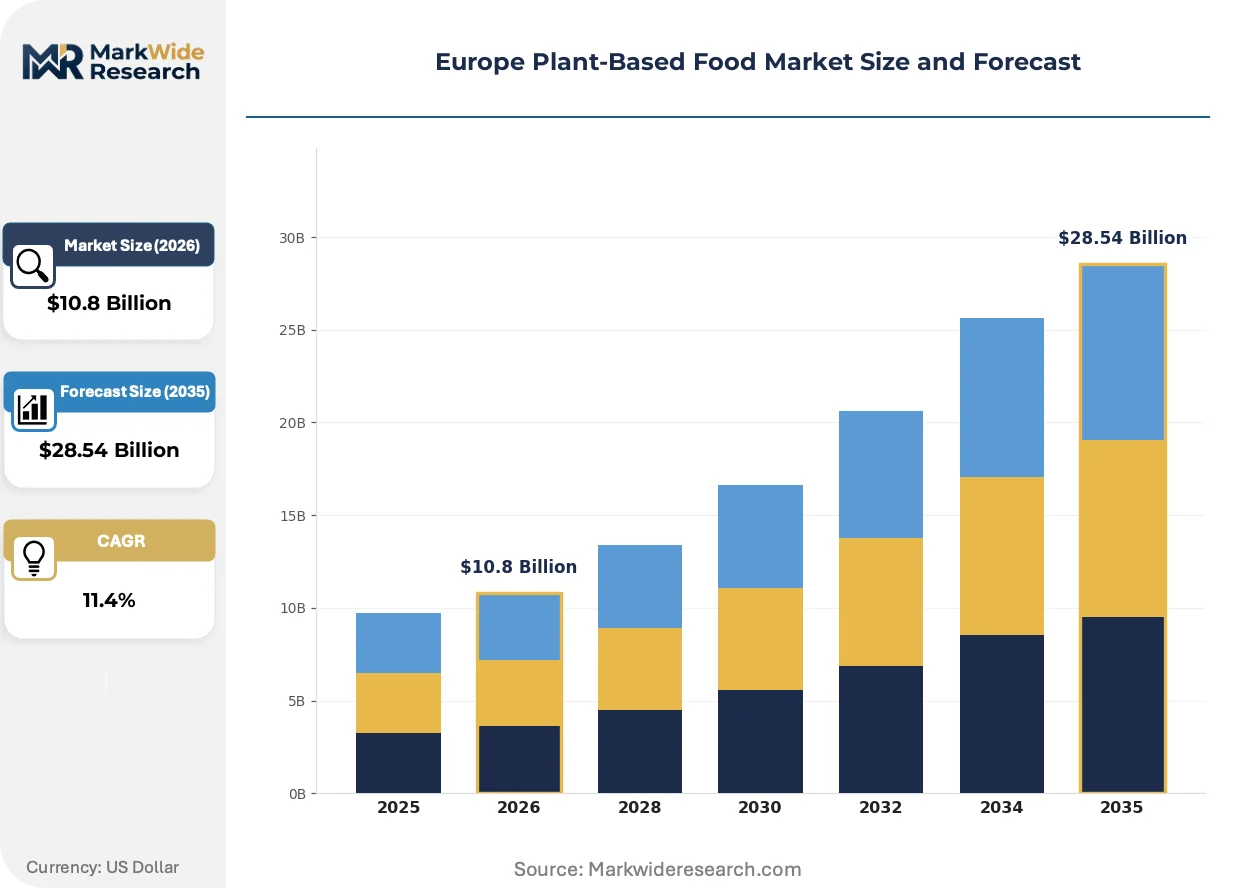
EU Green Deal carbon-disclosure mandates are forcing accelerated reformulation cycles across European food manufacturers, compressing time-to-market for clean-label plant-based alternatives while EFSA novel-protein safety evaluations gate health-positioning claims.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory sustainable-sourcing benchmarks are redirecting procurement budgets toward verified low-carbon ingredient suppliers, expanding addressable market for reformulated plant proteins.
- Quick-service restaurant chains:Institutional cafeterias and fast-casual operators are rotating menu engineering toward flexitarian-dominant demand archetypes, creating volume pull for textured vegetable protein applications.
- Shear-cell technology:Extrusion process innovations are improving muscle-fiber replication in meat alternatives, enabling sensory parity that converts skeptical meat-reducing consumers.
Market Restraints
- Pea protein isolate supply:Concentrated processing capacity in France and Netherlands creates input-cost volatility when harvest conditions disrupt raw-material flows.
- REACH solvent compliance:ECHA-mandated extraction-aid restrictions add certification layers for ingredient suppliers, extending qualification timelines for new protein sources.
- Whole-food cooking:Unprocessed legume and grain preparation retains cost and cultural preference advantages in Southern European household consumption, limiting processed-alternative penetration.
Strategic Opportunities
- Eastern European retail:Poland and Romania exhibit underpenetrated refrigerated-case distribution for oat-milk and fermented yogurt alternatives, offering first-mover expansion corridors.
- Carbon-border adjustment mechanisms:Upcoming EU import levies on high-emission agricultural goods will price-competitively advantage locally manufactured plant proteins against imported animal products.
- Precision fermentation:Convergence with recombinant protein expression is enabling animal-identical whey and casein production without dairy supply chains, opening specialized nutrition formats.
Industry Challenges
- Food technologist scarcity:Formulation chemistry expertise combining protein-stabilizer matrix knowledge with sensory science remains concentrated in Netherlands and Germany, constraining R&D scaling.
- Clean-label certification timelines:EFSA health-claim substantiation requires 18-24 month nutrient-bioavailability studies, delaying packaging-positioning advantages for novel ingredients.
- Legacy dairy equipment retrofit:UHT and aseptic filling lines require substantial capital reconfiguration to handle plant-based lipid systems with different thermal behaviors and fouling profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant-Based Food Market |
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $28.54 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Alternatives, Snack Products, Beverages, Frozen Foods Source Ingredient: Soy Protein, Pea Protein, Wheat Protein, Almond, Coconut, Oat Application: Retail, Food Service, Home Cooking, Institutional Catering, Online Sales Customer Type: Vegetarians, Vegans, Flexitarians, Health-Conscious Consumers, Athletes |
| Companies Covered | Oatly Group AB, Impossible Foods Inc., Danone SA, Quorn Foods Ltd., Hain Celestial Group Inc., Nestlé SA, Beyond Meat Inc., Amy's Kitchen Inc., Unilever plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant-Based Food Market Strategic Shifts & Innovations
Processing technology convergence and regulatory disclosure mandates are compressing traditional competitive moats in European plant-based food, while procurement behavior shifts reward suppliers with verified supply-chain transparency.
High-moisture extrusion is supplanting traditional low-moisture texturization in meat-alternative manufacturing, enabling continuous production of fibrous structures that replicate whole-muscle cuts rather than ground formats. German and Dutch food service distributors are accelerating adoption as flexitarian consumers reject crumbly, dry legacy products. This technology is supplanting batch-processed seitan and tempeh in premium positioned retail, concentrating volume with scaled manufacturers who can amortize capital-intensive twin-screw systems.
EU Green Deal carbon-footprint disclosure requirements are mandating lifecycle-assessment documentation for all packaged foods, creating competitive differentiation for brands with verified low-emission supply chains. EFSA novel-food dossier requirements for emerging protein sources add 12-18 month approval gates before health-positioning claims appear on packaging. Dairy-alternative categories face the steepest compliance burden given oat and almond sourcing complexity across Nordic and Mediterranean supplier bases.
Flexitarian consumers are rotating weekly protein procurement toward hybrid baskets combining reduced conventional meat with plant alternatives rather than full substitution. German and British supermarket loyalty data reveals declining commitment to exclusive vegetarianism, with instead fluid category-switching based on price-promotion and convenience. Food service operators in Netherlands and Belgium are responding with blended-menu architectures that normalize plant-forward options without segregated "vegan" sections.
Europe Plant-Based Food Market Segmentation
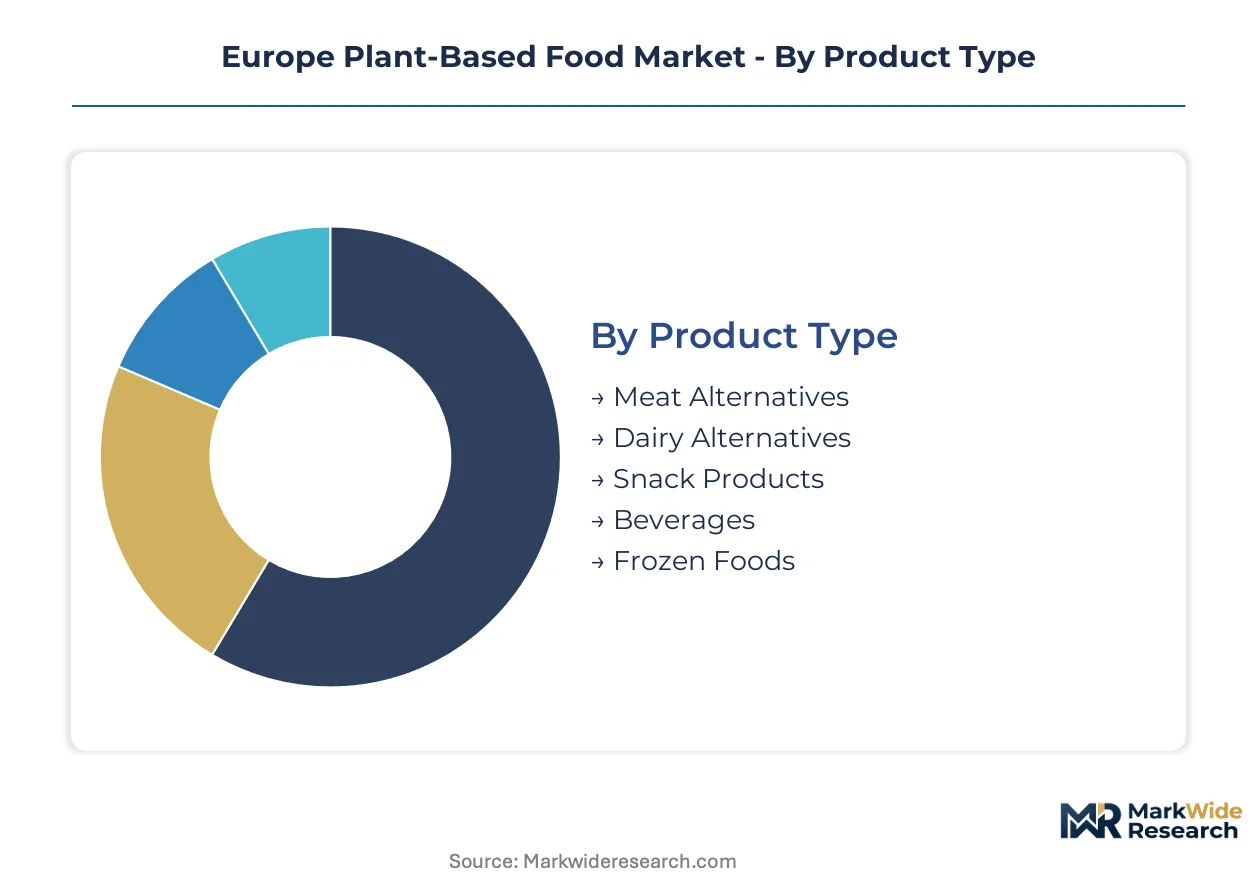
Segmentation in the Europe plant-based food market reveals how formulation choices, procurement channels, and consumer archetypes intersect to determine margin structures and listing priorities. Manufacturers must align R&D investment with the specific technical and regulatory requirements of each segment cluster.
Product Type:
Channel-mix patterns vary sharply across product categories, with refrigerated dairy alternatives dominating supermarket velocity while meat alternatives concentrate in food service and frozen retail.
- Dairy Alternatives:Oat and almond-based beverages and fermented formats lead refrigerated-case penetration. German and British supermarkets drive volume through private-label placement, though clean-label reformulation cycles compress margins for mid-tier suppliers.
- Meat Alternatives:Extruded and shear-cell processed products replicate muscle-fiber texture for flexitarian conversion. Quick-service restaurant chains in the Netherlands and Belgium are accelerating procurement as sensory parity improves.
- Snack Products:Protein-fortified bars and savory crisps target convenience-oriented consumption.
- Beverages:Ready-to-drink protein shakes and functional blends serve athletic and on-the-go segments.
- Frozen Foods:Complete meal formats compete for freezer-space allocation against legacy vegetarian offerings.
By volume, dairy alternatives lead. By growth pace, meat alternatives are expanding most quickly.
Source Ingredient:
Cost-tier stratification runs through ingredient selection, with commodity soy anchoring economy positioning and pea protein commanding premium shelf placement.
- Pea Protein:Isolates from French and Dutch processing facilities enable non-GMO and allergen-friendly positioning. Premium meat-alternative formulations in Germany and the United Kingdom prioritize pea over soy for label-claim differentiation.
- Oat:Nordic milling infrastructure supports the dominant oat-milk category. Oatly's manufacturing scale and café-channel relationships sustain price premiums despite private-label encroachment.
- Soy Protein:Established supply chains and functional properties retain economy-segment dominance.
- Wheat Protein:Seitan and gluten-based textures serve traditional vegetarian applications.
- Almond:Mediterranean sourcing complexity raises carbon-footprint compliance costs.
- Coconut:Tropical origin distances complicate EU Green Deal traceability requirements.
By margin capture, oat and pea protein lead. By volume scale, soy protein retains the largest share.
Application:
Customer-type concentration determines application priority, with flexitarian-heavy geographies driving food service innovation and vegan-dense markets sustaining retail specialty channels.
- Food Service:Quick-service restaurants and institutional cafeterias in Germany, the Netherlands, and Belgium are rotating menu engineering toward blended architectures. Procurement contracts emphasize consistent supply and scalable texture performance.
- Retail:Supermarket refrigerated-case competition intensifies as private-label alternatives proliferate. British and German retailers are compressing branded shelf space for own-label oat-milk and yogurt alternatives.
- Home Cooking:Unprocessed legume and grain preparation retains cost advantages in Southern European household consumption.
- Institutional Catering:School and hospital contracts are adopting sustainable-sourcing mandates under EU Farm to Fork benchmarks.
- Online Sales:Direct-to-consumer subscription models serve niche dietary requirements and specialty formats.
By revenue concentration, retail leads. By contract value growth, food service is gaining share fastest.
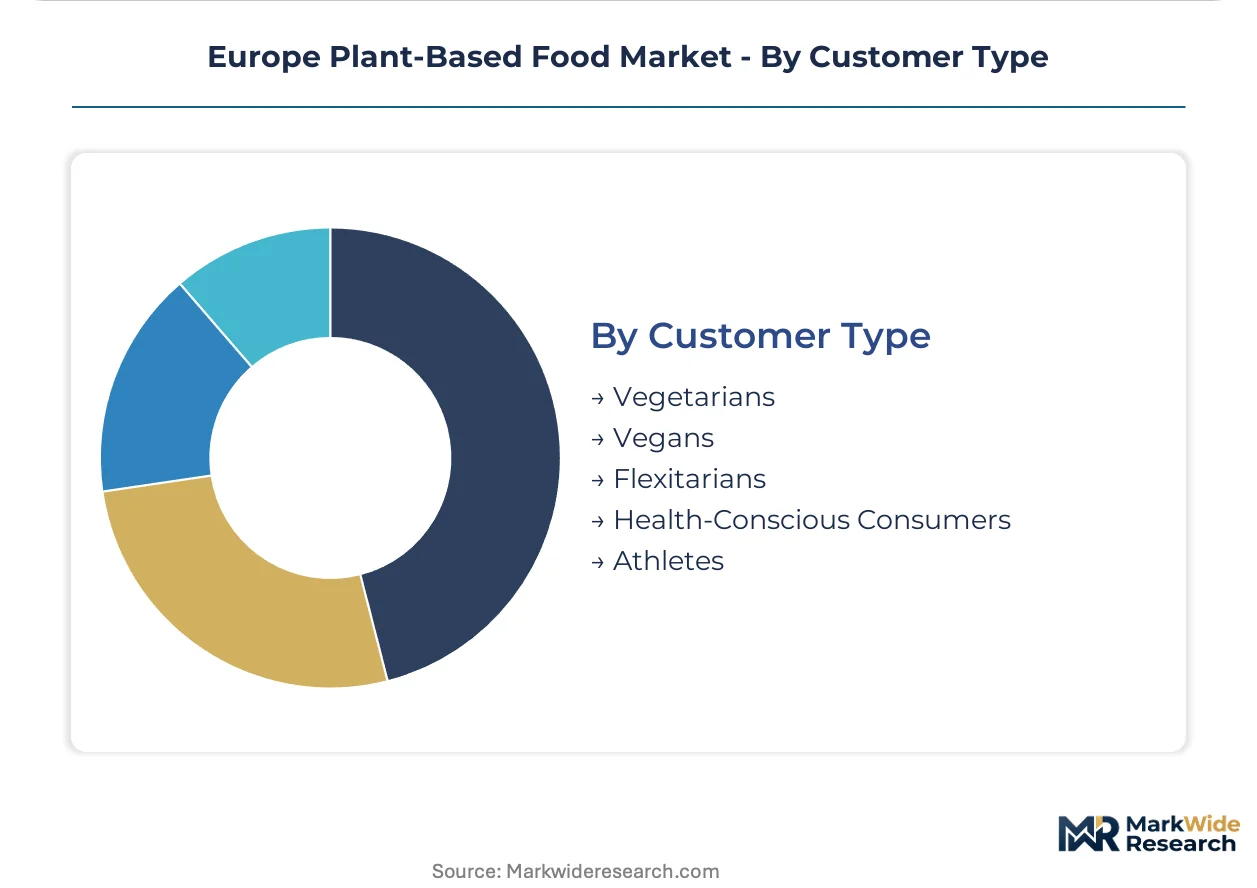
Customer Type:
Maturity-stage differentiation separates established vegetarian segments from emerging flexitarian demand, with the latter requiring sensory parity rather than ideological commitment.
- Flexitarians:Weekly protein procurement rotates between reduced conventional meat and plant alternatives based on price promotion and convenience. German and British loyalty data confirms fluid category-switching behavior.
- Health-Conscious Consumers:Clean-label and high-protein positioning drives purchase decisions. EFSA health-claim substantiation requirements delay packaging advantages for novel ingredients targeting this segment.
- Vegetarians:Traditional demand base with established brand loyalties and lower price sensitivity.
- Vegans:Ethical positioning prioritizes over sensory replication, sustaining smaller specialty brands.
- Athletes:Specialized nutrition formats with elevated protein content per serving.
By population scale, flexitarians lead. By willingness-to-pay premium, health-conscious consumers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic oat-milk exports from Sweden supply refrigerated-case networks across Germany and the United Kingdom, establishing the dominant trade-flow corridor in European plant-based dairy.
Germany
Flexitarian consumers drive volume through weekly protein rotation between conventional meat and plant alternatives. The EU Green Deal mandates carbon-footprint disclosure for all packaged foods, compressing reformulation timelines. Berlin and Hamburg host dense clusters of food service distributors accelerating high-moisture extrusion adoption for meat-alternative procurement.
United Kingdom
Supermarket private-label placement dominates oat-milk and fermented yogurt velocity, squeezing branded shelf space. EFSA novel-food dossier requirements gate health-positioning claims for emerging protein sources. The Midlands and Greater London concentrate R&D facilities where shear-cell technology specialists refine muscle-fiber replication.
Netherlands
Quick-service restaurant chains rotate menu engineering toward blended architectures normalizing plant-forward options. REACH compliance governs extraction solvents and processing aids in protein isolation, adding certification layers. Wageningen anchors the European food-technology corridor where formulation chemistry expertise concentrates.
France
Pea protein isolate processing facilities in northern regions supply premium non-GMO formulations to German and British manufacturers. The EU Farm to Fork Strategy redirects procurement budgets toward verified low-carbon ingredient suppliers. Lyon and Paris house institutional cafeteria operators adopting sustainable-sourcing mandates under carbon-disclosure requirements.
Poland
Underpenetrated refrigerated-case distribution for oat-milk and fermented yogurt alternatives offers first-mover expansion corridors. Upcoming EU carbon-border adjustment mechanisms will price-competitively advantage locally manufactured plant proteins. Warsaw and Kraków retail networks remain dominated by conventional dairy, creating whitespace for alternative penetration.
Europe Plant-Based Food Market Key Industry Players
Player mix skews toward multinational food conglomerates with diversified portfolio breadth, creating tiered competition between scale-driven manufacturers and specialized plant-based pure-plays. Three strategic archetypes dominate: Nordic oat-milk specialists leveraging manufacturing scale, European dairy giants extending into fermented alternatives, and American meat-alternative innovators pushing extrusion technology. Competitive moves concentrate on portfolio diversification into adjacent categories and geographic expansion through food service channel partnerships.
Within the scale-driven tier, Nestlé SA and Danone SA exemplify conglomerate strategies spanning frozen meals, shelf-stable formats, and specialized nutrition. Oatly Group AB anchors the Nordic specialist archetype with concentrated oat-milk manufacturing. These three occupy positions across distinct competitive vectors—conglomerate breadth, regional manufacturing dominance, and channel-specific penetration—rather than direct overlap in positioning.
| Leading Market Players |
|---|
| Oatly Group AB |
| Impossible Foods Inc. |
| Danone SA |
| Quorn Foods Ltd. |
| Hain Celestial Group Inc. |
| Nestlé SA |
| Beyond Meat Inc. |
| Amy's Kitchen Inc. |
| Unilever plc |
| Others |
Cost & Logistics Intelligence
Pea protein displacement of soy isolates is redrawing procurement geography across northern France and Dutch processing corridors while compressing premium-tier pricing premiums that previously rewarded non-GMO positioning. This input substitution simultaneously concentrates supplier power with French and Dutch millers and erodes the cost advantage soy once held in economy formulations, forcing mid-tier manufacturers to absorb margin compression or reformulate toward oat and wheat alternatives.
Pricing Analysis
Prior-generation low-moisture extrusion equipment commands depreciation-driven pricing floors, while current-generation high-moisture extrusion systems sustain 15-25% price premiums for whole-muscle texture fidelity, and next-generation shear-cell technology remains pre-commercial with pilot-scale pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein isolate grade and EFSA novel-food certification status. Pricing pressure stems from British and German supermarket private-label encroachment on oat-milk and yogurt alternatives. Food service buyers exhibit lowest price sensitivity given procurement contract structures, while retail flexitarian consumers demonstrate highest elasticity to promotion cycles.
Supply Chain Analysis
Strategic stockpiling of pea protein isolates dominates procurement behavior among German and British manufacturers confronting harvest-driven raw-material volatility, while just-in-time delivery persists for oat concentrates where Nordic milling infrastructure ensures supply continuity. Geographic concentration centers on France and Netherlands for pea processing, Sweden for oat milling, and northern Italy for almond sourcing. Raw material dependencies include yellow pea cultivation cycles, Nordic oat harvest yields, and Mediterranean almond irrigation requirements. Single-source vulnerability concentrates in French pea protein facilities supplying premium formulations. Distribution runs through Rotterdam and Hamburg port clusters into continental retail and food service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe plant-based food sits in early-cycle expansion with flexitarian population penetration still below saturation thresholds in Eastern European markets and food service channel development accelerating across quick-service restaurant chains.
For Market Incumbents: Secure formulation continuity by locking multi-year supply agreements with French and Dutch pea protein processors before carbon-border adjustment mechanisms tighten import competition. Defend shelf position through backward integration into Nordic oat milling capacity, countering private-label erosion in British and German supermarkets. Prioritize EFSA health-claim dossier investment to sustain packaging-positioning advantages against emerging precision-fermentation entrants.
For New Entrants and Emerging Players: Anchor in Poland and Romania where refrigerated-case distribution for oat-milk and fermented yogurt alternatives remains underpenetrated relative to Western European benchmarks. Target institutional cafeteria contracts in France and Belgium where EU Farm to Fork sustainable-sourcing mandates are redirecting procurement budgets toward verified low-carbon suppliers. Pursue food service distributor partnerships as the primary go-to-market angle, bypassing retail slotting-fee barriers that concentrate shelf access with established conglomerates.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed shear-cell technology specialists holding proprietary muscle-fiber replication IP and food service channel relationships in Netherlands and Belgium. Five-to-ten-year viability hinges on convergence with precision-fermentation platforms enabling animal-identical protein production. Watch EFSA novel-food approval timelines for recombinant whey and casein as the signal indicating platform-shift inflection toward fermentation-derived nutrition formats.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Processing | Captures margin from French and Dutch supply concentration while securing REACH-compliant solvent traceability. |
| EFSA Novel-Food Dossier Investment | Unlocks 18-24 month health-claim substantiation advantages for emerging protein sources targeting premium positioning. |
| Food Service Channel Partnership Expansion | Accelerates volume pull from quick-service restaurant chains rotating toward blended-menu architectures in Netherlands and Belgium. |
| Precision Fermentation Platform Development | Enables animal-identical whey and casein production without dairy supply chain carbon-footprint compliance burdens. |
| Eastern European Retail Distribution Buildout | Establishes first-mover position in Polish and Romanian refrigerated-case networks before private-label saturation. |
Research Approach
Cross-validation between executive interviews at German and Dutch food manufacturers and secondary trade data anchors the qualitative findings on procurement behavior shifts. Primary fieldwork engaged R&D directors at extrusion technology providers, category buyers at British and German supermarket chains, procurement officers at quick-service restaurant headquarters, and formulation chemists at Nordic oat-milk specialists. Secondary sources included EFSA novel-food register filings, EU Green Deal implementation guidance documents, REACH compliance databases, and refrigerated-case velocity data from retail audit panels. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Sensitivity analysis tested alternative adoption curves for flexitarian consumer conversion and regulatory implementation timelines for carbon-border adjustment mechanisms. Segmentation dimensions spanned product type, source ingredient, application channel, and customer archetype across the projection horizon. CAGRs derived from fitted growth curves incorporating food service contract value trajectories, retail private-label penetration rates, and EFSA approval pipeline status. Industry-specific inputs included shear-cell technology deployment schedules and EU Farm to Fork procurement mandate compliance deadlines.
Material uncertainties — harvest-driven pea protein price volatility, EFSA novel-food evaluation delays, and carbon-border adjustment mechanism implementation scope — sit outside the modeled envelope. Forecasts reflect assumptions on flexitarian population growth and food service channel development remaining within historical elasticity bands. Revision becomes warranted when precision-fermentation product approvals cross commercialization thresholds or when supermarket private-label share breaches concentration points that trigger branded manufacturer exit decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Asia-Pacific Pea Protein Market