
 Plant Based Food Colors Market | 2026-2036
Plant Based Food Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Food Colors Market Analytics
Modular color kit bundling is repositioning how food manufacturers source plant-based pigments, shifting procurement from bulk single-ingredient contracts toward application-specific portfolios. GNT Group leverages its vertical integration from seed breeding to extraction to sustain supply security for spirulina and beetroot concentrates. Sensient Technologies competes through R&D intensity in emulsion-stable anthocyanins for beverage applications. Kerry Group plc anchors its position through geographic dominance in European dairy colorant supply chains.
Plant based food colors comprise pigments extracted from fruits, vegetables, leaves, and other botanical sources through aqueous or solvent-based processes, yielding anthocyanins, carotenoids, chlorophylls, and betalains with defined color stability parameters and pH-dependent hue ranges. These colorants serve the primary commercial purpose of replacing synthetic azo and triarylmethane dyes in packaged foods subject to clean-label procurement policies. Fruit extracts dominate value contribution due to concentrated anthocyanin yields and broad pH tolerance, while vegetable extracts register the fastest trajectory as beetroot and paprika sources expand into savory applications. Powdered colors command margin concentration through extended shelf life and reduced logistics costs versus liquid alternatives.
FDA color additive regulations and EFSA re-evaluations of synthetic dye safety are compressing approval timelines for novel plant-derived colorants while elevating toxicological documentation burdens. REACH registration requirements for imported botanical extracts and EU Green Deal sustainable sourcing mandates are reshaping supply chain verification protocols. Stakeholders must monitor pending FDA petitions for new plant sources and EFSA health claim linkages to position formulation roadmaps ahead of regulatory ratification cycles.
Market Dynamics
Clean-label procurement mandates from retail chains are compressing synthetic dye tolerance thresholds, forcing packaged food manufacturers to rebuild formulation pipelines around botanical pigment stability parameters.
Growth Catalysts
- EFSA azo dye guidance:Reformulation deadlines in Germany and France are pulling anthocyanin concentrates into commercial bakery and confectionery lines ahead of enforcement windows.
- Beverage stabilization technology:Emulsion-stable carotenoid systems are unlocking pH-sensitive applications previously blocked by precipitation risk in fortified drinks.
- Spirulina cultivation clusters:Controlled-environment farms in India and Thailand are expanding raw material supply security for blue-green pigment extraction.
Market Restraints
- Beetroot harvest volatility:Weather-driven yield fluctuations in Ukrainian and Polish growing regions create betalain concentrate price instability.
- REACH registration burdens:ECHA documentation requirements for novel botanical extracts extend commercialization timelines by 18-24 months for imported raw materials.
- Anthocyanin pH sensitivity:Color shift toward gray-blue in neutral pH environments limits deployment in dairy and neutral-pH savory applications without expensive buffering systems.
Strategic Opportunities
- Japanese functional food channel:FOSHU claim linkages for antioxidant-rich colorants are opening premium positioning in beverage and supplement categories.
- EU Green Deal sourcing mandates:Verified sustainable cultivation protocols create preferential procurement status for European extraction facilities.
- Encapsulation-nanotechnology convergence:Liposome-embedded chlorophyll systems are extending light-stability performance into transparent packaging formats.
Industry Challenges
- Formulation chemist scarcity:Cross-functional expertise spanning botanical extraction science and food matrix compatibility remains concentrated among senior specialists at established suppliers.
- Dual certification complexity:Simultaneous FDA color additive petition and organic certification pathways create redundant toxicological testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Food Colors Market |
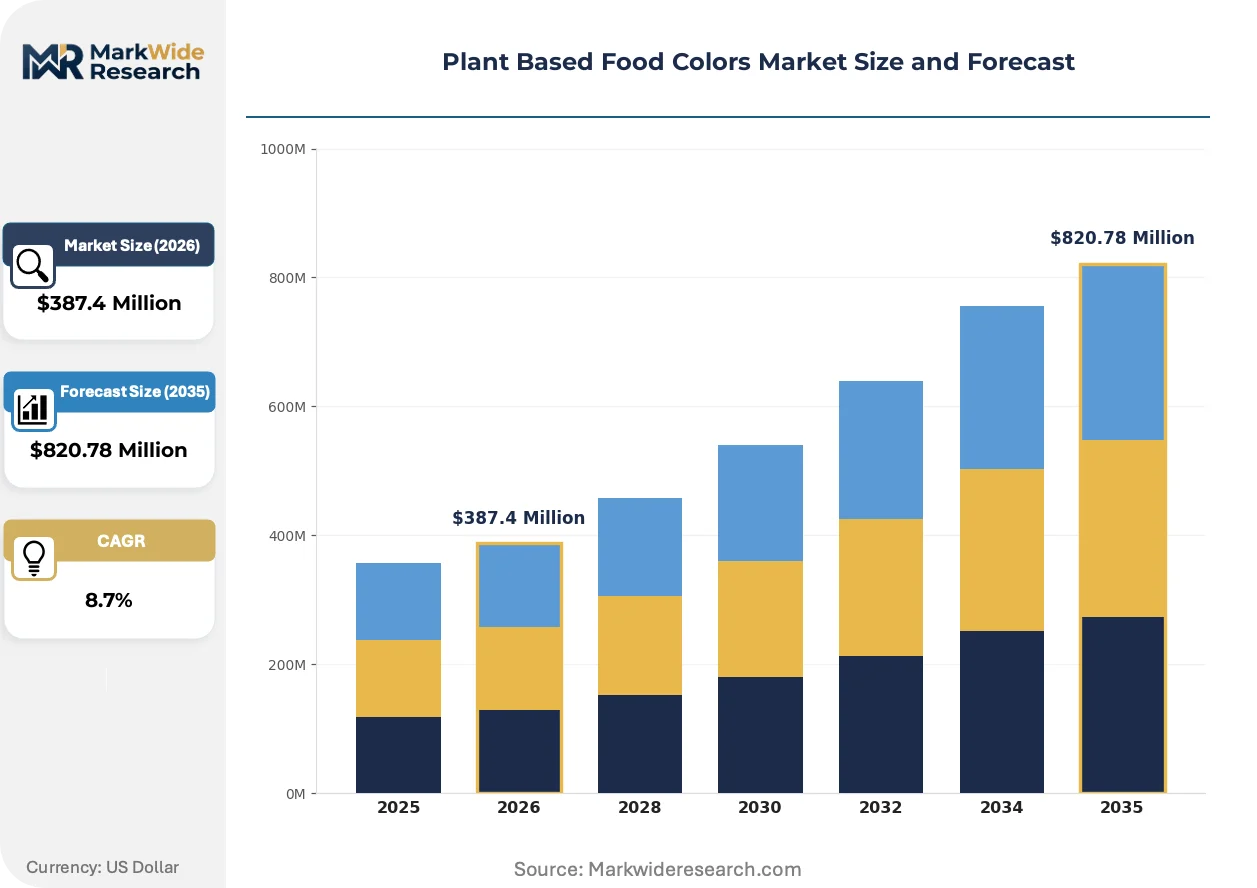
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $820.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Extracts, Vegetable Extracts, Natural Dyes, Leaf Extracts Application: Bakery Products, Beverages, Confectionery, Dairy Products Form: Liquid Colors, Powdered Colors, Gel Colors, Emulsified Colors End User: Food Manufacturers, Beverage Companies, Bakeries, Catering Services |
| Companies Covered | Symrise AG, GNT Group, Givaudan SA, Kalsec Inc., Archer Daniels Midland, Sensient Technologies, Döhler Group, Kerry Group plc, Chr. Hansen Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Food Colors Market Evolving Landscape
Stability engineering and regulatory documentation are converging to redefine competitive advantage, separating suppliers capable of predictive shelf-life modeling from commodity pigment traders.
Microencapsulation via spray-dried gum arabic matrices is electrifying color retention performance in heat-processed applications. Ready-meal manufacturers in the United Kingdom and Netherlands are adopting these systems at pilot scale ahead of full production transfers. The technology is electrifying margin structures by reducing dosage requirements and waste rates in high-temperature processing lines.
REACH authorization timelines for synthetic dye alternatives are compressing approval pathways for novel plant sources while elevating toxicological dossier standards. ECHA's 2024 updated guidance on botanical extract safety assessment is redirecting R&D investment toward well-characterized traditional food plants rather than exotic species. European dairy colorant suppliers are responding by prioritizing spirulina and turmeric over experimental fruit peel extracts.
Modular color kit bundling is replacing bulk single-pigment contracts as the dominant procurement pattern among mid-sized food manufacturers. Application-specific portfolios spanning pH-stable reds, heat-stable yellows, and light-stable greens are displacing volume-based annual agreements. Germany's industrial bakery sector exhibits the most advanced adoption, with formulation houses specifying complete color systems rather than raw pigment inputs.
Plant Based Food Colors Market Segmentation
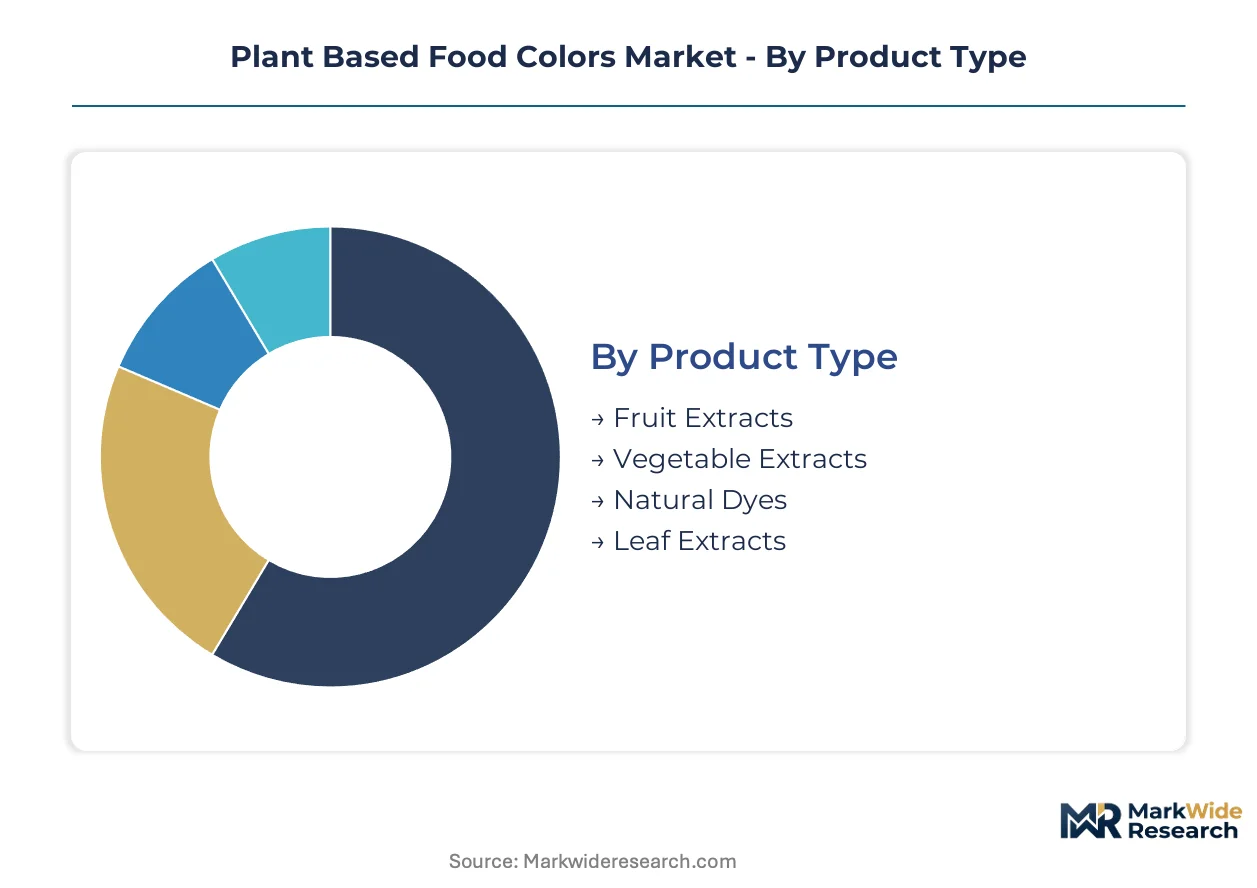
Plant-based food color suppliers configure their portfolios around formulation compatibility rather than pigment chemistry alone. Segmentation reveals where technical specifications diverge from procurement patterns, exposing margin concentration points.
Product Type:
Standardization dominates at commodity grades while extraction method and concentration ratios differentiate premium tiers.
- Fruit Extracts:Anthocyanin-rich concentrates from grape, elderberry, and blackcurrant sources deliver pH-responsive red-purple hues with defined stability parameters. German industrial bakeries and French confectionery houses anchor demand as EFSA azo dye deadlines force reformulation pipelines. Beetroot harvest volatility in Ukrainian growing regions creates intermittent supply gaps that fruit-derived alternatives exploit.
- Vegetable Extracts:Betalain systems from beetroot and carotenoid matrices from paprika and carrot sources target savory applications with heat tolerance requirements. Expansion is steepest here as ready-meal manufacturers in the United Kingdom pilot emulsion-stable systems for processed meat alternatives. Color shift sensitivity in neutral pH environments limits unbuffered deployment.
- Natural Dyes:Turmeric-derived curcuminoids and spirulina-based phycocyanins serve clean-label positioning with established regulatory dossiers.
- Leaf Extracts:Chlorophyll and chlorophyllin copper complexes provide green coloration with light-stability challenges driving encapsulation investment.
Most installed capacity flows through Fruit Extracts. Expansion is steepest in Vegetable Extracts.
Application:
Heat exposure and pH environment separate technical requirements across processing conditions.
- Beverages:Anthocyanin and carotenoid emulsions must survive pasteurization without precipitation or ring formation. Emulsion-stable systems from Sensient Technologies and GNT Group unlock fortified drink applications previously blocked by separation risk. German beverage compounders specify complete color systems rather than raw pigment inputs.
- Confectionery:Hard candy and panned coating applications demand thermal stability above 150°C, favoring encapsulated carotenoids and curcuminoids. Japanese functional candy manufacturers leverage FOSHU claim linkages for antioxidant positioning.
- Bakery Products:Maillard reaction interference and crumb moisture migration constrain natural color retention in bread and cake matrices.
- Dairy Products:Neutral pH environments trigger anthocyanin graying without expensive buffering infrastructure.
Volume concentrates in Beverages. Technical complexity peaks in Confectionery.
Form:
Logistics cost and shelf-life requirements determine liquid versus powder trade-offs.
- Powdered Colors:Spray-dried gum arabic matrices extend stability into 24-month horizons while reducing freight expenditure versus liquid alternatives. Powdered formats command margin concentration through reduced cold-chain dependency and simplified inventory management. Ready-meal manufacturers in the Netherlands adopt these systems at pilot scale.
- Liquid Colors:Ready-to-dose convenience dominates high-volume beverage lines with short production cycles and rapid color adjustment needs.
- Gel Colors:Viscous formats target artisan bakery and small-batch confectionery with precise dosing control.
- Emulsified Colors:Oil-dispersible carotenoid systems unlock fat-based applications including compound coatings and margarine.
Procurement weight sits with Powdered Colors. Gel Colors gain share in craft segments.
End User:
Scale and technical capability separate formulation outsourcing from in-house color management.
- Food Manufacturers:Multinational packaged food houses maintain dedicated color laboratories with shelf-life modeling capabilities and direct supplier relationships. Kerry Group plc anchors European dairy colorant supply chains through long-term service contracts. REACH registration burdens for novel botanical extracts favor established supplier partnerships over spot procurement.
- Beverage Companies:Concentrated production footprints and rapid SKU turnover demand just-in-time color delivery with batch-to-batch consistency guarantees.
- Bakeries:Industrial scale operations specify complete color systems; artisan segments rely on distributor-formulated gel kits.
- Catering Services:Low-volume, high-variety needs drive distributor channel dependence with limited technical specification input.
Contract value concentrates with Food Manufacturers. Service intensity peaks with Beverage Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European botanical extraction science originated in German university laboratories during the 1970s, establishing quality protocols that now govern global trade. Industrial clusters in the Netherlands and Switzerland subsequently scaled solvent-free processing technologies.
Germany
EFSA guidance on azo dye reformulation deadlines drive anthocyanin concentrate procurement from industrial bakeries in Bavaria and North Rhine-Westphalia. The country's national food safety regulator enforces strict additive documentation under EU harmonized standards. Frankfurt-Rhine-Main corridor hosts formulation houses specifying complete color systems rather than raw pigment inputs.
United States
FDA color additive petition backlogs create competitive windows for established plant-derived dossiers in beverage and confectionery manufacturing. The FDA maintains separate approval pathways for new botanical sources versus GRAS-affirmed traditional extracts. Chicago and Minneapolis-St. Paul processing hubs pilot emulsion-stable carotenoid systems for fortified drink lines.
Netherlands
Ready-meal manufacturers in Randstad cities adopt spray-dried gum arabic matrices for heat-processed applications. EU Green Deal sustainable sourcing mandates reshape supply chain verification protocols for imported botanical extracts. Eindhoven-Brabant region concentrates extraction facility investment serving Benelux dairy colorant demand.
India
Controlled-environment spirulina farms in Karnataka and Tamil Nadu expand raw material supply security for blue-green pigment extraction. The Food Safety and Standards Authority of India harmonizes import standards with Codex Alimentarius frameworks. Hyderabad-Deccan biotechnology corridor attracts contract cultivation partnerships for standardized botanical feedstocks.
Japan
FOSHU claim linkages for antioxidant-rich colorants open premium positioning in Tokyo-Osaka beverage and supplement channels. The Ministry of Health, Labour and Welfare maintains distinct functional food approval pathways separate from standard food additives. Kansai industrial belt houses encapsulation technology specialists serving transparent packaging format requirements.
Plant Based Food Colors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction method sophistication and regulatory dossier completeness. The vendor base stratifies into three tiers: vertically integrated seed-to-extraction operators, formulation-technology licensors, and regional commodity traders. Strategic archetypes include stability-engineering specialists, geographic supply chain dominators, and modular color system bundlers. Dominant competitive moves encompass backward integration into captive cultivation and technology licensing partnerships for emulsion stabilization.
Among European-integrated operators, GNT Group and Kerry Group plc exemplify distinct strategic postures. Sensient Technologies occupies a position among North American technology-intensive specialists. These three anchors demonstrate how geographic origin and organizational structure correlate with competitive archetype selection.
| Leading Market Players |
|---|
| Symrise AG |
| GNT Group |
| Givaudan SA |
| Kalsec Inc. |
| Archer Daniels Midland |
| Sensient Technologies |
| Döhler Group |
| Kerry Group plc |
| Chr. Hansen Holding |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap extraction specialists in the Netherlands and Switzerland anchor premium pricing through captive spirulina cultivation and solvent-free processing patents, while private-equity-rolled-up commodity traders compete on volume scale and logistics efficiency. This ownership bifurcation creates divergent supply behaviors: integrated operators withhold spot market participation to defend margin structures, while financialized competitors prioritize throughput over price discipline.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with organic certification and REACH dossier completeness as primary price differentiation drivers. Cost compression in economy-grade beetroot concentrates is intensifying because Ukrainian harvest volatility forces spot-market sourcing. Industrial bakeries in Germany exhibit lowest price sensitivity due to reformulation deadline pressure, while catering services face acute budget constraints.
Supply Chain Analysis
Skilled extraction chemist scarcity in German and Swiss processing hubs constrains capacity expansion despite demand pull from EFSA azo dye deadlines. Raw material flows draw from controlled-environment spirulina farms in India, betalain-rich beetroot fields in Poland and Ukraine, and anthocyanin-dense elderberry orchards in Germany. Single-source vulnerability in Ukrainian growing regions threatens betalain supply security. Distribution runs through formulation houses specifying complete color systems rather than commodity pigment traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where clean-label procurement mandates from retail chains force packaged food manufacturers toward premium stability-engineered pigments. The demand-shift toward emulsion-stable anthocyanins for neutral-pH dairy applications justifies sustained investment in encapsulation R&D.
For Market Incumbents: Anchor supply security through backward integration into captive spirulina cultivation in Karnataka and Tamil Nadu, while accelerating emulsion stabilization patent filings to defend against Sensient Technologies' beverage technology licensing. EFSA re-evaluation timelines for synthetic dyes create regulatory leverage for dossier-complete operators. Capacity addition in Eindhoven-Brabant extraction facilities captures Benelux dairy demand concentration. For New Entrants and Emerging Players: Encapsulation-nanotechnology convergence offers entry wedge into transparent packaging formats for Japanese functional beverage manufacturers, where FOSHU claim linkages command premium positioning. White-space concentrates in artisan bakery gel color kits across Southern Europe, where distributor fragmentation exceeds formulation expertise. Direct technical service partnerships with mid-sized ready-meal manufacturers bypass established supplier lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among regional commodity traders lacking REACH registration capabilities and stability-engineering R&D infrastructure. Long-term viability centers on regulatory dossier completeness and geographic supply chain control rather than extraction scale alone. Watch FDA color additive petition approval velocity for novel botanical sources as inflection indicator for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | GNT Group's seed-breeding programs secure spirulina supply against Indian climate volatility. |
| Emulsion Stabilization Patent Filing | Sensient Technologies' R&D intensity locks in beverage manufacturer switching costs. |
| REACH Dossier Completion | ECHA compliance accelerates market access for European extraction facilities versus importers. |
| Modular Color Kit Bundling | German industrial bakeries now specify complete color systems rather than raw pigment inputs. |
| FOSHU Claim Linkage Development | Japanese functional food channel opens premium positioning for antioxidant-rich anthocyanin systems. |
Research Methodology
Direct dialogue with extraction facility technical directors, formulation chemists at industrial bakeries, procurement leads at beverage compounders, and regulatory affairs specialists at botanical suppliers grounded qualitative insights. Secondary validation drew from FDA color additive petitions, EFSA scientific opinions, REACH registration databases, and EU Green Deal sustainable sourcing guidelines. Bottom-up capacity modeling and top-down demand segmentation triangulated market sizing across pigment chemistry, application matrix, and geographic clusters.
Segment-level outputs spanning fruit extracts, vegetable extracts, leaf extracts, and natural dyes by beverage, confectionery, bakery, and dairy applications calibrated volume and value trajectories across the projection horizon. CAGRs derived from regression analysis against EFSA reformulation deadline enforcement patterns and FDA petition approval timelines. Crop yield volatility in Ukrainian beetroot regions and spirulina farm expansion rates in India fed supply-side constraints into demand elasticity models.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA azo dye enforcement rigor and FDA novel botanical source petition velocity. Forecasts reflect documented assumptions on regulatory ratification cycles and cultivation yield normalization. Material deviation in REACH authorization timelines or Indian spirulina farm financing conditions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Global Tofu Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Africa Soy Beverages Market