
 Middle East and Africa Meat Substitute Market | 2026-2036
Middle East and Africa Meat Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Meat Substitute Market Foresight
Single-serve chilled portions is shifting how retail buyers stock meat substitutes across Middle East and Africa supermarkets. Beyond Meat Inc. anchors its regional presence through frozen patty distribution in Gulf retail chains. Al Islami Foods leverages its halal-certified supply infrastructure to compete in plant-based protein segments. Switch Foods specializes in localized product development for Emirati and Saudi consumer palates.
Meat substitutes comprise formulated protein products derived from plant biomass, typically containing 15-25% protein content by dry weight, manufactured through extrusion or fermentation processes to replicate the fibrous texture and umami profile of conventional meat. These products serve commercial foodservice and retail channels seeking to reduce saturated fat content while maintaining sensory acceptance among flexitarian consumers. Pea protein formulations currently occupy the fastest-growing product type slot as manufacturers reformulate away from soy allergens. The ready-to-eat form category sustains premium margin pools through chilled deli slices and prepared meal components targeting urban convenience demand. Foodservice distribution channels dominate volume throughput as hotel groups and airline caterers in Dubai and Riyadh integrate meat alternatives into contracted menus.
Saudi Food and Drug Authority (SFDA) standards for novel food ingredient safety assessments shape product registration timelines for imported meat substitutes. South Africa's Department of Health labeling regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) halal certification requirements collectively determine market access parameters across the region's two largest demand clusters. Stakeholders must monitor how Gulf Cooperation Council harmonization of food-tech regulations reshapes cross-border product approval pathways.
Market Dynamics
Halal certification requirements across Gulf Cooperation Council jurisdictions are fragmenting product approval pathways and forcing manufacturers to maintain parallel formulation standards for the same SKU.
Growth Catalysts
- SFDA Novel Food Framework:Saudi Arabia's streamlined safety assessment protocols are reducing import registration timelines for extruded protein products, accelerating Gulf market entry.
- Airline Catering Procurement:Emirates, Qatar Airways, and Etihad Airways have integrated plant-based meal options into premium cabin service contracts, creating institutional demand anchors.
- Pea Protein Extrusion:Advances in high-moisture extrusion technology are enabling fibrous texture replication without soy allergen concerns, expanding addressable consumer bases.
Market Restraints
- Input Cost Volatility:Yellow pea protein isolate prices fluctuate with Canadian prairie harvest yields, compressing formulation margins for regional contract manufacturers.
- Supply Concentration Risk:Over 70% of regional cold-chain distribution for chilled meat analogues routes through Dubai's Jebel Ali port, creating single-point vulnerability.
- Technical Limitation:Current fermentation-derived heme precursors face ESMA novel ingredient classification delays, blocking authentic umami profile replication in UAE retail.
Strategic Opportunities
- Nigeria Urban Centers:Lagos and Abuja supermarket chains remain underserved for branded meat substitutes, presenting first-mover shelf space capture potential.
- Regulatory Tailwind:South Africa's proposed front-of-pack warning label regulations on processed red meat create substitution incentives for plant-based alternatives.
- Direct-to-Institution Channels:Hospital and corporate cafeteria procurement bypasses traditional retail markup structures, enabling volume pricing experiments.
Industry Challenges
- Halal Certification Timelines:ESMA and South African National Halaal Authority parallel review processes add 8-14 months to product launch schedules.
- Refrigerated Infrastructure Capex:Establishing chilled distribution networks for ready-to-eat formats requires cold-store investments that strain mid-cap balance sheets.
- Sensory Scientist Scarcity:Regional universities produce limited food technologists trained in meat texture emulation, forcing reliance on expatriate talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Meat Substitute Market |
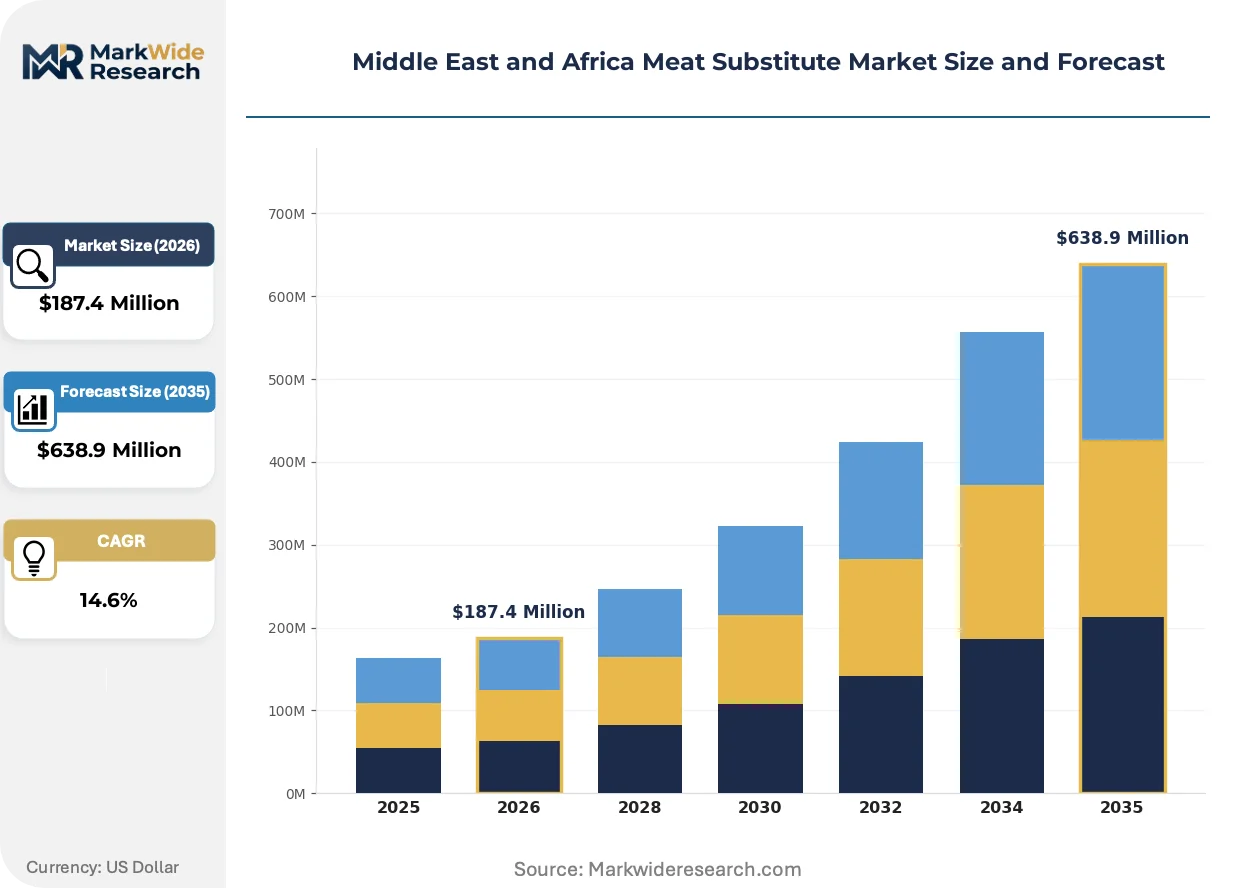
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Pea Protein Form: Frozen, Dried, Chilled, Ready-to-Eat Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice Consumer Type: Vegetarians, Vegans, Flexitarians, Health-Conscious Consumers |
| Companies Covered | Beyond Meat Inc., Impossible Foods Inc., VBites Foods Ltd, Danone SA, Upfield Holdings B.V., Al Islami Foods, Switch Foods, Thryve, Monde Nissin Corp., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Meat Substitute Market Shifts & Advancements
Extrusion equipment manufacturers are retrofitting legacy soy-processing lines for pea-protein compatibility, while regulatory clarity on novel ingredients remains the primary pacing item for product pipeline velocity.
High-moisture extrusion technology is modularizing across regional contract manufacturing facilities, enabling mid-scale producers to reconfigure production runs between burger patty and shredded meat analogue formats within single shifts. South African foodservice distributors are adopting these flexible lines to serve both quick-service restaurant and institutional catering contracts from shared facilities. This modularity is compressing minimum viable batch sizes and reducing working capital requirements for SKU proliferation.
SFDA's 2023 novel food ingredient guidelines are mandating chronic toxicity studies for fermentation-derived proteins, extending registration timelines for mycelium-based products entering Saudi retail. The industrial consequence is a temporary product mix skew toward established plant-protein extrudates in Gulf markets. UAE-based manufacturers are responding by accelerating pea-soy blend formulations that predate the novel food classification threshold.
Flexitarian purchasing patterns in Dubai and Riyadh are fragmenting traditional retail category management, with chilled meat substitutes now merchandised adjacent to conventional proteins rather than segregated in vegetarian aisles. Carrefour UAE and Lulu Hypermarket have adopted this cross-category placement, displacing legacy shelf-space conventions. This behavioral shift is most visible in premium supermarket formats targeting expatriate and affluent local households.
Middle East and Africa Meat Substitute Market Segmentation
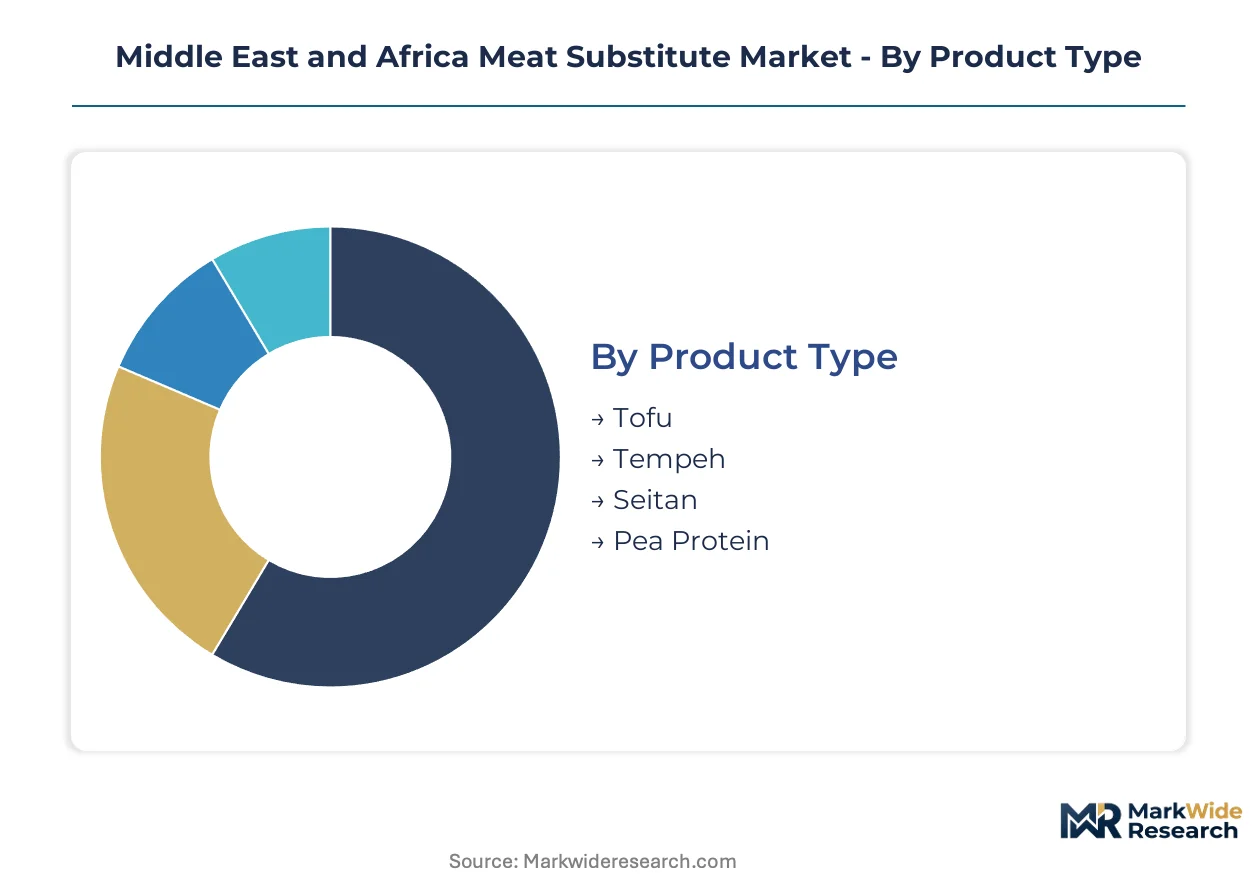
Meat substitute segmentation in the Middle East and Africa reveals distinct formulation and distribution strategies across protein sources and temperature-controlled formats. Manufacturers calibrate product portfolios to match Gulf retail infrastructure constraints and South African foodservice procurement patterns.
Product Type:
Standardized commodity proteins anchor volume at the base of this spectrum, while pea protein formulations command premium positioning through allergen-free positioning and texture innovation.
- Pea Protein:High-moisture extrusion yields fibrous textures replicating conventional meat chew without soy allergen concerns. Emirates and Qatar Airways premium cabin menus drive institutional procurement concentration. SFDA novel food assessments favor established plant proteins over fermentation alternatives, accelerating Gulf market entry for extruded pea isolates.
- Tofu:Coagulated soy curd with 8-15% protein content serves traditional vegetarian communities and institutional catering cost targets. South African quick-service restaurants integrate firm tofu cubes into bowl formats alongside plant-based patties. Input cost volatility for Canadian yellow pea isolates is compressing margins for regional contract manufacturers blending soy and pea bases.
- Tempeh:Fermented whole-soybean cake with firmer texture and higher fiber content than tofu, produced through Rhizopus oligosporus cultivation.
- Seitan:Vital wheat gluten protein concentrate delivering 25-30% protein content through gluten mesh formation, positioned for wheat-tolerant flexitarian segments.
Leading the category by volume: Tofu. Growing fastest: Pea Protein.
Form:
Temperature requirements segment working capital intensity, with chilled formats demanding Gulf cold-store investments that strain mid-cap balance sheets while frozen products leverage existing retail freezer infrastructure.
- Chilled:Single-serve portions with 14-21 day shelf life target urban convenience demand through premium supermarket placement. Carrefour UAE and Lulu Hypermarket merchandise chilled analogues adjacent to conventional proteins, displacing legacy vegetarian-aisle segregation. Jebel Ali port concentration creates single-point vulnerability for over 70% of regional cold-chain throughput.
- Ready-to-Eat:Pre-cooked deli slices and meal components eliminate preparation barriers for time-constrained professionals. Dubai and Riyadh hospital and corporate cafeteria procurement channels bypass retail markup structures for this format. ESMA halal certification timelines add 8-14 months to product launch schedules for prepared formats.
- Frozen:Extended shelf life through blast-freezing enables Gulf retail chain distribution without specialized chilled logistics.
- Dried:Dehydrated textured vegetable protein requiring rehydration, positioned for pantry-stocking and emergency procurement.
Volume concentration: Frozen formats. Steepest expansion trajectory: Chilled.
Distribution Channel:
Channel selection determines margin capture, with foodservice bypassing retail markup while supermarkets demand slotting fees and promotional support.
- Foodservice:Hotel groups and airline caterers in Dubai and Riyadh integrate meat alternatives into contracted institutional menus. Beyond Meat Inc. anchors regional presence through frozen patty distribution to Gulf retail chains. South African foodservice distributors adopt modular extrusion lines serving both quick-service restaurants and institutional contracts from shared facilities.
- Supermarkets:Carrefour UAE and Lulu Hypermarket cross-category placement strategies fragment traditional vegetarian-aisle conventions. Switch Foods develops localized products for Emirati and Saudi consumer palates targeting this channel. Refrigerated infrastructure capex requirements strain mid-cap manufacturer balance sheets for chilled format entry.
- Online Retail:Direct-to-consumer platforms enabling subscription models and bulk procurement for repeat purchasers.
- Specialty Stores:Health food and organic retailers serving concentrated vegetarian communities and allergen-conscious segments.
Dominant throughput: Foodservice. Fastest channel expansion: Online Retail.
Consumer Type:
Dietary commitment intensity segments price elasticity and product attribute priorities, from strict ethical avoidance to health-motivated substitution.
- Flexitarians:Consumers reducing but not eliminating meat consumption drive mainstream volume through sensory-acceptable alternatives. Pea protein extrusion advances enable fibrous texture replication satisfying this segment's taste expectations. Nigerian urban centers in Lagos and Abuja present first-mover shelf space capture potential for flexitarian-targeted brands.
- Health-Conscious Consumers:Saturated fat reduction seekers prioritize protein content and clean-label ingredient lists over strict ethical positioning. South Africa's proposed front-of-pack warning label regulations on processed red meat create substitution incentives for this segment. Regional universities produce limited food technologists trained in meat texture emulation, forcing manufacturer reliance on expatriate talent.
- Vegetarians:Lacto-ovo and lacto-vegetarian consumers with established protein substitution habits and lower price sensitivity.
- Vegans:Strict plant-based consumers demanding absence of all animal derivatives including honey and trace processing aids.
Largest addressable base: Flexitarians. Gaining share fastest: Health-Conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional production capacity lags consumption growth across Middle East and Africa markets, forcing Gulf states to rely on imported extruded protein isolates while South Africa cultivates domestic contract manufacturing capabilities.
United Arab Emirates
Emirates and Etihad Airways premium cabin procurement anchors institutional demand for pea protein patties in Dubai and Abu Dhabi. ESMA halal certification requirements and novel food ingredient classifications shape product registration timelines for fermentation-derived alternatives. Jebel Ali port concentration creates single-point vulnerability for over 70% of regional cold-chain distribution.
Saudi Arabia
SFDA streamlined safety assessment protocols are reducing import registration timelines for extruded protein products, accelerating market entry for established plant-protein formats. Riyadh hotel chains and corporate cafeteria programs integrate meat alternatives into contracted institutional menus. Domestic foodservice distributors adopt modular extrusion lines serving quick-service restaurants from shared facilities.
South Africa
Quick-service restaurant chains menu plant-based patties alongside traditional offerings, while the Department of Health labeling guidelines for meat analogues shape formulation standards. Proposed front-of-pack warning label regulations on processed red meat create substitution incentives for plant-based alternatives. Cape Town and Johannesburg foodservice hubs drive chilled format distribution infrastructure expansion.
Nigeria
Lagos and Abuja supermarket chains remain underserved for branded meat substitutes, presenting first-mover shelf space capture potential for flexitarian-targeted brands. Limited cold-chain infrastructure constrains chilled format penetration, favoring frozen and ambient-stable product entries. Urban professional demand concentrates in expatriate-heavy districts of Victoria Island and Ikoyi.
Middle East and Africa Meat Substitute Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Middle East and Africa meat substitute markets. The vendor base fragments across multinational protein ingredient suppliers, regional halal-certified food manufacturers, and localized product developers. Three archetypes dominate: global extruded protein brands, Gulf-based halal supply infrastructure operators, and domestic taste-localization specialists. M&A activity concentrates on distribution network acquisitions, while capacity expansion focuses on modular extrusion line deployment.
Within the halal-certified infrastructure tier, Al Islami Foods and Switch Foods exemplify regional players leveraging existing supply chain assets. Beyond Meat Inc. anchors the global brand presence through frozen patty distribution in Gulf retail chains. These three companies occupy distinct positioning vectors: Al Islami Foods represents legacy halal protein suppliers diversifying into plant-based segments, Switch Foods exemplifies taste-localization specialists developing for Emirati and Saudi consumer palates, and Beyond Meat Inc. sits within the multinational pure-play archetype driving premium-tier penetration.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Impossible Foods Inc. |
| VBites Foods Ltd |
| Danone SA |
| Upfield Holdings B.V. |
| Al Islami Foods |
| Switch Foods |
| Thryve |
| Monde Nissin Corp. |
| Others |
Supply & Pricing Matrix
Family-owned halal protein specialists across the Gulf Cooperation Council anchor supply discipline through generational control of cold-store assets and ESMA-certified production lines, translating into pricing power that resists spot-market volatility for chilled meat analogue formats.
Pricing Analysis
Margin tightening in premium chilled segments reflects Canadian yellow pea protein isolate volatility and Jebel Ali port congestion surcharges. Three-tier pricing structure across premium airline-catering, standard retail frozen, and economy foodservice bulk tiers separates flexitarian households from institutional procurement. Cost-down pressure on mid-cap contract manufacturers accelerates because SFDA novel food registration fees compound working capital strain. Health-conscious consumers in Dubai and Riyadh show lowest price elasticity, while Nigerian supermarket chains remain most sensitive to landed cost fluctuations.
Supply Chain Analysis
Pea protein isolate supply rests on Canadian prairie processing capacity and Chinese extrusion equipment manufacturing. Raw material dependencies include yellow pea isolates, high-moisture extrusion machinery, and halal-certified emulsifier blends. Single-source vulnerability concentrates at Dubai's Jebel Ali port, where over seventy percent of regional cold-chain throughput routes through a single customs checkpoint. Distribution runs through South African foodservice distributors operating modular extrusion lines and Gulf retail chains with captive freezer infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chilled format cold-store capacity constraints across the Gulf Cooperation Council prop pricing premiums, creating durable margin pools for operators with existing refrigerated infrastructure.
For Market Incumbents: Cement halal certification moats through parallel ESMA and South African National Halaal Authority submissions, compressing review timelines for new SKUs. Deepen backward integration into Canadian pea protein sourcing through long-term offtake agreements, insulating formulations from prairie harvest volatility. Expand modular extrusion line deployment across Riyadh and Johannesburg foodservice hubs to capture quick-service restaurant contract renewals. For New Entrants and Emerging Players: Direct-to-institution digital procurement platforms bypass retail slotting fee structures and enable volume pricing experiments with Dubai hospital cafeteria networks. Lagos and Abuja supermarket chains present first-mover shelf space capture potential for frozen patty formats suited to limited cold-chain infrastructure. Localized taste development for Emirati spice profiles differentiates against multinational brands merchandised in Carrefour UAE cross-category placements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap South African contract manufacturers with existing Department of Health labeling compliance and underutilized chilled distribution capacity. Long-term viability hinges on regulatory clarity for fermentation-derived proteins across the analysis window. Watch SFDA novel food ingredient guideline revisions as the primary inflection signal for mycelium-based product pipeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Parallel Processing | ESMA and South African National Halaal Authority simultaneous submissions compress product launch timelines by 8-14 months. |
| Modular Extrusion Line Deployment | High-moisture extrusion flexibility enables single-shift reconfiguration between burger patty and shredded meat analogue formats. |
| Direct-to-Institution Channel Development | Hospital and corporate cafeteria procurement bypasses retail markup structures for ready-to-eat deli slice formats. |
| Canadian Pea Protein Backward Integration | Long-term offtake agreements with prairie processors insulate margins from yellow isolate spot price volatility. |
| Localized Palate Formulation Investment | Emirati and Saudi spice profile development differentiates Switch Foods-style specialists against standardized multinational offerings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across foodservice procurement directors, halal certification auditors, extrusion equipment engineers, and retail category buyers at Carrefour UAE and Lulu Hypermarket. SFDA novel food guidelines, ESMA halal standards, and South African Department of Health labeling regulations provided regulatory boundary conditions. Bottom-up volume modeling triangulated against top-down expenditure estimates from airline catering contract disclosures.
Granularity extended to protein source, temperature-controlled format, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories and price-per-kilogram assumptions for pea protein isolates. Forecast inputs incorporated Jebel Ali port throughput capacity, Canadian prairie harvest yield variance, and modular extrusion line adoption rates in South African foodservice hubs.
The model holds under stable Gulf Cooperation Council regulatory harmonization; deviation in SFDA novel food reclassification or ESMA fermentation-derived ingredient restrictions would shift product mix assumptions toward established extrudates. A small set of named triggers—halal certification timeline extensions, Jebel Ali logistics disruptions, and pea protein input cost spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Plant-Based Butter Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Europe Tofu Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
United States Plant Protein Market