
 Europe Duckweed Protein Market | 2026-2036
Europe Duckweed Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Duckweed Protein Market Foresight
Skilled aquatic agronomists familiar with closed-loop hydroponic systems is unwinding capacity bottlenecks across European duckweed cultivation. Plantible Foods leverages proprietary extraction technology to anchor its position in protein isolate production. Algama competes through microalgae-duckweed hybrid formulations, while Rubisco Foods specializes in minimally processed flour variants for clean-label food applications.
Europe duckweed protein denotes protein biomass harvested from Lemnaceae aquatic plants, typically containing 35-45% crude protein by dry weight with a complete essential amino acid profile comparable to soy. The primary commercial purpose centers on substituting resource-intensive terrestrial protein sources in both human nutrition and animal feed formulations. Powder formats dominate current manufacturing output due to shelf stability and blending versatility across nutraceutical and food additive applications. Protein isolate segments capture premium margin pools as EFSA novel food certifications validate higher-purity products for human consumption, while animal feed applications sustain volume throughput through less stringent regulatory thresholds.
EFSA novel food protocols, EU Green Deal sustainability benchmarks, and REACH chemical safety standards collectively shape product development timelines and cross-border market access for duckweed-derived ingredients. The F-Gas Regulation indirectly influences cultivation economics by restricting synthetic climate control gases in greenhouse and indoor aquaponics operations. Stakeholders must monitor evolving EFSA guidance on aquatic plant proteins and assess whether captive cultivation or contract farming delivers more resilient supply security under tightening EU environmental compliance.
Market Dynamics
EFSA novel food certification timelines and EU Green Deal sustainability mandates are compressing product development cycles while rewarding early movers with validated supply chains. Dutch aquaponics clusters and German nutraceutical formulators currently capture disproportionate margin from this regulatory acceleration.
Growth Catalysts
- EU Green Deal benchmarks:Binding sustainability targets for protein sourcing are redirecting R&D budgets toward aquatic biomass. Food manufacturers face procurement mandates that favor low-carbon intensity ingredients.
- Netherlands aquaponics infrastructure:Concentrated greenhouse engineering expertise and water management systems enable industrial-scale duckweed cultivation with predictable year-round output.
- EFSA streamlined pathways:Revised guidance for aquatic plant proteins reduces approval uncertainty. Novel food dossiers now benefit from precedent data accumulated since 2021.
Market Restraints
- Input cost volatility:Synthetic fertilizer prices and energy tariffs for climate-controlled cultivation create margin pressure. Dutch growers face particular exposure to natural gas price swings.
- Supply concentration risk:Protein isolate capacity clusters with a handful of extraction technology licensors. Dependence on single-source equipment vendors limits scaling flexibility.
- Regulatory friction:REACH chemical safety data requirements for novel protein derivatives extend registration timelines. Smaller cultivators lack toxicology study budgets.
Strategic Opportunities
- Poland and Romania:Underdeveloped aquaponics base offers first-mover land and labor cost advantages. Greenfield facilities bypass legacy infrastructure constraints.
- Pet food formulations:Lower purity thresholds than human food create faster revenue paths. EFSA feed additive rules permit earlier market entry.
- CSRD disclosure mandates:Corporate sustainability reporting requirements create B2B demand pull. Ingredient suppliers with certified carbon footprints gain preferred vendor status.
Industry Challenges
- Aquatic agronomist scarcity:Closed-loop hydroponic system expertise concentrates in Dutch agricultural universities. Recruitment competition intensifies as sector expansion outpaces training pipeline output.
- Capex intensity:Climate-controlled cultivation facilities and protein extraction equipment demand eight-figure investment commitments. Financing access fragments across venture capital and strategic corporate sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Duckweed Protein Market |
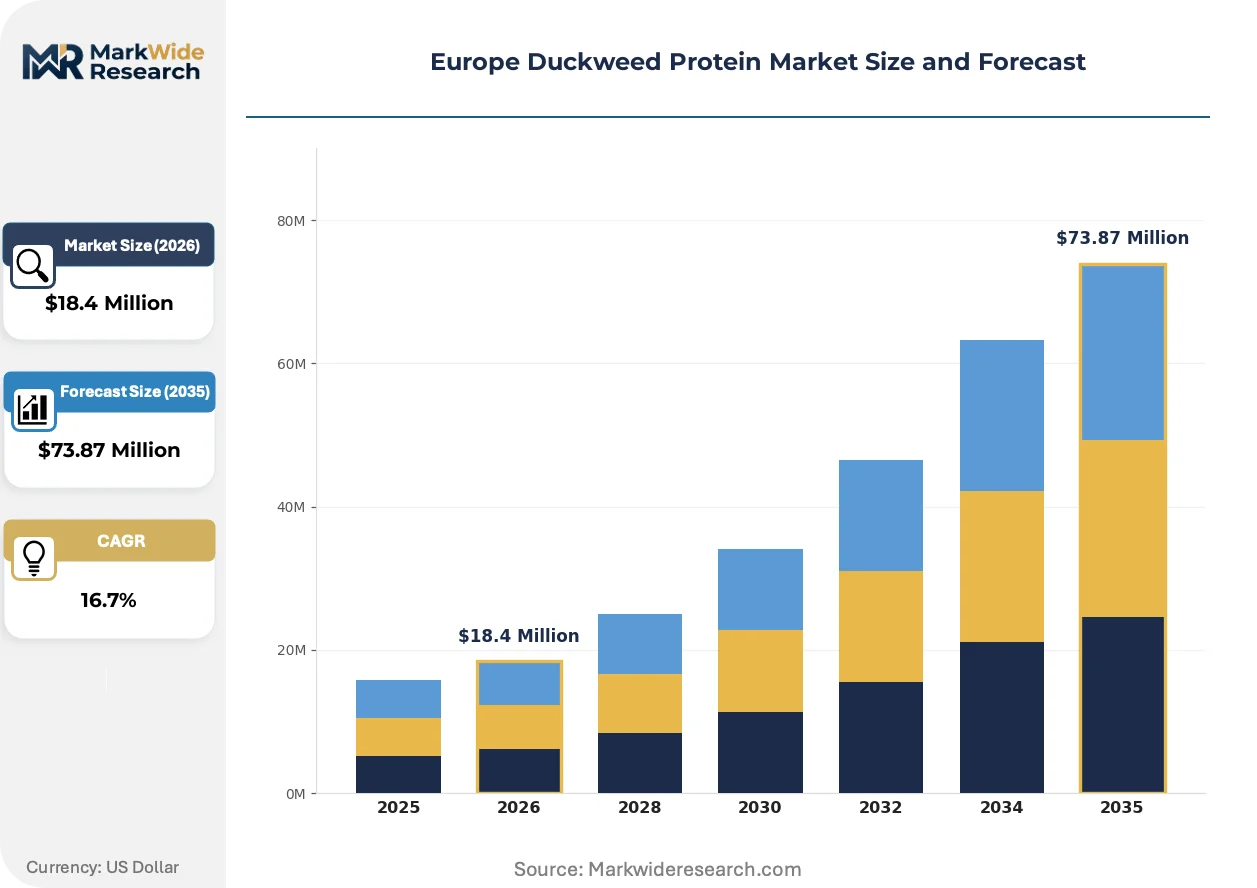
| Market Size in 2026 | $18.4 Million |
| Market Size in 2035 | $73.87 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flour, Protein Isolate, Extract Application: Animal Feed, Nutraceuticals, Food Additives, Pet Food Delivery Mode: Sustainable Agriculture, Aquaponics, Hydroponics, Organic Cultivation End User: Food Industry, Livestock Sector, Aquaculture, Health Supplements |
| Companies Covered | Plantible Foods, Algama, GreenOnyx Ltd., Barentz B.V., Rubisco Foods, Hinoman Ltd., Ducky's, LemnaTec, Parabel Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Duckweed Protein Market Shifts & Advancements
Protein extraction technology and regulatory data accumulation are converging to unlock food-grade applications previously confined to feed markets. Three developments merit particular attention.
Membrane filtration systems for protein concentration is miniaturizing. German nutraceutical contract manufacturers are adopting skid-mounted units for flexible batch sizing. This equipment downsizing enables distributed processing near cultivation sites, reducing biomass transport spoilage losses.
REACH chemical safety standards are tightening substance data requirements for novel protein hydrolysates. ECHA guidance on aquatic plant derivatives now demands expanded toxicology dossiers. Human food applications absorb the heaviest compliance burden, while feed-grade products maintain faster market access.
Ingredient procurement is consolidating around sustainability certification requirements. Large food manufacturers now mandate third-party carbon footprint verification before supplier qualification. Dutch and German buyers lead this specification tightening, with Polish processors beginning to mirror these standards.
Europe Duckweed Protein Market Segmentation
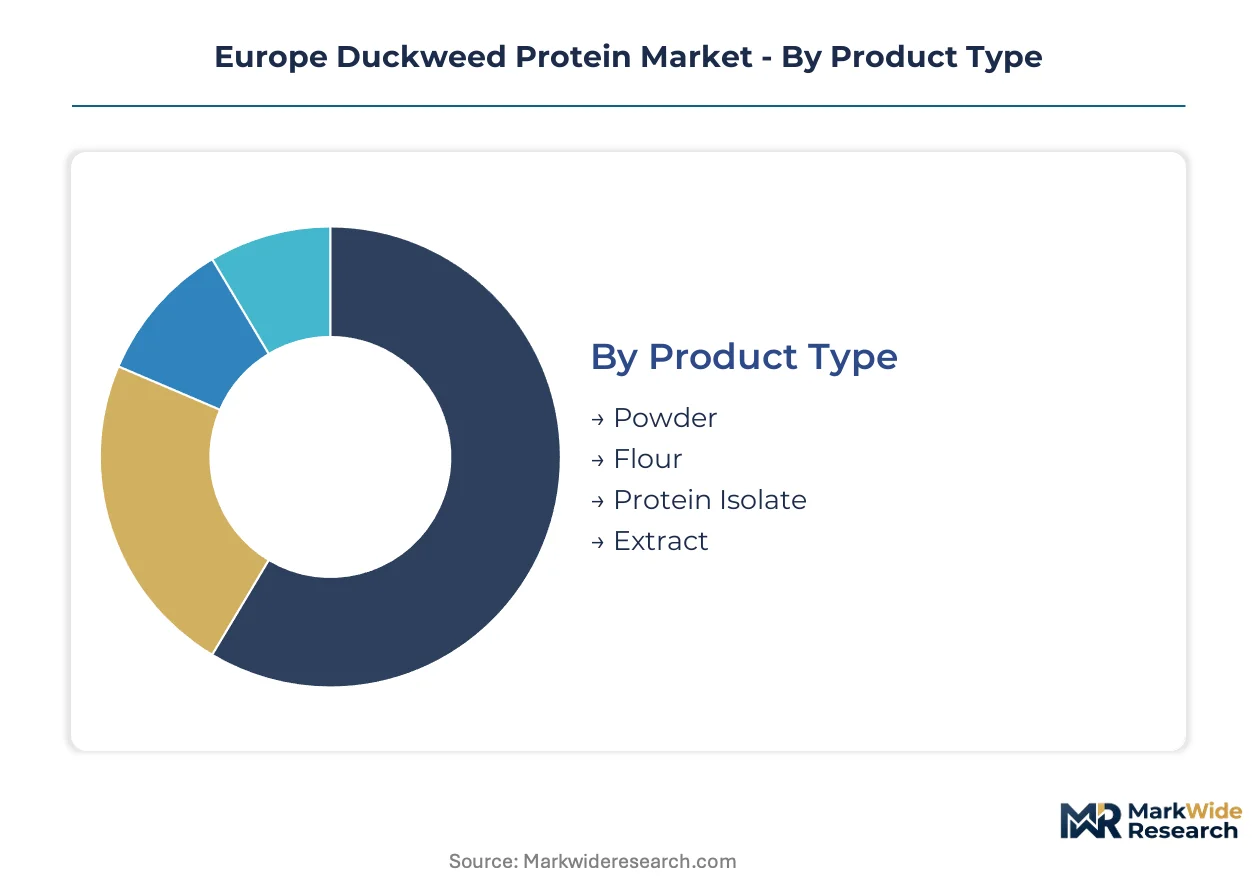
Duckweed protein segments flow through distinct commercial channels shaped by EFSA novel food certification tiers and buyer procurement specifications. Powder and isolate formats command premium positioning in Dutch nutraceutical supply chains, while feed-grade flour moves through less regulated livestock procurement networks.
Product Type:
Powder formats dominate Dutch B2B ingredient distribution, while isolates concentrate in German pharmaceutical-grade manufacturing channels. Flour and extract variants flow through regional feed compounders with lower purity thresholds.
- Protein Isolate:Refined to 80-90% protein concentration through membrane filtration and precipitation sequences. German nutraceutical contract manufacturers absorb the bulk of EFSA-certified isolate output for human-grade applications, driven by binding EU Green Deal protein sourcing mandates for food manufacturers.
- Powder:Crude protein content of 35-45% by dry weight with complete essential amino acid profiles comparable to soy. Dutch aquaponics clusters supply industrial-scale powder volumes to pan-European food additive distributors, constrained by energy tariff volatility affecting climate-controlled cultivation economics.
- Flour:Minimally processed whole-biomass product retaining fiber and micronutrients. Livestock feed compounders in Poland and Romania source flour for poultry and swine rations under less stringent REACH registration requirements.
- Extract:Partially purified protein fractions for specialized hydrolysate applications. Pet food formulators represent the primary demand channel, leveraging faster EFSA feed additive approval pathways relative to human food categories.
Protein Isolate dominates installed base. Powder is where expansion concentrates.
Application:
Cost tier differentiation separates premium human nutrition from commodity feed applications, with nutraceuticals absorbing the heaviest EFSA compliance investment.
- Nutraceuticals:Capsule, tablet, and functional food formats requiring EFSA novel food dossier validation. German formulators lead procurement of certified isolates for sports nutrition and senior protein fortification, absorbing margin compression from REACH toxicology study requirements.
- Food Additives:Emulsifier and texture modifier applications in plant-based meat analogues. Dutch ingredient distributors channel powder volumes into European food manufacturer R&D pipelines, constrained by batch-to-batch protein consistency requirements.
- Pet Food:Premium companion animal nutrition with lower purity thresholds than human consumption. Polish processors are gaining share in private-label pet food manufacturing, exploiting faster EFSA feed additive registration timelines.
- Animal Feed:Bulk protein supplementation for poultry, swine, and aquaculture operations. Romanian livestock integrators represent emerging demand as domestic aquaponics infrastructure scales to displace imported soy meal.
Animal Feed commands volume throughput. Nutraceuticals is climbing the fastest.
Delivery Mode:
Volume concentration tracks regional infrastructure maturity, with Dutch aquaponics clusters achieving year-round predictability unavailable to organic cultivation alternatives.
- Aquaponics:Integrated fish-plant systems delivering nitrogen-rich wastewater to duckweed cultivation beds. Netherlands greenhouse engineering expertise enables industrial-scale output with automated harvesting, though F-Gas Regulation restrictions on synthetic climate control gases elevate capex requirements.
- Hydroponics:Soilless cultivation with synthetic nutrient dosing in controlled environments. German research institutes pilot closed-loop hydroponic systems for pharmaceutical-grade protein production, constrained by aquatic agronomist recruitment competition.
- Organic Cultivation:Certification-compliant production avoiding synthetic inputs. Premium food additive buyers in France and Italy specify organic duckweed for clean-label positioning, limited by seasonal output variability and lower protein yields.
- Sustainable Agriculture:Open-pond and extensive wetland harvesting with minimal infrastructure. Eastern European greenfield projects in Poland and Romania exploit land cost advantages for feed-grade biomass, sacrificing yield consistency for capital efficiency.
Aquaponics dominates installed base. Sustainable Agriculture is where expansion concentrates.
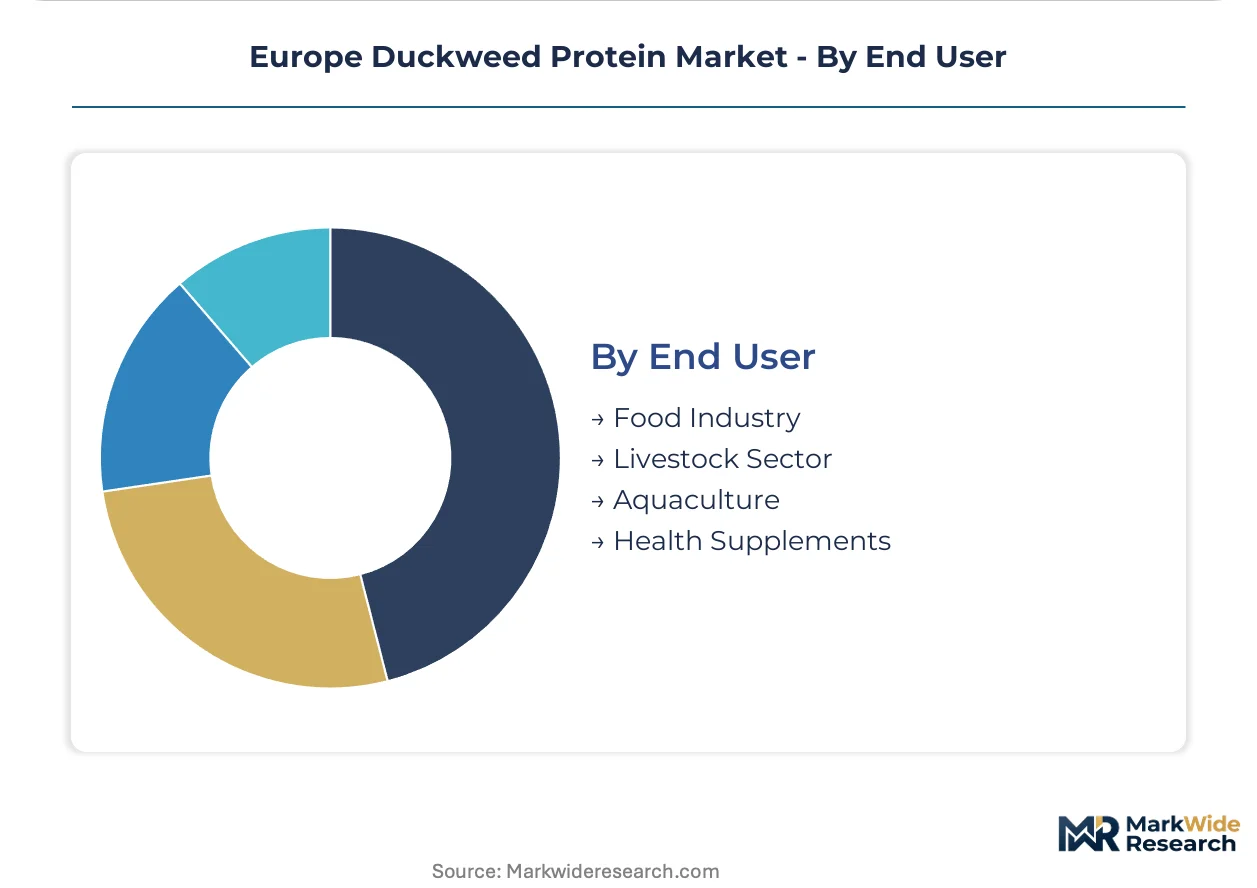
End User:
Customer type fragmentation reflects divergent procurement specifications, with health supplements demanding certificate-backed traceability absent from livestock sector purchasing.
- Health Supplements:Direct-to-consumer protein powders and functional foods requiring batch-level carbon footprint documentation. German and Dutch buyers mandate third-party verification under tightening CSRD disclosure standards, filtering supplier qualification.
- Food Industry:Ingredient procurement by multinational manufacturers for plant-based product lines. EFSA novel food certification serves as gatekeeper for supplier onboarding, with precedent dossiers from 2021 onward reducing approval uncertainty.
- Livestock Sector:Poultry and swine integrators sourcing feed-grade protein. Polish and Romanian operations lead adoption as domestic cultivation displaces imported soy, driven by EU Green Deal procurement mandates for low-carbon feed ingredients.
- Aquaculture:Fish meal substitution in salmon and trout feed formulations. Norwegian aquafeed producers evaluate duckweed protein digestibility trials, pending EFSA feed additive approval for species-specific applications.
Food Industry dominates installed base. Livestock Sector is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Europe. Dutch buyers prioritize aquaponics-derived isolates for nutraceutical applications, while Eastern European feed compounders absorb minimally processed flour for livestock rations under lighter regulatory burdens.
Netherlands
Dutch aquaponics clusters supply industrial-scale protein volumes to German nutraceutical formulators. EFSA novel food certification timelines compress as precedent dossiers accumulate since 2021. Westland greenhouse engineering expertise enables automated duckweed harvesting with year-round output predictability.
Germany
German sports nutrition and senior protein fortification segments absorb premium isolate volumes. REACH chemical safety data requirements for novel protein hydrolysates extend registration timelines for human food applications. Bavarian contract manufacturers pilot skid-mounted membrane filtration units for flexible batch sizing.
Poland
Polish livestock integrators source feed-grade flour to displace imported soy meal under EU Green Deal procurement mandates. Lower purity thresholds for animal feed create faster revenue paths than human food categories. Greater Poland greenfield aquaponics projects exploit land cost advantages for capital-efficient scaling.
Romania
Romanian poultry and swine operations represent emerging demand as domestic cultivation infrastructure scales. F-Gas Regulation restrictions on synthetic climate control gases elevate capex requirements for climate-controlled facilities. Dobrogea region open-pond projects sacrifice yield consistency for minimal infrastructure investment.
France
French premium food additive buyers specify organic duckweed for clean-label positioning in plant-based meat analogues. Certification-compliant production avoids synthetic inputs but faces seasonal output variability. Occitanie agricultural cooperatives evaluate hybrid organic-aquaponics systems to bridge yield gaps.
Europe Duckweed Protein Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Europe duckweed protein. The upper tier commands extraction technology licensing and EFSA-certified isolate capacity. Mid-scale specialists cluster around regional aquaponics operations and feed-grade flour production. Dominant competitive moves include captive cultivation partnerships and membrane filtration equipment deployment.
Within the integrated technology tier, Plantible Foods anchors proprietary extraction positioning while Algama occupies the microalgae-duckweed hybrid formulation space. Rubisco Foods exemplifies the minimally processed flour archetype for clean-label applications. These three entities represent distinct strategic postures: technology licensing, ingredient hybridization, and whole-biomass simplification.
| Leading Market Players |
|---|
| Plantible Foods |
| Algama |
| GreenOnyx Ltd. |
| Barentz B.V. |
| Rubisco Foods |
| Hinoman Ltd. |
| Ducky's |
| LemnaTec |
| Parabel Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Dutch aquaponics operators and German nutraceutical formulators lock in multi-year protein isolate supply at fixed escalators, anchoring price visibility against natural gas tariff volatility while constraining spot market liquidity for smaller buyers.
Pricing Analysis
Contract-based long-term offtake dominates human-grade protein isolate transactions, with EFSA novel food certification tier and volume scale serving as the primary price differentiation drivers. Cost compression in feed-grade flour is intensifying because Polish and Romanian open-pond cultivators sacrifice yield consistency for capital efficiency. Animal feed compounders exhibit highest price sensitivity, while German pharmaceutical-grade buyers absorb premium positioning with limited elasticity.
Supply Chain Analysis
Strategic stockpile preferences concentrate among German nutraceutical contract manufacturers buffering against EFSA certification timeline uncertainty, while Dutch aquaponics clusters run lean just-in-time biomass flows to minimize climate-controlled holding costs. Supply concentrates in the Netherlands, Germany, and Poland. Protein isolate production draws from synthetic fertilizer inputs, membrane filtration equipment, and skilled aquatic agronomist labor. Single-source vulnerability runs through German extraction technology licensors. Distribution runs through Dutch B2B ingredient distributors serving pan-European food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
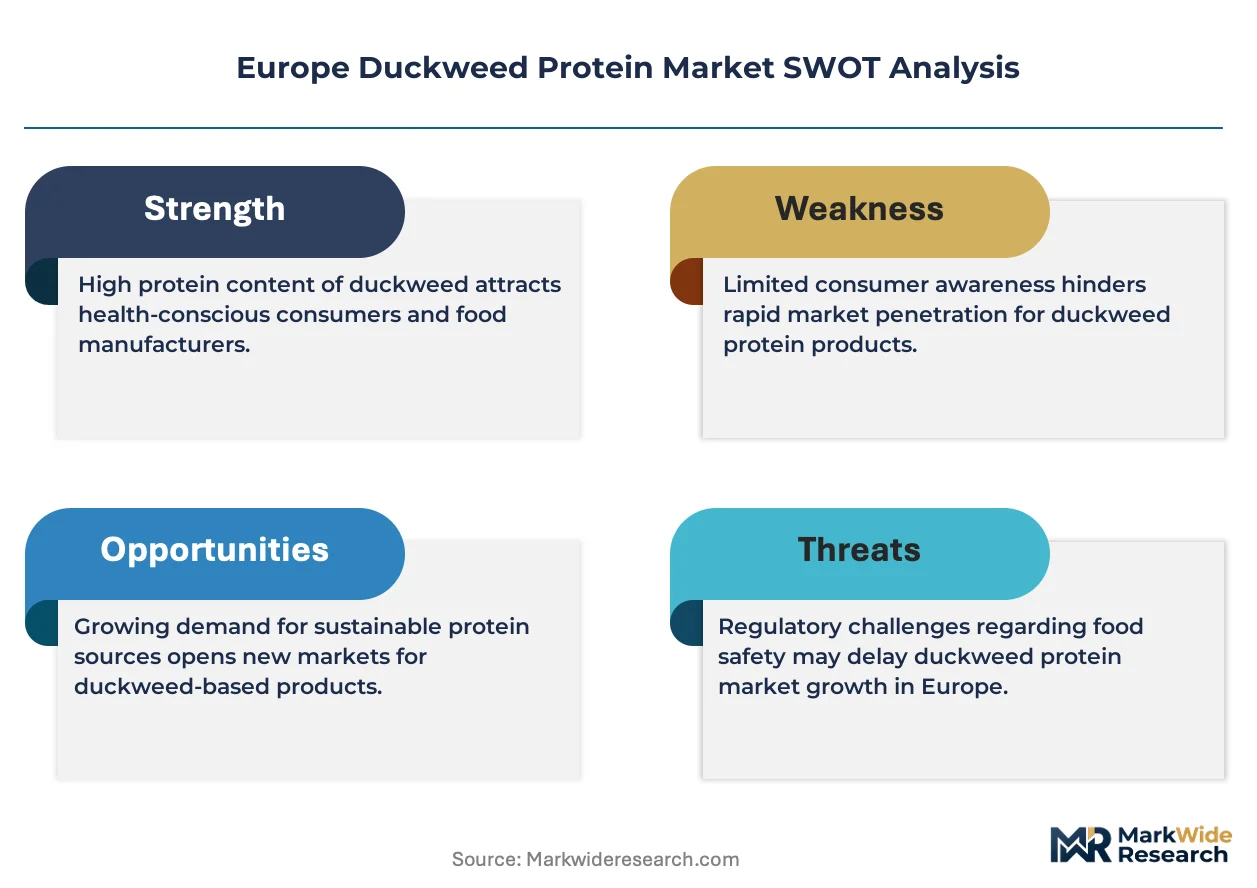
The acute shortage of aquatic agronomists trained in closed-loop hydroponic systems constrains cultivation scaling across Europe, amplifying returns for stakeholders who secure this specialized workforce pipeline.
For Market Incumbents: Fortify supply security through captive cultivation partnerships in Greater Poland, where land cost advantages compound with EU Green Deal procurement tailwinds. Deepen backward integration into membrane filtration equipment deployment to reduce dependence on single-source German technology licensors. EFSA novel food dossier precedent accumulation since 2021 now serves as a defendable moat against emerging entrants lacking regulatory data libraries.
For New Entrants and Emerging Players: Lead with pet food formulation partnerships in Poland, where lower purity thresholds and faster EFSA feed additive timelines compress revenue realization versus human food categories. Private-label manufacturing for Eastern European livestock integrators represents the most penetrable white space. Anchor go-to-market positioning on certified carbon footprint documentation enabling CSRD-compliant B2B supplier qualification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Dutch aquaponics operators with multi-year offtake contracts to German nutraceutical formulators, offering visibility across the analysis window. Acquisition target archetype: integrated cultivator-extractors with EFSA-certified isolate capacity and proprietary greenhouse engineering IP. Watch EFSA guidance evolution on aquatic plant proteins as the inflection signal for human food application expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Partnership | Secures land and labor cost advantages in Greater Poland while bypassing Dutch infrastructure constraints. |
| Membrane Filtration Scale-Up | Reduces biomass transport spoilage through distributed processing near Eastern European cultivation sites. |
| EFSA Novel Food Dossier Investment | Validates higher-purity isolates for human consumption under streamlined aquatic plant protein pathways. |
| CSRD Carbon Footprint Certification | Enables preferred vendor status with Dutch and German buyers mandating third-party verification. |
| Pet Food Formulation Entry | Exploits faster EFSA feed additive timelines in Poland versus human food regulatory burdens. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food dossier databases, EU customs trade records, and Dutch greenhouse engineering patent filings. Primary interviews engaged aquaponics operations managers, German nutraceutical procurement leads, EFSA regulatory affairs specialists, and Polish livestock feed compounders. Secondary validation drew from REACH chemical safety registrations, CSRD disclosure filings, and EU Green Deal procurement mandate documentation. Bottom-up cultivation capacity modeling triangulates against top-down protein demand projections from food manufacturer sustainability reports.
Segmentation dimensions modeled include product type tier, application purity threshold, delivery mode infrastructure, and end-user procurement specification across the projection horizon. CAGRs derive from weighted capacity buildout schedules, EFSA approval timeline distributions, and substitution elasticity estimates for soy protein displacement. Industry-specific forecast inputs incorporate F-Gas Regulation compliance cost trajectories and natural gas tariff volatility scenarios affecting Dutch climate-controlled cultivation economics.
Forecasts assume regulatory continuity in EFSA novel food protocols and EU Green Deal binding targets; material policy shifts would require re-modeling. REACH chemical safety data requirement tightening or F-Gas Regulation scope expansion represent specific revision triggers. Revision becomes warranted when EFSA aquatic plant protein guidance crosses substantive amendment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Europe Algae Protein Market