

Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market Insights
EU Green Deal compliance is consolidating the cost-of-entry calculus for test equipment vendors serving European fuel cell developers. AVL List GmbH leverages its Graz engineering heritage to dominate electrochemical validation workflows for automotive OEMs. HORIBA anchors its position through integrated emissions-and-durability test cells that span multiple fuel cell chemistries. Greenlight Innovation specializes in membrane electrode assembly cycling rigs that occupy a narrow but defensible niche in North American research corridors.
Hydrogen fuel cell stack durability and performance test equipment comprises electrochemical diagnostic stations, thermal cycling chambers, and mechanical load frames designed to subject proton exchange membrane and solid oxide stacks to accelerated degradation protocols at current densities exceeding 2.0 A/cm². The apparatus validates stack lifetime against OEM warranty thresholds before commercial deployment. Durability Test Systems and Performance Test Systems represent the twin revenue pillars, with the former commanding premium pricing due to thousand-hour minimum test durations. Electrochemical Impedance Spectroscopy leads technology adoption for in-situ degradation tracking, while Accelerated Stress Testing grows fastest as developers compress validation timelines.
FEV Group and TOYO Corporation navigate divergent regulatory terrains where EPA tailpipe rules, EU F-Gas Regulation on fluorinated membrane materials, and Japan's METI hydrogen safety standards each reshape equipment specifications and calibration requirements. The EU AI Act introduces algorithmic transparency mandates for automated pass-fail determination in test cells. Stakeholders must decide whether to architect modular platforms that adapt to jurisdiction-specific protocols or accept stranded asset risk in markets with tightening durability thresholds.
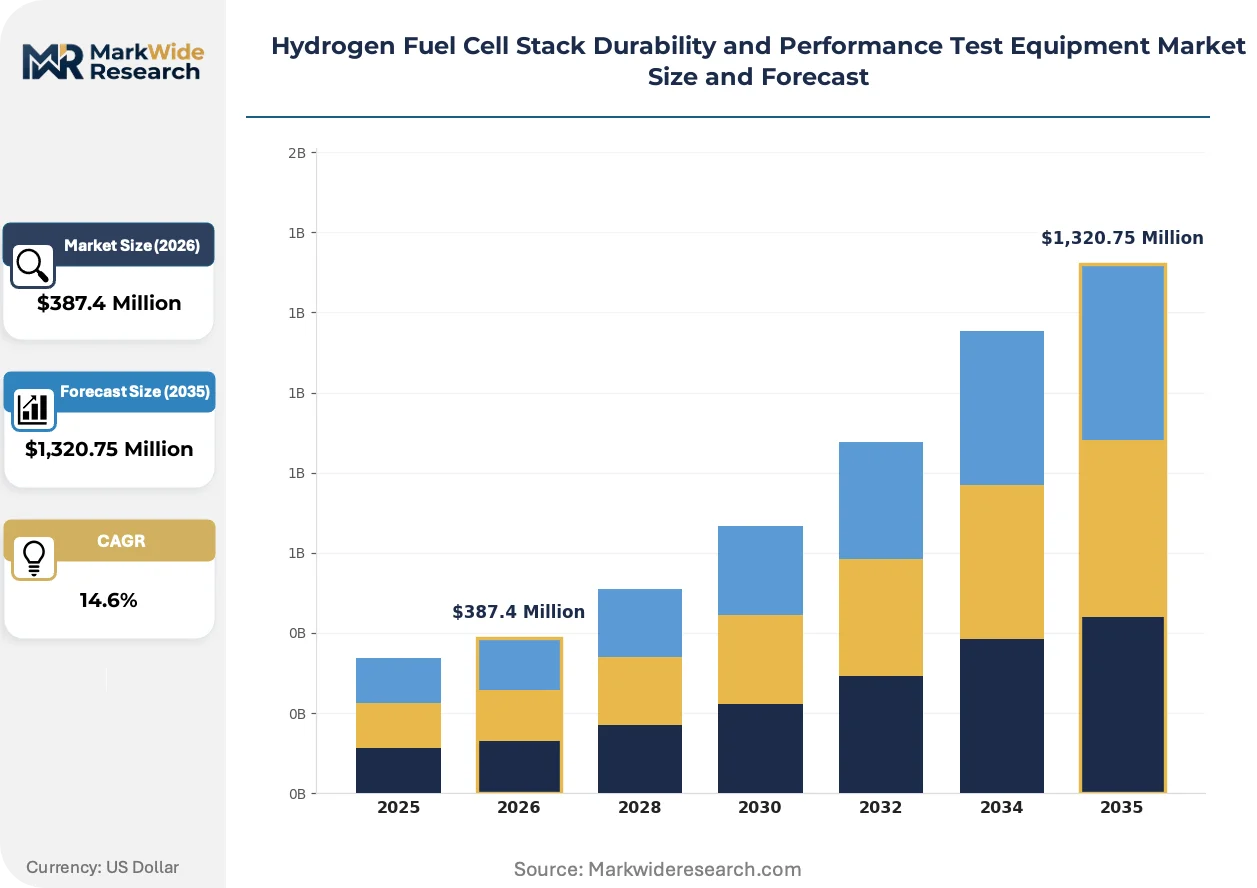
Market Dynamics
Accelerated degradation protocols are compressing validation timelines while thousand-hour test durations remain mandatory, forcing equipment vendors to architect modular platforms that adapt to jurisdiction-specific durability thresholds without stranded asset exposure.
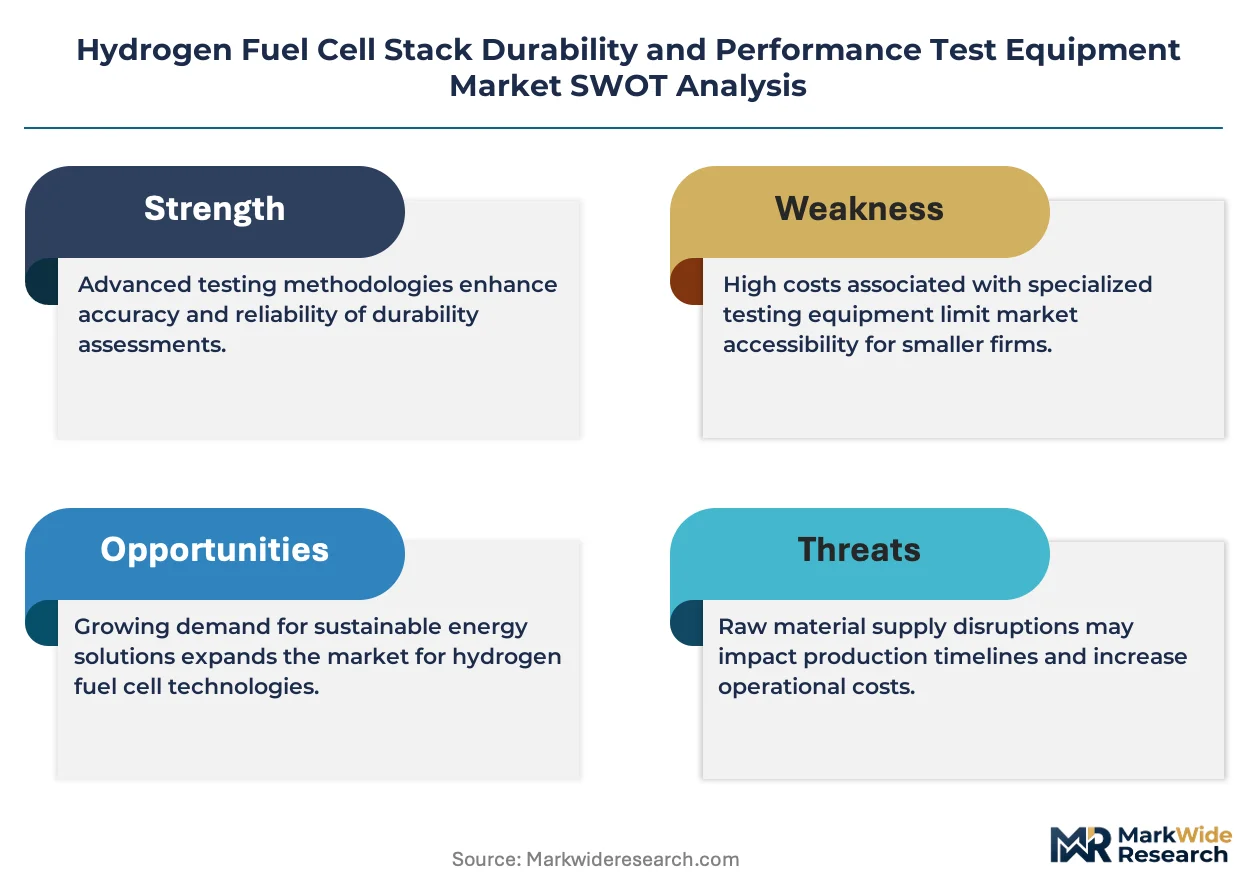
Growth Catalysts
- EU F-Gas Regulation:Fluorinated membrane material restrictions are lengthening test cycles for European fuel cell developers, expanding demand for electrochemical impedance spectroscopy systems that track degradation in-situ.
- Heavy-duty truck validation:Manufacturers across Germany, Japan, and South Korea are scaling fuel cell stack certification programs ahead of commercial deployment, concentrating procurement in national hydrogen corridor clusters.
- Accelerated Stress Testing protocols:Developers are adopting faster degradation simulation methods to compress warranty validation timelines, pulling investment toward thermal cycling chambers capable of extreme current density operation.
Market Restraints
- Platinum group metal volatility:Membrane electrode assembly cost fluctuations constrain stack production volumes, indirectly capping test equipment utilization rates at validation facilities.
- Calibration equipment concentration:Precision electrochemical diagnostic stations rely on specialized sensor suppliers concentrated in German and Japanese industrial corridors, creating single-source vulnerability.
- Solid oxide stack thermal limitation:Ceramic electrolyte brittleness under rapid thermal cycling restricts test chamber throughput, elongating capital recovery periods for durability system operators.
Strategic Opportunities
- India hydrogen roadmap gaps:National hydrogen mission targets lack mature stack certification infrastructure, opening first-mover positioning for test equipment vendors in Pune and Chennai automotive corridors.
- EU AI Act compliance services:Algorithmic transparency mandates for automated pass-fail determination create adjacent revenue streams in validation software and audit documentation.
- Maritime fuel cell convergence:Solid oxide and proton exchange membrane hybrid architectures for shipping propulsion require new multi-chemistry test cell configurations absent from current product portfolios.
Industry Challenges
- Electrochemical diagnostics talent scarcity:Specialized technicians capable of interpreting impedance spectra and correlating degradation mechanisms to failure modes command premium compensation, constraining facility expansion.
- Cross-jurisdiction certification timelines:Equipment must satisfy EPA tailpipe protocols, EU F-Gas material restrictions, and METI hydrogen safety standards simultaneously, fragmenting engineering resources.
- Legacy test cell retrofit complexity:Existing mechanical load frames lack digital thread architecture for real-time data streaming, forcing capital-intensive replacement cycles rather than modular upgrades.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market Trends and Innovations
Digital twin architectures and real-time degradation modeling are displacing static test protocols, compressing the feedback loop between laboratory validation and stack design iteration while regulatory algorithmic mandates reshape automation requirements.
Electrochemical Impedance Spectroscopy is integrating distributed sensor arrays throughout stack architectures to capture spatial degradation heterogeneity previously invisible to terminal-only measurement. Automotive OEMs in Germany and Japan are deploying these systems at full-scale validation facilities. This distributed sensing architecture is integrating predictive maintenance algorithms that flag cell-to-cell voltage divergence before catastrophic failure, compressing warranty risk exposure for stack suppliers.
Japan's METI hydrogen safety standards now mandate third-party witnessed validation for commercial fuel cell deployment, elevating test equipment calibration traceability requirements. Industrial consequence includes mandatory ISO 17025 accreditation for facilities serving Japanese automotive supply chains. Korean and German test houses are responding by consolidating certification documentation workflows into unified digital audit trails that satisfy multiple jurisdiction requirements simultaneously.
Buyer concentration among heavy-duty truck manufacturers is consolidating procurement leverage, forcing equipment vendors toward performance-guarantee contract structures that transfer operational risk. Traditional capital-sale arrangements are yielding to outcome-based engagements where payment ties to validated stack lifetime achievement. This restructuring is most visible in European corridors where Green Deal compliance deadlines compress procurement decision cycles and OEMs demand shared accountability for certification outcomes.
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market Segmentation
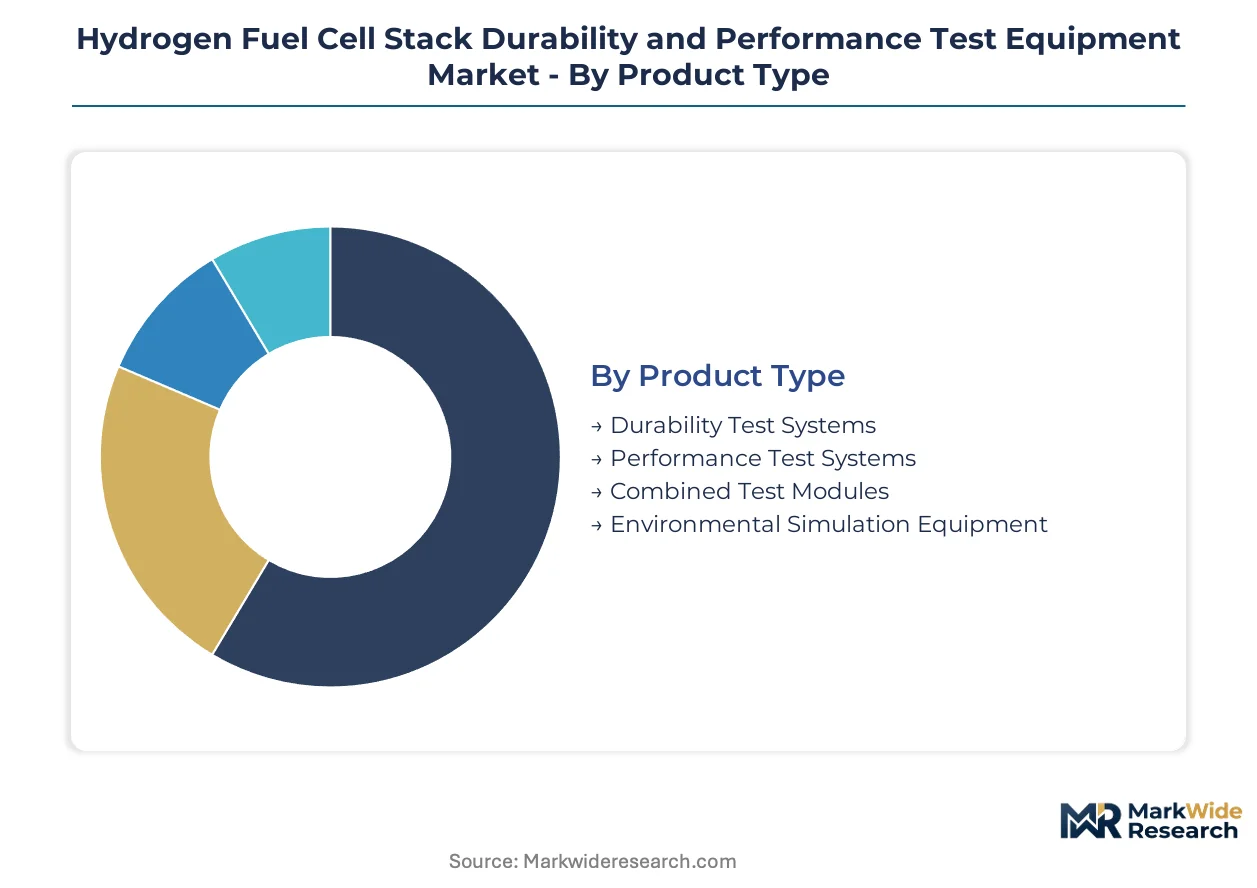
Test equipment procurement patterns diverge sharply between validation-heavy automotive programs and research-oriented development cycles. Equipment specifications, pricing tiers, and service attach rates track directly to buyer maturity and stack commercialization timelines.
Product Type:
Investment thresholds separate buyers pursuing full-stack warranty validation from those targeting component-level screening.
- Durability Test Systems:These platforms execute thousand-hour minimum degradation protocols at current densities exceeding 2.0 A/cm², incorporating electrochemical impedance spectroscopy for in-situ tracking. Procurement concentrates among German and Japanese heavy-duty truck manufacturers facing EU Green Deal compliance deadlines and METI hydrogen safety mandates.
- Performance Test Systems:Equipment validates power output, efficiency curves, and thermal response under variable load profiles. Korean automotive OEMs and Tier-1 suppliers deploy these systems for pre-certification screening before committing to full durability cycles.
- Combined Test Modules:Integrated platforms merge durability and performance capabilities for facilities with constrained capital budgets.
- Environmental Simulation Equipment:Chambers replicate altitude, humidity, and temperature extremes for stack conditioning protocols.
Durability Test Systems lead volumes today; Combined Test Modules are gaining share fastest.
Technology:
Adoption velocity correlates with regulatory pressure to compress validation timelines without sacrificing warranty integrity.
- Electrochemical Impedance Spectroscopy:Distributed sensor arrays capture spatial degradation heterogeneity invisible to terminal-only measurement. German validation facilities deploy these systems for real-time cell-to-cell voltage divergence detection.
- Accelerated Stress Testing:Protocols compress warranty validation through extreme thermal and current cycling. Japanese developers favor this approach under METI mandates for faster commercial deployment timelines.
- Thermal Cycling:Chambers subject stacks to rapid temperature ramps testing ceramic electrolyte brittleness limits.
- Mechanical Vibration Analysis:Load frames simulate transport and operational vibration spectra for automotive integration.
Electrochemical Impedance Spectroscopy anchors current procurement; Accelerated Stress Testing shows steepest expansion trajectory.
Application:
End-use durability requirements dictate test cycle length and sensor density specifications.
- Stationary Power Generation:Extended operational lifespans demand rigorous degradation tracking. Korean utility-scale deployments and German industrial cogeneration projects drive specification tightening.
- Portable Power Units:Compact form factors require miniaturized test cells with rapid throughput. Japanese material handling and backup power developers prioritize these systems.
- Material Research:Academic and national laboratory programs focus on membrane electrode assembly innovation.
- Quality Assurance:Production-line screening ensures outgoing stack consistency against OEM warranty thresholds.
Stationary Power Generation dominates capital deployment; Portable Power Units are climbing the fastest.
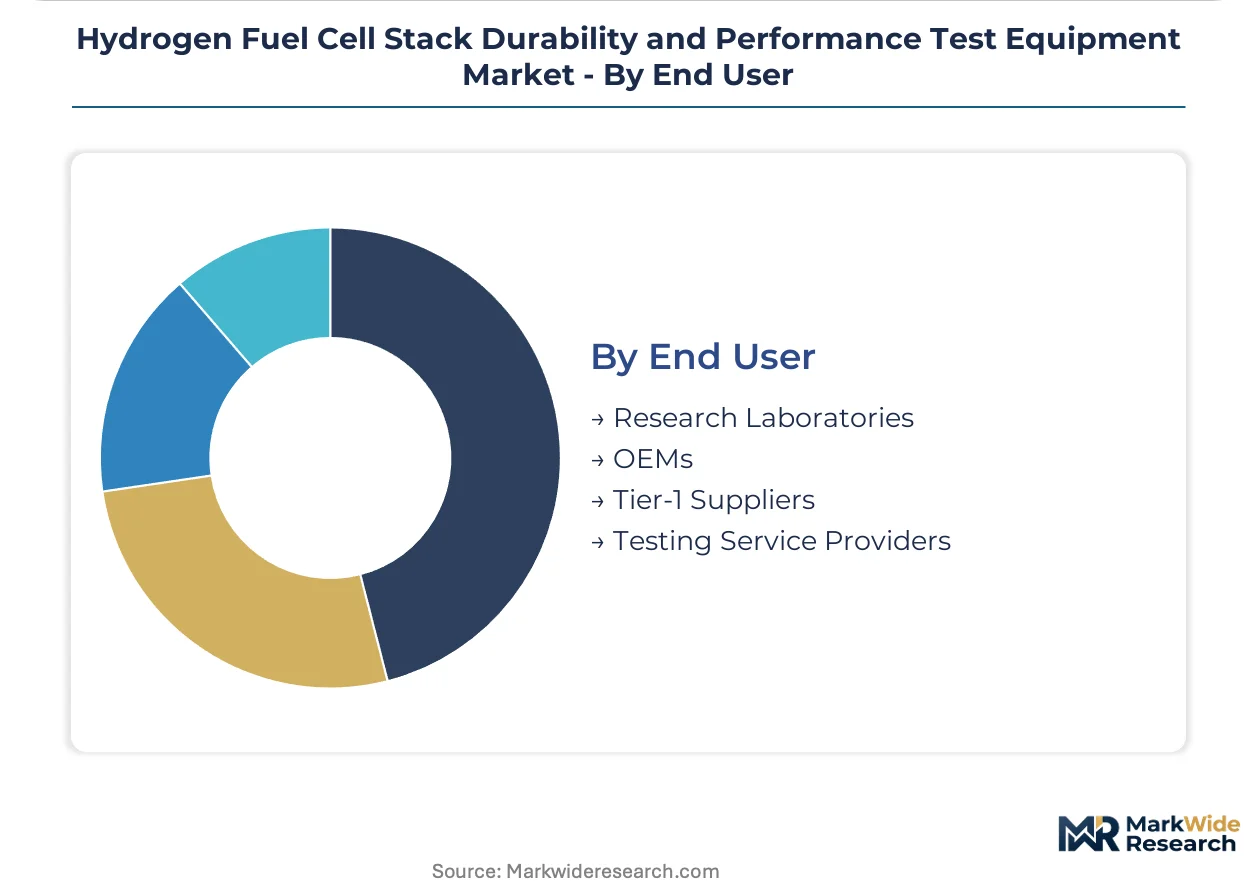
End User:
Facility accreditation requirements and calibration traceability standards fragment the buyer landscape.
- Research Laboratories:National hydrogen institutes and university consortia in Germany, Japan, and South Korea operate pre-competitive validation programs. METI-mandated ISO 17025 accreditation is elevating equipment calibration requirements.
- OEMs:Heavy-duty truck manufacturers internalize critical durability validation to protect warranty exposure. Procurement concentrates in Stuttgart, Toyota City, and Seoul metropolitan clusters.
- Tier-1 Suppliers:Stack subsystem vendors perform incoming quality verification and outgoing certification.
- Testing Service Providers:Independent laboratories serve developers lacking captive validation infrastructure.
OEMs command the largest equipment budgets; Testing Service Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electrochemical diagnostics technicians cluster in Stuttgart, Toyota City, and Seoul metropolitan corridors, anchoring validation infrastructure deployment decisions for heavy-duty truck manufacturers.
Germany
Heavy-duty truck manufacturers in Stuttgart and Munich are expanding fuel cell validation programs ahead of EU Green Deal compliance deadlines. The EU F-Gas Regulation on fluorinated membrane materials is lengthening test cycles for European developers. Electrochemical impedance spectroscopy system procurement concentrates in Baden-Württemberg validation facilities serving automotive OEM warranty thresholds.
Japan
Automotive OEMs in Toyota City and Nagoya metropolitan clusters are scaling stack certification programs under compressed commercial deployment timelines. METI hydrogen safety standards mandate third-party witnessed validation with ISO 17025 accreditation for facility calibration traceability. Accelerated stress testing protocol adoption is pulling investment toward thermal cycling chambers in Chubu industrial corridors.
South Korea
Utility-scale stationary power deployments and automotive OEM pre-certification screening are driving specification tightening in Seoul metropolitan and Busan-Ulsan clusters. National hydrogen roadmaps prioritize stack longevity certification for commercial fuel cell deployment. Korean test houses are consolidating certification documentation into unified digital audit trails satisfying multiple jurisdiction requirements.
United States
Research-oriented membrane electrode assembly cycling programs anchor demand in national laboratory corridors, with EPA tailpipe rules reshaping equipment specifications for automotive integration. Portable power unit developers prioritize miniaturized test cells with rapid throughput for material handling applications. Procurement leverage concentrates among heavy-duty truck manufacturers demanding performance-guarantee contract structures.
India
National hydrogen mission targets lack mature stack certification infrastructure, opening first-mover positioning for test equipment vendors in Pune and Chennai automotive corridors. The country's central renewable energy authority is establishing framework conditions for hydrogen valley deployment. Academic and national laboratory programs in Maharashtra and Tamil Nadu focus on membrane electrode assembly innovation with constrained capital budgets.
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the equipment landscape, producing a tiered structure where scale-driven engineering houses and narrow-niche technology vendors coexist. The vendor base spans electrochemical diagnostic stations, thermal cycling chambers, and integrated multi-chemistry test cells. Three archetypes dominate: diversified instrumentation conglomerates with cross-industry calibration expertise, automotive-focused engineering specialists with OEM validation relationships, and pure-play fuel cell technology vendors with membrane electrode assembly cycling specialization. Competitive moves center on modular platform architecture for jurisdiction-specific protocol adaptation and outcome-based contract structures transferring operational risk to equipment suppliers.
Among European engineering specialists, AVL List GmbH and FEV Group exemplify the automotive-validation archetype with Graz and Aachen engineering heritage anchoring electrochemical workflow relationships. HORIBA represents the diversified instrumentation conglomerate model, occupying a position spanning integrated emissions-and-durability test cells across multiple fuel cell chemistries. Greenlight Innovation sits within the pure-play specialist tier, with membrane electrode assembly cycling rigs occupying a narrow but defensible niche in North American research corridors.
| Leading Market Players |
|---|
| AVL List GmbH |
| HORIBA |
| Greenlight Innovation |
| Scribner Associates |
| CHINO Corporation |
| ENORISE |
| FEV Group |
| TOYO Corporation |
| Commonwealth Automation Technologies |
| Others |
Pricing and Supply Chain Analysis
Specialized electrochemical diagnostics technicians clustering in Stuttgart, Toyota City, and Seoul metropolitan corridors create labor-cost differentials that widen pricing-tier spreads between premium validation facilities and economy-tier screening operations. Equipment vendors serving METI-mandated ISO 17025 accreditation requirements command substantial premiums over unaccredited competitors in emerging hydrogen corridors.
Pricing Analysis
The bundled-versus-unbundled service split separates outcome-based performance-guarantee contracts from traditional capital-sale arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU F-Gas Regulation compliance and METI hydrogen safety mandates elevating premium-tier thresholds. Cost compression in the economy tier is intensifying because Indian national hydrogen mission targets lack mature infrastructure, forcing price competition among first-mover vendors. Tier-1 suppliers and research laboratories exhibit highest price sensitivity; heavy-duty truck OEMs internalizing warranty risk show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with precision sensor suppliers concentrated in German and Japanese industrial corridors. Electrochemical diagnostic stations draw from platinum group metal membrane electrode assemblies, ceramic electrolyte solid oxide components, and fluorinated membrane materials subject to EU F-Gas Regulation restrictions. Tariff exposure runs through calibration equipment imports serving Japanese automotive supply chains. Distribution runs through direct OEM procurement in Stuttgart, Toyota City, and Seoul clusters alongside testing service provider channels in research corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation material restrictions and METI hydrogen safety mandates continuously elevate equipment specifications and calibration traceability requirements, driving replacement cycles rather than modular upgrades.
For Market Incumbents: Anticipate algorithmic transparency mandates from the EU AI Act reshaping automated pass-fail determination workflows, forcing certification investment in validation software audit documentation. Defensive consolidation through backward integration into precision sensor supply chains mitigates single-source vulnerability in German and Japanese industrial corridors. Channel control over ISO 17025 accreditation workflows protects margin position against emerging pure-play specialists.
For New Entrants and Emerging Players: Testing service providers represent the most penetrable channel partner type for establishing footprint without captive validation infrastructure investment. White-space targets concentrate in Indian Pune and Chennai automotive corridors where national hydrogen mission targets lack mature stack certification infrastructure, and maritime fuel cell convergence creates demand for multi-chemistry test cell configurations absent from current portfolios. Go-to-market positioning through combined test modules addresses facilities with constrained capital budgets.
For Investors and Strategic Acquirers: Diversified instrumentation conglomerates with cross-industry calibration expertise are the most active acquirer in this space, seeking electrochemical diagnostic specialization to complement existing emissions testing portfolios. Long-term viability over the projection horizon hinges on modular platform architecture enabling jurisdiction-specific protocol adaptation without stranded asset exposure. Acquisition target archetype: pure-play fuel cell technology vendors with membrane electrode assembly cycling specialization and established relationships in North American research corridors. The signal to watch is consolidation of certification documentation workflows into unified digital audit trails satisfying multiple jurisdiction requirements simultaneously.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Architecture | Enables adaptation to EU F-Gas, METI, and EPA protocols without stranded asset exposure. |
| ISO 17025 Accreditation Investment | Mandatory for facilities serving Japanese automotive supply chains under METI mandates. |
| Outcome-Based Contract Structuring | Transfers operational risk to equipment suppliers as Green Deal deadlines compress procurement cycles. |
| Digital Twin Integration | Compresses feedback loops between laboratory validation and stack design iteration for automotive OEMs. |
| Multi-Chemistry Test Cell Development | Addresses solid oxide and proton exchange membrane hybrid architectures for maritime propulsion. |
Research Methodology
Direct dialogue with electrochemical validation facility directors, fuel cell stack procurement managers at heavy-duty truck OEMs, Tier-1 supplier quality assurance leads, and national hydrogen institute program officers grounded qualitative assessment in operational realities. Secondary validation drew from EPA tailpipe protocol filings, EU F-Gas Regulation implementation guidance, METI hydrogen safety standard documentation, and automotive OEM warranty threshold disclosures. Bottom-up equipment procurement tracking and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation-level outputs reflect modeling across durability versus performance test system categories, electrochemical impedance spectroscopy versus accelerated stress testing technology adoption curves, and stationary power versus portable power application deployment patterns. CAGRs were derived from thousand-hour test duration mandates, platinum group metal cost volatility impacts on stack production volumes, and regulatory timeline compression effects. Industry-specific forecast inputs incorporated EU AI Act algorithmic transparency implementation schedules and Korean utility-scale stationary power deployment trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum group metal price volatility, ceramic electrolyte brittleness breakthroughs in solid oxide architectures, and maritime fuel cell hybrid commercialization timelines. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM warranty threshold stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.