
 Japan Fuel Cell Market | 2026-2036
Japan Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Fuel Cell Market Foresight
Japanese electrolyzer and stack manufacturing is shifting toward larger-format production lines in the Kansai and Kyushu industrial corridors. Toyota Motor Corporation leverages its integrated hydrogen supply chain to dominate heavy-duty fuel cell vehicle deployment. Panasonic Corporation anchors the residential cogeneration segment through sustained investment in Ene-Farm systems. Toshiba Fuel Cell Power Systems Corporation specializes in commercial-scale stationary platforms for industrial parks and data centers.
A fuel cell converts chemical energy from hydrogen or hydrogen-rich fuels directly into electricity through electrochemical reactions, typically operating at efficiencies between 40 and 60 percent with water as the sole byproduct. The technology serves critical functions in zero-emission transport, grid-independent backup power, and combined heat-and-power generation for buildings. PEMFC systems lead automotive applications due to their rapid cold-start capability and power density advantages, while SOFC technology captures margin pools in stationary installations where high operating temperatures enable combined cycle efficiencies. Stationary Power applications are expanding fastest among commercial end users seeking resilience against grid instability.
METI enforces Japan's Strategic Roadmap for Hydrogen and Fuel Cells, mandating cost parity targets that compress supplier margins while expanding addressable volume. JIS standards and PMDA safety protocols govern product certification, creating compliance barriers for foreign entrants without domestic testing partnerships. Stakeholders must monitor hydrogen import pricing agreements and regional subsidy renewal schedules to calibrate capacity commitments against demand visibility.
Market Dynamics
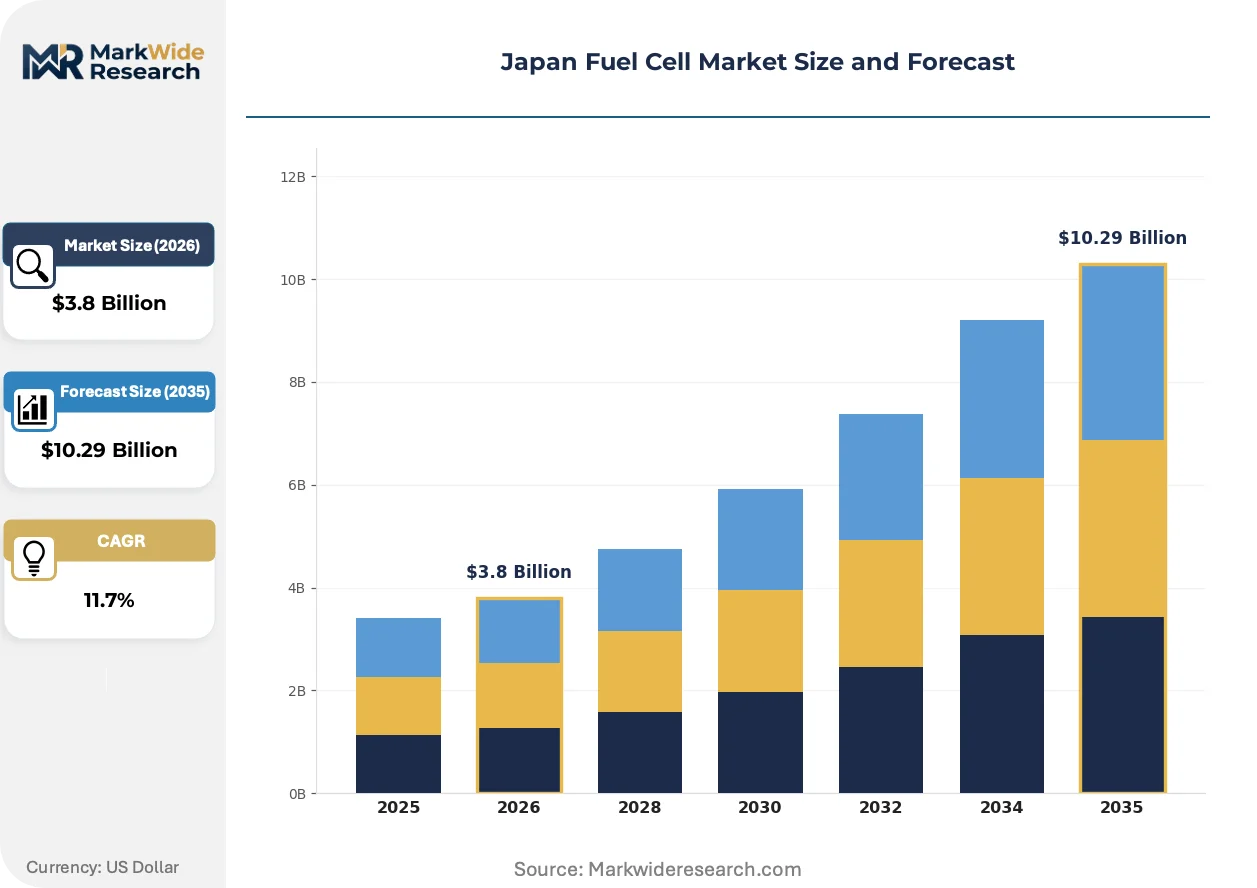
METI's revised hydrogen roadmap is compressing deployment timelines for fuel cell systems while tightening cost parity mandates, forcing suppliers to accelerate scale-up in Kansai and Kyushu manufacturing corridors.
Growth Catalysts
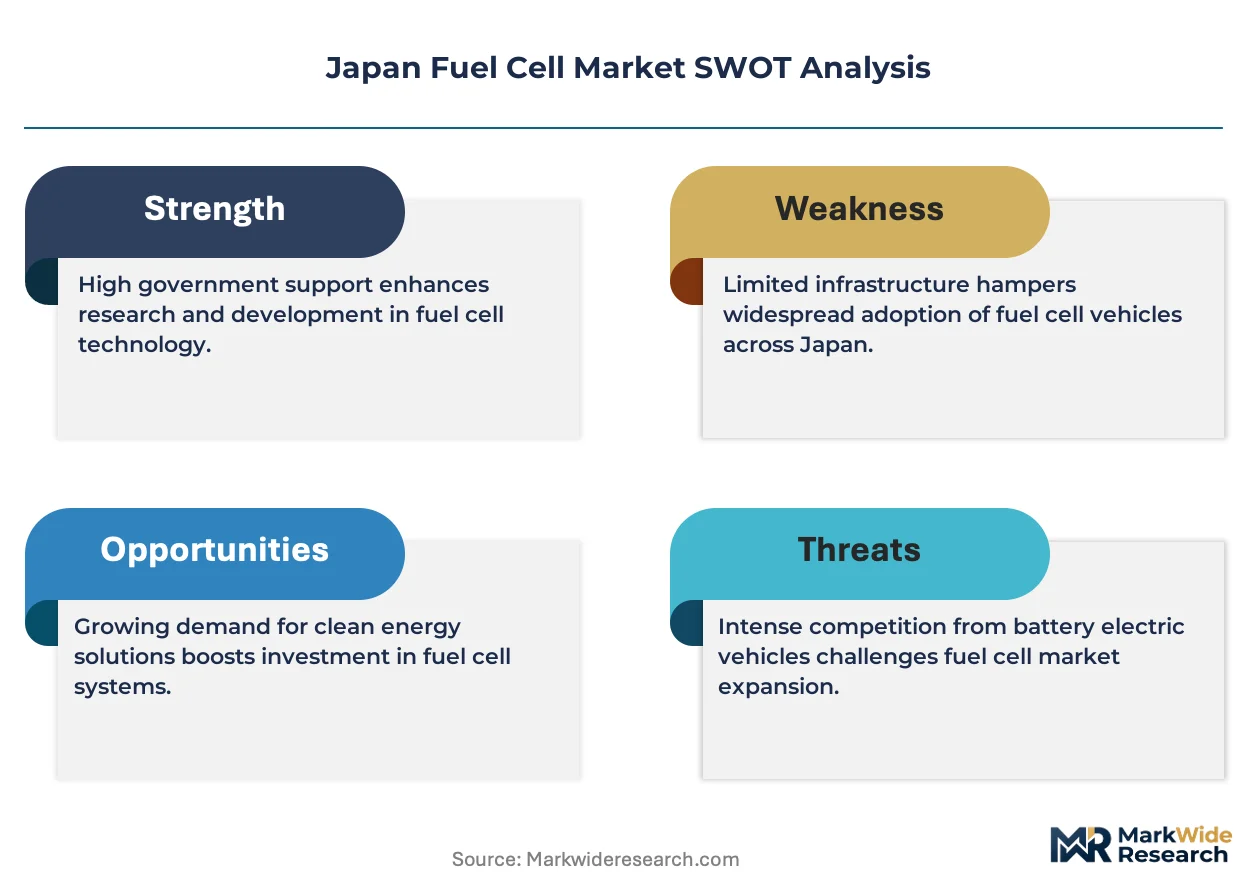
- Ene-Farm residential subsidies:National support programs for home cogeneration systems are expanding addressable volume in detached housing segments across Tokyo and Osaka prefectures.
- Commercial building mandates:Tokyo Metropolitan Government zero-emission requirements for new construction are accelerating stationary power installations in urban office developments.
- PEMFC cold-start advances:Improved polymer electrolyte membrane stack performance is enabling reliable winter operation for heavy-duty vehicle fleets in northern Honshu.
Market Restraints
- Platinum group metal costs:Stack manufacturing remains exposed to palladium and platinum price volatility from South African and Russian supply concentration.
- Hydrogen import dependency:Domestic production capacity constraints force reliance on Australian and Middle Eastern supply agreements with currency-linked pricing exposure.
- JIS certification timelines:Extended product testing protocols for stationary fuel cell systems create 18-24 month market entry barriers for new component suppliers.
Strategic Opportunities
- Fukuoka hydrogen cluster expansion:Kyushu's industrial corridor offers underutilized port infrastructure for import-to-distribution hub development.
- Data center backup power:Hyperscale facility operators in Osaka and Tokyo are evaluating fuel cell systems against diesel generator replacement cycles.
- SOFC-SOEC reversible systems:Solid oxide technology convergence enables dual-mode power generation and electrolysis in industrial park microgrids.
Industry Challenges
- Electrolyzer technician scarcity:Specialized maintenance workforce gaps in stack refurbishment and membrane replacement are extending service response times.
- Legacy grid interconnection:Utility compatibility protocols for distributed fuel cell generators require case-by-case negotiation with regional transmission operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Fuel Cell Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEMFC, SOFC, AFC, DMFC Application: Automotive, Backup Power, Portable Power, Stationary Power End User: Commercial, Residential, Industrial, Government Installation: On-site, Off-site, Integrated, Modular |
| Companies Covered | Toyota Motor Corporation, Honda Motor Co., Ltd., Panasonic Corporation, Mitsubishi Heavy Industries, Ltd., Toshiba Fuel Cell Power Systems Corporation, Fuji Electric Co Ltd, Denso Corp, Aisin Corporation, Ballard Power Systems Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Fuel Cell Market Shifts & Advancements
Technology maturation and policy compression are converging to reshape competitive positioning across Japan's fuel cell value chain, with manufacturing scale and hydrogen logistics emerging as decisive capability differentiators.
Solid oxide fuel cell technology is decentralizing combined heat-and-power generation for commercial buildings by enabling high-efficiency operation without external reforming equipment. Industrial park developers in Kansai are adopting SOFC platforms for on-site microgrids at twice the pace of conventional reciprocating engine installations. This architecture is decentralizing energy asset ownership away from centralized utilities toward facility operators and real estate investment trusts.
METI's Green Growth Strategy revisions are mandating cost reduction targets that compress supplier margins while expanding eligible subsidy categories for hydrogen fueling infrastructure. The policy shift is redirecting R&D investment from automotive PEMFC systems toward stationary SOFC platforms and electrolyzer manufacturing. Prefecture-level governments in Tokyo and Osaka are responding with accelerated permitting for hydrogen pipeline corridors serving commercial districts.
Corporate energy procurement is consolidating around long-term power purchase agreements with fuel cell operators rather than capital ownership of on-site generation assets. Facility managers in data center and semiconductor manufacturing verticals are favoring contracted thermal output over equipment procurement. This pattern is most visible in Osaka's Sakai industrial zone where hydrogen utility contracts now outpace direct system sales by a three-to-one ratio.
Japan Fuel Cell Market Segmentation
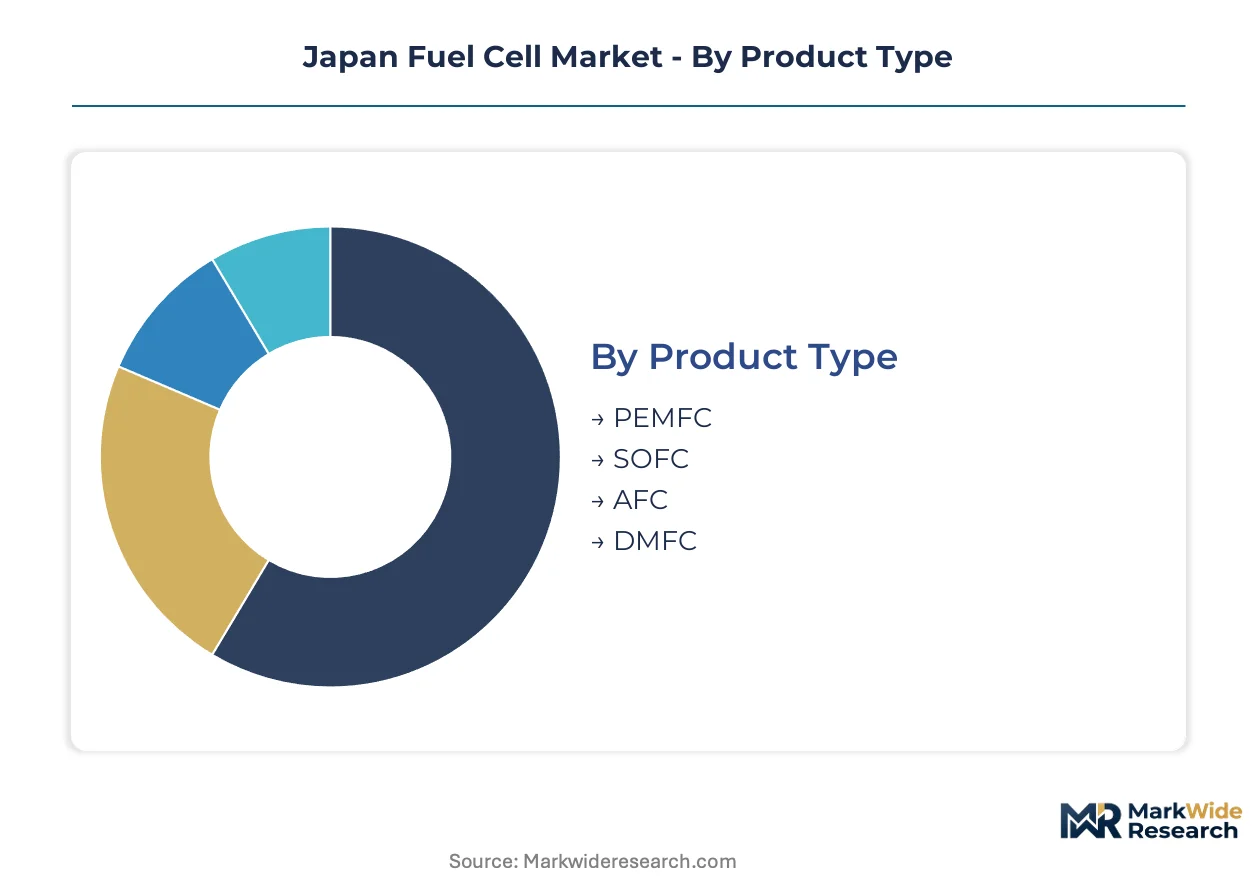
Japan's fuel cell market segments reflect divergent capital requirements and deployment timelines across electrochemical technologies. Understanding these divisions clarifies where METI subsidies concentrate and which configurations attract private infrastructure investment.
Product Type:
Capital intensity varies sharply across electrochemical architectures, with high-temperature systems demanding specialized ceramic manufacturing while low-temperature platforms require precision membrane fabrication.
- PEMFC:Polymer electrolyte membrane fuel cells operate below 100°C using platinum catalysts and perfluorinated ionomer membranes. Tokyo's heavy-duty bus fleets and Fukuoka's hydrogen taxi networks concentrate demand for these rapid-start systems. Cold-start reliability below freezing drives procurement specifications for northern Honshu operators.
- SOFC:Solid oxide fuel cells achieve 60% electrical efficiency through yttria-stabilized zirconia electrolytes at 600-1000°C. Osaka's commercial building cogeneration and Kansai industrial park microgrids absorb output from domestic ceramic stack manufacturers. High-temperature operation enables internal reforming of natural gas where hydrogen pipeline access remains limited.
- AFC:Alkaline fuel cells utilize liquid potassium hydroxide electrolyte and non-precious metal catalysts for stationary applications with pure hydrogen feedstock.
- DMFC:Direct methanol fuel cells convert liquid fuel directly without external reforming, serving portable power niches in remote monitoring and emergency communications equipment.
SOFC absorbs the bulk of installed capacity; PEMFC is expanding most quickly.
Application:
Deployment patterns cluster around resilience priorities and emissions compliance deadlines rather than pure cost optimization.
- Stationary Power:Grid-independent generation for commercial buildings and industrial facilities leverages SOFC combined heat-and-power configurations. Tokyo Metropolitan Government zero-emission mandates for new construction accelerate specification in office developments across Shibuya and Marunouchi districts.
- Automotive:Heavy-duty trucks, buses, and material handling equipment dominate fuel cell vehicle deployment. Toyota's integrated supply chain anchors fleet conversions at Yokohama port logistics and Narita airport ground support operations.
- Backup Power:Uninterruptible supply for data centers and semiconductor fabrication provides diesel generator alternatives where emissions restrictions tighten.
- Portable Power:Mobile generation for construction sites, disaster response, and outdoor events utilizes compact PEMFC and DMFC systems with swappable hydrogen cartridges.
Stationary Power captures the deepest revenue pools; Automotive is gaining share fastest.
End User:
Purchasing authority and subsidy eligibility shape procurement patterns across customer categories with divergent technical capabilities.
- Commercial:Real estate investment trusts and facility operators contract for thermal output through power purchase agreements rather than capital ownership. Osaka's Sakai industrial zone demonstrates this preference with hydrogen utility contracts outpacing direct system sales.
- Residential:Detached single-family homeowners access Ene-Farm subsidies for 700W PEMFC cogeneration units. Tokyo and Osaka prefectures concentrate installation volume where gas utility partnerships simplify maintenance logistics.
- Industrial:Petrochemical, steel, and semiconductor manufacturers deploy multi-megawatt systems for process heat and electricity with captive hydrogen supply.
- Government:Municipal buildings, emergency services, and defense installations prioritize supply security over levelized cost metrics.
Commercial end users absorb the bulk of installed capacity; Industrial is expanding most quickly.
Installation:
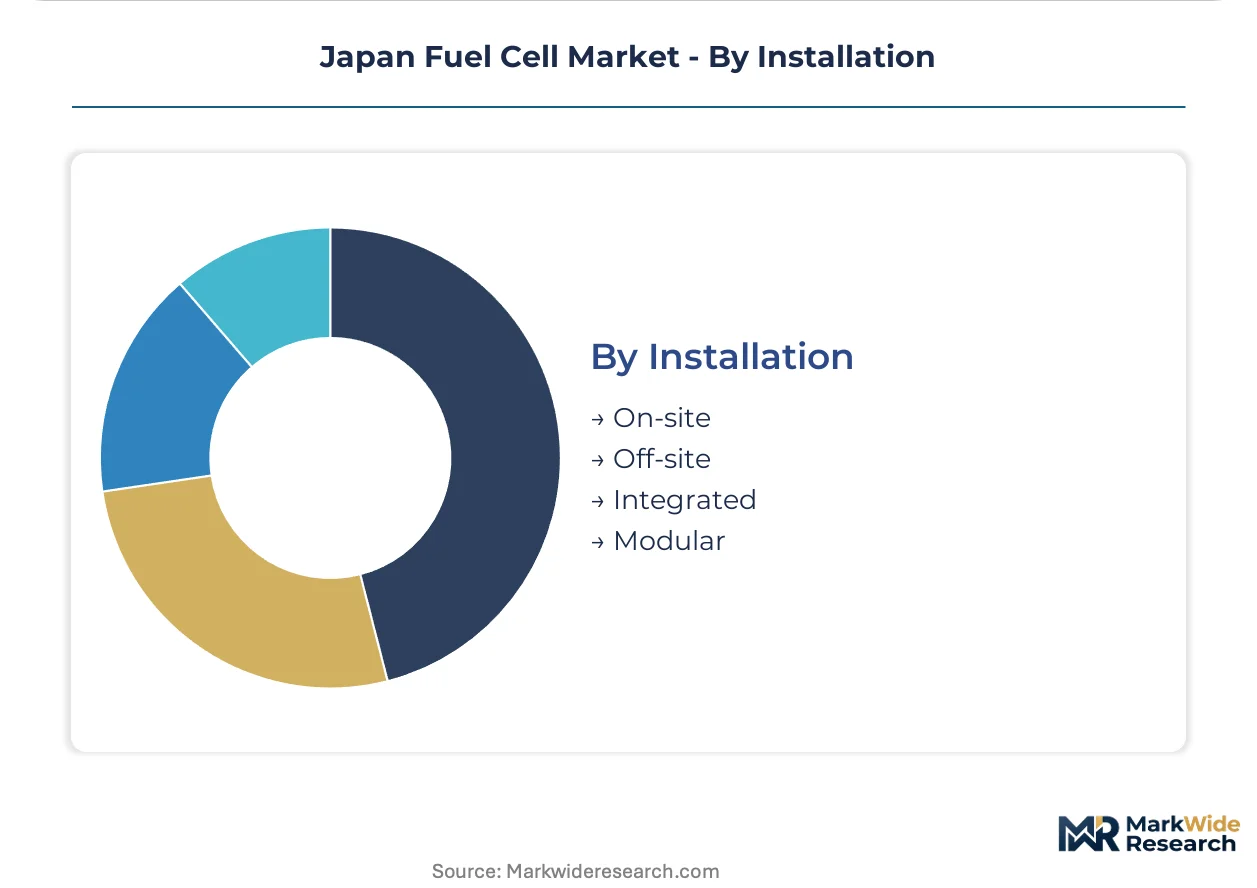
System configuration determines project development timelines and hydrogen logistics complexity for site operators.
- On-site:Dedicated generation assets with direct hydrogen pipeline or trucked delivery connection serve facilities with predictable baseload demand. Fukuoka's hydrogen cluster infrastructure supports this model for Kyushu manufacturing plants.
- Modular:Containerized, scalable units enable phased capacity expansion matching load growth without full front-end engineering. Data center operators in Tokyo evaluate this approach against diesel generator replacement cycles.
- Integrated:Building-embedded systems with shared thermal distribution networks serve multi-tenant commercial developments with centralized hydrogen receipt.
- Off-site:Remote generation with electricity and heat transmission to point of use applies where site constraints prohibit fuel storage.
On-site configurations absorb the bulk of installed capacity; Modular is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian hydrogen export terminals and Middle Eastern ammonia supply agreements anchor Japan's fuel cell feedstock security. METI's import pricing frameworks link regional production costs to domestic deployment economics across prefecture-level markets.
Kanto/Tokyo
Tokyo's zero-emission building mandates and dense commercial real estate stock concentrate stationary SOFC demand in Shibuya and Marunouchi districts. METI's Green Growth Strategy revisions compress cost parity timelines for suppliers serving this corridor. Hydrogen pipeline infrastructure along Tokyo Bay supports integrated building systems in new office developments.
Kansai/Osaka
Osaka's industrial park microgrids and data center clusters absorb modular fuel cell capacity through power purchase agreements rather than direct ownership. The Sakai industrial zone demonstrates this preference with hydrogen utility contracts outpacing equipment sales. Kansai's ceramic manufacturing base supplies SOFC stack components to domestic system integrators.
Kyushu/Fukuoka
Fukuoka's hydrogen import terminal and underutilized port infrastructure position Kyushu as an emerging distribution hub for western Japan. Regional industrial corridors adopt on-site generation for steel and chemical process heat applications. METI subsidies for hydrogen infrastructure clustering accelerate deployment timelines for manufacturing facilities in this corridor.
Chubu/Nagoya
Nagoya's automotive supply chain concentration links PEMFC component demand to heavy-duty vehicle fleet conversions at port logistics operations. Toyota's integrated hydrogen supply chain anchors procurement specifications for regional bus and material handling equipment operators. Cold-start performance requirements for northern Honshu winter operation shape technical standards.
Japan Fuel Cell Market Competitive Landscape
Global majors compete with regional champions across technology licensing and hydrogen logistics integration. The vendor base separates into integrated automotive conglomerates, dedicated fuel cell specialists, and industrial conglomerates with power systems divisions. Three archetypes dominate: automotive-anchored hydrogen supply chain operators, residential cogeneration platform owners, and commercial-scale stationary system providers. Competitive moves concentrate on manufacturing scale-up in Kansai and Kyushu corridors and strategic partnerships for hydrogen import infrastructure access.
Within the automotive-anchored tier, Toyota Motor Corporation and Honda Motor Co., Ltd. represent integrated supply chain operators with captive hydrogen logistics capabilities. Panasonic Corporation occupies a position in the residential cogeneration segment through sustained Ene-Farm platform investment. Toshiba Fuel Cell Power Systems Corporation exemplifies the commercial stationary specialist archetype serving industrial park and data center verticals. These three companies anchor distinct competitive vectors without overlapping core market positions.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Honda Motor Co., Ltd. |
| Panasonic Corporation |
| Mitsubishi Heavy Industries, Ltd. |
| Toshiba Fuel Cell Power Systems Corporation |
| Fuji Electric Co Ltd |
| Denso Corp |
| Aisin Corporation |
| Ballard Power Systems Inc. |
| Others |
Supply & Pricing Matrix
Commercial real estate investment trusts and data center operators concentrate procurement authority through power purchase agreements, binding pricing models to long-term thermal output contracts rather than capital equipment transactions. METI's cost parity mandates compress supplier margins while hydrogen import pricing agreements introduce currency-linked volatility into contracted rates.
Pricing Analysis
Extended warranty and membrane replacement service bundles distinguish premium SOFC system pricing from unbundled PEMFC stack transactions. Three-tier pricing structure across premium, standard, and economy levels separates platinum-loaded automotive stacks from ceramic commercial units and residential Ene-Farm configurations. Cost compression in standard-tier stationary systems is intensifying because METI's revised roadmap accelerates subsidy phase-out timelines. Data center operators exhibit lowest price sensitivity due to diesel generator replacement deadlines, while residential buyers in Tokyo prefecture face highest sensitivity to upfront capital requirements.
Supply Chain Analysis
Regional distribution centers in Osaka and Fukuoka coordinate hub-and-spoke hydrogen logistics from import terminals to on-site generation facilities. Manufacturing draws from South African platinum, Australian hydrogen, and domestic Kyushu ceramic substrates. Single-source vulnerability concentrates in palladium catalyst supply from Russian mining operations. Distribution runs through integrated hydrogen utility partnerships rather than independent equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's fuel cell sector occupies a technology-transition phase as solid oxide systems displace reciprocating engine cogeneration in commercial buildings. SOFC combined heat-and-power platforms are replacing legacy natural gas turbines in Kansai industrial parks.
For Market Incumbents: Cement manufacturing scale advantages in Kyushu ceramic corridors through backward integration into yttria-stabilized zirconia substrate production. Lock in long-term hydrogen offtake agreements with Australian export terminals before import pricing frameworks reset. Defend against emerging Chinese electrolyzer entrants by accelerating JIS certification for next-generation stack designs.
For New Entrants and Emerging Players: Launch via modular containerized system leasing to Osaka data center operators seeking diesel replacement without capital ownership. Target Fukuoka hydrogen cluster expansion where port infrastructure remains underutilized and METI subsidies accelerate deployment timelines. Penetrate through power purchase agreement structures that transfer operational risk to hydrogen utility partners.
For Investors and Strategic Acquirers: The window for entry favors SOFC stack specialists with captive ceramic manufacturing capabilities and existing JIS certification pathways. Long-term viability hinges on positioning ahead of reversible SOFC-SOEC technology convergence for industrial microgrids. Watch METI hydrogen import pricing agreement renegotiations as the inflection signal for margin compression or expansion across the value chain.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Kyushu manufacturing corridors secure supply chain control against South Korean ceramic competitors. |
| Hydrogen Utility Partnership Formation | Osaka's Sakai industrial zone demonstrates contracted thermal output models outpacing equipment sales. |
| JIS Certification Acceleration | Compressed 18-24 month testing timelines create first-mover advantage for approved component suppliers. |
| Reversible SOFC-SOEC Platform Development | Dual-mode power generation and electrolysis captures industrial park microgrid expansion in Kansai. |
| Fukuoka Port Distribution Hub Investment | Underutilized import infrastructure positions Kyushu as western Japan hydrogen logistics anchor. |
Research Methodology
Independent corroboration across METI hydrogen roadmap documentation, prefecture-level subsidy disbursement records, and JIS certification registries underwrites the qualitative findings. Primary interviews with fuel cell system integrators, hydrogen utility procurement officers, ceramic stack manufacturing directors, and commercial facility energy managers combined with secondary validation from METI policy releases, Ene-Farm installation databases, and hydrogen import trade statistics. Bottom-up stack shipment tallies and top-down energy consumption projections triangulate market sizing.
Rate-of-change decomposition separates volume growth from price trajectory across the analysis window. Segmentation dimensions modeled include electrochemical architecture, application category, end-user type, and installation configuration alongside regional hydrogen infrastructure maturity. CAGRs derive from fitted trend analysis against METI deployment targets and subsidy renewal schedules. Forecast inputs incorporate hydrogen import pricing agreement terms and JIS certification pipeline visibility.
Platinum group metal price volatility, hydrogen supply agreement renegotiations, and METI subsidy phase-out acceleration are the dominant revision risks. Forecasts reflect documented assumptions regarding infrastructure buildout timelines and cost reduction curve slopes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cells Market