
 Commercial Generator Market | 2026-2036
Commercial Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Generator Market Analysis
Market Dynamics and Competitive Landscape
China is narrowing its diesel engine supply gap through domestic foundry and alternator investments. Caterpillar Inc. leverages captive component manufacturing to control lead times across Asian distribution channels. Cummins Inc. anchors its position with a vertically integrated power systems platform spanning engines, controls, and exhaust after-treatment. Generac Power Systems, Inc. specializes in gaseous-fueled stationary units for healthcare and data center applications, competing on emissions compliance rather than upfront cost.
Technical Definition and Segment Structure
A commercial generator is an engine-driven electromechanical device that converts mechanical energy into alternating current electricity, typically rated above 5 kW and designed for continuous, prime, or standby duty cycles in industrial, institutional, or commercial facilities. Diesel configurations dominate heavy-load segments above 300 kW due to fuel energy density and cold-start reliability, though gas and bi-fuel variants gain share where pipeline infrastructure exists and emissions restrictions tighten. Portable and containerized deployments expand fastest in construction and remote mining, while stationary units above 150 kW command the margin pool in data center and healthcare standby applications where NFPA 110 compliance is mandatory.
Regulatory Environment and Strategic Outlook
EPA Tier 4 Final and the EU F-Gas Regulation constrain diesel particulate and fluorinated greenhouse gas emissions, forcing redesigns of cooling and exhaust systems across export-bound product lines. OSHA lockout/tagout standards and NFPA 110 Type 10 startup requirements shape installation protocols and service contract structures in the United States. Stakeholders must monitor carbon border adjustment mechanisms and state-level clean backup mandates, as these will determine whether bi-fuel and hydrogen-ready platforms become standard specification or premium options.
Market Dynamics
EPA Tier 4 Final compliance is forcing diesel generator manufacturers to absorb after-treatment costs while maintaining price competitiveness against gas alternatives, compressing margins and accelerating dual-fuel platform development.
Growth Catalysts
- Data center uptime mandates:Hyperscale operators now require NFPA 110 Type 10 startup guarantees, driving procurement of 500 kW+ stationary units with paralleling controls.
- Grid reliability gaps in India:Industrial clusters in Gujarat and Maharashtra face 8-12 hour daily outages, creating parallel demand for prime-rated diesel and gas generator sets.
- China's dual carbon goals:Provincial emissions trading schemes are accelerating bi-fuel retrofits in manufacturing zones where pipeline gas infrastructure exists.
Market Restraints
- Platinum group metal volatility:Diesel particulate filters and selective catalytic reduction systems depend on palladium and rhodium, with price swings directly hitting landed engine costs.
- Foundry concentration in China:Heavy-duty engine block casting capacity clusters in Shandong and Jiangsu provinces, creating single-source vulnerability for export-bound manufacturers.
- Gas infrastructure asymmetry:Bi-fuel and dedicated gas generators face deployment limits in sub-Saharan Africa and Southeast Asia where pipeline networks remain sparse.
Strategic Opportunities
- Hydrogen-ready platform development:Engine OEMs investing in 20% hydrogen blending capability now will capture first-mover advantage as EU hydrogen backbone corridors mature.
- Containerized rental fleets:Modular 1-2 MW skid-mounted units address construction and remote mining demand in Australia and Chile where capital avoidance drives procurement.
- State-level clean backup mandates:California's SB 100 directives and New York's Local Law 97 are creating premium segments for low-NOx gas generators in commercial real estate.
Industry Challenges
- After-treatment technician scarcity:EPA Tier 4 Final systems require specialized diagnostic capabilities that existing service networks lack, extending repair timelines.
- NFPA 110 commissioning complexity:Type 10 compliance demands synchronized fuel delivery, cooling, and exhaust design that stretches project engineering resources.
- Legacy control integration:Modern paralleling switchgear must interface with 1990s-era building management systems in healthcare retrofits, driving customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Generator Market |
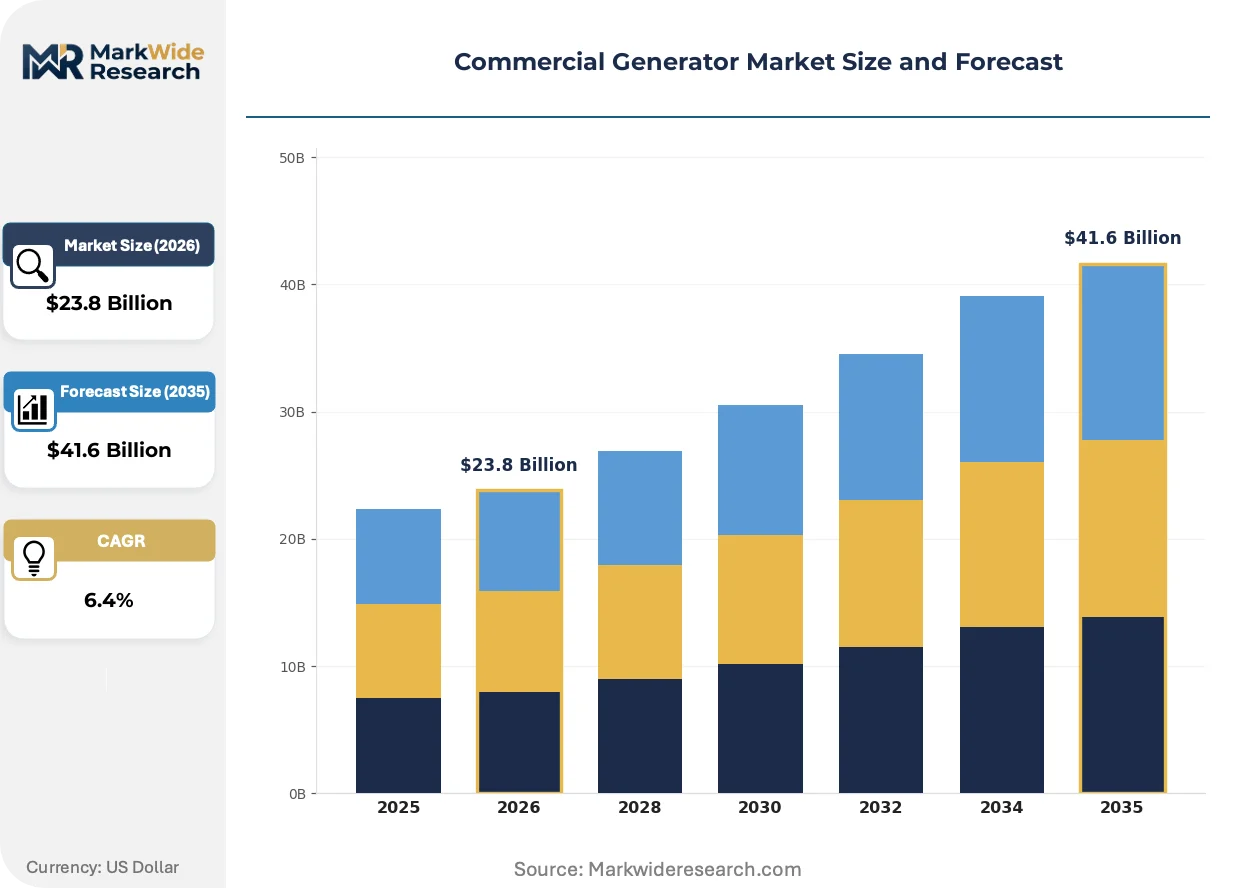
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Diesel, Gas, Propane, Bi-Fuel Power Rating: 0-50 kW, 51-150 kW, 151-300 kW, Above 300 kW Deployment: Portable, Stationary, Mobile, Containerized End User: Construction, Healthcare, Data Centers, Hospitality |
| Companies Covered | Rolls-Royce plc, Kohler Co., Caterpillar Inc., Atlas Copco AB, Doosan Bobcat Inc., Cummins Inc., Mitsubishi Heavy Industries, Ltd., GE Vernova Group, Generac Power Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Generator Market Emerging Trajectories
Generator architecture is converging around software-defined power management, with hardware becoming a commodity substrate for predictive analytics and grid-interactive response capabilities.
Silicon carbide power electronics are collapsing the physical footprint of variable speed drives used in hybrid generator-battery systems. Data center operators in Northern Virginia and Frankfurt are specifying these compact drives for 500 kW+ installations where floor space carries premium lease rates. The technology is collapsing traditional distinctions between prime, standby, and continuous duty ratings by enabling dynamic load-following.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in generator cooling systems, forcing redesigns of closed-loop radiator packages. Manufacturers serving European export markets must now qualify CO2 or propane-based cooling circuits, adding six to nine months to product development cycles. Healthcare and data center segments are absorbing these compliance costs through extended service contracts.
Buyers are consolidating vendor relationships around lifecycle cost guarantees rather than upfront equipment pricing. Large industrial facilities in Texas and Alberta now procure generators through ten-year availability contracts where OEMs retain ownership and charge per kWh delivered. This model shifts capital expenditure to operational budgets while binding manufacturers to uptime performance metrics.
Commercial Generator Market Segmentation
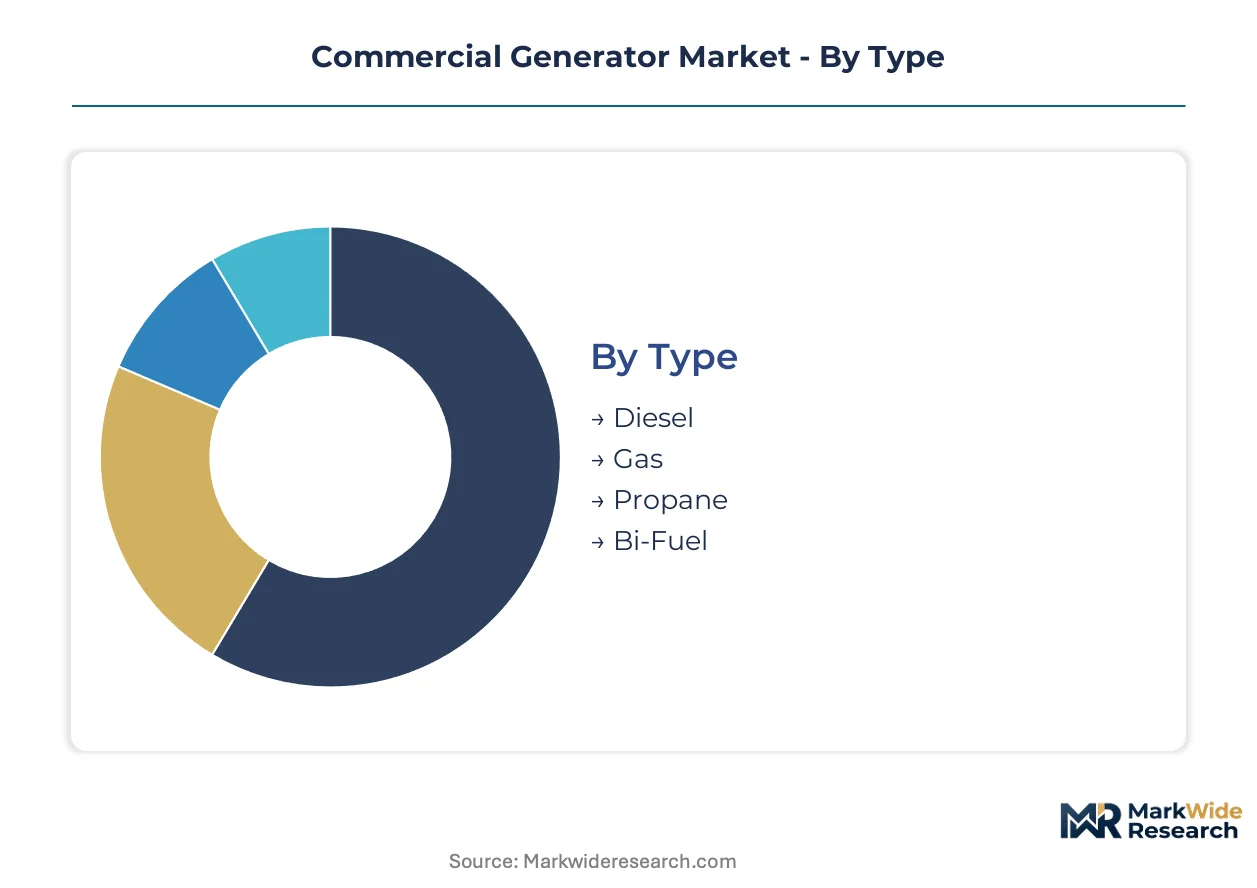
Commercial generator procurement patterns diverge sharply across fuel types, power classes, and deployment modes. Understanding these fault lines reveals where margin pools concentrate and which specifications command premium pricing.
Type:
Diesel, gas, propane, and bi-fuel configurations serve distinct use-case spectra spanning prime power, standby backup, and emissions-constrained environments.
- Diesel:Compression-ignition engines deliver maximum torque at low RPM and tolerate fuel quality variability across remote sites. Demand clusters in Indian manufacturing zones and African mining operations where grid instability demands prime-rated reliability and fuel logistics favor liquid storage.
- Gas:Spark-ignited natural gas units achieve lower NOx emissions without after-treatment complexity and pair efficiently with combined heat and power systems. Procurement is accelerating in Texas and Pennsylvania shale regions where pipeline access eliminates fuel logistics overhead.
- Propane:LPG configurations offer indefinite fuel stability and cleaner combustion than diesel, suiting healthcare facilities with limited maintenance windows.
- Bi-Fuel:Dual-fuel architectures blend diesel pilot injection with natural gas main combustion, cutting particulate emissions while preserving compression-ignition reliability during gas supply interruptions.
The dominant share belongs to diesel, while gas is closing the gap fastest.
Power Rating:
Cost tiers stratify sharply across these four bands, with engineering complexity and application criticality rising nonlinearly above 150 kW.
- 0-50 kW:Single-phase portable units serve small retail and residential backup with minimal installation overhead. Demand concentrates in storm-prone US Gulf Coast counties where residential contractors specify quick-deploy rental fleets.
- 51-150 kW:Three-phase industrial units bridge light commercial and small institutional loads. Procurement is expanding in Vietnamese manufacturing parks where foreign investors require guaranteed power for precision electronics assembly.
- 151-300 kW:Heavy-duty stationary platforms support mid-size healthcare and hospitality loads with NFPA 110 Type 10 compliance.
- Above 300 kW:High-voltage synchronous machines with paralleling capability serve hyperscale data centers and district heating plants.
Above 300 kW commands the steepest margin expansion trajectory, while 51-150 kW sees the densest competitive pressure.
Deployment:
Volume patterns track capital availability and mobility requirements across construction cycles and permanent infrastructure.
- Portable:Towable skid-mounted units with integrated fuel tanks deploy within hours for emergency response and temporary power. Demand concentrates in Australian mining fly-in-fly-out operations where camp electrification follows exploration drilling schedules.
- Stationary:Permanent installations with concrete pads, permanent fuel storage, and building-integrated exhaust systems serve critical facilities. Procurement dominates Northern Virginia data center clusters where lease agreements mandate 99.999% uptime guarantees.
- Mobile:Truck or trailer-mounted generators with rapid connection hardware serve utility grid support and disaster recovery.
- Containerized:ISO-standard enclosures with integrated switchgear and cooling enable modular scaling and intermodal transport.
Stationary deployments retain the dominant revenue share, though containerized formats are expanding most quickly in remote resource extraction.
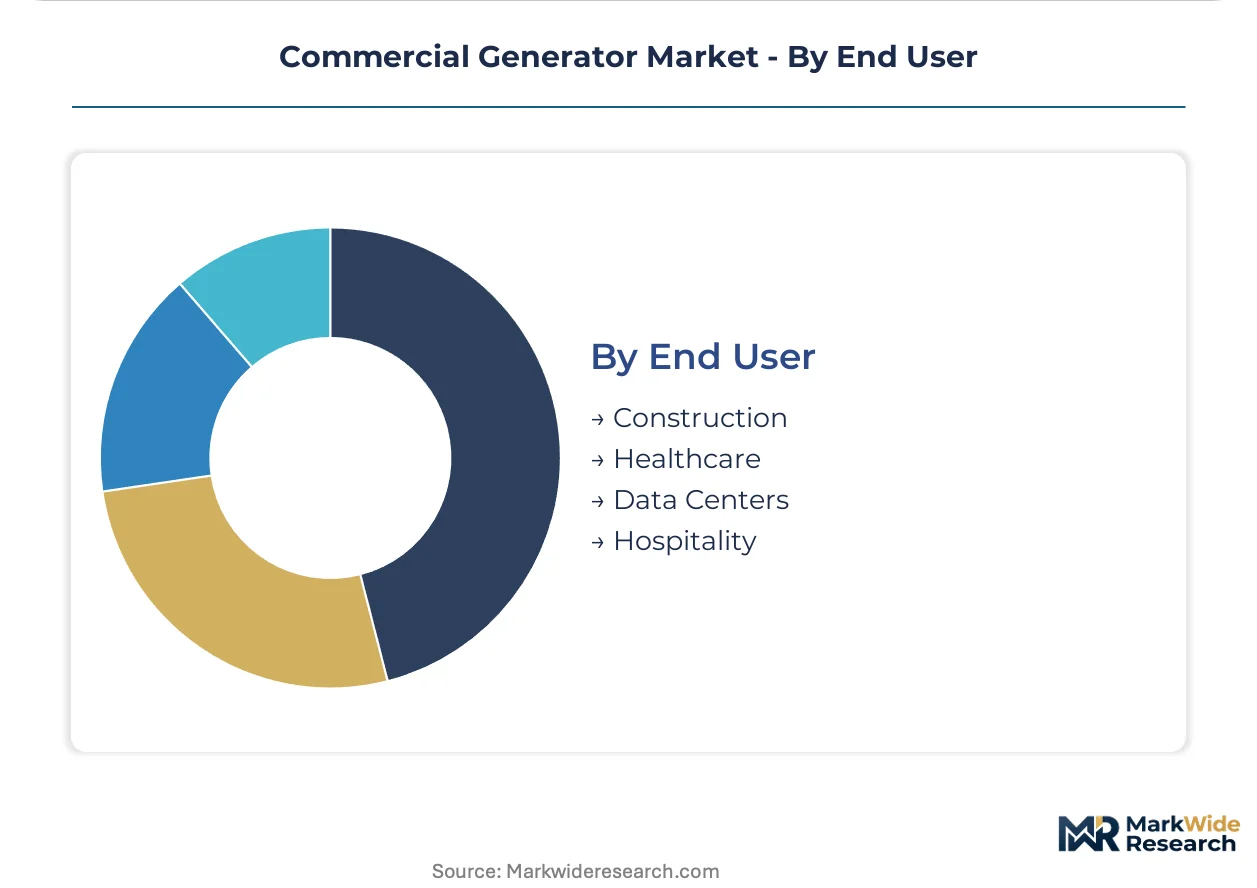
End User:
Customer maturity and compliance burden vary dramatically across these four verticals, shaping specification complexity and service contract structures.
- Construction:Rental-driven procurement favors durability and rapid deployment over efficiency, with units often operating in dusty, unimproved conditions. Demand clusters in Saudi giga-project sites where power requirements scale from megawatts to gigawatts across multi-year buildouts.
- Healthcare:Life safety applications demand NFPA 99 and NFPA 110 compliance with automatic transfer switching and 10-second startup guarantees. Procurement concentrates in US urban hospital systems where Joint Commission accreditation mandates documented testing protocols.
- Data Centers:Hyperscale operators specify N+1 redundancy with synchronized paralleling and sub-500ms transfer times.
- Hospitality:Hotels and resorts prioritize acoustic attenuation and aesthetic enclosure design over extreme reliability metrics.
Data centers capture the dominant share of above-300 kW procurement, while construction drives portable and containerized volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for heavy-duty engine blocks clusters in Shandong and Jiangsu provinces, creating single-source vulnerability for manufacturers serving export markets. Demand geography diverges between developed markets where emissions compliance drives replacement cycles and emerging economies where grid instability accelerates first-time procurement.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives 500 kW+ stationary unit procurement with NFPA 110 Type 10 mandates. EPA Tier 4 Final enforcement through 2024 model year deadlines forces after-treatment integration across diesel product lines. Caterpillar Inc. leverages captive component manufacturing to control lead times through Asian distribution channels.
China
Provincial emissions trading schemes under dual carbon goals accelerate bi-fuel retrofits in manufacturing zones with pipeline gas infrastructure. MIIT standards for non-road mobile machinery tighten particulate limits annually. Domestic foundry investments in alternator and engine block casting narrow the supply gap for locally assembled generator sets.
India
Industrial clusters in Gujarat and Maharashtra face 8-12 hour daily grid outages, creating parallel demand for prime-rated diesel and gas generator sets. CEA mandates for captive power plants above 10 MW require emission monitoring systems. Pune and Chennai manufacturing corridors concentrate procurement for automotive and precision electronics assembly facilities.
Germany
EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants forces closed-loop radiator redesigns for export-bound product lines. ECHA REACH compliance adds six to nine months to product development cycles for cooling circuit qualification. Frankfurt data center operators specify silicon carbide variable speed drives for floor space-constrained 500 kW+ installations.
Australia
Fly-in-fly-out mining operations in Western Australia drive containerized 1-2 MW skid-mounted rental fleet demand where capital avoidance shapes procurement. State-level clean backup mandates remain absent, preserving diesel competitiveness in remote extraction. Perth-based contractors specify rapid-deploy portable units for camp electrification following exploration drilling schedules.
Commercial Generator Market Vendor Landscape
Vertically integrated power systems specialists and component-focused fabricators split the market between lifecycle contract capture and equipment-only transactions. The vendor base concentrates around three strategic archetypes: captive foundry operators controlling casting and alternator supply, software-defined power management platforms monetizing predictive analytics, and rental fleet aggregators deploying modular containerized assets. Consolidation pressure intensifies through strategic partnerships for hydrogen-ready platform development and geographic licensing arrangements for EPA Tier 4 Final technology transfer.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries, Ltd. and GE Vernova Group exemplify scale-driven archetypes with cross-sector energy equipment portfolios. Within the specialized generator segment, Kohler Co. and Generac Power Systems, Inc. occupy positions emphasizing gaseous-fueled stationary architectures for emissions-constrained end uses. Rolls-Royce plc anchors the premium-tier vector through high-speed reciprocating engine technology serving marine and power generation applications. These representatives illustrate how competitive positioning diverges between upfront equipment pricing and extended availability guarantee models.
| Leading Market Players |
|---|
| Rolls-Royce plc |
| Kohler Co. |
| Caterpillar Inc. |
| Atlas Copco AB |
| Doosan Bobcat Inc. |
| Cummins Inc. |
| Mitsubishi Heavy Industries, Ltd. |
| GE Vernova Group |
| Generac Power Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
Shandong and Jiangsu foundry concentration for heavy-duty engine block casting funnels pricing power toward diesel OEMs with captive manufacturing, while Tier 4 after-treatment integration redistributes margin pools toward gas and bi-fuel architectures where emissions compliance costs compress less severely.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across diesel product lines, forcing three-tier pricing stratification across premium after-treatment-integrated units, standard compliant configurations, and economy pre-Tier 4 legacy inventory. Price differentiation hinges on certification grade for NFPA 110 Type 10 compliance and geographic delivery cost to remote mining sites. Pricing pressure intensifies in the 51-150 kW band where Chinese domestic assembly erodes incumbent premiums. Healthcare facilities demonstrate lowest price sensitivity due to Joint Commission accreditation mandates, while construction rental fleets maximize cost-per-kW optimization.
Supply Chain Analysis
Contract manufacturing capacity clusters at Cummins' captive power systems platform, Caterpillar's Asian component foundries, and Generac's gaseous-fuel specialized assembly lines. Geographic supply concentration centers on China for alternator and engine block casting, the United States for high-voltage synchronous machine winding, and India for prime-rated diesel generator assembly. Raw material dependencies rest on palladium and rhodium for diesel particulate filters, silicon carbide substrates for variable speed drives, and copper magnet wire for alternator windings. Single-source vulnerability in Shandong foundry capacity creates tariff exposure risk. Distribution runs through OEM-direct specification for data center projects and regional rental fleet aggregators for construction deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial generator market rewards regulatory entrenchment as a defensive moat, where EPA Tier 4 Final certification timelines and NFPA 110 commissioning protocols create switching costs that lock in incumbent relationships across multi-year service contracts.
For Market Incumbents: Insulate market position by deepening backward integration into alternator manufacturing and expanding hydrogen-ready platform R&D ahead of EU hydrogen backbone corridor maturation. Consolidate service technician training networks to address after-treatment diagnostic scarcity that extends repair timelines. Lock in data center operators through ten-year availability contracts that shift capital expenditure to operational budgets and bind performance to uptime metrics. For New Entrants and Emerging Players: Sub-Saharan African grid instability represents the most penetrable white-space opportunity, where pipeline gas infrastructure absence preserves diesel competitiveness and local assembly partnerships circumvent import logistics overhead. Target containerized rental fleet deployment in Australian fly-in-fly-out mining operations where capital avoidance drives procurement. Pursue joint venture licensing for EPA Tier 4 Final technology transfer to accelerate compliance without captive R&D investment. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined power management platforms monetizing predictive analytics and grid-interactive response capabilities. Long-term viability favors vendors capturing lifecycle value through outcome-based availability contracts rather than equipment-only transactions. Watch state-level clean backup mandate adoption as the inflection signal determining whether bi-fuel and hydrogen-ready platforms become standard specification or premium segmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Platform Development | 20% hydrogen blending capability captures first-mover advantage as EU hydrogen corridors mature. |
| Containerized Rental Fleet Expansion | Modular 1-2 MW skid-mounted units address capital avoidance in Australian and Chilean mining. |
| After-Treatment Service Network Buildout | Specialized diagnostic capabilities reduce repair timelines for EPA Tier 4 Final systems. |
| Lifecycle Availability Contract Conversion | Ten-year per-kWh pricing shifts data center procurement from capex to opex models. |
| Silicon Carbide Drive Integration | Compact variable speed electronics reduce footprint in Northern Virginia floor space-constrained installations. |
Methodological Framework
A standing panel of data center facilities managers, healthcare engineering directors, mining procurement leads, and OEM aftermarket service heads provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA Tier 4 Final enforcement documentation, EIA power reliability statistics, EU F-Gas Regulation phase-down schedules, and customs data on alternator and engine block trade flows. Bottom-up unit shipment estimates triangulated against top-down power generation capacity forecasts to anchor market sizing.
Scenario-bracketing around grid reliability disruption frequency, emissions regulation acceleration, and hydrogen infrastructure deployment pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include fuel type architecture, power rating tier, deployment mode mobility, and end-use vertical criticality. CAGRs derived from regression analysis against macroeconomic indicators and industry-specific inputs including data center construction permitting velocity and mining exploration drilling schedules.
Practitioners should monitor platinum group metal price volatility, state-level clean backup mandate legislative progression, and hydrogen blending infrastructure deployment for early signals of forecast revision. Quarterly review of EPA enforcement discretion, foundry capacity utilization in Shandong province, and hyperscale data center lease rate premiums is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South Africa Diesel Generator Market
Generators
Emergency Power Generators Sales Market
Generators
India Diesel Generator Market
Generators
Power Generator Rental Market
Generators
Generator Sales Market
Generators
Europe Generator Sets Market
Generators
Europe Portable Generator Market
Generators
Africa Diesel Generator Market
Generators
Construction Generator Sets Market
Generators
South America Gas Generator Market
Generators
China Diesel Generator Market
Generators
Construction Portable Generators Market
Generators
North America Gasoline Gensets Market
Generators
United States Portable Generator Market
Generators
Onboard Marine Gensets Market
Generators
Digital Inverter Generator Market