
 France Electric Vehicle Battery Electrolyte Market | 2026-2036
France Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Battery Electrolyte Market Insights
Solid-state electrolyte chemistry is reshaping how French battery suppliers configure their material roadmaps. Umicore SA anchors its position through integrated cathode-electrolyte research near Antwerp with supply lines into France. Arkema Global leverages its fluoropolymer expertise to specialize in high-purity lithium salts for next-generation cells. Solvay SA dominates specialty polymer formulations that bridge liquid and solid electrolyte performance gaps.
France electric vehicle battery electrolyte encompasses the ion-conducting medium—typically lithium hexafluorophosphate dissolved in carbonate solvents for liquid systems, or lithium-conducting ceramics and sulfide glasses for solid architectures—that enables lithium-ion transport between anode and cathode during charge and discharge cycles. Liquid electrolyte maintains cost leadership for near-term passenger vehicle deployments, though solid electrolyte is capturing R&D investment as energy density targets tighten. Sodium-ion technology is emerging as a structural hedge against lithium supply volatility, particularly for commercial vehicle and e-bike applications where energy density requirements moderate.
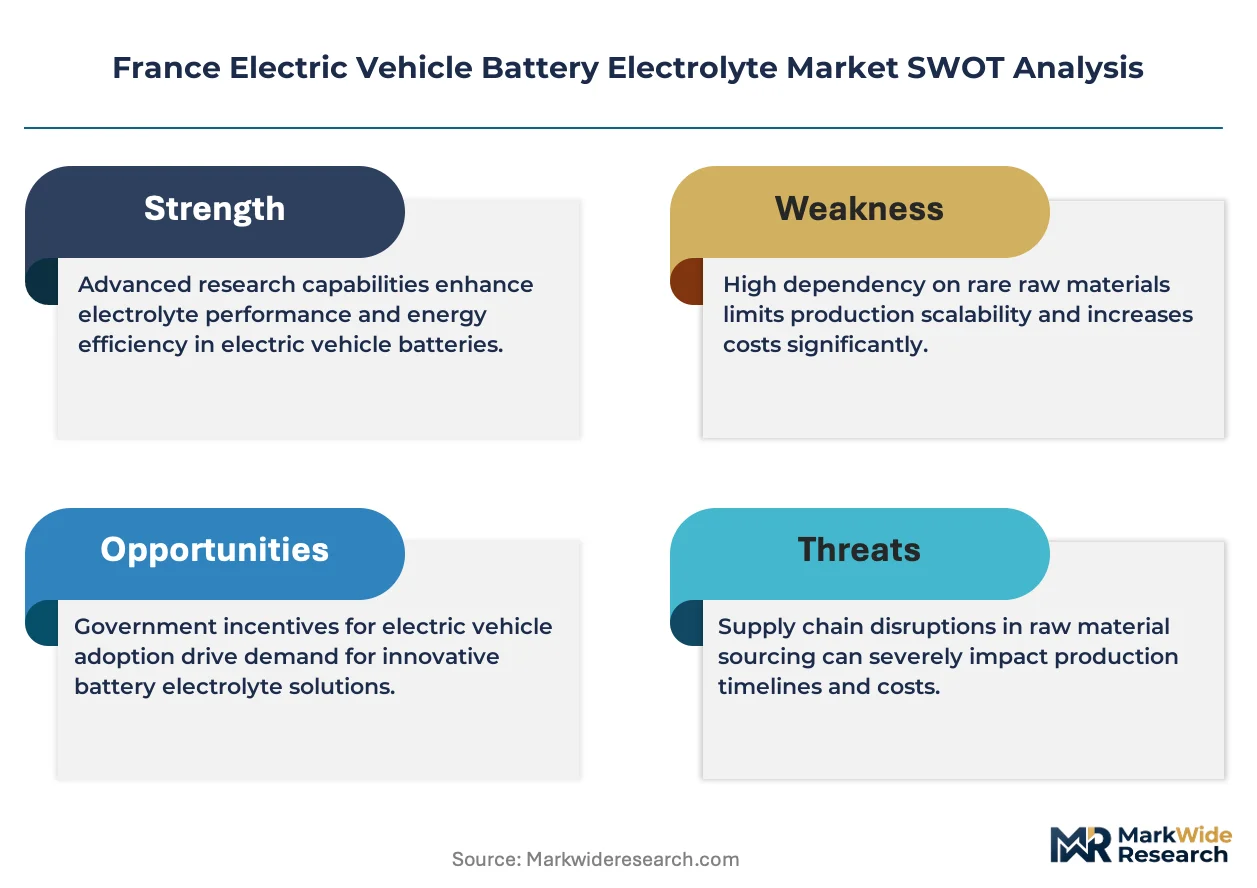
France's national energy regulator and the EU's REACH framework govern chemical substance registration and workplace exposure limits for electrolyte manufacturing facilities. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations that reshape how automotive manufacturers and battery manufacturers qualify their electrolyte suppliers. Stakeholders must monitor how France's implementation of the EU Critical Raw Materials Act alters domestic sourcing requirements for lithium salts and fluorinated compounds.
Market Dynamics
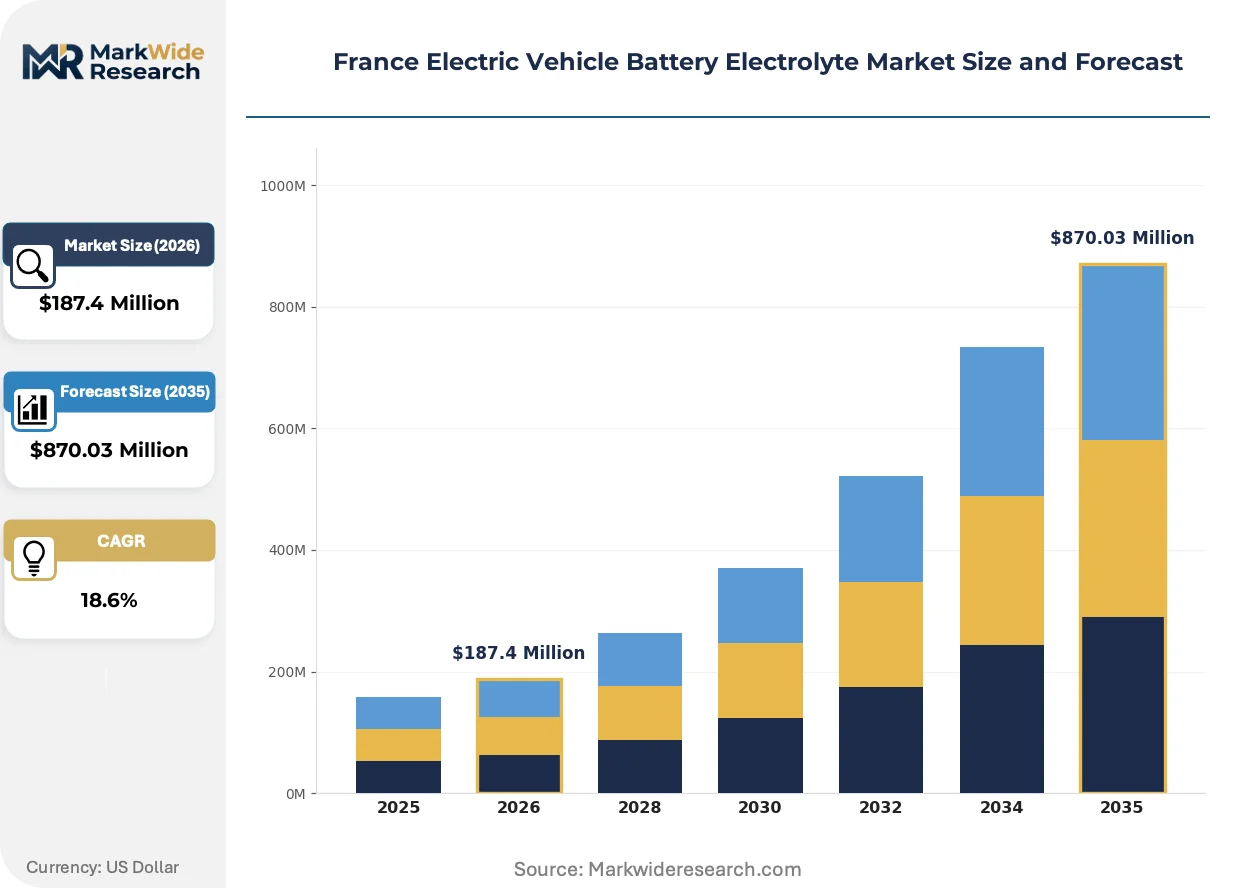
The France electric vehicle battery electrolyte market is being fundamentally restructured by the EU Battery Regulation's carbon footprint declaration requirements, which force automotive OEMs to requalify their entire supplier base against embodied emissions thresholds.
Growth Catalysts
- EU Green Deal implementation:France's national low-carbon vehicle incentives are accelerating chemistry transitions toward solid-state architectures. Domestic EV assembly expansion at Renault's ElectriCity hub drives electrolyte procurement scaling.
- Paris-Saclay battery cluster concentration:Research infrastructure density is pulling specialty chemical suppliers into co-location arrangements. Proximity to cathode material development accelerates integrated cell design cycles.
- REACH framework alignment:Chemical substance registration harmonization across EU member states reduces cross-border compliance friction for French electrolyte manufacturers. Shared workplace exposure standards lower facility certification costs.
Market Restraints
- Lithium salt supply concentration:Hexafluorophosphate precursor production clusters in Chinese industrial zones. French formulators face input cost volatility and geopolitical exposure.
- Fluorinated compound regulatory friction:The EU F-Gas Regulation tightens containment requirements for electrolyte manufacturing. Facility retrofit costs compress margin structures for mid-scale producers.
- Sodium-ion substitution threat:Commercial vehicle and e-bike segments are piloting sodium-ion cells for moderate energy density applications. Lithium-based electrolyte demand faces structural hedging.
Strategic Opportunities
- Recycled content mandates:The EU Battery Regulation's recycled lithium thresholds create first-mover advantage for French suppliers developing closed-loop salt recovery. Automotive OEMs will pay premium qualification slots for compliant sources.
- Solid-liquid hybrid architectures:Gel polymer electrolytes bridge performance gaps while manufacturing infrastructure transitions. Arkema's fluoropolymer expertise positions for intermediate chemistry capture.
- Northern France logistics corridor:Port of Dunkirk hydrogen infrastructure investments enable low-carbon solvent production. Electrolyte formulators can source carbonate solvents with reduced Scope 3 emissions.
Industry Challenges
- Electrochemist talent scarcity:Solid-state electrolyte R&D requires specialized ionic conductivity expertise. French technical universities face competition from German battery clusters for graduate recruitment.
- Dual certification timelines:Automotive OEMs demand simultaneous UN 38.3 transport certification and EU Battery Regulation carbon footprint validation. Testing queue congestion delays commercialization.
- Legacy liquid electrolyte asset stranding:Existing French formulating facilities face technical retrofit requirements for high-purity solid-state precursor handling. Capital allocation decisions compress under uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Battery Electrolyte Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolyte, Polymer Electrolyte, Solid Electrolyte, Gel Electrolyte Application: Passenger Vehicles, Commercial Vehicles, E-scooters, E-bikes Technology: Lithium-Ion, Sodium-Ion, Solid-State, Flow Battery End User: Automotive Manufacturers, Battery Manufacturers, Research Institutions, Aftermarket Providers |
| Companies Covered | Umicore SA, Targray Industries Inc., Arkema Global, Cabot Corporation, NEI Corporation, BASF SE, Mitsubishi Chemical Group, Samsung SDI, Solvay SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Battery Electrolyte Market Trends and Innovations
Solid-state electrolyte architectures are forcing French suppliers to reconfigure their material roadmaps around sulfide glass and oxide ceramic processing capabilities. Chemistry transitions are compressing traditional liquid electrolyte investment horizons.
Sulfide-based solid electrolytes are migrating from laboratory validation to pilot-scale cell assembly at French automotive research centers. These materials offer lithium-ion conductivity approaching liquid systems while enabling lithium metal anode compatibility. Renault's battery engineering teams are accelerating testing protocols as energy density targets tighten for next-generation passenger vehicle platforms.
The EU Critical Raw Materials Act is reshaping how French electrolyte manufacturers qualify their lithium salt supply chains. Domestic sourcing requirements for strategic raw materials are forcing formulators to audit and recontract with European-based precursor suppliers. Automotive OEMs in northern France are now requiring documented supply chain provenance as a condition of electrolyte procurement.
Automotive OEMs are consolidating their electrolyte supplier panels from multi-source arrangements toward single-source qualification for specific cell formats. Long-term offtake agreements with volume guarantees are displacing spot market purchasing. This concentration is most visible in the Paris-Saclay corridor, where battery cell startups are locking in dedicated electrolyte supply before facility commissioning.
France Electric Vehicle Battery Electrolyte Market Segmentation
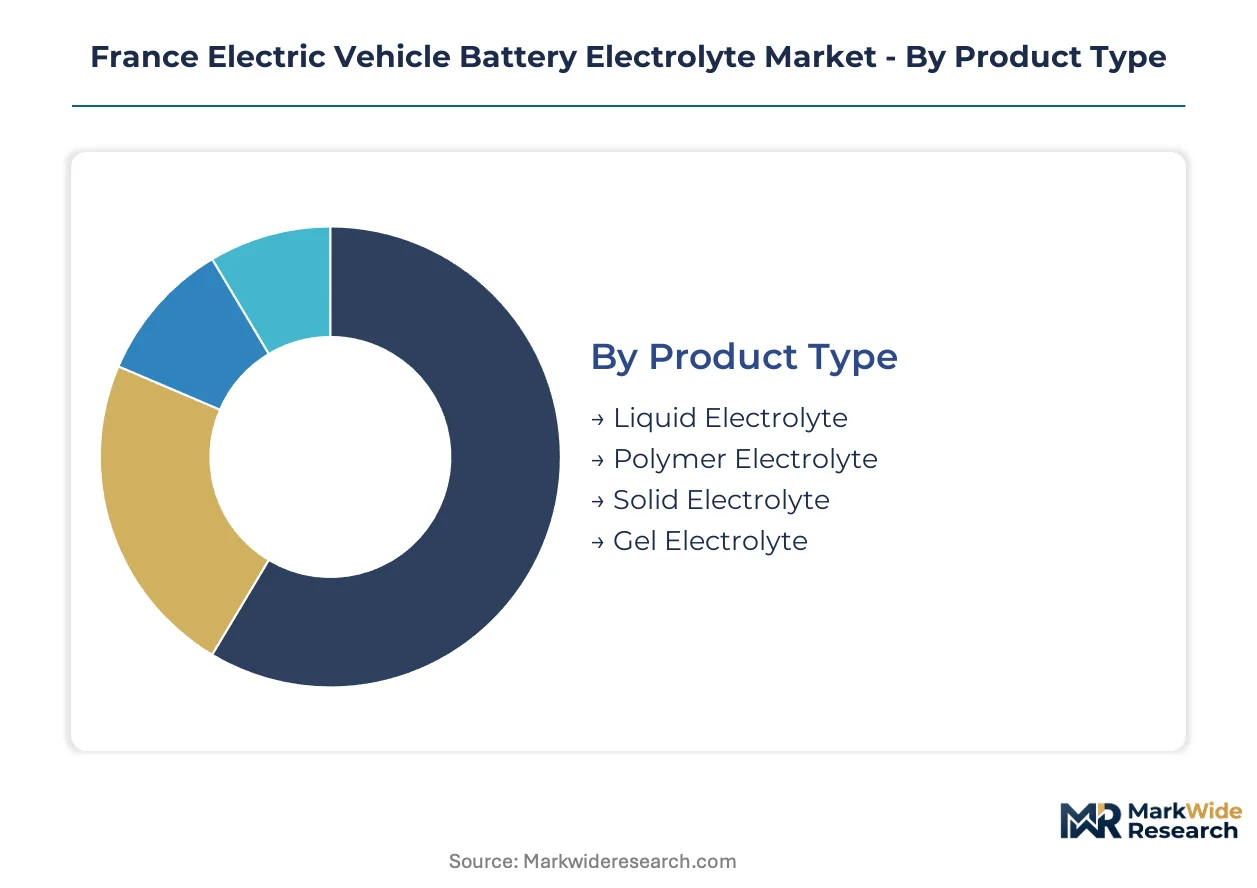
Electrolyte procurement patterns in France diverge sharply across vehicle platforms and cell chemistries. Understanding these segment boundaries clarifies where formulation complexity commands premium pricing versus where standardization dominates.
Product Type:
After-sales service intensity varies dramatically by electrolyte format, with solid-state architectures requiring specialized diagnostic equipment and polymer systems demanding precise humidity-controlled handling protocols.
- Liquid Electrolyte:Lithium hexafluorophosphate dissolved in carbonate solvents remains the dominant formulation for near-term passenger vehicle deployments. Procurement concentrates around Renault's ElectriCity manufacturing hub in northern France, where volume scale and established supply chains offset energy density limitations.
- Solid Electrolyte:Lithium-conducting ceramics and sulfide glasses enable lithium metal anode compatibility for next-generation platforms. R&D investment clusters at the Paris-Saclay battery cluster as energy density targets tighten, though manufacturing infrastructure remains under development.
- Polymer Electrolyte:Dry solid polymer matrices eliminate flammability risks in confined urban vehicle architectures.
- Gel Electrolyte:Hybrid architectures bridge liquid conductivity with solid-state safety profiles during industry transition phases.
Liquid electrolyte holds the largest share; momentum sits with solid electrolyte.
Application:
Cost tier differentiation separates premium passenger vehicle specifications from commercial vehicle tolerance for moderate energy density.
- Passenger Vehicles:OEMs at Renault's ElectriCity hub and Stellantis facilities demand high-purity formulations with stringent carbon footprint documentation under EU Battery Regulation mandates. Cell format standardization enables supplier consolidation.
- Commercial Vehicles:Sodium-ion pilot programs are gaining traction for urban delivery fleets where weight and range requirements moderate. Bus manufacturers in Lyon and Marseille test electrolyte formulations optimized for high-cycle-life duty profiles.
- E-scooters:Compact cell formats prioritize cost minimization over energy density optimization.
- E-bikes:Regional assemblers in the Alps and Loire Valley source standardized electrolyte volumes with minimal customization.
Passenger vehicles command the revenue concentration; commercial vehicles are expanding most quickly through electrification mandates.
Technology:
Customer type stratification separates automotive OEMs with dedicated R&D budgets from aftermarket providers focused on replacement compatibility.
- Lithium-Ion:Mature supply chains and established recycling infrastructure support current production scale. French formulators leverage REACH framework alignment to reduce cross-border compliance friction for carbonate solvent handling.
- Solid-State:Sulfide glass processing capabilities are migrating from laboratory validation to pilot-scale assembly. Renault's battery engineering teams accelerate testing protocols as cell designs integrate lithium metal anodes.
- Sodium-Ion:Structural hedge against lithium supply volatility attracts commercial vehicle and stationary storage applications.
- Flow Battery:Grid-scale storage applications remain peripheral to automotive electrolyte demand.
Lithium-ion retains volume dominance; solid-state chemistry gains share fastest through OEM R&D commitments.
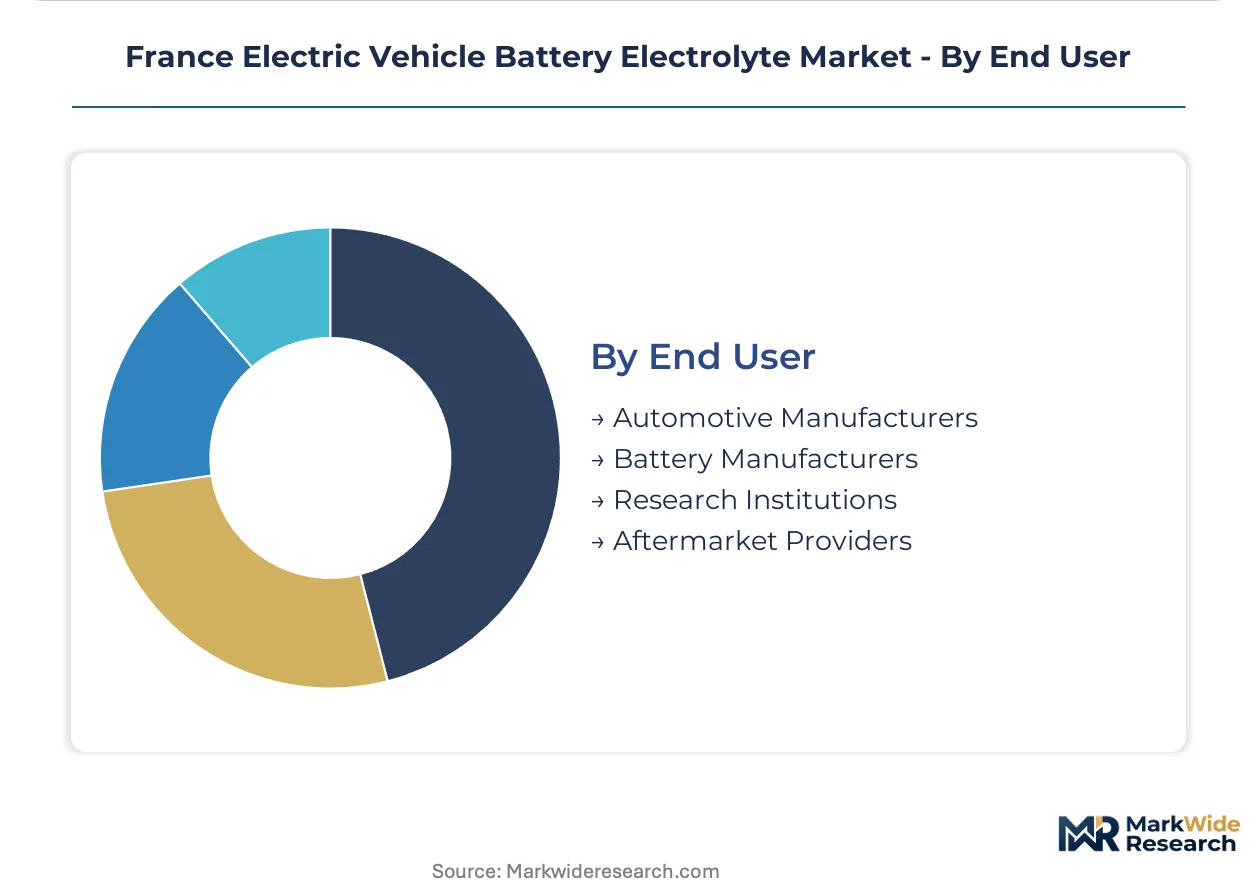
End User:
Supply concentration shapes procurement power, with automotive manufacturers consolidating supplier panels while research institutions fragment demand across experimental formulations.
- Automotive Manufacturers:Renault, Stellantis, and emerging French EV startups demand documented supply chain provenance under EU Critical Raw Materials Act implementation. Long-term offtake agreements displace spot purchasing.
- Battery Manufacturers:Cell producers in the Paris-Saclay corridor require electrolyte qualification before facility commissioning, creating first-mover advantage for compliant suppliers.
- Research Institutions:CEA and university laboratories pilot novel ionic conductivity formulations with limited commercial scale.
- Aftermarket Providers:Replacement cell refurbishment in Lyon and Toulouse generates residual demand for legacy liquid electrolyte formats.
Automotive manufacturers hold the largest share; momentum sits with battery manufacturers as domestic cell production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electrolyte formulators export carbonate solvent blends to French automotive OEMs through the Rhine-Ruhr logistics corridor. Belgian specialty chemical producers supply lithium salt precursors across the northern France manufacturing belt. Dutch port infrastructure enables low-carbon solvent imports for Paris-Saclay battery cluster operations.
Germany
BASF SE and specialty chemical producers in Ludwigshafen supply carbonate solvents and lithium hexafluorophosphate formulations to Renault's ElectriCity hub. The EU Battery Regulation's carbon footprint declarations force German exporters to document Scope 3 emissions for French automotive procurement teams. Research partnerships between Karlsruhe Institute of Technology and Paris-Saclay laboratories accelerate solid-state electrolyte co-development cycles.
Belgium
Umicore SA's integrated cathode-electrolyte research facility near Antwerp feeds directly into French battery cell prototyping. REACH framework alignment between Belgian and French regulators reduces cross-border chemical substance registration friction. The Port of Antwerp-Bruges handles lithium salt precursor shipments bound for northern France electrolyte formulating plants.
Netherlands
Dutch chemical traders distribute high-purity carbonate solvents through Rotterdam terminals to French formulators seeking low-carbon supply chain options. The EU F-Gas Regulation's containment requirements apply equally to Dutch exporters and French manufacturers. Eindhoven's materials science institutes collaborate with Grenoble research centers on polymer electrolyte architectures.
Spain
Spanish mining interests in Extremadura lithium deposits supply raw material feedstock for French electrolyte salt production under EU Critical Raw Materials Act sourcing rules. Iberian solar-powered chemical plants offer French buyers renewable-energy-attributed solvent volumes. Barcelona-based research institutions partner with Lyon engineering schools on sodium-ion electrolyte formulations for commercial vehicle applications.
Italy
Italian fluoropolymer specialists in Lombardy export specialty additives for high-voltage electrolyte formulations used in French premium passenger vehicles. ANSM chemical substance notifications align with French workplace exposure standards through mutual recognition agreements. Milan-Turin automotive supply chains feed components into Stellantis facilities that source electrolyte from northern France formulators.
France Electric Vehicle Battery Electrolyte Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated chemical conglomerates with cathode material portfolios leverage cross-selling leverage against dedicated electrolyte formulators. The market structure rewards backward integration into lithium salt precursors and forward integration into cell manufacturer qualification programs. Dominant competitive moves include long-term offtake agreements with volume guarantees and co-location investments near Paris-Saclay research infrastructure.
Among Belgian-integrated material suppliers, Umicore SA exemplifies the cathode-electrolyte convergence archetype. French specialty chemical producers Arkema Global and Solvay SA occupy positions bridging fluoropolymer expertise with battery-grade purity requirements. These three entities represent distinct strategic postures: integrated materials, polymer specialization, and specialty formulation leadership.
| Leading Market Players |
|---|
| Umicore SA |
| Targray Industries Inc. |
| Arkema Global |
| Cabot Corporation |
| NEI Corporation |
| BASF SE |
| Mitsubishi Chemical Group |
| Samsung SDI |
| Solvay SA |
| Others |
Pricing and Supply Chain Analysis
Chinese lithium hexafluorophosphate precursor production clusters concentrate upstream margin capture, forcing French formulators to absorb input cost volatility while automotive OEMs downstream extract carbon footprint compliance premiums. This structural asymmetry compresses mid-scale electrolyte producers between feedstock inflation and qualification-driven pricing discipline.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate long-term offtake agreements between French formulators and automotive OEMs. Price differentiation separates battery-grade purity tiers from technical-grade formulations, with REACH-compliant carbon footprint documentation commanding additional premiums. Cost compression in standard liquid electrolyte runs through sodium-ion substitution pilots in commercial vehicle segments. Aftermarket refurbishment providers in Lyon exhibit highest price sensitivity, while Paris-Saclay cell startups prioritize qualification speed over unit economics.
Supply Chain Analysis
Contract manufacturing capacity for solid-state electrolyte precursor handling concentrates with German chemical processors in Ludwigshafen and Belgian specialty producers near Antwerp. The French supply chain draws from Chinese lithium salt refineries, German carbonate solvent blenders, and Spanish Extremadura mining feedstock under EU Critical Raw Materials Act sourcing rules. Single-source vulnerability concentrates in hexafluorophosphate precursor streams. Distribution runs through Port of Dunkirk bulk terminals and Rhine-Rufer barge corridors to northern France manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating toward automotive OEMs and Paris-Saclay cell manufacturers, fragmenting electrolyte supplier negotiating leverage as long-term offtake agreements displace spot purchasing.
For Market Incumbents: Entrench qualification relationships with Renault and Stellantis through dedicated carbon footprint audit trails aligned with EU Battery Regulation thresholds. Prioritize backward integration into lithium salt recovery infrastructure to capture recycled content mandate premiums before competitor capacity scales. Sodium-ion pilot programs in commercial vehicle segments threaten lithium-based electrolyte volume assumptions. For New Entrants and Emerging Players: Build out solid-state precursor handling capabilities targeting Paris-Saclay battery cluster startups before incumbent retrofit investments mature. The gel polymer electrolyte segment offers most penetrable white space, bridging liquid conductivity with solid-state safety profiles during manufacturing infrastructure transitions. Co-location investments near CEA research facilities accelerate qualification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward fluoropolymer-specialist formulators with existing high-purity chemical handling infrastructure adaptable to sulfide glass processing. Long-term viability centers on suppliers capable of serving both liquid electrolyte replacement demand and solid-state chemistry transitions across the analysis window. Monitor sodium-ion commercial vehicle adoption rates as inflection indicator for lithium electrolyte demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Recovery | Positions French suppliers to meet EU Battery Regulation recycled content thresholds before competitor capacity. |
| Solid-State Precursor Handling Capacity Buildout | Captures Paris-Saclay cluster demand as Renault accelerates lithium metal anode cell testing protocols. |
| Co-location Investment Near Research Infrastructure | Compresses integrated cell design cycles with CEA laboratories and cathode material developers. |
| Long-term Carbon Footprint Documentation Investment | Secures automotive OEM qualification slots under EU Battery Regulation embodied emissions thresholds. |
| Gel Polymer Electrolyte Pilot Production | Bridges liquid and solid-state performance gaps during manufacturing infrastructure transition phases. |
Research Methodology
Initial hypotheses were tested against primary input from electrolyte formulating plant managers, automotive OEM procurement leads, battery cell R&D directors, and REACH compliance officers, then refined through secondary validation against ECHA substance registration databases, EU Battery Regulation implementation texts, French customs trade records, and SEC filings from listed chemical conglomerates. Bottom-up volume estimates from individual facility capacities were triangulated with top-down demand projections derived from EV production forecasts.
Demand-supply balance modeling across the projection horizon incorporated electrolyte chemistry transitions, carbon footprint compliance timelines, and sodium-ion substitution elasticity. Segmentation dimensions included product type, vehicle platform, cell technology, and end-user concentration. CAGRs were derived from S-curve adoption modeling of solid-state chemistry penetration and linear extrapolation of liquid electrolyte replacement cycles. Industry-specific inputs captured fluoropolymer supply constraints and F-Gas Regulation containment cost pass-through assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese lithium salt refiners or accelerated sodium-ion commercialization by European cell manufacturers would shift outcomes. Quarterly review of EU Battery Regulation delegated act publication timelines and Paris-Saclay facility commissioning announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market