
 Second-Life EV Battery Module Qualification Test Systems Market | 2026-2036
Second-Life EV Battery Module Qualification Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Second-Life EV Battery Module Qualification Test Systems Market Insights
Modular test platform bundling is consolidating buyer preference around integrated electrical safety, performance, and thermal validation suites rather than standalone instruments. DEKRA anchors European qualification workflows through its battery testing laboratories in Germany and the Netherlands. UL Solutions leverages its North American safety certification heritage to dominate grid-storage customer channels. Bureau Veritas competes by extending marine and industrial inspection expertise into stationary energy storage verification protocols.
Second-life EV battery module qualification test systems comprise instrumented platforms that verify state-of-health, remaining capacity, internal resistance, and thermal stability of decommissioned automotive battery modules prior to non-automotive redeployment. These systems execute charge-discharge cycling, insulation resistance measurement, and temperature mapping to certify modules for downstream stationary applications. Performance analyzers and cycle life testers capture the deepest margin pools as buyers prioritize accurate remaining useful life prediction over basic safety screening. Grid storage applications lead volume demand while renewable integration represents the fastest-expanding addressable segment for qualification service providers.
The EU Battery Regulation mandates chain-of-custody documentation and state-of-health disclosure, compelling test system vendors to embed traceability software directly into hardware platforms. China's SAMR enforces GB/T 34014 standards for retired power battery reuse, creating parallel compliance requirements for equipment sold into Asian markets. Stakeholders must monitor how divergent regional certification timelines reshape capital deployment priorities for test infrastructure.
Market Dynamics
Stationary grid storage operators now dominate test system procurement as decommissioned automotive battery packs cascade into second-life applications, creating a demand pull that outpaces original equipment manufacturer replacement cycles.
Growth Catalysts
- EU Battery Regulation:Chain-of-custody documentation and state-of-health disclosure mandates compel test system vendors to embed traceability software directly into hardware platforms, expanding equipment functionality requirements.
- China's GB/T 34014 standards:SAMR-enforced protocols for retired power battery reuse create parallel compliance requirements that equipment manufacturers must satisfy to access Asian markets.
- Grid storage deployment:Renewable integration projects in Germany and the Netherlands require TÜV-certified testing workflows, anchoring circular economy supply chains for repurposed lithium-ion modules.
Market Restraints
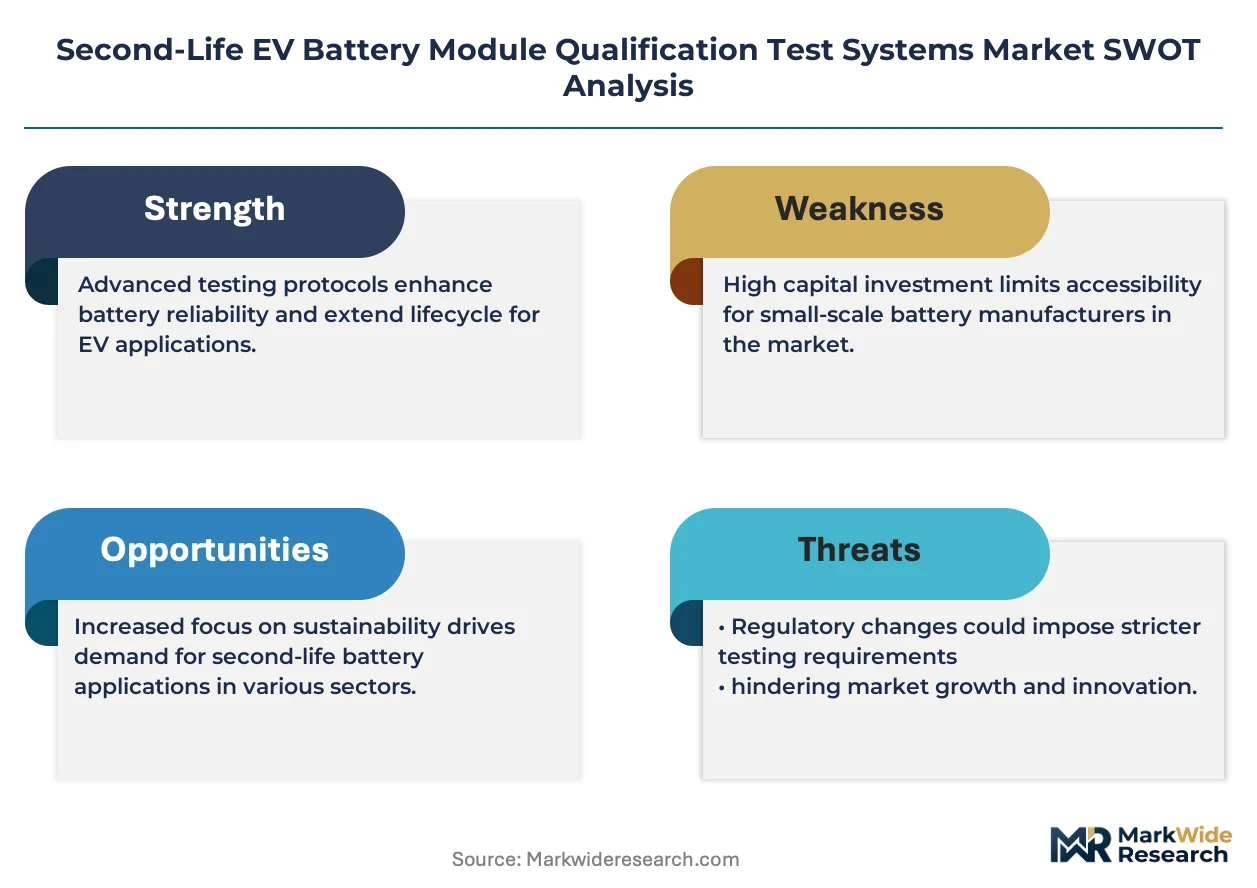
- Semiconductor component volatility:Test system manufacturers face input cost instability from specialized analog-to-digital converters and precision current sensors sourced from concentrated Asian foundry networks.
- Laboratory capacity concentration:DEKRA and Bureau Veritas testing facilities cluster in Germany and the Netherlands, creating geographic bottlenecks for qualification throughput during demand surges.
- Calibration equipment lead times:Metrology-grade reference sources for high-voltage insulation testing extend delivery schedules by 8-14 months, constraining test system production scaling.
Strategic Opportunities
- India's CEA storage mandates:Central Electricity Authority regulations requiring grid-scale battery deployment create an underpenetrated qualification services market as domestic second-life supply chains mature.
- Marine propulsion verification:Bureau Veritas extends marine classification expertise into stationary energy storage protocols, opening vessel-to-shore battery repurposing channels.
- Cloud-based test orchestration:Remote monitoring platforms enable distributed qualification workflows, allowing test service providers to aggregate capacity across multiple laboratory locations without physical consolidation.
Industry Challenges
- Electrochemical modeling expertise scarcity:Battery degradation algorithm development requires specialized knowledge spanning lithium-ion chemistry, thermal dynamics, and predictive analytics that crosses traditional engineering disciplinary boundaries.
- Multi-standard certification complexity:Equipment vendors must simultaneously satisfy UL Solutions safety protocols for North American grid storage customers, TÜV requirements for German circular economy chains, and GB/T compliance for Chinese reuse markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second-Life EV Battery Module Qualification Test Systems Market |
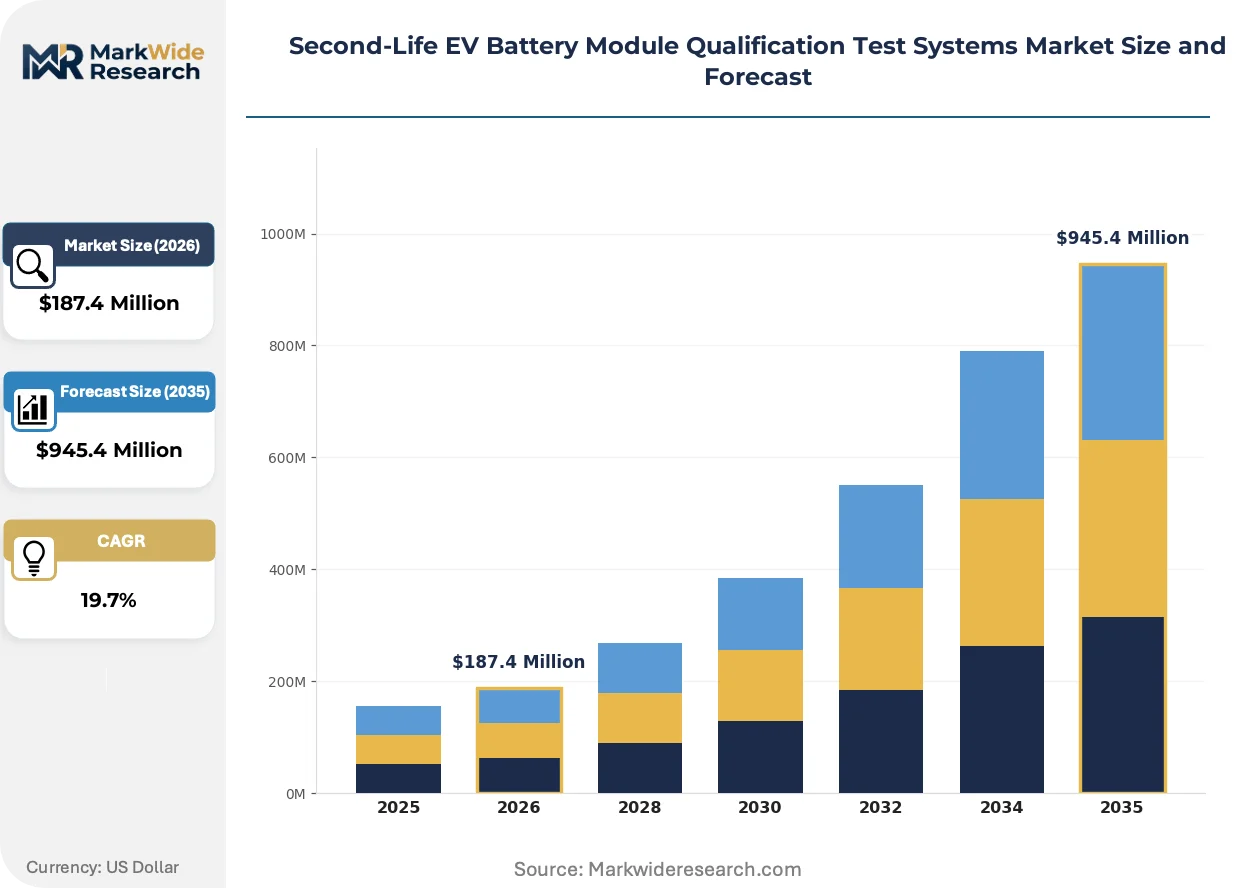
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test System Type: Electrical Safety Tester, Performance Analyzer, Thermal Management System, Cycle Life Tester, Voltage Measurement Unit Application: Grid Storage, Backup Power, Renewable Integration, Telecom Infrastructure, Data Center Energy Storage End User: Energy Storage Providers, Telecom Operators, Data Center Facilities, Industrial Equipment Manufacturers, Renewable Project Developers Deployment Method: Stationary Setup, Portable Systems, Automated Testing Lines, Manual Inspection Stations |
| Companies Covered | TÜV SÜD, TÜV Rheinland, DEKRA, UL Solutions, Intertek Group, SGS, Bureau Veritas, TÜV NORD GROUP, Applus+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second-Life EV Battery Module Qualification Test Systems Market Trends and Innovations
Test platform architecture is converging around integrated validation suites as buyers reject standalone instruments in favor of unified electrical safety, performance, and thermal verification systems.
Modular battery management system emulation hardware is decentralizing test floor configurations. Grid storage operators in Germany now deploy distributed cell-level monitoring arrays rather than centralized rack-based testers. This topology reduces qualification cycle times by enabling parallel state-of-health assessment across multiple decommissioned modules.
REACH substance restriction amendments are tightening hazardous material documentation requirements for battery recycling equipment. Test system manufacturers must now verify that thermal chambers and cycling fixtures contain no restricted phthalates or flame retardants. European qualification service providers are responding by demanding supplier material declarations before equipment procurement approval.
Buyers now unbundle after-sales calibration contracts from initial hardware purchases. Grid storage operators in the Netherlands negotiate separate service agreements with DEKRA-affiliated metrology providers rather than accepting bundled manufacturer maintenance. This shift compresses vendor service margins while expanding third-party qualification ecosystem participation.
Second-Life EV Battery Module Qualification Test Systems Market Segmentation
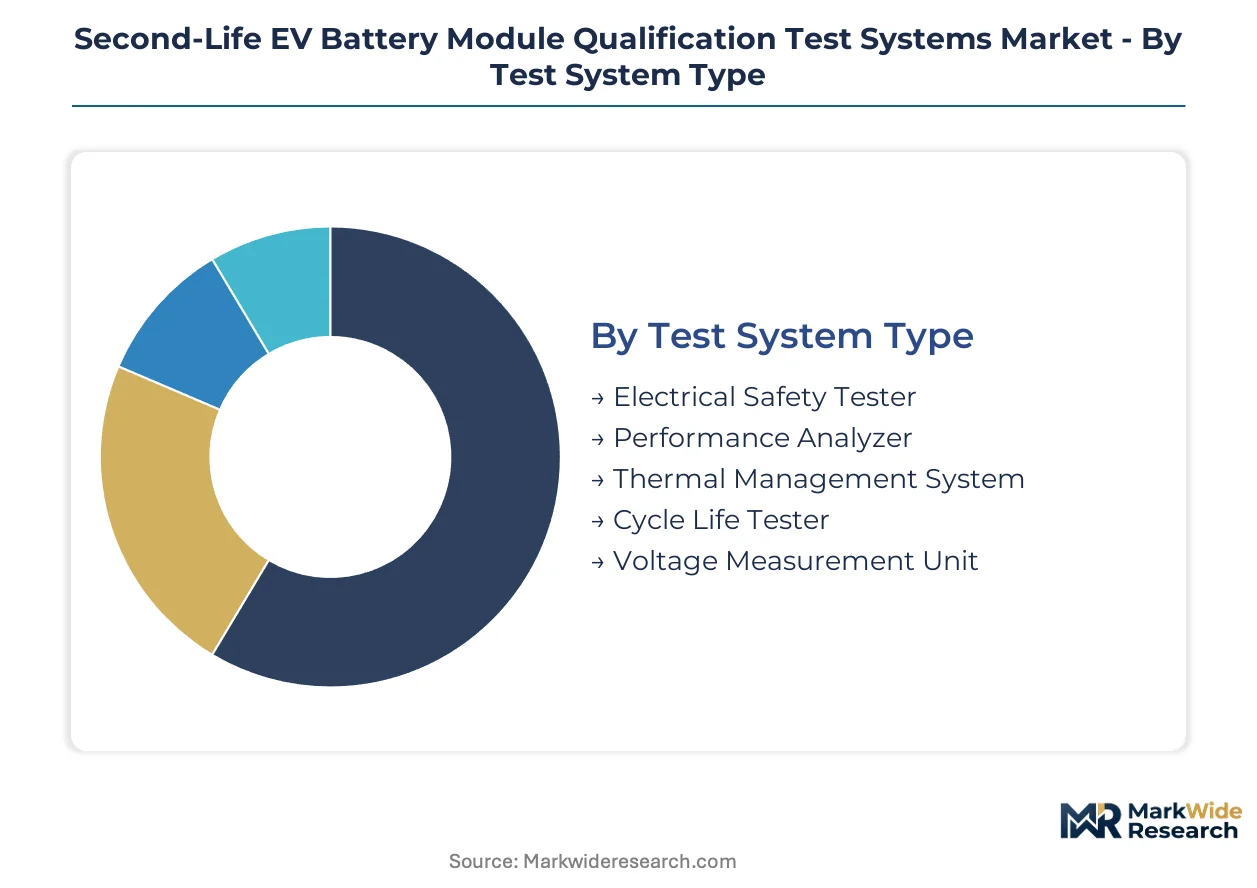
Test system procurement patterns diverge sharply across qualification workflows. Buyers prioritize integrated platforms for high-throughput grid storage operations while accepting modular instruments for distributed backup power verification. Segmentation reveals how capital allocation splits between centralized laboratory infrastructure and field-deployable testing assets.
Test System Type:
Supply concentration in precision current sensing and high-voltage insulation components favors integrated platform vendors with captive semiconductor sourcing.
- Performance Analyzer:These platforms execute state-of-health algorithms, remaining capacity estimation, and internal resistance profiling through electrochemical impedance spectroscopy. German grid storage operators specify TÜV-certified analyzers with embedded traceability software to satisfy EU Battery Regulation chain-of-custody mandates. Component lead times for metrology-grade reference sources extend 8-14 months, constraining production scaling for specialized units.
- Cycle Life Tester:Accelerated degradation protocols simulate multi-year calendar aging through controlled charge-discharge cycling at elevated temperatures. China's SAMR-enforced GB/T 34014 standards require documented cycle validation before retired automotive modules enter stationary reuse, driving procurement by Asian qualification service providers. Thermal chamber integration and precision current control differentiate premium configurations from basic cycling hardware.
- Electrical Safety Tester:Insulation resistance measurement and dielectric withstand verification platforms anchor preliminary qualification screening workflows.
- Thermal Management System:Temperature mapping arrays and active cooling validation suites verify thermal stability under load profiles mimicking target deployment conditions.
- Voltage Measurement Unit:Cell-level potential monitoring instruments support distributed BMS emulation architectures in modular test floor configurations.
Today's leader: Performance Analyzer. Tomorrow's challenger: Cycle Life Tester.
Application:
Cost tier stratification separates capital-intensive grid storage qualification from price-sensitive backup power verification workflows.
- Grid Storage:Utility-scale battery deployment in Germany and the Netherlands requires comprehensive electrical safety, performance, and thermal validation suites rather than standalone instruments. TÜV-certified testing anchors circular economy supply chains as decommissioned automotive packs cascade into second-life stationary applications. Procurement concentrates around integrated platforms with embedded traceability documentation.
- Renewable Integration:Solar-plus-storage and wind-coupled battery projects demand rapid qualification throughput to match project construction timelines. Cloud-based test orchestration platforms enable distributed workflows across multiple laboratory locations, reducing bottlenecks from geographically concentrated DEKRA and Bureau Veritas facilities.
- Backup Power:Commercial and industrial uninterruptible power supply applications accept simplified state-of-health screening without full cycle life characterization.
- Telecom Infrastructure:Remote cell tower battery replacement programs prioritize portable test systems for field-deployed qualification.
- Data Center Energy Storage:Hyperscale facility operators specify automated testing lines to match high-volume module processing requirements.
Grid Storage commands current procurement volumes. Renewable Integration is climbing the fastest as solar-wind hybrid projects multiply.
End User:
Customer type fragmentation splits between asset-owning operators seeking in-house qualification capability and outsourced testing service clients.
- Energy Storage Providers:Stationary battery system integrators and independent power producers build captive testing infrastructure to control qualification timelines and protect proprietary degradation algorithms.
- Data Center Facilities:Hyperscale cloud operators negotiate unbundled after-sales calibration contracts with third-party metrology providers rather than accepting bundled manufacturer maintenance.
- Renewable Project Developers:Solar and wind farm operators with co-located storage procure qualification services to satisfy offtake agreement performance guarantees.
- Telecom Operators:Mobile network infrastructure managers specify portable systems for distributed tower battery replacement programs.
- Industrial Equipment Manufacturers:Forklift, mining vehicle, and marine propulsion OEMs extend battery reuse programs into stationary applications.
Energy Storage Providers dominate capital deployment. Data Center Facilities are gaining share fastest through hyperscale captive infrastructure investment.
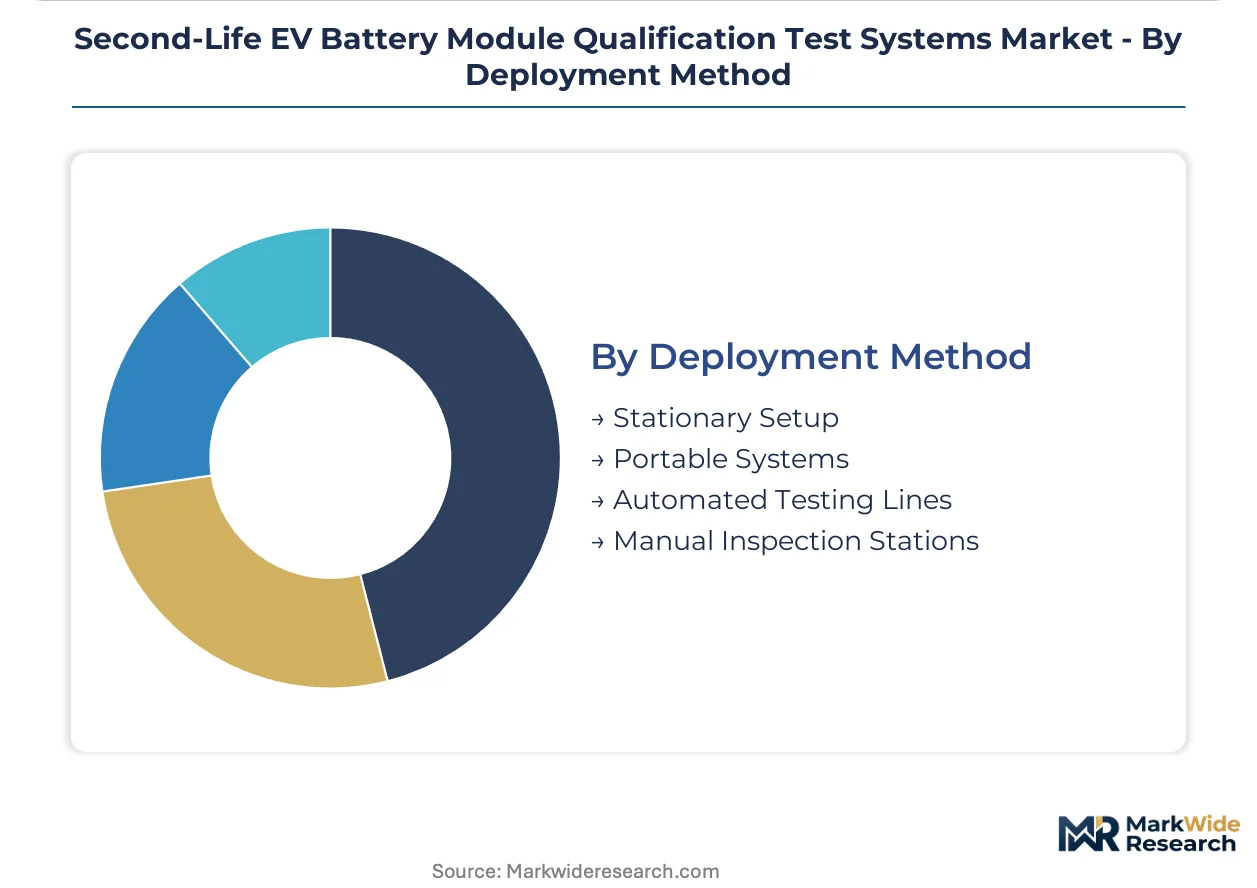
Deployment Method:
Volume concentration favors automated testing lines for grid-scale qualification while manual stations persist in low-throughput backup power applications.
- Automated Testing Lines:Conveyor-integrated platforms with robotic module handling process hundreds of decommissioned packs daily for German circular economy supply chains. REACH substance restriction amendments now mandate hazardous material documentation for thermal chambers and cycling fixtures, extending procurement approval timelines. Cloud-based orchestration layers enable remote monitoring across distributed laboratory networks.
- Stationary Setup:Fixed laboratory installations with centralized rack-based testers remain standard for TÜV-certified workflows in the Netherlands and Germany.
- Portable Systems:Field-deployable instruments support telecom tower and remote renewable site qualification where laboratory access is impractical.
- Manual Inspection Stations:Operator-directed testing persists in small-scale backup power and industrial equipment repurposing workflows with low module throughput requirements.
Automated Testing Lines anchor current infrastructure investment. Portable Systems represent the steepest expansion trajectory as distributed renewable and telecom applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive battery testing infrastructure during the early electric vehicle commercialization wave of the 2010s, establishing the regulatory and technical foundations that now govern second-life qualification protocols worldwide.
Germany
Stationary grid storage operators in North Rhine-Westphalia and Bavaria drive procurement volumes as decommissioned automotive packs cascade into circular economy supply chains. TÜV-certified testing workflows satisfy EU Battery Regulation chain-of-custody mandates, compelling equipment vendors to embed traceability software directly into hardware platforms. Stuttgart and Munich anchor qualification laboratory clusters where DEKRA and Bureau Veritas process high-throughput module verification for utility-scale battery deployment.
China
Retired power battery reuse from Ningde and Shenzhen manufacturing bases creates massive qualification demand as SAMR enforces GB/T 34014 standards. The Yangtze River Delta concentration of battery production generates parallel compliance requirements for test system manufacturers accessing Asian markets. Shanghai and Suzhou host the dominant share of domestic qualification service providers building captive testing infrastructure for state-owned grid storage operators.
United States
Independent power producers in California and Texas procure integrated validation suites for solar-plus-storage projects requiring rapid qualification throughput. FERC interconnection standards and state-level energy storage mandates create fragmented but substantial equipment demand across deregulated electricity markets. The Pacific Northwest and Southwest regions concentrate early second-life deployment pilots as utility procurement programs mature.
Netherlands
Renewable integration projects in the Randstad region require TÜV-certified testing workflows that anchor European circular economy supply chains for repurposed lithium-ion modules. Dutch grid storage operators negotiate unbundled after-sales calibration contracts with third-party metrology providers rather than accepting bundled manufacturer maintenance. Eindhoven's battery technology cluster supports distributed qualification workflows through cloud-based test orchestration platforms.
India
Central Electricity Authority regulations requiring grid-scale battery deployment create an underpenetrated qualification services market as domestic second-life supply chains mature. Maharashtra and Gujarat industrial corridors concentrate early equipment procurement by renewable project developers seeking to satisfy offtake agreement performance guarantees. The national regulator's storage mandates are pulling test system vendors into partnership discussions with domestic battery assemblers.
Second-Life EV Battery Module Qualification Test Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification heritage and integrated platform capabilities. The vendor base clusters around testing service providers with captive laboratory networks and equipment manufacturers supplying instrumented validation platforms. Three archetypes dominate: heritage certification bodies with automotive safety expertise, industrial inspection specialists extending into energy storage protocols, and pure-play test equipment manufacturers with semiconductor sourcing advantages. Competitive positioning hardens through strategic partnerships between certification bodies and grid storage operators, plus geographic expansion of laboratory capacity to reduce qualification bottlenecks.
Among heritage European certification specialists, TÜV SÜD, DEKRA, and Bureau Veritas occupy positions that exemplify the integrated service-provider archetype. TÜV SÜD represents the German automotive safety certification lineage now applied to stationary energy storage verification. DEKRA anchors battery testing laboratory networks across Germany and the Netherlands. Bureau Veritas extends marine and industrial inspection expertise into stationary energy storage protocols, opening vessel-to-shore battery repurposing channels.
| Leading Market Players |
|---|
| TÜV SÜD |
| TÜV Rheinland |
| DEKRA |
| UL Solutions |
| Intertek Group |
| SGS |
| Bureau Veritas |
| TÜV NORD GROUP |
| Applus+ |
| Others |
Pricing and Supply Chain Analysis
Integrated platform bundling is compressing margins for standalone instrument vendors while amplifying pricing power for semiconductor-captive manufacturers. Test system cost economics now hinge on captive sourcing of precision analog-to-digital converters and metrology-grade reference sources rather than assembly labor or software development.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates TÜV-certified integrated platforms from basic cycling hardware and unbundled component sales. Price differentiation centers on certification tier and after-sales service bundling, with Dutch grid storage operators driving unbundled calibration contract negotiation. Cost compression in economy tiers is intensifying because semiconductor input volatility forces margin sacrifice to maintain volume. Telecom operators exhibit highest price sensitivity, while German utility-scale battery deployers absorb premium pricing for embedded traceability documentation.
Supply Chain Analysis
Precision current sensing components rest on concentrated Asian foundry networks in Taiwan, South Korea, and Japan. Test system manufacturers draw from specialized suppliers of high-voltage insulation testers, thermal chamber assemblies, and electrochemical impedance spectroscopy modules. Single-source vulnerability in metrology-grade reference sources constrains production scaling during demand surges. Distribution runs through DEKRA and Bureau Veritas laboratory networks rather than direct OEM channels, creating service-provider gatekeeper dynamics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-embedded hardware platforms as traceability documentation requirements from the EU Battery Regulation create premium-tier pull. Semiconductor-captive sourcing and cloud-based test orchestration capabilities represent the primary cost-down and value-up levers.
For Market Incumbents: Cement laboratory network density in Germany and the Netherlands to lock in TÜV-certified workflow dominance against emerging cloud-based distributed qualification platforms. Expand captive semiconductor sourcing partnerships to neutralize analog-to-digital converter price volatility. Prioritize backward integration into precision current sensor manufacturing to defend margin position against Asian component suppliers. For New Entrants and Emerging Players: Certification body partnerships offer the fastest path to revenue as DEKRA and Bureau Veritas seek capacity expansion without capital deployment. India's CEA storage mandates present the most penetrable geography given underdeveloped domestic qualification infrastructure and accelerating grid-scale battery procurement. Position around portable system architectures for telecom and distributed renewable applications where laboratory concentration creates service gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play test equipment manufacturers lacking certification heritage but possessing semiconductor sourcing advantages. The five-to-ten year viability window favors vendors with embedded software capabilities that satisfy evolving chain-of-custody mandates. Acquisition targets should demonstrate cloud-based orchestration development or Indian market entry partnerships. Watch GB/T 34014 enforcement intensity in China as the signal for Asian qualification infrastructure investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Test Orchestration Platform | Enables DEKRA and Bureau Veritas to aggregate distributed laboratory capacity without physical consolidation. |
| Semiconductor Sourcing Partnership | Secures captive supply of precision analog-to-digital converters from Taiwanese foundry networks. |
| Indian Market Entry Partnership | Positions vendors to capture CEA-mandated grid storage qualification demand as domestic supply chains mature. |
| TÜV Certification Workflow Integration | Embeds traceability software directly into hardware platforms to satisfy EU Battery Regulation mandates. |
| Portable System Architecture Development | Targets telecom tower and remote renewable site qualification where laboratory access remains impractical. |
Research Methodology
Multiple input streams — qualification laboratory directors, grid storage procurement officers, test equipment R&D heads, semiconductor component suppliers — were reconciled through structured primary interviews and secondary validation. Regulatory filings from SAMR and EU Battery Regulation implementation guidance provided compliance framework boundaries. Trade data on precision current sensor imports, SEC disclosures from listed testing service providers, and project development databases for grid-scale battery deployment supplied quantitative anchors. Bottom-up equipment procurement estimates and top-down market sizing were cross-referenced for convergence.
Data-stream reconciliation across the modeling period applied segmentation dimensions spanning test system type, application workflow, end-user archetype, and deployment method. CAGRs were derived from equipment procurement run-rates and qualification capacity expansion plans. Electrochemical modeling expertise scarcity and multi-standard certification complexity were incorporated as supply-side constraints. Renewable integration project timelines and automotive battery retirement curves fed demand-side projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GB/T 34014 enforcement timelines, REACH substance restriction amendments, and semiconductor foundry capacity allocation shifts. Forecasts reflect documented assumptions about regulatory implementation pacing and battery retirement volume trajectories. A small set of named triggers — India's CEA mandate acceleration, marine propulsion verification protocol adoption, cloud orchestration platform commercialization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
India Battery Market
Batteries
Molten Salt Battery Market
Batteries
Smart Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
FORTELION Battery Module Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
South America Battery Cell Market
Batteries
Silicon Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Non-Rechargeable Battery Market
Batteries
Netherlands Rechargeable Battery Market
Batteries
Battery Swapping Market
Batteries
North America Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
Vietnam Battery Market