
 Global Pharmaceutical Cartridges Market | 2026-2036
Global Pharmaceutical Cartridges Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Cartridges Market Intelligence
Integrated drug-device combination product development services are repositioning the value of cartridges from a simple container to a critical system component. Gerresheimer AG leverages its extensive glass and plastic manufacturing scale to serve high-volume markets. West Pharmaceutical Services differentiates through its focus on integrated containment and delivery systems, including elastomers and seals. Schott AG specializes in high-purity borosilicate glass for sensitive biologic drugs, anchoring its position in the premium segment.
A pharmaceutical cartridge is a cylindrical primary drug container, typically made of Type I borosilicate glass or a high-performance polymer. These components are manufactured to extremely tight dimensional tolerances to ensure compatibility with auto-injectors and pen devices. Their primary purpose is to hold a drug formulation securely while enabling precise, repeatable dosing. While glass remains the dominant product type, plastic cartridges are seeing accelerated use in the injectable drugs application for their break resistance and compatibility with sensitive biologics.
Market access is shaped by stringent regulatory oversight from bodies like the US FDA and the European Medicines Agency. These authorities enforce strict guidelines on container closure integrity and extractables and leachables under frameworks like the EU's Medical Device Regulation (MDR) and US combination product rules. Navigating these complex requirements is a prerequisite for market entry. The central challenge for manufacturers is selecting materials that meet both regulatory demands and the specific stability needs of novel therapeutic proteins.
Market Dynamics
The central force shaping the market is the increasing integration of cartridges as critical components within drug-device combination products. This shift is driven by the rise of self-administered biologics, which elevates the cartridge from a simple container to an engineered system component essential for drug stability and device functionality.
Growth Catalysts
- Chronic Disease Therapies:The expanding pipeline of injectable treatments for chronic conditions like diabetes and autoimmune diseases fuels demand for user-friendly pen and auto-injector devices, which rely on cartridges for multi-dose delivery.
- Advanced Polymer Materials:The adoption of Cyclic Olefin Polymers (COP) provides a break-resistant alternative to glass with low extractables and leachables, making them ideal for sensitive biologic drug formulations.
- Regulatory Harmonization:Efforts by bodies like the International Council for Harmonisation (ICH) to align standards for container closure systems encourage investment in high-quality cartridges that meet global requirements.
Market Restraints
- Material Cost Volatility:The high and fluctuating cost of pharmaceutical-grade borosilicate glass tubing and specialty polymers creates pricing pressure and margin challenges for cartridge manufacturers.
- Technical Failure Risks:Glass cartridges remain susceptible to delamination and breakage, while polymer cartridges can face challenges with gas permeability, posing risks to drug integrity and shelf life.
- Stringent Validation Processes:New cartridge materials or designs require extensive and costly extractables and leachables studies and stability testing to gain approval from regulators like the EMA and US FDA.
Strategic Opportunities
- Lyophilized Drug Formulations:Developing dual-chamber cartridges that enable the reconstitution of lyophilized drugs at the point of administration opens new applications for complex, unstable biologic therapies.
- Emerging Market Manufacturing:Establishing production capabilities in pharmaceutical manufacturing centers in India and Brazil can capture demand from local and regional drug developers seeking to shorten supply chains.
- Smart Packaging Integration:Incorporating features like near-field communication (NFC) tags onto cartridges can enhance supply chain traceability and enable connected health solutions for monitoring patient adherence.
Industry Challenges
- Dimensional Tolerance Control:Maintaining sub-millimeter precision across millions of units is a significant manufacturing challenge, as slight deviations can cause device malfunction in auto-injectors.
- Specialized Raw Material Supply:The supply of high-purity borosilicate glass tubing is concentrated among a few global suppliers, creating potential bottlenecks and supply chain vulnerabilities for cartridge converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Cartridges Market |
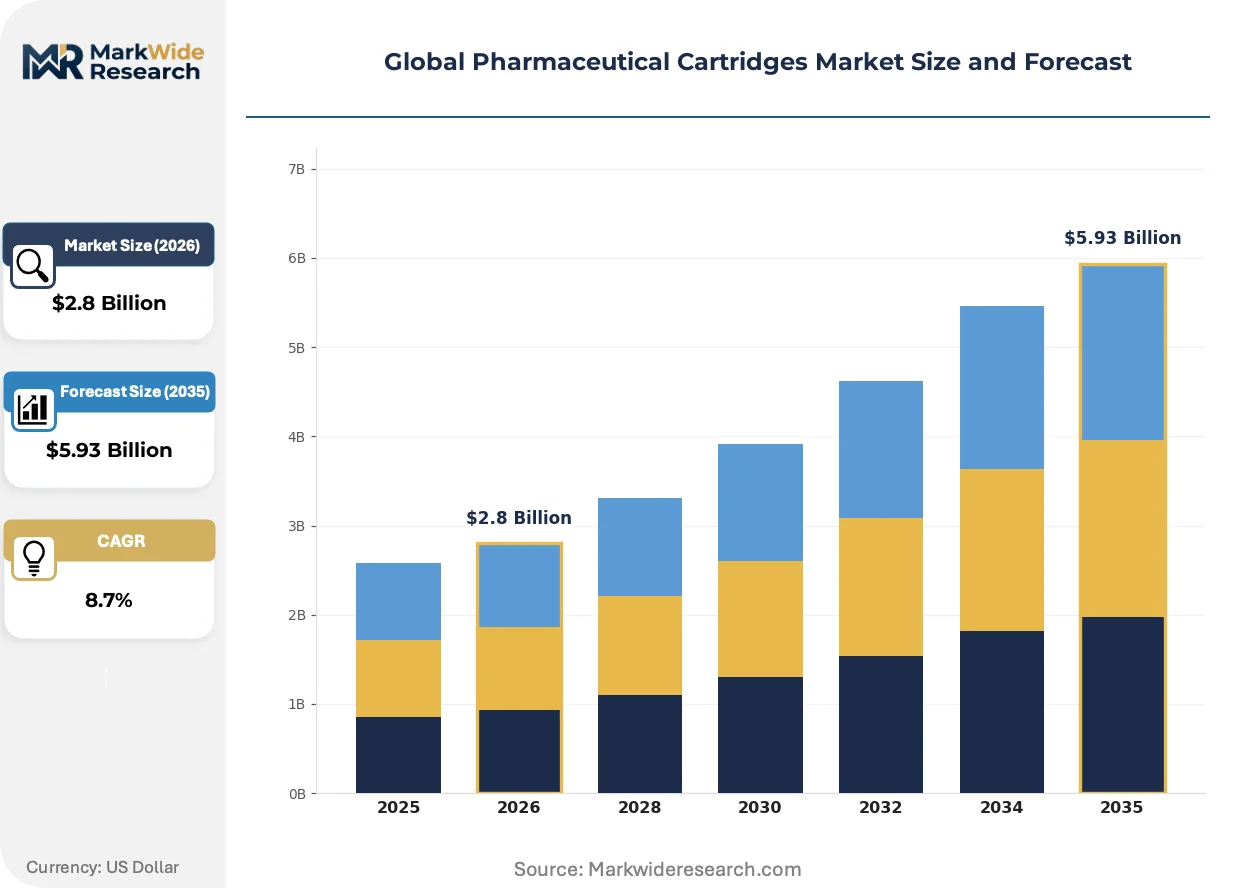
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Hybrid, Stainless Steel, Polycarbonate Application: Injectable Drugs, Insulin Delivery, Vaccines, Hormone Therapy, Anesthetic Delivery End User: Pharmacies, Biotechnology Firms, Research Laboratories, Contract Manufacturing Organizations, Diagnostic Centers Packaging Type: Single-Dose, Multi-Dose, Pre-Filled, Sterile, Tamper-Evident |
| Companies Covered | Gerresheimer AG, Schott AG, West Pharmaceutical Services, Stevanato Group, Nipro Corporation, Datwyler Holding, Becton, Dickinson and Company, Merck KGaA, Transcoject GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Cartridges Market Strategic Shifts & Innovations
The convergence of material science and precision engineering defines the market's trajectory. Cartridges are evolving from passive containers into active, enabling components of integrated drug delivery systems, a change necessitated by the stringent requirements of biologic drugs and patient-centric device design.
Advanced polymer cartridges, particularly those made from Cyclic Olefin Polymer (COP) and sometimes featuring specialized internal coatings, are engineered to minimize protein adsorption and eliminate the risk of glass delamination. Developers of sensitive biologics, including monoclonal antibodies and cell therapies, are increasingly specifying these materials to ensure drug stability. This material evolution is absorbing the chemical and physical interaction risks traditionally associated with glass containers.
Regulatory frameworks, such as the European Union's Medical Device Regulation (MDR), are placing greater emphasis on the entire combination product as a single integrated system. This forces drug developers to consider the cartridge's interaction with the device and drug formulation from the earliest stages of development. The biologic drug segment is most affected, responding by forming closer partnerships with cartridge and device manufacturers to generate comprehensive performance data for submissions.
A shift toward platform-based device strategies is altering procurement patterns for cartridges. Pharmaceutical companies are increasingly standardizing on a single auto-injector or pen platform to be used across multiple drugs in their portfolio. This streamlines development and simplifies the supply chain by creating demand for a single, well-characterized cartridge specification. This trend is highly visible in the diabetes and obesity therapeutic areas in the United States and Germany.
Global Pharmaceutical Cartridges Market Segmentation
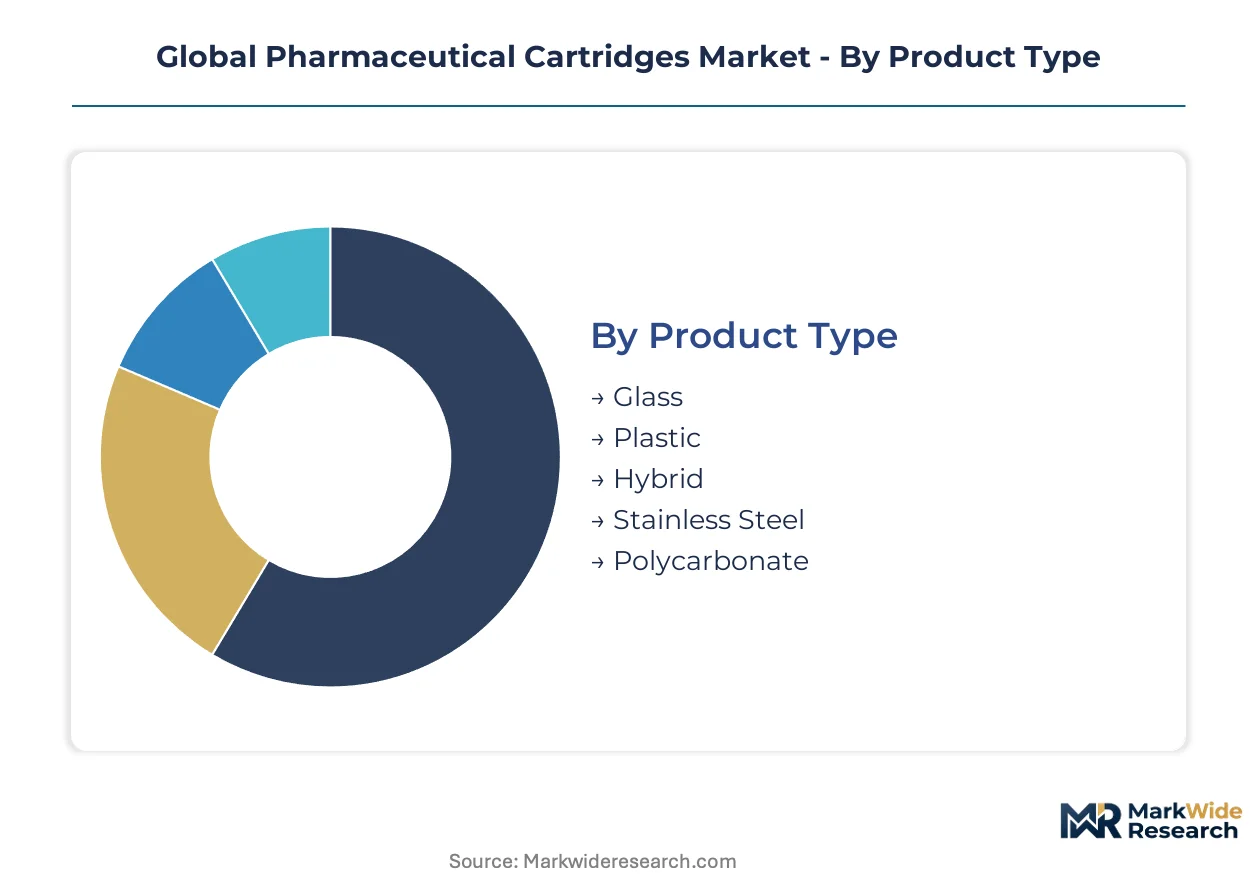
The pharmaceutical cartridges market exhibits diverse requirements driven by drug characteristics, patient needs, and regulatory mandates. Understanding these distinct market segments reveals varied requirements across therapeutic areas and delivery methods. This segmentation highlights the diverse needs pharmaceutical manufacturers address in their drug delivery systems.
Product Type:
Pharmaceutical manufacturers prioritize material selection based on drug compatibility, break resistance, and cost-effectiveness for their specific formulations.
- Glass:Type I borosilicate glass remains the standard for chemical inertness and clarity, crucial for sensitive drug formulations requiring minimal interaction. Demand concentrates in established pharmaceutical manufacturing centers like Germany and the United States for high-volume biologics and small molecule drugs.
- Plastic:Cyclic Olefin Polymers (COP) and Cyclic Olefin Copolymers (COC) offer superior break resistance and low protein adsorption, making them ideal for sensitive biologic drugs and patient-friendly auto-injectors. Their use is expanding rapidly in therapeutic areas like diabetes and autoimmune diseases where self-administration is common.
- Hybrid:These cartridges combine different materials, often glass barrels with polymer components, to leverage specific material advantages for complex drug delivery systems.
- Stainless Steel:Stainless steel cartridges are primarily used for specialized applications requiring extreme durability or specific chemical resistance, such as certain industrial or veterinary contexts.
- Polycarbonate:Polycarbonate offers impact resistance and transparency, finding niche applications where specific mechanical properties are prioritized over chemical inertness for less sensitive drugs.
Glass leads on market scale; plastic leads on technological momentum.
Application:
The specific therapeutic application dictates cartridge design, material choice, and volume requirements.
- Injectable Drugs:This broad category encompasses a wide range of parenteral medications, driving demand for cartridges that ensure sterility, dose accuracy, and compatibility with various administration devices. Demand is strong in the United States and Switzerland for novel biologics and complex small molecules.
- Insulin Delivery:Cartridges for insulin delivery require precise dosing mechanisms and often support multi-dose pen devices, emphasizing user-friendliness and long-term drug stability for chronic disease management. Germany and the US exhibit high demand for advanced insulin pen systems.
- Vaccines:Vaccine cartridges often prioritize single-dose or multi-dose presentations with robust sterility and stability requirements for widespread public health programs.
- Hormone Therapy:Cartridges for hormone therapies, including fertility treatments, require accurate dosing and often support pen injectors for patient self-administration over extended periods.
- Anesthetic Delivery:Anesthetic cartridges typically serve dental or localized pain management, demanding precise volumes and secure containment for controlled substances.
Diverse applications collectively shape the market's technological evolution and regulatory compliance landscape.
End User:
Different end-user groups engage with pharmaceutical cartridges at various stages of the drug lifecycle, from development to dispensing.
- Biotechnology Firms:These firms drive innovation in biologics and advanced therapies, requiring specialized cartridges that protect sensitive formulations from aggregation and adsorption. Their demand concentrates in R&D-intensive regions like Boston and San Francisco in the US, and Basel in Switzerland.
- Contract Manufacturing Organizations:CMOs produce cartridges for a wide range of clients, necessitating flexible manufacturing capabilities and stringent quality control to meet diverse drug specifications and regulatory requirements. Production hubs in Germany and India are significant for these services.
- Pharmacies:Pharmacies dispense pre-filled cartridges and pen devices directly to patients, focusing on product availability and ease of use for self-administration.
- Research Laboratories:Laboratories utilize cartridges for drug development, stability testing, and formulation studies, requiring small batches and specialized configurations for experimental purposes.
- Diagnostic Centers:Diagnostic centers may use cartridges for specific diagnostic reagents or sample collection, where sterility and precise volume are critical for accurate testing.
End-user demands significantly influence cartridge design specifications and supply chain dynamics.
Packaging Type:
Packaging configuration directly impacts patient convenience, dosing accuracy, and drug security.
- Single-Dose:Single-dose cartridges provide a precise, one-time administration, reducing contamination risks and simplifying dosage for many injectable therapies.
- Multi-Dose:Multi-dose cartridges enable repeated administrations from a single container, commonly found in insulin pens and growth hormone devices, requiring robust septa and precise dose delivery mechanisms. Demand is high in diabetes management across developed markets.
- Pre-Filled:Pre-filled cartridges come with the drug already loaded, minimizing preparation steps and reducing medication errors for patients and healthcare providers. This format is crucial for patient-centric devices like auto-injectors and pens, particularly in the US and Europe.
- Sterile:Sterile cartridges are manufactured and packaged under aseptic conditions, essential for parenteral drug products to prevent microbial contamination.
- Tamper-Evident:Tamper-evident features on cartridges provide visual assurance that the package has not been opened or altered, enhancing drug integrity and patient safety.
Packaging innovation responds directly to evolving patient needs and regulatory safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for pharmaceutical cartridges in the United States contrasts with that in Germany and Switzerland, driven by distinct regulatory landscapes and therapeutic focus. While the US prioritizes novel biologics, European centers emphasize high-volume manufacturing. Both regions require advanced containment solutions for sensitive drug formulations.
United States
The United States market sees strong demand for cartridges supporting novel biologics and advanced combination products. US FDA regulations rigorously govern container closure integrity and extractables, shaping material selection. Research and development hubs in Boston and San Francisco drive innovation for specialized cartridge designs.
Germany
Germany's market concentrates on high-volume biologics and small molecule drugs, leveraging established pharmaceutical manufacturing infrastructure. The European Medicines Agency (EMA) and EU Medical Device Regulation (MDR) enforce stringent quality and performance standards. Production centers around Frankfurt and Munich maintain a strong focus on precision engineering.
Switzerland
Switzerland, a hub for biologic drug development, fuels demand for premium, high-purity cartridges for sensitive therapies. Swissmedic regulations mandate robust stability data and material compatibility for new drug submissions. Basel, a prominent pharmaceutical cluster, leads in specifying advanced polymer and specialized glass cartridges.
India
India's pharmaceutical sector drives demand for cartridges from local and regional drug developers, focusing on cost-effective and efficient supply chains. The Central Drugs Standard Control Organization (CDSCO) guides product approvals and manufacturing standards. Production hubs in Hyderabad and Ahmedabad are expanding capabilities for cartridge manufacturing.
Japan
Japan's aging population and focus on advanced therapies, including regenerative medicine, increase demand for specialized cartridges. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict quality and safety requirements for drug delivery systems. Pharmaceutical clusters in Tokyo and Osaka are key centers for adopting innovative cartridge technologies.
Global Pharmaceutical Cartridges Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting a tiered market structure. The competitive landscape features high-purity material providers, integrated containment system developers, and large-scale glass and plastic manufacturers. Capacity expansion and strategic partnerships for combination product development are dominant competitive moves.
Within the high-volume manufacturing segment, Gerresheimer AG, an AG-structured company, exemplifies scale in both glass and plastic production. Schott AG, another AG-structured firm, represents the premium segment for high-purity borosilicate glass. West Pharmaceutical Services, a US-based entity, anchors the integrated containment and delivery systems archetype, focusing on elastomers and seals for complex drug products.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| West Pharmaceutical Services |
| Stevanato Group |
| Nipro Corporation |
| Datwyler Holding |
| Becton, Dickinson and Company |
| Merck KGaA |
| Transcoject GmbH |
| Others |
Cost & Logistics Intelligence
EU Medical Device Regulation (MDR) rigorously gates qualified supply for pharmaceutical cartridges, demanding extensive material validation. This regulatory stringency directly influences premium-tier pricing for compliant, high-performance containment solutions.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for pharmaceutical cartridges, particularly for high-volume glass products. The dominant pricing model involves contract-based long-term offtake agreements, driven by stringent certification levels from US FDA and EMA, alongside volume scale. Cost compression is intensifying for standard glass cartridges due to raw material volatility, while premium polymer solutions command higher prices. Biotechnology firms exhibit lower price sensitivity for specialized biologics, contrasting with the cost-focused procurement of contract manufacturing organizations.
Supply Chain Analysis
Regional distribution centers support the pharmaceutical cartridge supply chain, ensuring timely delivery to manufacturing hubs. Supply concentrates in Germany and Switzerland for premium glass and polymer products, with India expanding capabilities for regional drug developers. The supply chain draws from high-purity borosilicate glass tubing and specialized Cyclic Olefin Polymers. Single-source vulnerability for critical raw materials presents a structural risk, with distribution running directly from manufacturers to pharmaceutical companies and Contract Manufacturing Organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical cartridges market presents a compelling margin-expansion story, driven by the premium-tier shift towards advanced polymer cartridges. These specialized solutions command higher pricing due to their enhanced compatibility with sensitive biologic drugs.
For Market Incumbents: To counter technical failure risks like glass delamination and polymer gas permeability, incumbents must invest in advanced material R&D. Expanding production capacity for Cyclic Olefin Polymer (COP) cartridges in Germany strengthens market position. Deepening partnerships with device manufacturers for integrated combination products ensures compatibility and streamlines regulatory submissions under EU MDR. Pursuing US FDA certification for novel polymer formulations captures premium biologic demand.
For New Entrants and Emerging Players: Small biotechnology firms developing niche therapies represent an underserved buyer archetype for specialized cartridges. Targeting demand from research laboratories for dual-chamber cartridges for lyophilized drugs provides a white-space opportunity. Establishing cost-effective manufacturing capabilities in India allows access to regional drug developers. Offering rapid prototyping services and smart packaging integration provides a compelling go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among legacy glass cartridge manufacturers facing material cost volatility. The market offers long-term viability given the essential role of cartridges in biologic and chronic disease management. Targeting specialized polymer cartridge manufacturers or integrated containment system developers provides strategic acquisition opportunities. Increased regulatory clarity from US FDA or EMA on novel polymer materials is a crucial signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Polymer Cartridges | Scaling production of Cyclic Olefin Polymer cartridges meets demand from sensitive biologic drug developers. |
| Regulatory Approval Pathway Acceleration | Streamlining US FDA and EMA submissions for novel materials shortens time-to-market for advanced solutions. |
| Strategic Partnerships with Device Manufacturers | Collaborating on integrated drug-device combination products ensures seamless functionality and patient safety. |
| Dual-Chamber Cartridge Product Launch | Introducing multi-chamber systems enables point-of-administration reconstitution for complex lyophilized drugs. |
| Green Manufacturing Process Transition | Adopting sustainable production methods aligns with evolving environmental mandates and enhances brand reputation. |
Research Approach
Multiple input streams — primary interviews, secondary research, and proprietary databases — were reconciled to construct this market analysis. Primary engagements included drug development executives, regulatory affairs leads, procurement managers, and material scientists across Germany and the United States. Secondary validation drew from US FDA filings, EMA submissions, industry association reports, and scientific literature. This approach ensured robust bottom-up and top-down triangulation of market data.
Historical market performance was cross-referenced against expert panel input to project future trends across the analysis window. The analytical framework modeled segmentation by product type, application, end user, and packaging type, plus regional regulatory clusters. Compound annual growth rates were derived through a multi-variable regression approach. New drug approvals for biologics and chronic disease prevalence rates served as key forecast inputs.
Underlying measurement precision varies by segment; glass and plastic product types carry tighter precision than hybrid offerings. Forecasts reflect documented assumptions, acknowledging regulatory changes or raw material supply disruptions could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Cryogenic Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market