
 Pharmaceutical Stability and Storage Services Market | 2026-2036
Pharmaceutical Stability and Storage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Stability and Storage Services Market Intelligence
North American contract service capacity is rebalancing after pandemic-era expansion. Alcami Corporation leverages its integrated analytical and stability platform to capture complex small-molecule programs. Catalent, Inc. anchors North American clinical-trial supply with multi-temperature storage networks. SGS SA competes through its global footprint in regulatory-compliant stability testing.
Pharmaceutical stability and storage services encompass controlled-environment holding, accelerated and long-term stability evaluation, and regulatory documentation for drug substances and products, typically maintained between 2-8°C for biologics or 25°C/60% RH for standard pharmaceuticals to establish shelf-life claims and release specifications. The primary purpose is to generate data packages that satisfy health authority requirements before commercial approval and throughout product lifecycle management. Stability testing commands premium pricing due to ICH guideline complexity and extended study durations. Automated Monitoring technology is displacing manual chart recorders as real-time data integrity becomes non-negotiable. Cold Chain Distribution infrastructure determines geographic service radius for temperature-sensitive biologics.
FDA enforces current Good Manufacturing Practice through 21 CFR Part 211, while EMA implements ICH Q1A(R2) guidelines across European member states; both frameworks mandate documented stability data for market authorization applications. The EU's F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants, forcing storage providers to retrofit environmental chambers with alternative cooling systems. Stakeholders must monitor how evolving pharmacopoeial standards for cell and gene therapies reshape facility qualification requirements.
Market Dynamics
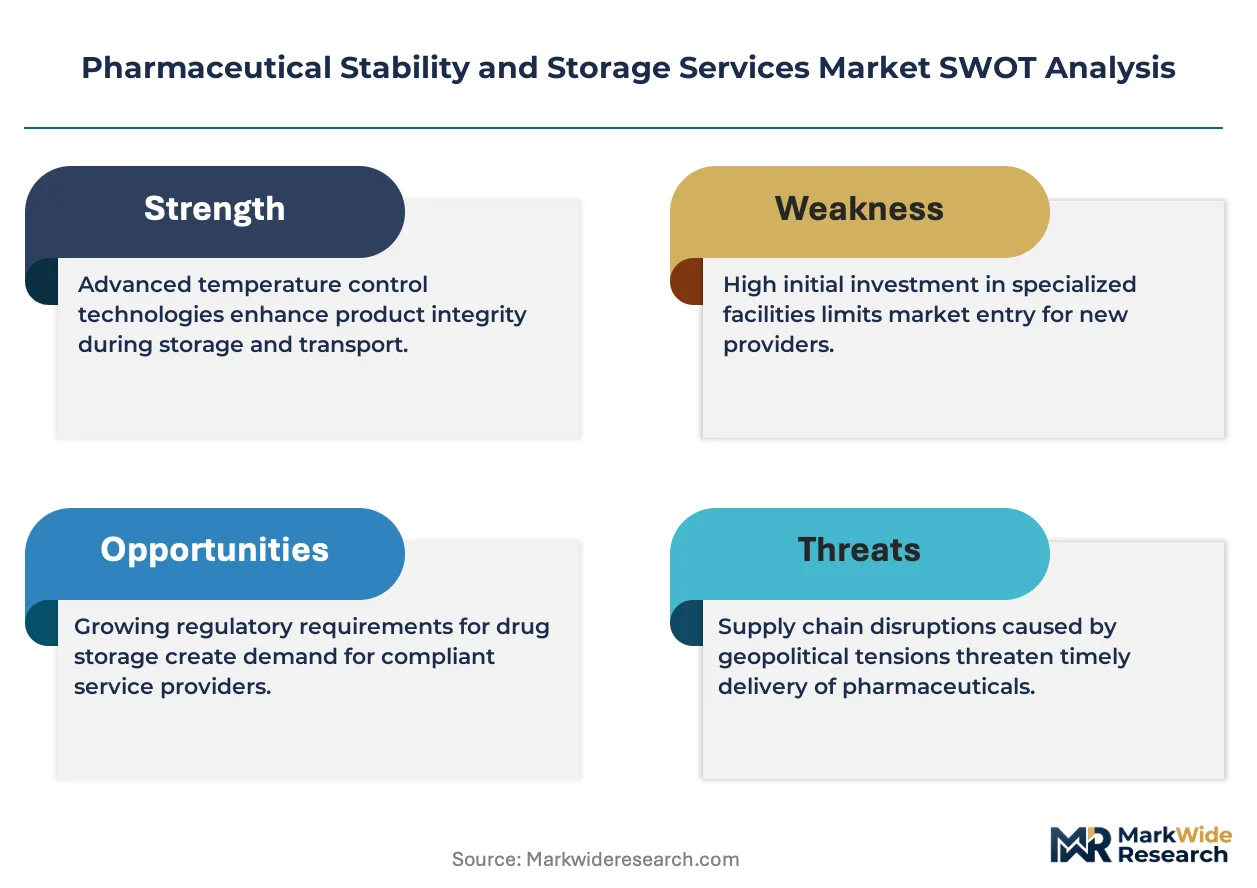
Automated environmental monitoring systems are compressing operational margins for legacy storage providers while creating tiered capability gaps between ICH Q1A-compliant facilities and manual operations.
Growth Catalysts
- ICH Q1A(R2) guideline expansion:FDA and EMA now require continuous temperature documentation for commercial biologics, forcing developers to outsource stability studies to specialized contract laboratories rather than maintain in-house chambers.
- Cell and gene therapy pipeline:Ultra-cold storage requirements for CAR-T and viral vector products below minus 150 degrees Celsius are generating demand for cryogenic stability infrastructure that most pharmaceutical manufacturers lack.
- United States biopharma clustering:Massachusetts and California concentration of advanced therapy developers creates geographic pull for integrated stability-testing-and-storage facilities within 50-mile radii of manufacturing sites.
Market Restraints
- EU F-Gas Regulation retrofit costs:The progressive hydrofluorocarbon phase-down forces European storage providers to replace existing environmental chamber cooling systems with natural refrigerant alternatives at capital intensity exceeding standard equipment replacement cycles.
- Qualified personnel scarcity:Stability study directors with combined analytical chemistry and regulatory documentation expertise command compensation premiums that inflate fixed costs for mid-scale service providers.
- Real estate concentration:Cold-chain facilities require proximity to transportation hubs, limiting site selection to industrial zones with escalating lease rates in pharmaceutical corridors.
Strategic Opportunities
- India CDMO stability integration:Domestic biopharma developers are localizing stability testing to support export registration filings, creating whitespace for contract laboratories with WHO-prequalified facilities.
- Continuous manufacturing alignment:Real-time release testing methodologies are converging with automated stability monitoring, enabling service providers to offer integrated shelf-life prediction rather than discrete timepoint studies.
- Japan PMDA gene therapy guidance:New stability requirements for regenerative medicine products are mandating extended characterization protocols that specialized storage providers can capture from domestic pharmaceutical companies.
Industry Challenges
- Data integrity audit intensity:FDA Warning Letters citing ALCOA+ violations in stability records are extending qualification timelines for new environmental monitoring system deployments.
- Multi-temperature facility complexity:Simultaneous maintenance of ICH Q1A zones at 25 degrees Celsius, 2-8 degrees Celsius, minus 20 degrees Celsius, minus 80 degrees Celsius, and cryogenic conditions strains HVAC redundancy engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Stability and Storage Services Market |
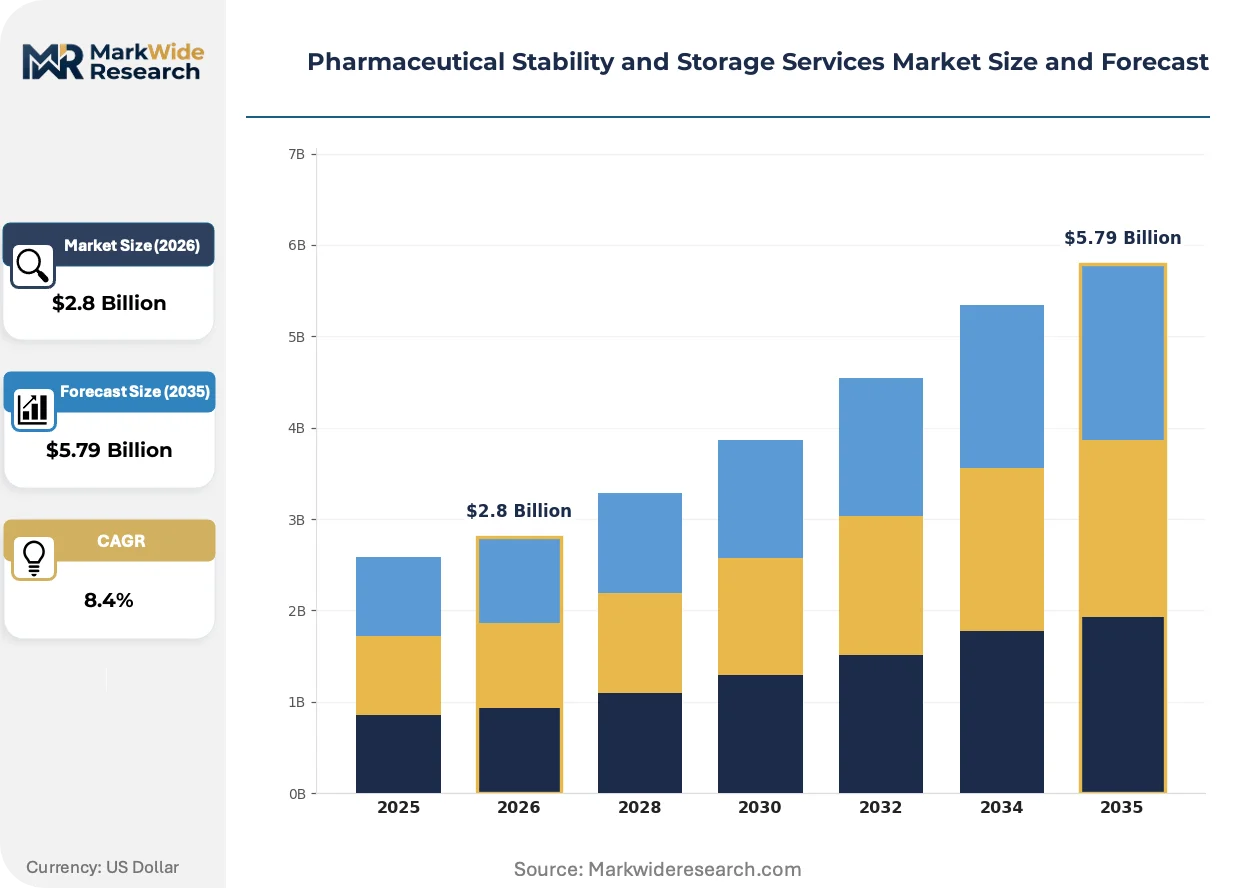
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Temperature Control, Stability Testing, Storage Solutions, Compliance Management Application: Clinical Trials, Research Studies, Inventory Management, Regulatory Compliance End User: Pharmaceutical Manufacturers, Bio-Tech Companies, Contract Research Organizations, Quality Control Laboratories Technology: Automated Monitoring, Cold Chain Distribution, Analytical Instrumentation, Data Management Systems |
| Companies Covered | Alcami Corporation, Intertek Group plc, Catalent, Inc., PCI Pharma Services, SGS SA, Charles River Laboratories, Almac Group, Thermo Fisher Scientific, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Stability and Storage Services Market Strategic Shifts & Innovations
Digital integration of stability data generation with regulatory submission workflows is compressing study turnaround timelines while elevating technical barriers to market entry.
Wireless sensor networks with blockchain-anchored data logging are consolidating fragmented environmental monitoring architectures into unified platforms. Biopharmaceutical developers with distributed manufacturing footprints are adopting these systems to harmonize stability documentation across multiple contract sites. This consolidation is eliminating manual transcription errors while reducing the labor component of ICH Q1A compliance by half.
The EU F-Gas Regulation's hydrofluorocarbon quota system is accelerating adoption of transcritical CO2 and ammonia-based cooling in environmental chambers. European storage providers face equipment replacement deadlines that compress capital planning horizons. Germany and France are witnessing facility retrofit waves that favor turnkey engineering partnerships over component procurement.
Integrated service contracting is displacing discrete stability study procurement. Large molecule developers now bundle long-term storage, accelerated testing, and regulatory documentation under single-provider agreements. This bundling is most pronounced in the United States, where sponsors prioritize audit reduction over per-study cost minimization.
Pharmaceutical Stability and Storage Services Market Segmentation
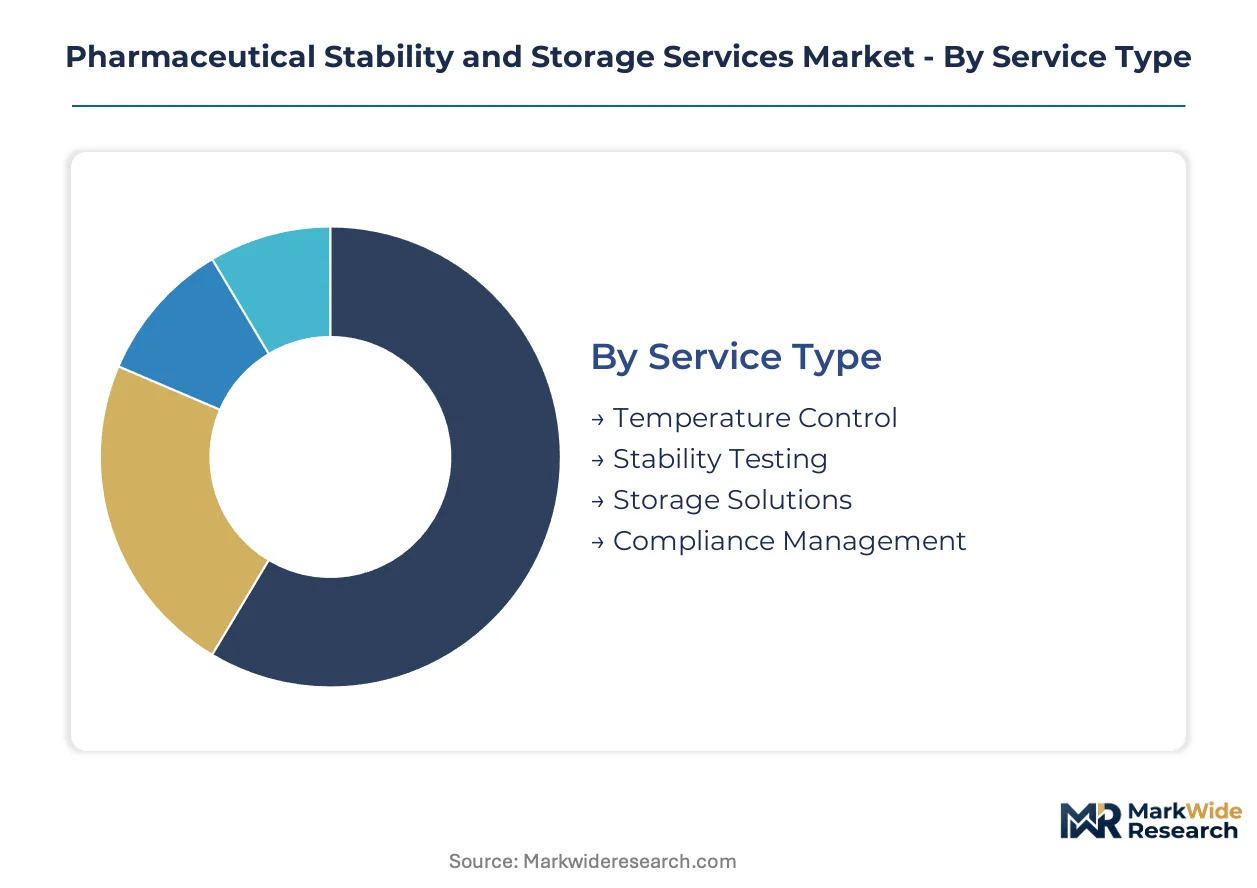
Segmentation in pharmaceutical stability and storage services reveals how specialized capabilities command pricing premiums. Service providers configure infrastructure investments around distinct temperature regimes, study phases, and regulatory documentation requirements.
Service Type:
Replacement cycles for environmental chamber fleets are accelerating as ICH Q1A(R2) compliance deadlines force infrastructure upgrades across contract laboratories.
- Temperature Control:Precision thermal management systems maintain ICH-specified conditions from 25°C/60% RH through cryogenic ranges below -150°C. Demand clusters in Massachusetts and California corridors where advanced therapy developers require redundant cold-chain validation for FDA submissions.
- Stability Testing:Accelerated and long-term protocols generate shelf-life data packages for commercial authorization. European facilities face compressed retrofit timelines under the EU F-Gas Regulation's hydrofluorocarbon phase-down, favoring providers with transcritical CO2 systems already deployed.
- Storage Solutions:Multi-zone warehousing with 21 CFR Part 11-compliant documentation supports clinical and commercial inventory.
- Compliance Management:Regulatory submission preparation and health authority response coordination.
Temperature Control sits at the top of the volume ranking, with Stability Testing climbing the fastest.
Application:
Cost tiering separates discrete study procurement from integrated program contracts that bundle testing, storage, and documentation under single-provider frameworks.
- Clinical Trials:Phase-appropriate stability protocols support investigational product release and shelf-life extension. Catalent's North American network captures sponsor preference for multi-temperature storage adjacent to clinical distribution hubs.
- Research Studies:Preclinical and formulation development testing establishes preliminary stability profiles. SGS SA leverages its global footprint to harmonize early-phase protocols across manufacturing sites in Switzerland, Germany, and the United States.
- Inventory Management:Commercial product holding with batch release documentation.
- Regulatory Compliance:Health authority query response and post-approval change management.
Clinical Trials anchor revenue concentration, with Research Studies gaining share fastest among mid-scale developers outsourcing early-phase work.
End User:
Customer type determines facility qualification depth, with large molecule developers demanding redundant HVAC engineering that smaller quality laboratories rarely specify.
- Pharmaceutical Manufacturers:Integrated stability programs spanning drug substance through finished product lifecycle. Alcami Corporation captures complex small-molecule portfolios requiring combined analytical and storage capabilities.
- Bio-Tech Companies:Ultra-cold infrastructure for cell and gene therapy products with cryogenic stability requirements. CAR-T developers in Boston and San Diego corridors drive demand for -150°C validation protocols that most in-house facilities cannot maintain.
- Contract Research Organizations:Outsourced stability capacity for sponsor risk distribution.
- Quality Control Laboratories:Release testing and routine monitoring services.
Pharmaceutical Manufacturers represent the largest addressable base, with Bio-Tech Companies expanding most quickly as gene therapy pipelines mature.
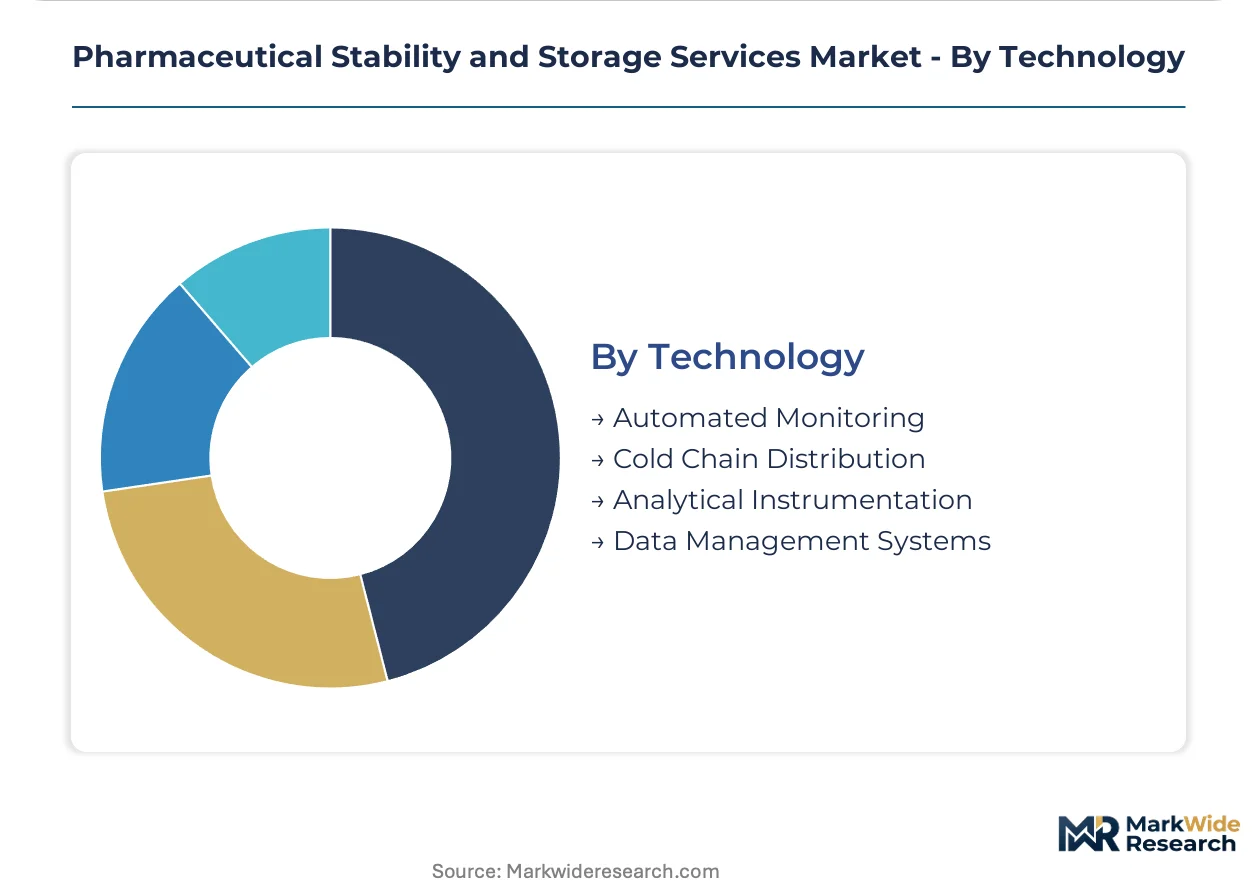
Technology:
Margin compression from automated systems is widening capability gaps between ICH Q1A-compliant facilities and manual operations.
- Automated Monitoring:Wireless sensor networks with real-time alerting and blockchain-anchored data logging. FDA Warning Letters citing ALCOA+ violations are forcing legacy providers to accelerate system deployments or exit commercial biologics work.
- Cold Chain Distribution:Temperature-validated logistics bridging storage facilities and clinical sites. Geographic service radius for biologics contracts tightens as developers prioritize 50-mile proximity to manufacturing clusters.
- Analytical Instrumentation:Chromatography and spectroscopy systems for stability-indicating method development.
- Data Management Systems:LIMS integration with regulatory submission workflows.
Automated Monitoring leads technology investment, with Cold Chain Distribution showing the steepest expansion trajectory as distributed manufacturing footprints proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where pharmaceutical developers locate stability programs, with cost-of-compliance gaps between jurisdictions driving selective migration of biologics storage capacity toward regions with streamlined health authority frameworks.
United States
FDA's 21 CFR Part 211 enforcement and ICH Q1A(R2) compliance deadlines are forcing domestic biopharma developers to outsource stability studies. Massachusetts and California corridors concentrate CAR-T and viral vector developers demanding cryogenic validation protocols below minus 150 degrees Celsius. Alcami Corporation and Catalent anchor multi-temperature networks within 50-mile radii of Boston and San Diego manufacturing clusters.
Germany
EMA's ICH guideline implementation across European member states generates demand for regulatory-compliant stability documentation. The EU F-Gas Regulation's hydrofluorocarbon phase-down is accelerating transcritical CO2 retrofits in environmental chambers across Baden-Württemberg and Bavaria. SGS SA maintains facilities in Frankfurt and Munich to capture sponsor preference for integrated testing-and-storage contracts.
Switzerland
Swissmedic's alignment with EMA stability requirements supports Basel and Zurich's concentration of large-molecule developers. The country's pharmaceutical corridor attracts integrated service providers offering bundled long-term storage, accelerated testing, and regulatory submission preparation. Eurofins Scientific and Charles River Laboratories occupy positions serving domestic biotechs with distributed European manufacturing footprints.
India
CDSCO's tightening stability documentation requirements for export registration filings are driving domestic biopharma developers toward WHO-prequalified contract laboratories. Maharashtra and Gujarat pharmaceutical manufacturing zones are localizing stability testing capacity previously routed to European providers. Thermo Fisher Scientific and Intertek Group plc represent archetypes capturing this whitespace through facility investments in Hyderabad and Mumbai corridors.
Japan
PMDA's new stability requirements for regenerative medicine products mandate extended characterization protocols that domestic pharmaceutical companies increasingly outsource. Kanto and Kansai regions concentrate gene therapy developers requiring specialized cryogenic infrastructure. Almac Group and PCI Pharma Services occupy positions serving sponsors navigating Japan's evolving shelf-life claim documentation standards.
Pharmaceutical Stability and Storage Services Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue automated monitoring and cryogenic specialization as differentiation vectors. The vendor base stratifies across three capability levels: integrated analytical-and-storage platforms, discrete testing laboratories, and regional cold-chain operators. Two dominant competitive moves are reshaping positioning: strategic partnerships to combine temperature control expertise with regulatory documentation capabilities, and selective capacity expansion in 50-mile proximity zones around biopharma manufacturing clusters.
Within the integrated platform tier, Alcami Corporation, Catalent, and SGS SA exemplify archetypes combining multi-temperature storage networks with ICH Q1A-compliant stability testing. These entities represent positions where sponsors prioritize audit reduction over per-study cost minimization, particularly for commercial biologics requiring continuous temperature documentation. Charles River Laboratories and Thermo Fisher Scientific occupy the analytical-specialist vector, anchoring early-phase and preclinical stability work across distributed manufacturing footprints.
| Leading Market Players |
|---|
| Alcami Corporation |
| Intertek Group plc |
| Catalent, Inc. |
| PCI Pharma Services |
| SGS SA |
| Charles River Laboratories |
| Almac Group |
| Thermo Fisher Scientific |
| Eurofins Scientific |
| Others |
Cost & Logistics Intelligence
Horizontal integration into multi-temperature facility networks anchors supply positioning for contract stability providers while concentrating pricing power among operators with redundant ICH Q1A-compliant infrastructure. Alcami Corporation and Catalent leverage contiguous storage-and-testing footprints to command premium contract terms from biopharmaceutical developers prioritizing audit consolidation over per-study cost minimization.
Pricing Analysis
Distributor margins in cold-chain logistics compress net realized prices for storage providers serving distributed clinical trial networks. Three-tier pricing structure across premium, standard, and economy levels separates ICH Q1A-validated cryogenic facilities from chamber-only operations and manual monitoring services. Pricing pressure stems from automated environmental monitoring systems displacing labor-intensive documentation workflows. Mid-scale contract laboratories exhibit highest price sensitivity as FDA Warning Letters force capital redeployment into compliance infrastructure.
Supply Chain Analysis
Dual-sourcing requirements for cryogenic refrigerants and HVAC redundancy components compel stability providers to qualify multiple equipment vendors across Germany, Japan, and the United States. Supply chains draw from specialized environmental chamber manufacturers, wireless sensor network providers, and transcritical CO2 cooling system engineers. Single-source vulnerability concentrates in precision temperature control modules qualified for ICH guideline compliance. Distribution runs through pharmaceutical corridor logistics hubs with validated last-mile cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU F-Gas Regulation retrofit costs and United States infrastructure subsidies creates cost differentials favoring selective capacity migration toward jurisdictions with streamlined environmental compliance timelines.
For Market Incumbents: Anticipate margin compression from automated monitoring technology by accelerating captive analytical capability integration and securing redundant HVAC engineering talent pools in Massachusetts and California corridors. Defensive consolidation around cryogenic validation expertise protects against emerging entrants with ammonia-based cooling specializations. Certification investment in WHO-prequalified facilities captures India CDSCO export registration demand. For New Entrants and Emerging Players: Blockchain-anchored data logging platforms offer technology-first wedge into fragmented environmental monitoring architectures serving distributed manufacturing footprints. White-space concentrates in India CDMO stability integration and Japan PMDA gene therapy guidance compliance. Hyderabad and Mumbai corridors present most penetrable geography for WHO-prequalified facility investment. Go-to-market positioning emphasizes real-time release testing convergence with automated stability monitoring. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale analytical-specialist laboratories because ICH Q1A compliance complexity creates acquisition targets with irreplaceable regulatory documentation expertise and qualified study director talent. Long-term viability hinges on platform consolidation spanning temperature control, stability testing, and submission preparation capabilities. Acquisition target archetype: regional cold-chain operators with underutilized cryogenic capacity and established FDA inspection histories. Signal to watch: FDA Warning Letter volume citing ALCOA+ violations as indicator of forced seller emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Expansion | CAR-T developers in Boston and San Diego corridors demand minus 150°C validation protocols. |
| Transcritical CO2 Retrofit Partnership | EU F-Gas Regulation deadlines favor turnkey engineering relationships over component procurement in Germany. |
| Automated Monitoring Platform Integration | WHO-prequalified facilities in Hyderabad capture CDSCO export registration filing demand. |
| Regulatory Submission Bundling | Integrated contracts spanning storage, testing, and documentation reduce sponsor audit burden. |
| 50-Mile Proximity Zone Capacity Addition | Massachusetts and California manufacturing clusters prioritize adjacent stability infrastructure. |
Research Approach
Multiple input streams — regulatory filing databases, contract service capacity audits, and equipment procurement records — were reconciled through structured primary interviews with stability study directors, regulatory affairs leads, contract laboratory procurement managers, and biopharmaceutical quality executives. Secondary validation incorporated FDA 483 observations, EMA inspection reports, ICH guideline documentation, and customs data on environmental chamber imports. Bottom-up facility capacity estimates and top-down sponsor outsourcing expenditure patterns were triangulated to anchor market sizing.
Data-stream reconciliation across service type, temperature regime, application phase, and end-user archetype generated segmentation-level projections throughout the forecast period. CAGRs were derived from capacity expansion announcements, regulatory deadline impacts on retrofit cycles, and sponsor pipeline maturation curves. Forecast inputs incorporated ICH Q1A(R2) compliance timeline acceleration, EU F-Gas Regulation phase-down schedules, and cell and gene therapy commercialization trajectories.
The model holds under stable regulatory enforcement intensity and sustained biopharmaceutical outsourcing preference; deviation in FDA Warning Letter issuance rates or EMA inspection prioritization shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Cryogenic Ampoules Market
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market