
 Asia-Pacific CDMO Market | 2026-2036
Asia-Pacific CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific CDMO Market Insights
Pharmaceutical outsourcing channels across the Asia-Pacific CDMO Market is fragmenting as sponsor companies diversify supplier bases beyond single-source dependencies. Samsung Biologics anchors massive mammalian cell culture capacity in South Korea. WuXi Biologics extends integrated discovery-to-commercial platforms across China and beyond. Lonza Group competes through specialized microbial fermentation and advanced therapy manufacturing networks.
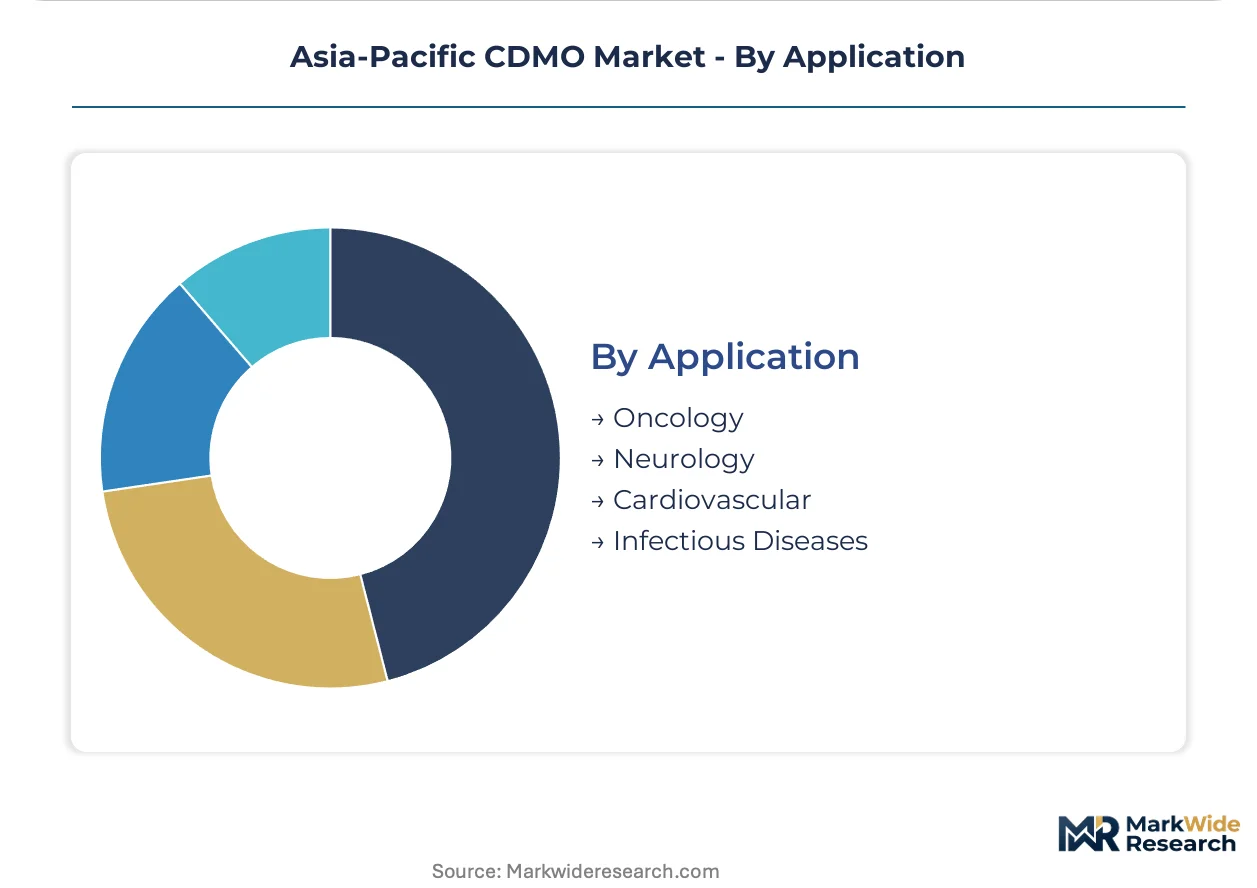
Contract development and manufacturing organizations provide integrated pharmaceutical services spanning drug substance production, formulation, analytical testing, and regulatory filing support, typically operating under GMP conditions with batch sizes ranging from clinical-scale to multi-thousand-liter commercial bioreactors. The Asia-Pacific CDMO Market segments across service type, end user, technology, and application dimensions. Contract Manufacturing captures the dominant value pool given capital intensity and long-term supply agreements, while Product Development commands premium margins for early-phase molecules. Oncology applications lead volume demand due to the pipeline of biologics targeting solid tumors.
China's NMPA and South Korea's MFDS enforce evolving GMP standards that determine facility approval timelines and cross-border shipment eligibility for drug substances. India's CDSCO aligns with ICH guidelines while imposing local stability testing requirements that shape facility investment decisions. Japan's PMDA maintains distinct pharmacopeial standards for imported biologics. Stakeholders must monitor regulatory divergence across these agencies when allocating capacity and qualifying alternate manufacturing sites.
Market Dynamics
Biopharmaceutical sponsors are fragmenting supplier bases across the Asia-Pacific CDMO Market, driven by single-source risk mitigation and the geographic concentration of mammalian cell culture capacity in South Korea and eastern China.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for active pharmaceutical ingredients and biologics are accelerating domestic fermentation capacity expansion. Domestic sponsors now qualify for cost offsets tied to local manufacturing value-add.
- Monoclonal antibody pipelines:Oncology biologics targeting solid tumors are pulling demand for multi-thousand-liter stainless steel bioreactors. Sponsor companies are locking in long-term supply agreements ahead of Phase III readouts.
- NMPA reform pathway:China's streamlined GMP inspection mutual recognition protocols are compressing facility approval timelines for cross-border drug substance shipments. This reduces redundant qualification audits for multinational sponsors.
Market Restraints
- Freight cost volatility:Temperature-controlled logistics for drug substance shipments face jet fuel price swings and constrained cold-chain container availability. This squeezes margin on clinical-scale batches.
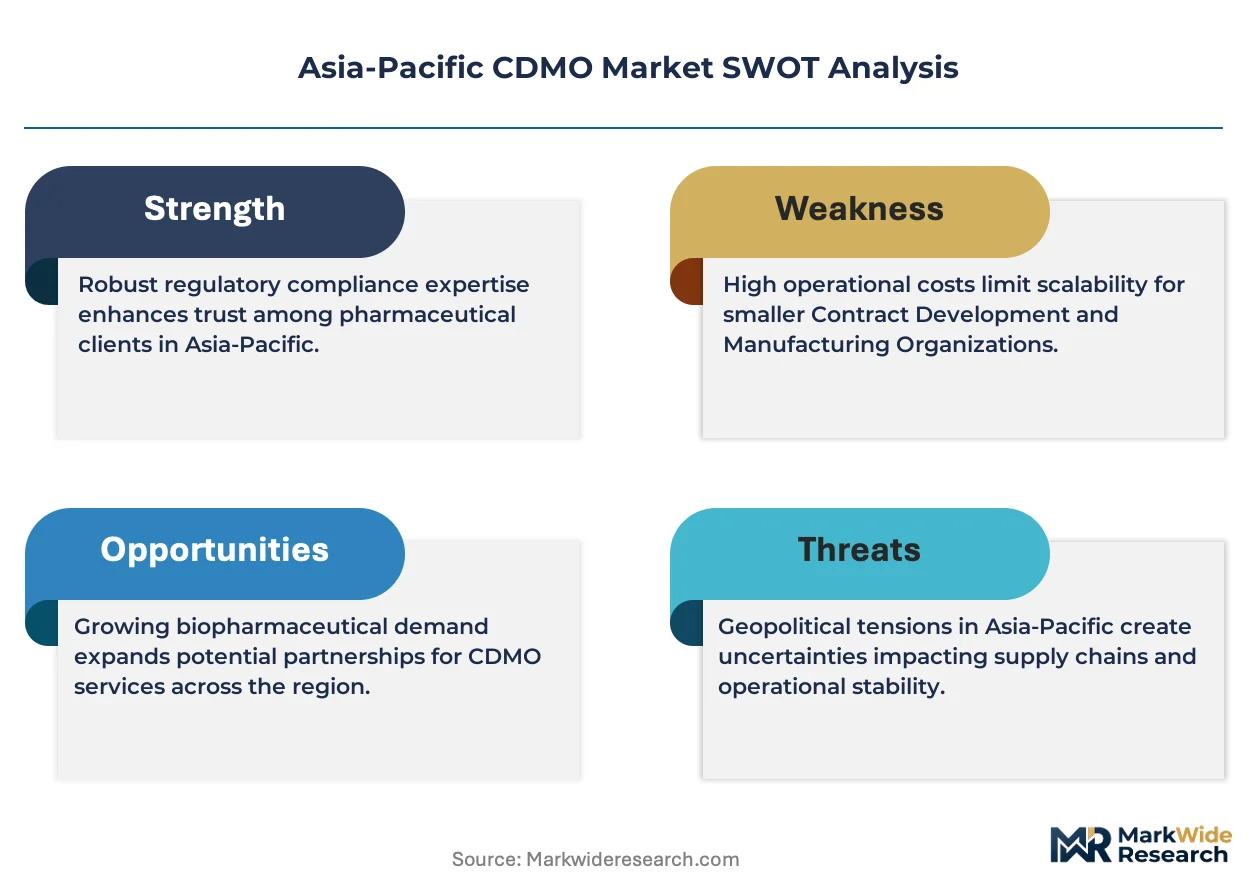
- Single-region concentration:Mammalian cell culture capacity clusters heavily in South Korea's Songdo and China's Suzhou-Shanghai corridor. Geopolitical friction or regional health events disrupt contingency planning.
- Skilled technician scarcity:Advanced therapy manufacturing requires GMP-compliant cell handling expertise that outpaces regional vocational training output. This elongates facility qualification timelines.
Strategic Opportunities
- Southeast Asia greenfield:Vietnam and Indonesia lack commercial-scale biologics capacity despite rising sponsor interest. First-mover CDMOs can anchor regional supply before infrastructure matures.
- Continuous processing convergence:Perfusion bioreactor technology married with real-time analytics is enabling smaller-footprint facilities. This opens tier-two city deployment without sacrificing batch economics.
- MFDS orphan drug incentives:South Korea's expedited review and tax credits for rare disease biologics are pulling early-phase manufacturing into the region. Sponsors leverage this for global launch sequencing.
Industry Challenges
- Multi-agency GMP divergence:China's NMPA, South Korea's MFDS, and Japan's PMDA maintain non-harmonized stability testing and validation requirements. This forces redundant documentation and inspection cycles.
- Legacy equipment integration:Stainless steel bioreactor trains predating single-use adoption require retrofitting for flexible multi-product campaigns. Capex recovery timelines stretch across contract renegotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific CDMO Market |
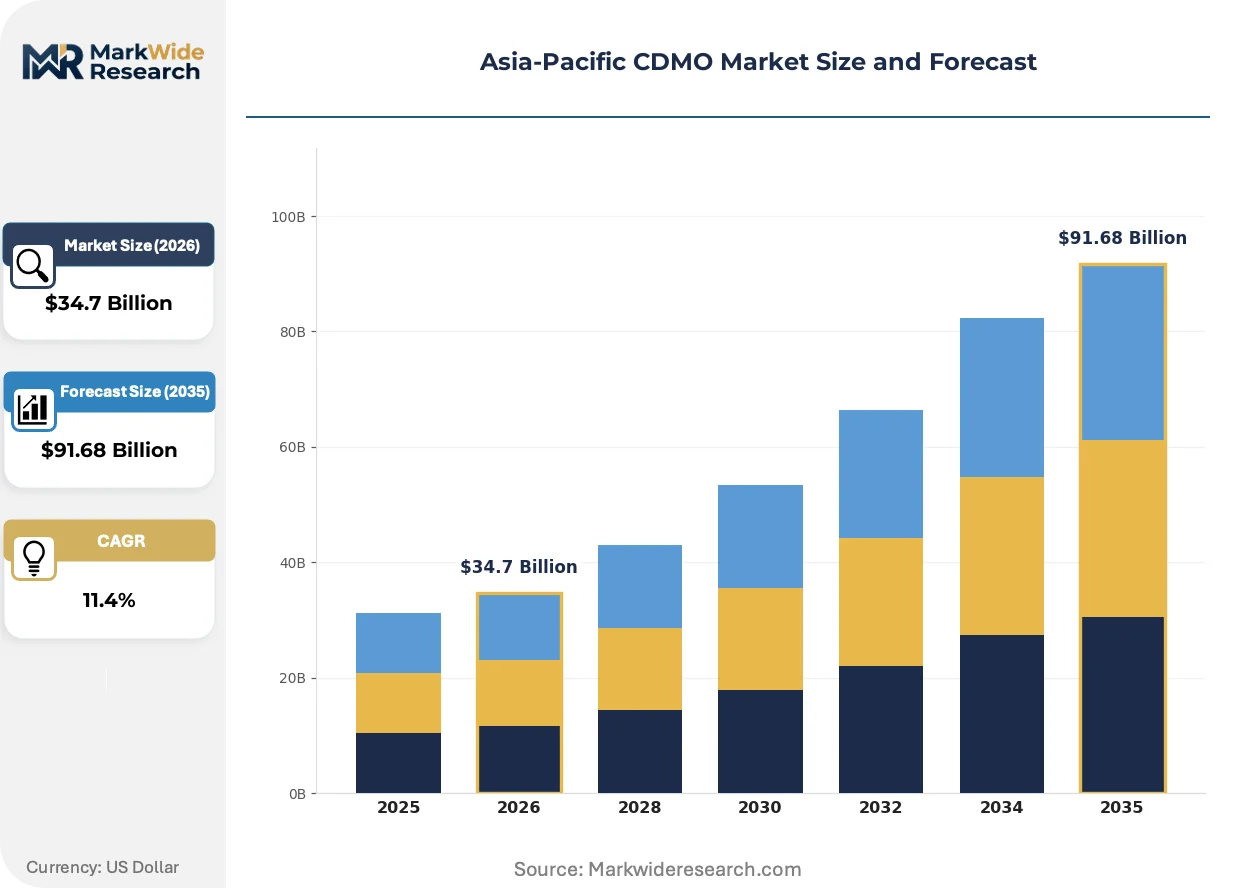
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Contract Manufacturing, Product Development, Analytical Services, Regulatory Affairs End User: Biopharmaceutical Companies, Medical Device Manufacturers, Generic Drug Producers, Research Institutions Technology: Cell Culture, Microbial Fermentation, Formulation Development, Aseptic Processing Application: Oncology, Neurology, Cardiovascular, Infectious Diseases |
| Companies Covered | Samsung Biologics, WuXi Biologics, Jubilant Biosys Ltd, Syngene International Limited, Thermo Fisher Scientific Inc., Lonza Group, Catalent Inc., FUJIFILM Diosynth Biotechnologies, Boehringer Ingelheim Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific CDMO Market Trends and Innovations
Process analytical technology and modular facility design are compressing batch cycle times across the Asia-Pacific CDMO Market. Sponsors now demand real-time release testing and rapid product changeover capabilities.
Single-use bioreactor systems are digitizing quality control workflows across clinical and commercial manufacturing. Biopharmaceutical sponsors in South Korea are adopting these platforms at scale for multi-product facilities. This technology is digitizing batch record review and deviation tracking, compressing release timelines from weeks to days.
China's NMPA has implemented data integrity guidelines aligned with ICH Q9 and Q10 frameworks for computerized manufacturing systems. This mandates audit trails for all critical process parameters in biologics production. Domestic CDMOs in Suzhou and Hangzhou are retrofitting legacy distributed control systems to meet these requirements ahead of sponsor audits.
Sponsor procurement teams are consolidating vendor panels from fifteen-plus suppliers to three to five strategic partners with integrated discovery-to-commercial platforms. This consolidation is displacing transactional fee-for-service relationships with outcome-tied master service agreements. The shift is most visible among mid-cap biotech sponsors based in Shanghai and Singapore seeking regulatory filing support bundled with manufacturing.
Asia-Pacific CDMO Market Segmentation
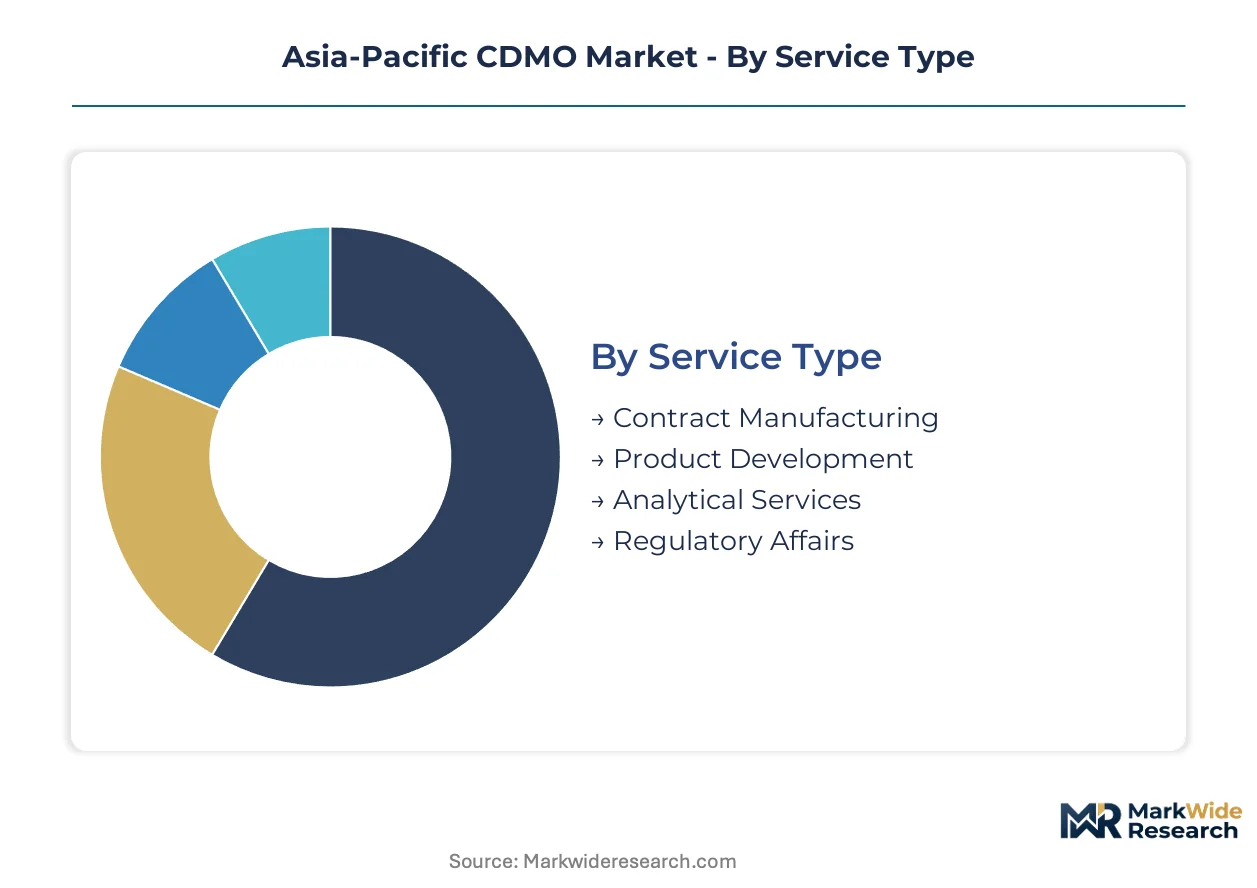
CDMO service portfolios in Asia-Pacific stratify sharply between capital-intensive commercial manufacturing and margin-rich early-phase development. Sponsor procurement teams now weight geographic regulatory alignment as heavily as technical capability when segmenting vendor panels.
Service Type:
Use-case spectrum spans commodity production runs through high-touch regulatory navigation, with capital deployment intensity determining contract economics.
- Contract Manufacturing:Multi-thousand-liter bioreactor operations under GMP conditions anchor long-term supply agreements. Demand concentrates in South Korea's Songdo corridor and China's Suzhou-Shanghai cluster, where stainless steel trains and single-use systems compete for monoclonal antibody campaigns.
- Product Development:Cell line engineering, process characterization, and CMC documentation for IND-enabling studies command premium pricing per full-time equivalent. Biopharmaceutical sponsors in Shanghai and Singapore are bundling these services with manufacturing slots to compress timeline risk.
- Analytical Services:Release testing, stability protocols, and biosimilar comparability studies support batch disposition decisions.
- Regulatory Affairs:Dossier preparation and agency correspondence for NMPA, MFDS, and PMDA submissions navigate divergent documentation requirements.
Established volume favors Contract Manufacturing; emerging adoption favors Product Development.
End User:
Customer-type concentration shapes facility qualification priorities, with biologics sponsors demanding mammalian cell culture capacity that generic manufacturers rarely require.
- Biopharmaceutical Companies:Originators of monoclonal antibodies, recombinant proteins, and advanced therapies outsource manufacturing to avoid fixed asset burdens. Oncology pipeline sponsors in China and South Korea are locking in capacity ahead of Phase III readouts.
- Medical Device Manufacturers:Combination product assembly and sterile fill-finish for drug-device integrations require ISO 13485 overlays on pharmaceutical GMP.
- Generic Drug Producers:Cost-competitive API sourcing and formulation development for off-patent small molecules.
- Research Institutions:Academic GMP manufacturing for investigator-initiated trials and preclinical material generation.
Biopharmaceutical Companies absorb the dominant share of mammalian cell culture capacity; Research Institutions represent the most price-sensitive demand tier.
Technology:
Process modality selection determines facility footprint, workforce composition, and contamination risk profiles across the manufacturing network.
- Cell Culture:Mammalian expression systems for complex glycoproteins and monoclonal antibodies dominate commercial biologics output. Perfusion bioreactor adoption in South Korea is compressing facility footprints while maintaining batch economics.
- Microbial Fermentation:Bacterial and yeast platforms for insulin analogs, growth factors, and biosimilars leverage India's expanding fermentation capacity under PLI scheme incentives.
- Formulation Development:Lyophilization, liposomal encapsulation, and sustained-release matrix design for parenteral and oral dosage forms.
- Aseptic Processing:Isolator-based fill-finish and terminal sterilization for sterile injectables and ophthalmic preparations.
Cell Culture commands the steepest capital investment per liter of capacity; Microbial Fermentation offers the fastest payback on greenfield fermentation suites.
Application:
Therapeutic area concentration aligns with pipeline maturation and reimbursement dynamics across Asia-Pacific health systems.
- Oncology:Immuno-oncology biologics and antibody-drug conjugates drive demand for potent compound handling suites. Solid tumor indications anchor multi-thousand-liter campaigns in eastern China.
- Neurology:Blood-brain barrier penetration technologies and CNS-targeted delivery systems for Alzheimer's and Parkinson's candidates.
- Cardiovascular:Recombinant clotting factors and PCSK9 inhibitors for metabolic and thrombotic conditions.
- Infectious Diseases:Vaccine bulk manufacturing and antiviral biologics for pandemic preparedness and endemic disease control.
Oncology concentrates the largest committed capacity blocks; Infectious Diseases shows the most volatile demand spikes tied to outbreak cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea commands premium pricing for mammalian cell culture capacity while India competes on cost through fermentation scale. This asymmetry shapes sponsor procurement strategies across the Asia-Pacific CDMO Market.
China
NMPA reform pathways accelerate cross-border drug substance approvals for multinational sponsors. Suzhou and Shanghai anchor the dominant biologics manufacturing corridor with multi-thousand-liter stainless steel trains. Domestic CDMOs retrofit legacy distributed control systems to meet data integrity guidelines ahead of sponsor audits.
South Korea
Songdo bioclusters concentrate mammalian cell culture capacity serving oncology biologics pipelines. MFDS orphan drug incentives pull early-phase manufacturing into the region for global launch sequencing. Samsung Biologics anchors massive commercial-scale facilities that compete on batch economics.
India
PLI scheme incentives accelerate domestic fermentation capacity for insulin analogs and biosimilars. CDSCO aligns with ICH guidelines while imposing local stability testing requirements. Hyderabad and Bangalore emerge as cost-competitive alternatives to Chinese mammalian cell culture pricing.
Japan
PMDA maintains distinct pharmacopeial standards for imported biologics that shape facility qualification timelines. Kanto and Kansai regions host specialized aseptic processing capacity for combination products. Domestic sponsors prefer local manufacturing to navigate complex import release protocols.
Singapore
Biopharmaceutical sponsors based in Singapore bundle product development with manufacturing slots to compress timeline risk. The city-state's regulatory alignment with US FDA and EMA streamlines multi-region filing strategies. Tuas Biomedical Park anchors advanced therapy manufacturing infrastructure.
Asia-Pacific CDMO Market Competitive Landscape
Integrated platform operators and specialized manufacturing specialists split the market along capability depth versus geographic reach. The vendor base concentrates around three tiers: global full-service networks, regional mammalian cell culture anchors, and domestic fermentation specialists. Scale-driven capacity expansion and regulatory filing bundling represent the dominant competitive moves as sponsors consolidate vendor panels.
Among South Korea-based operators, Samsung Biologics exemplifies the scale-driven archetype through massive mammalian cell culture infrastructure. WuXi Biologics represents the integrated platform model with discovery-to-commercial capabilities spanning China and beyond. Lonza Group occupies a position as the specialized manufacturing specialist competing through microbial fermentation and advanced therapy networks.
| Leading Market Players |
|---|
| Samsung Biologics |
| WuXi Biologics |
| Jubilant Biosys Ltd |
| Syngene International Limited |
| Thermo Fisher Scientific Inc. |
| Lonza Group |
| Catalent Inc. |
| FUJIFILM Diosynth Biotechnologies |
| Boehringer Ingelheim Group |
| Others |
Pricing and Supply Chain Analysis
Bioreactor supply clusters in South Korea's Songdo corridor and China's Suzhou-Shanghai belt concentrate upstream mammalian cell culture capacity, anchoring margin pools in long-term supply agreements for oncology biologics sponsors. This geographic concentration shapes pricing power across the Asia-Pacific CDMO Market as procurement teams negotiate locked-in capacity against spot-market alternatives.
Pricing Analysis
Configured-to-order biologics manufacturing commands a 40-60% premium over standard platform processes due to cell line engineering and custom media optimization. Contract Manufacturing operates on project-based pricing with milestone payments tied to GMP batch release, while Product Development uses full-time-equivalent billing for CMC documentation. Price differentiation hinges on MFDS/NMPA dual-certification status and single-use versus stainless steel bioreactor technology. Cost compression in clinical-scale batches is intensifying because jet fuel volatility and constrained cold-chain container availability squeeze logistics margins. Generic drug producers represent the most price-sensitive demand tier, while oncology originators absorb premium pricing for expedited regulatory filing support.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk planning for drug substance shipments, prompting sponsor qualification of alternate manufacturing sites. Raw material dependencies center on Chinese-sourced cell culture media, South Korean-produced single-use bioreactor bags, and Indian-manufactured fermentation feedstocks. Single-source vulnerability concentrates in mammalian cell culture capacity, where Samsung Biologics and WuXi Biologics anchor multi-thousand-liter trains that lack immediate substitutes. Distribution runs through temperature-controlled air freight corridors linking Shanghai and Incheon to European and North American fill-finish networks, with sea freight emerging for stable biosimilar bulk shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the Asia-Pacific CDMO Market creates entry niches as sponsor procurement teams consolidate vendor panels from fifteen-plus suppliers to three to five strategic partners with integrated discovery-to-commercial platforms.
For Market Incumbents: Pre-empt sponsor defection by locking in multi-year master service agreements with embedded capacity reservation clauses before Phase III readouts. Add microbial fermentation capacity in India under PLI scheme incentives to diversify beyond mammalian cell culture margin pressure. Backward integration into cell culture media production reduces raw material cost volatility from Chinese suppliers. For New Entrants and Emerging Players: Southeast Asia greenfield sites in Vietnam and Indonesia represent the most penetrable entry point, lacking commercial-scale biologics capacity despite rising sponsor interest. Continuous processing technology with perfusion bioreactors enables smaller-footprint facilities in tier-two cities without sacrificing batch economics. A go-to-market angle bundling MFDS orphan drug filing support with early-phase manufacturing slots attracts rare disease biotech sponsors seeking global launch sequencing advantages. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap CDMOs with existing GMP facilities in regulatory alignment zones—specifically NMPA-MFDS dual-inspected sites—rather than greenfield construction plays. Long-term viability across the analysis window favors operators with outcome-tied master service agreements displacing transactional fee-for-service relationships. The signal to watch is sponsor procurement team consolidation velocity, measured by vendor panel reduction announcements and strategic partnership press releases.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | NMPA reform protocols compress cross-border drug substance approval timelines for multinational sponsors. |
| Manufacturing Scale-Up | Multi-thousand-liter stainless steel bioreactor trains anchor long-term supply agreements for oncology monoclonal antibodies. |
| Backward Integration | In-house cell culture media production insulates margin from Chinese raw material cost volatility. |
| Geographic Expansion | Vietnam and Indonesia greenfield sites capture first-mover advantage before regional infrastructure matures. |
| Platform Integration | Discovery-to-commercial bundling displaces transactional relationships with outcome-tied master service agreements. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, CDMO procurement managers, and biologics manufacturing heads and refined through secondary validation. Primary fieldwork combined structured interviews with sponsor-side decision-makers and facility qualification specialists across South Korea, China, and India. Secondary sources included NMPA GMP inspection databases, MFDS orphan drug approval records, CDSCO PLI scheme beneficiary lists, and customs trade data on biologics drug substance shipments. Bottom-up capacity utilization models were triangulated against top-down sponsor outsourcing spend estimates.
Demand-supply balance dynamics across mammalian cell culture, microbial fermentation, and advanced therapy manufacturing segments anchored the analytical framework. Segmentation dimensions modeled included service type, end user archetype, technology modality, therapeutic application, and regional regulatory cluster. CAGRs were derived from capacity expansion announcements, sponsor pipeline progression rates, and long-term supply agreement disclosure patterns. Forecast inputs incorporated PLI scheme incentive trajectories, NMPA data integrity guideline implementation timelines, and MFDS orphan drug incentive uptake curves.
Stress conditions across jet fuel price bands, cold-chain container availability scenarios, and geopolitical friction indices were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sponsor vendor consolidation velocity and regulatory mutual recognition protocol adoption rates. Pandemic-scale health events, abrupt trade policy shifts, or sustained skilled technician scarcity could materially revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Radiosynthesis Equipment Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market