
 Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market | 2026-2036
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market Insights
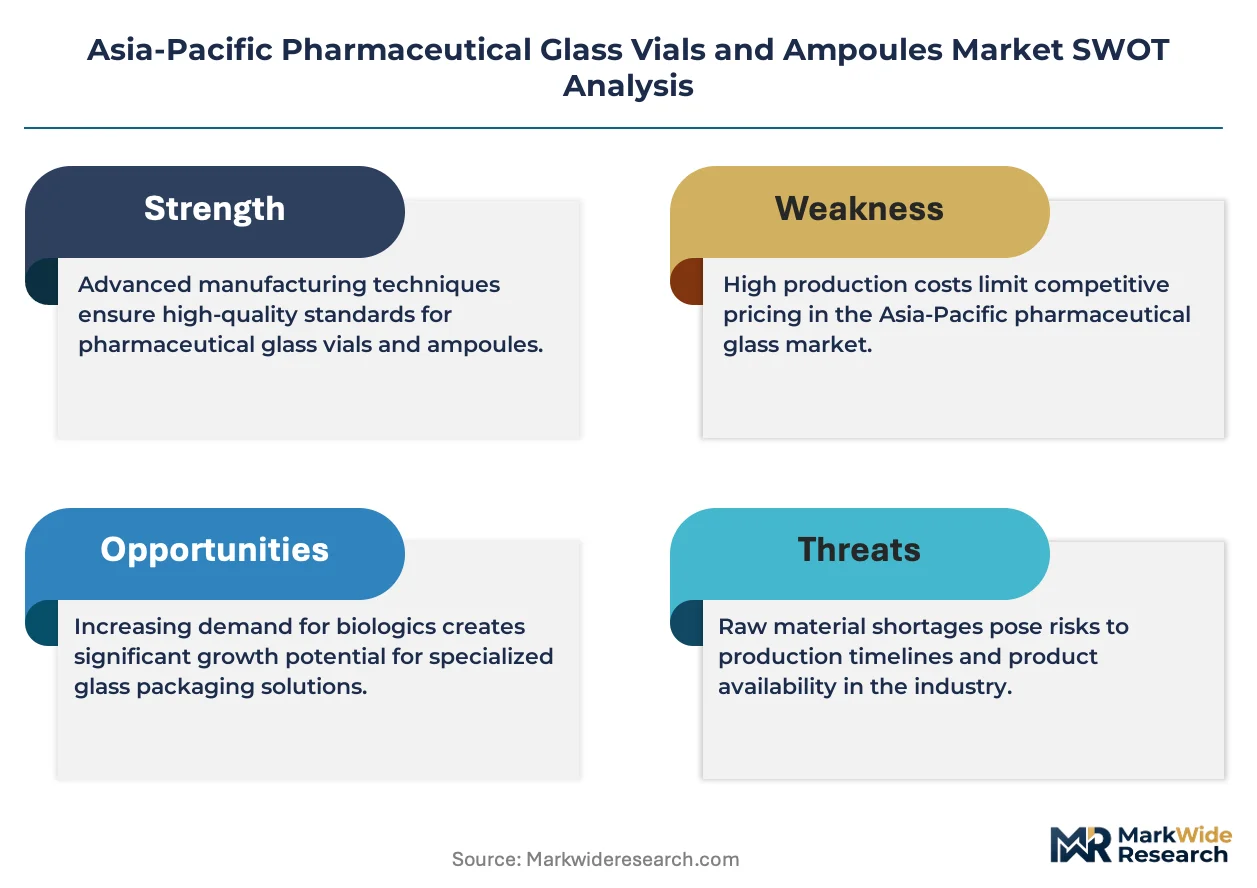
Skilled glass-forming technician availability is collapsing across Southeast Asian manufacturing zones, forcing producers to automate or relocate. Gerresheimer AG leverages its Borosilicate expertise to sustain high-purity output for biologics clients. Shandong Pharmaceutical Glass Co., Ltd. anchors Chinese domestic supply through backward integration into tubular glass production. SGD Pharma differentiates via its Type I molded vial specialization for sensitive parenterals.
Pharmaceutical glass vials and ampoules are sealed containers manufactured from borosilicate or soda-lime glass, typically meeting hydrolytic resistance Class I or II under pharmacopeial testing to prevent ion leaching into parenteral solutions. Their primary purpose is to maintain sterility, chemical stability, and dimensional precision for injectable drugs, vaccines, and diagnostic reagents across cold-chain and ambient distribution. Borosilicate glass commands premium positioning due to superior thermal shock resistance and low extractable profiles, while plastic and composite alternatives carve share in single-use diagnostic applications. Vaccines and biologics applications attract the fastest capacity additions, though injectables retains the largest absolute volume base across the region.
China's NMPA enforces GB standards harmonized with pharmacopeial hydrolytic resistance classifications, while India's CDSCO mandates compliance with Indian Pharmacopoeia Type I specifications for all parenteral packaging. Japan's PMDA applies JIS quality benchmarks that effectively filter lower-grade imports from regional competition. Stakeholders must monitor how tightening extractables-and-leachables protocols across these three regulatory jurisdictions reshape qualification timelines and supplier eligibility.
Market Dynamics
China's NMPA tightened pharmacopeial glass standards for injectables, forcing supply chain requalification across the region and compressing supplier eligibility timelines. This regulatory pressure converges with collapsing technician availability in Southeast Asian manufacturing zones to accelerate automation adoption.
Growth Catalysts
- Biologics manufacturing expansion:Vaccine production corridors in India attract dedicated vial capacity additions as CDSCO mandates Indian Pharmacopoeia Type I specifications for all parenteral packaging, hardening demand for hydrolytic-resistant containers.
- GB standards harmonization:China's NMPA enforcement of pharmacopeial hydrolytic resistance classifications filters substandard imports and elevates domestic borosilicate output quality thresholds.
- Cold-chain infrastructure buildout:Thermal shock-resistant borosilicate glass captures preference across ambient and refrigerated distribution networks as biologics volume accelerates.
Market Restraints
- Borosilicate feedstock concentration:Tubular glass production concentrates among limited Asian suppliers, exposing converters to input bottlenecks during demand spikes.
- Plastic substitution in diagnostics:Single-use polymer containers displace glass in point-of-care testing applications where extractables profiles matter less than unit cost.
- Extractables-and-leachables protocol fragmentation:Divergent qualification timelines across China's NMPA, India's CDSCO, and Japan's PMDA inflate compliance overhead for multi-jurisdictional suppliers.
Strategic Opportunities
- Indonesia's underpenetrated vaccine fill-finish capacity:Domestic glass sourcing gaps create openings for qualified Type I molded vial suppliers as the country expands immunization self-sufficiency.
- SGD Pharma's specialization model:Type I molded vial expertise for sensitive parenterals demonstrates how differentiation around hydrolytic performance captures premium positioning.
- Automated forming technology convergence:Robotics integration with borosilicate processing addresses technician scarcity while tightening dimensional precision for biologics clients.
Industry Challenges
- Glass-forming technician attrition:Manual skill pools in Thailand and Vietnam manufacturing zones shrink faster than training pipelines replenish, forcing emergency automation investments.
- Qualification timeline compression:Tightened extractables protocols across three regulatory jurisdictions simultaneously extend approval cycles while customers demand faster supplier onboarding.
- Legacy furnace reconfiguration:Converting soda-lime capacity to borosilicate output requires capital-intensive refractory and thermal control upgrades with extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market |
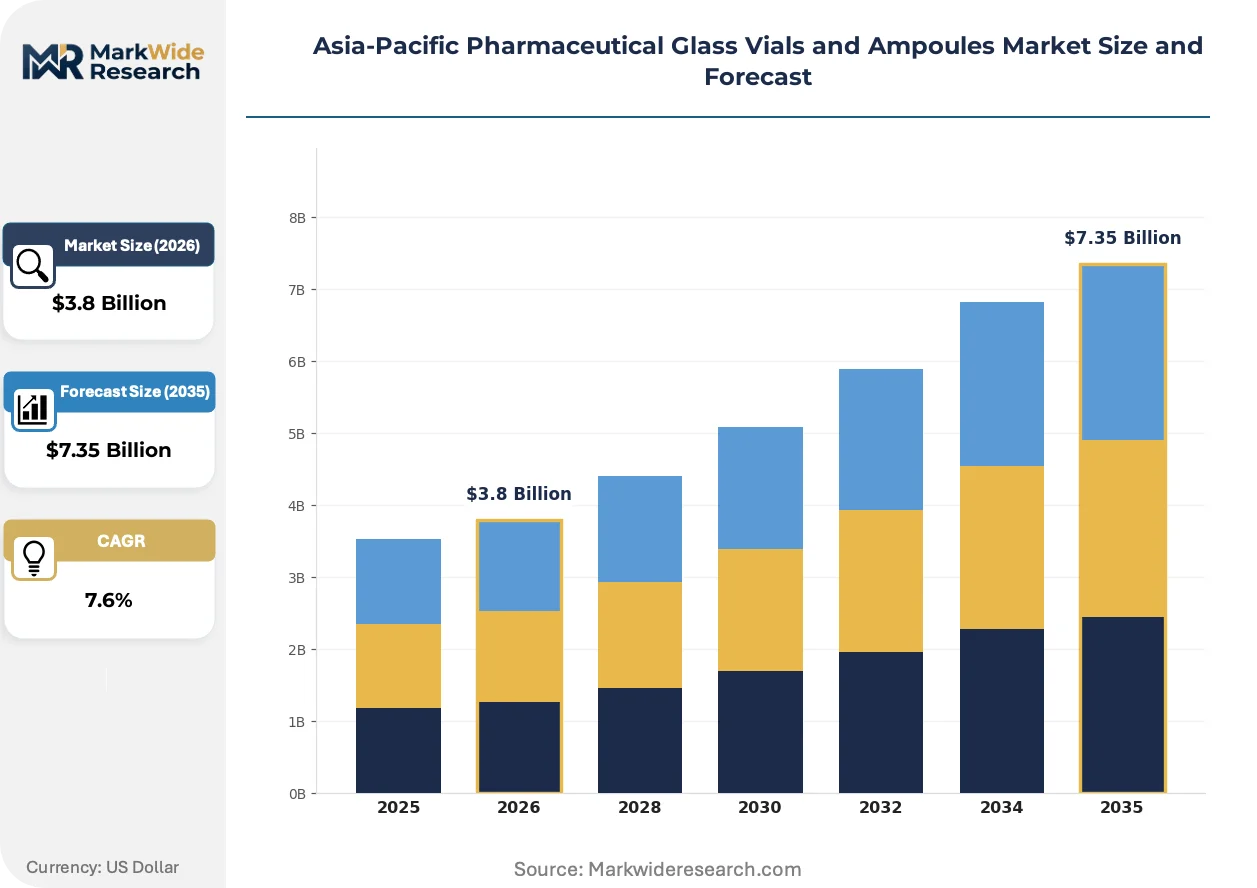
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Pre-filled Syringes, Cartridges Material: Borosilicate Glass, Soda-lime Glass, Plastic, Composites End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Labs, Hospitals Application: Vaccines, Biologics, Injectables, Diagnostics |
| Companies Covered | Gerresheimer AG, Schott AG, SGD Pharma, Shandong Pharmaceutical Glass Co., Ltd., Stevanato Group, Shiotani Glass Co., Ltd., DWK Life Sciences GmbH, Cangzhou Four Stars Glass Co., Ltd., Kapoor Glass India Pvt Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market Trends and Innovations
Automation is decomposing traditional glass-forming labor models across Asia-Pacific manufacturing zones. Three interconnected developments reshape competitive positioning: robotic forming systems, regulatory protocol convergence, and procurement centralization among biologics manufacturers.
Robotic glass-forming systems are decomposing the artisan-dependent production model that dominated Southeast Asian vial manufacturing. Biologics manufacturers in India and China now specify automated lines for new supplier qualifications, compressing the viable vendor pool to capitalized players. This technology shift elevates dimensional precision consistency while collapsing the cost advantage of manual operations.
Japan's PMDA applies JIS quality benchmarks that effectively filter lower-grade imports from regional competition. The industrial consequence is accelerated supplier consolidation as smaller converters abandon Japan-facing qualifications. High-purity parenteral applications absorb the strictest enforcement, driving domestic Japanese glassmakers to expand borosilicate capacity rather than source externally.
Biologics procurement is consolidating around qualified supplier panels with demonstrated extractables control. Multi-national vaccine manufacturers now mandate single-source accountability for vial-to-fill integration, displacing fragmented multi-vendor arrangements. This concentration is most visible in India's vaccine production corridors where CDSCO compliance documentation has become a non-negotiable gate for contract awards.
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market Segmentation
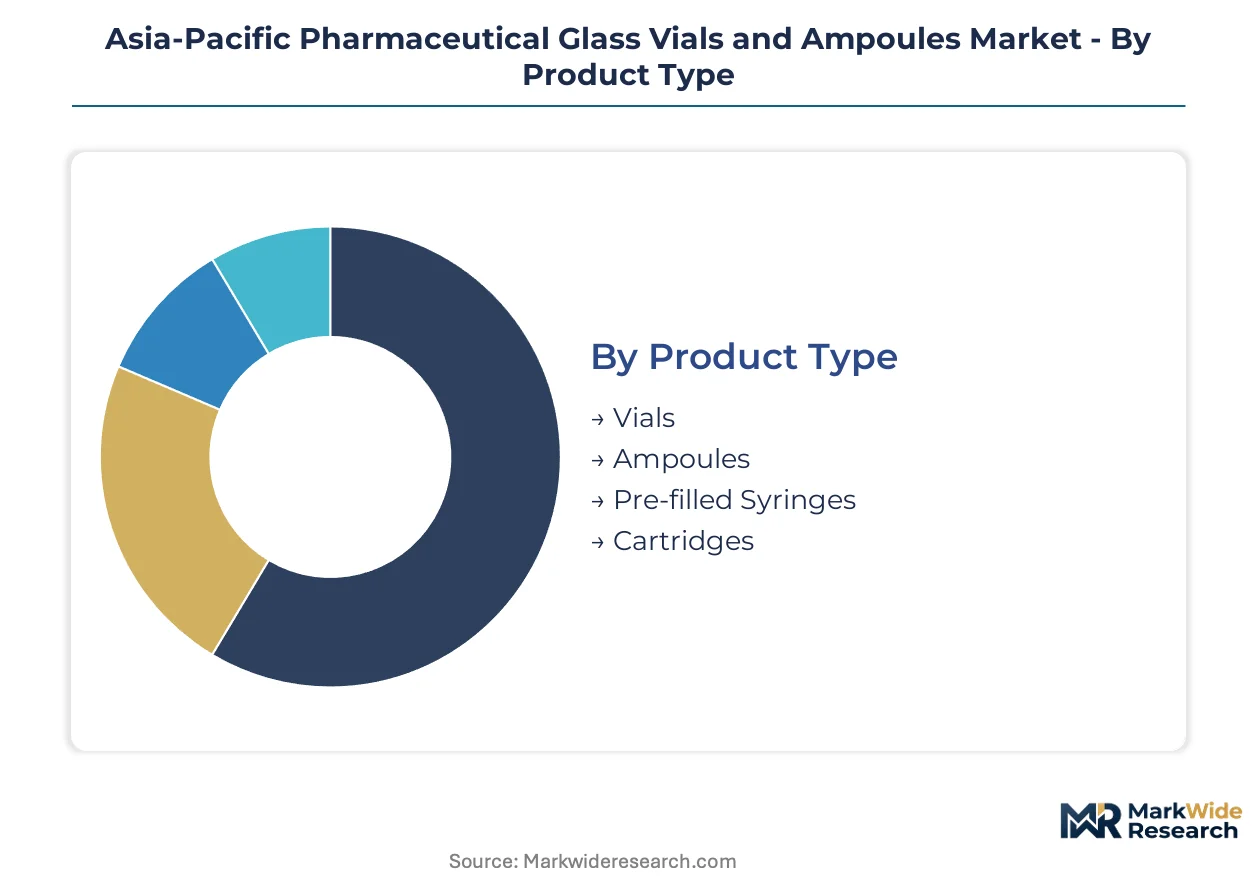
Segmentation in pharmaceutical glass packaging reveals how regulatory stringency and therapeutic application reshape procurement priorities. Material specifications and end-user requirements fragment supplier qualification pathways across the Asia-Pacific region.
Product Type:
NMPA, CDSCO, and PMDA each impose distinct dimensional tolerances and hydrolytic resistance testing protocols that favor specific container geometries.
- Vials:Multi-dose borosilicate containers dominate vaccine fill-finish operations across India and China. CDSCO mandates Indian Pharmacopoeia Type I compliance for all parenteral vials entering government immunization programs, hardening specification requirements.
- Ampoules:Single-use sealed glass units serve lyophilized biologics where sterility assurance demands absolute seal integrity. Japan's PMDA applies JIS quality benchmarks that filter lower-grade ampoule imports, accelerating domestic sourcing preferences.
- Pre-filled Syringes:Integrated drug-container combinations reduce medication errors in hospital settings.
- Cartridges:Pen-injector compatible glass reservoirs target diabetes and hormone therapy markets.
Established volume favors vials; emerging adoption favors pre-filled syringes.
Material:
Cost tiers separate premium borosilicate from standard soda-lime offerings, with plastic and composites occupying diagnostic niches.
- Borosilicate Glass:Superior thermal shock resistance and minimal ion leaching command premium positioning for biologics cold-chain distribution. China's NMPA enforcement of GB standards harmonized with pharmacopeial hydrolytic resistance classifications elevates domestic quality thresholds.
- Soda-lime Glass:Lower-cost alternative for ambient-stable injectables where hydrolytic Class II specifications suffice. Southeast Asian manufacturers retain soda-lime capacity for cost-sensitive generic markets despite tightening customer specifications.
- Plastic:Polymer containers displace glass in point-of-care diagnostics where extractables profiles matter less than unit economics.
- Composites:Multi-layer barrier structures target oxygen-sensitive parenterals.
Premium procurement concentrates in borosilicate; cost-optimized tenders favor soda-lime.
End User:
Customer type determines order scale, qualification documentation burden, and integration depth with fill-finish operations.
- Pharmaceutical Companies:Integrated drug manufacturers mandate single-source accountability for vial-to-fill integration, displacing fragmented multi-vendor arrangements. Multi-national vaccine producers in India's production corridors now require CDSCO compliance documentation as a non-negotiable contract gate.
- Contract Manufacturing Organizations:Third-party fill-finish operators demand flexible batch sizing and rapid format changeover capabilities. CMO procurement panels favor suppliers with demonstrated extractables control across multiple regulatory jurisdictions.
- Research Labs:Small-volume, high-SKU requirements characterize preclinical and clinical trial material sourcing.
- Hospitals:Direct institutional procurement focuses on ready-to-administer formats with minimal compounding steps.
Consolidated demand flows to pharmaceutical companies; fragmented volumes characterize research labs.
Application:
Application-specific performance requirements stratify material selection and regulatory qualification intensity.
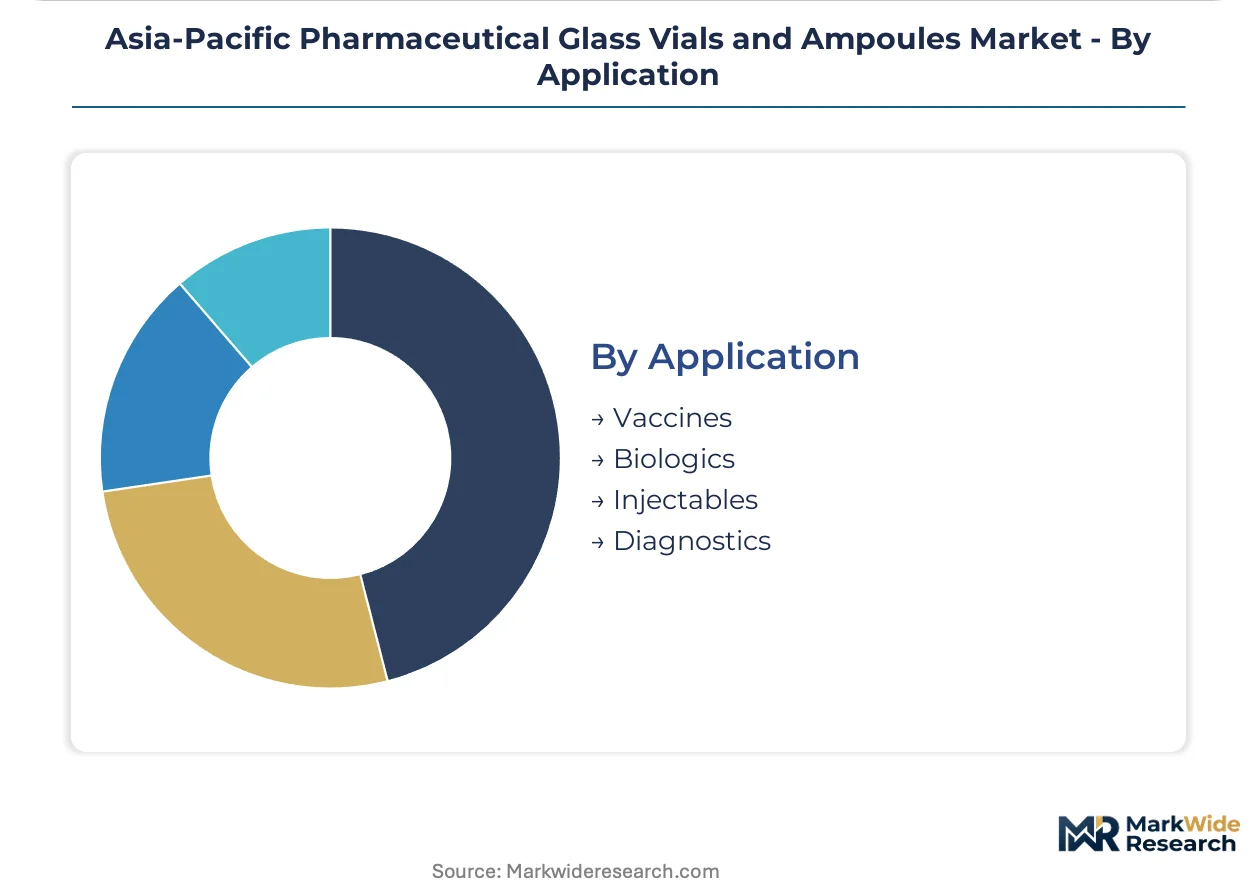
- Vaccines:Temperature excursion sensitivity drives borosilicate preference across ambient and refrigerated distribution networks. India's vaccine production corridors attract dedicated vial capacity additions as immunization self-sufficiency programs expand.
- Biologics:Protein-based therapeutics demand the lowest extractable profiles, filtering supplier pools to borosilicate specialists with automated forming lines. Biologics manufacturers in India and China now specify robotic production systems for new supplier qualifications.
- Injectables:Generic small-molecule parenterals retain the largest absolute volume base across the region.
- Diagnostics:Reagent containment tolerates wider material variance, opening substitution opportunities.
Injectables sustain volume leadership; biologics climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan and Australia, where PMDA-enforced JIS standards and premium biologics procurement filter lower-grade imports. Southeast Asian manufacturing zones compete on unit economics but surrender margin to automated specialists in North Asia.
China
Domestic borosilicate output quality thresholds rise as NMPA enforces GB standards harmonized with pharmacopeial hydrolytic resistance classifications. Tubular glass production concentrates in Shandong province, where backward-integrated furnaces supply vaccine fill-finish corridors in Jiangsu and Zhejiang.
India
CDSCO mandates Indian Pharmacopoeia Type I specifications for all parenteral packaging entering government immunization programs. Vaccine production corridors in Pune and Hyderabad attract dedicated vial capacity additions as immunization self-sufficiency programs expand.
Japan
PMDA applies JIS quality benchmarks that effectively filter lower-grade imports from regional competition. Domestic glassmakers in Osaka and Kanagawa prefectures expand borosilicate capacity rather than source externally for high-purity parenteral applications.
Indonesia
Domestic glass sourcing gaps create openings for qualified Type I molded vial suppliers as the country expands immunization self-sufficiency. Vaccine fill-finish capacity in Java remains underpenetrated by local container manufacturers.
Vietnam
Manual glass-forming skill pools in manufacturing zones near Ho Chi Minh City shrink faster than training pipelines replenish. Producers face emergency automation investments or relocation to maintain qualification for export-facing pharmaceutical contracts.
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific pharmaceutical glass vials and ampoules market. German and Japanese specialists command premium positioning through borosilicate expertise and automated forming systems, while Chinese and Indian converters compete on scale and backward-integrated feedstock control. Three archetypes dominate: integrated borosilicate specialists, regional soda-lime volume players, and automated precision suppliers. Competitive moves concentrate on furnace reconfiguration for borosilicate conversion and robotic forming line deployment to offset technician attrition.
Among European-headquartered specialists, Gerresheimer AG and SGD Pharma occupy positions at the premium tier, representing technology-led archetypes with demonstrated extractables control. Shandong Pharmaceutical Glass Co., Ltd. anchors the integrated domestic supplier archetype in China through captive tubular glass production. These three exemplify how qualification depth and automation intensity separate viable suppliers from those exiting the market under regulatory compression.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| SGD Pharma |
| Shandong Pharmaceutical Glass Co., Ltd. |
| Stevanato Group |
| Shiotani Glass Co., Ltd. |
| DWK Life Sciences GmbH |
| Cangzhou Four Stars Glass Co., Ltd. |
| Kapoor Glass India Pvt Ltd. |
| Others |
Pricing and Supply Chain Analysis
GB standards harmonization with pharmacopeial hydrolytic resistance classifications gates supplier eligibility while simultaneously stratifying price tiers across the Asia-Pacific pharmaceutical glass vials and ampoules market. NMPA enforcement filters substandard imports, compressing the qualified supplier pool and elevating premium positioning for borosilicate specialists with demonstrated extractables control.
Pricing Analysis
Japan and Australia command 40-60% premiums over Southeast Asian manufacturing zones for equivalent borosilicate vial specifications. Three-tier pricing structure across premium, standard, and economy levels separates automated Type I molded vial output from manual soda-lime production and plastic diagnostic alternatives. Cost compression in standard-grade segments intensifies as Indian vaccine procurement panels consolidate around qualified supplier panels with CDSCO documentation. Generic injectables manufacturers in Vietnam and Thailand exhibit highest price sensitivity; biologics producers in Japan and China demonstrate lowest sensitivity due to extractables liability exposure.
Supply Chain Analysis
Inventory cycles for tubular borosilicate glass feedstock extend to 8-14 weeks across converter operations, forcing pre-positioning ahead of demand spikes. Supply concentrates in China, India, and Japan, with Shandong province furnaces feeding downstream fill-finish corridors in Jiangsu and Zhejiang. Raw material dependencies center on high-purity silica sand, boron oxide, and alumina fluxes sourced from domestic Chinese deposits and Turkish boron mines. Single-source vulnerability concentrates in tubular glass production, where limited Asian suppliers expose converters to input bottlenecks. Distribution runs through direct pharmaceutical company procurement for volume contracts and CMO panel arrangements for flexible batch requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual glass-forming technician pools in Southeast Asian manufacturing zones are collapsing faster than training pipelines replenish, creating acute capability scarcity for artisan-dependent production models. This skill gap accelerates competitive separation between capitalized automation leaders and manual operations facing forced exit.
For Market Incumbents: Fortify automated forming line deployments in India and China to offset technician attrition while securing CDSCO and NMPA qualification documentation as non-negotiable contract gates. Prioritize backward integration into captive tubular glass production to insulate against feedstock concentration risk. Defensive consolidation around extractables control capabilities protects premium positioning as biologics procurement centralizes. For New Entrants and Emerging Players: Anchor in Indonesia's underpenetrated vaccine fill-finish capacity, where domestic glass sourcing gaps create white-space for qualified Type I molded vial suppliers. Target CMO procurement panels seeking flexible batch sizing with rapid format changeover capabilities. Go-to-market leverage rests on multi-jurisdictional qualification documentation spanning NMPA, CDSCO, and PMDA protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated borosilicate forming segments as robotic line deployments replace manual operations. Long-term viability favors suppliers with demonstrated extractables control and captive feedstock integration. Acquisition target archetype: mid-cap converters with partial automation and regional qualification depth. Signal to watch: furnace reconfiguration announcements converting soda-lime capacity to borosilicate output.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Forming Line Deployment | Robotic integration addresses technician scarcity while tightening dimensional precision for biologics clients. |
| Backward Integration into Tubular Glass | Captive feedstock production insulates converters from input bottlenecks during demand spikes. |
| Multi-Jurisdictional Qualification Investment | CDSCO, NMPA, and PMDA compliance documentation opens access to consolidated vaccine procurement panels. |
| Furnace Reconfiguration for Borosilicate | Refractory and thermal control upgrades elevate output quality thresholds to match GB standards enforcement. |
| Type I Molded Vial Specialization | Hydrolytic performance differentiation captures premium positioning in sensitive parenteral applications. |
Research Methodology
Operator-level perspectives from glass-forming technicians, pharmaceutical packaging procurement managers, regulatory affairs leads at CDSCO and NMPA, and CMO fill-finish directors anchored the qualitative base. Primary interviews combined with secondary validation from Indian Pharmacopoeia compliance documentation, JIS quality benchmark filings, customs trade data for borosilicate glass imports, and SEC disclosures from listed packaging manufacturers. Bottom-up capacity assessments triangulated against top-down demand modeling from vaccine production corridor expansions.
Sensitivity analysis tested forecast robustness across regulatory timeline compression scenarios and automation adoption rate variations. Segmentation dimensions modeled include material grade tier, container geometry, end-user procurement scale, and regional regulatory cluster. CAGRs derived from volume trajectory analysis intersecting with pricing tier migration patterns. Industry-specific inputs incorporated furnace reconfiguration lead times and robotic forming line deployment cycles.
Material uncertainties — regulatory protocol fragmentation across NMPA, CDSCO, and PMDA jurisdictions, technician attrition acceleration, and borosilicate feedstock supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding immunization program expansion rates and biologics manufacturing capacity additions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market