
 Pharmaceutical Storage and Material Handling Equipment Market | 2026-2036
Pharmaceutical Storage and Material Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Storage and Material Handling Equipment Market Intelligence
The direct-to-pharmacy distribution model for specialized biologics is rewriting cold chain logistics and storage requirements. This shift demands more localized, high-performance storage solutions at points of care. Thermo Fisher Scientific leverages its extensive portfolio to serve large pharmaceutical clients with end-to-end solutions. Haier Biomedical specializes in ultra-low temperature freezers, competing on energy efficiency and temperature stability. Sartorius Stedim Biotech differentiates through integrated systems that combine bioprocessing with secure storage and handling.
Pharmaceutical storage and material handling equipment encompasses systems designed to maintain product integrity and automate logistics within regulated environments. This includes units capable of holding precise temperatures, such as -80°C for certain vaccines, and robotic systems for high-throughput screening. Cold Storage Units, particularly cryogenic systems, represent a high-value segment driven by advanced therapies. Automated Storage & Retrieval Systems are seeing rapid adoption in large-scale facilities to improve inventory management and reduce human error during vaccine preservation and drug packaging.
The FDA's Current Good Manufacturing Practice (CGMP) regulations in the United States set stringent standards for equipment qualification. In Europe, compliance with CE marking and the revised EU GMP Annex 1 for sterile products dictates equipment design and operational protocols. Adherence to these frameworks is non-negotiable for market access. Vendor selection will increasingly hinge on providing equipment with integrated data logging and audit trail capabilities to meet evolving regulatory scrutiny.
Market Dynamics
The decentralization of pharmaceutical supply chains, driven by the rise of personalized medicines like cell and gene therapies, is the central force shaping the market. This shift creates demand for a new class of agile, high-performance storage and handling equipment deployable at smaller, distributed points of care, moving away from centralized bulk storage models.
Growth Catalysts
- Advanced Therapy Proliferation:The expanding pipeline of biologics, cell therapies, and mRNA vaccines requires specialized ultra-low temperature and cryogenic storage, directly stimulating demand for corresponding high-value equipment.
- Biopharma Hub Investment:Concentrated capital investment in biopharmaceutical development clusters in the United States, Ireland, and Switzerland is financing the construction of new manufacturing facilities and the modernization of existing logistics infrastructure.
- Data Integrity Mandates:Regulatory pressure for enhanced data logging and audit trails, as stipulated by frameworks like FDA's CGMP, compels manufacturers to upgrade to equipment with integrated digital monitoring capabilities.
Market Restraints
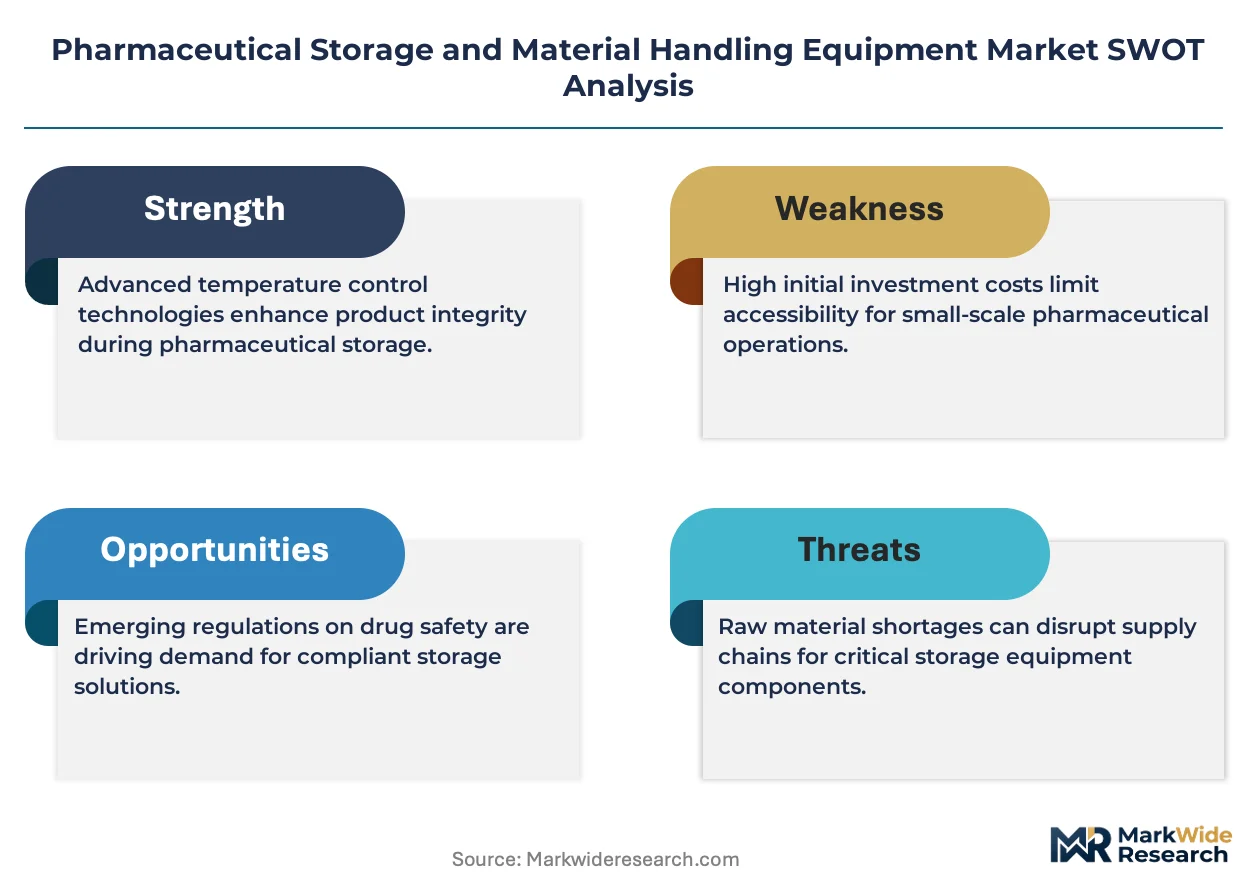
- High Capital Outlay:The significant upfront investment required for Automated Storage & Retrieval Systems and cryogenic freezers acts as a barrier to adoption for smaller research laboratories and contract manufacturing organizations.
- Qualification and Validation Timelines:Stringent and lengthy equipment qualification processes mandated by regulators like the EMA and FDA delay the deployment of new systems and increase implementation costs for end-users.
- Energy Cost and Consumption:Large-scale deployments of ultra-low temperature freezers present substantial operational cost challenges related to high energy consumption, particularly in regions with volatile electricity prices.
Strategic Opportunities
- Modular Point-of-Care Solutions:Developing smaller, modular, and validated cold storage units can capture demand from the growing number of clinical trial sites, specialty pharmacies, and outpatient treatment centers.
- Integrated Software and Analytics:Offering subscription-based software services for fleet management, predictive maintenance, and regulatory compliance reporting creates a recurring revenue stream beyond the initial hardware sale.
- Emerging Market Infrastructure Buildout:Pharmaceutical manufacturing capacity expansion in countries like India and South Korea presents a significant opportunity for equipment vendors as these regions build out their GMP-compliant infrastructure.
Industry Challenges
- Skilled Technician Scarcity:A shortage of technicians with the dual expertise required to service and maintain both sophisticated robotic automation and complex cryogenic refrigeration systems constrains operational uptime for end-users.
- System Integration Complexity:Integrating new automated handling equipment and storage units with a facility’s existing legacy enterprise resource planning and warehouse management systems remains a significant technical and operational hurdle.
- Standardization Gaps:The lack of data format standardization between equipment from different vendors complicates the creation of a unified, interoperable digital ecosystem for facility-wide monitoring and control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Storage and Material Handling Equipment Market |
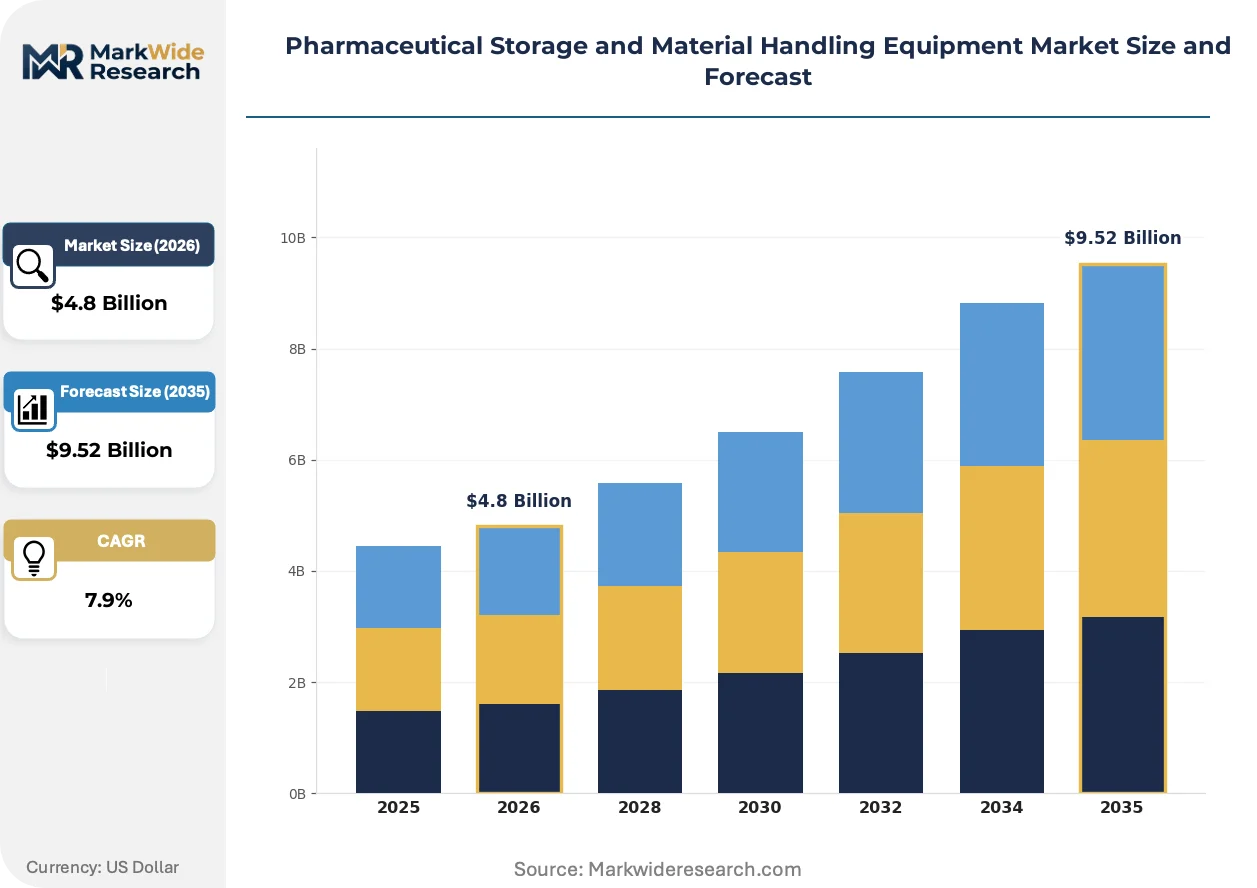
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Cold Storage Units, Automated Storage & Retrieval Systems, Pallet Jacks, Conveyor Systems, Manual Carts Storage Technology: Refrigeration, Humidity Control, Vacuum Storage, Cryogenic, Dry Storage Application: Vaccine Preservation, Drug Packaging, Inventory Management, Raw Material Storage, Finished Goods Handling End User: Biotech Firms, Clinical Research Centers, Hospital Pharmacies, Contract Manufacturing Organizations |
| Companies Covered | Haier Biomedical, Summit Appliance, Cardinal Health, Darwin Chambers, Memmert, Azenta, Philipp Kirsch, Sartorius Stedim Biotech, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Storage and Material Handling Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of automation and stringent temperature control, driven by the need to handle increasingly sensitive and high-value therapeutic products with zero tolerance for error. This is pushing equipment design towards integrated, data-rich systems that can prove compliance and ensure product integrity.
Robotic systems designed for aseptic environments are a key product evolution. These systems perform tasks like vial handling and plate transfers within sterile isolators. Major biopharmaceutical companies and contract manufacturers are adopting these robots to reduce human intervention and minimize contamination risks in sterile manufacturing. This technology is hybridizing discrete handling and environmental control functions into unified platforms that improve process security.
The revised EU GMP Annex 1 presents a significant regulatory driver. This regulation heightens the requirements for contamination control strategies in the manufacturing of sterile medicinal products. It directly impacts equipment design, forcing vendors to incorporate features that support more rigorous cleaning, sterilization, and environmental monitoring. Aseptic processing and robotic handling equipment segments are most affected, needing to provide enhanced validation data to clients operating in the European Union.
A notable behavioral shift is the move from large, fixed capital equipment purchases to more flexible, scalable deployment models. This change disrupts the traditional sales cycle for large-scale ASRS and freezer farms, favoring vendors who offer modular or containerized solutions. This trend is most visible in the clinical trial supply sector, where sponsors need to rapidly deploy and decommission storage capacity at sites across different geographies.
Pharmaceutical Storage and Material Handling Equipment Market Segmentation
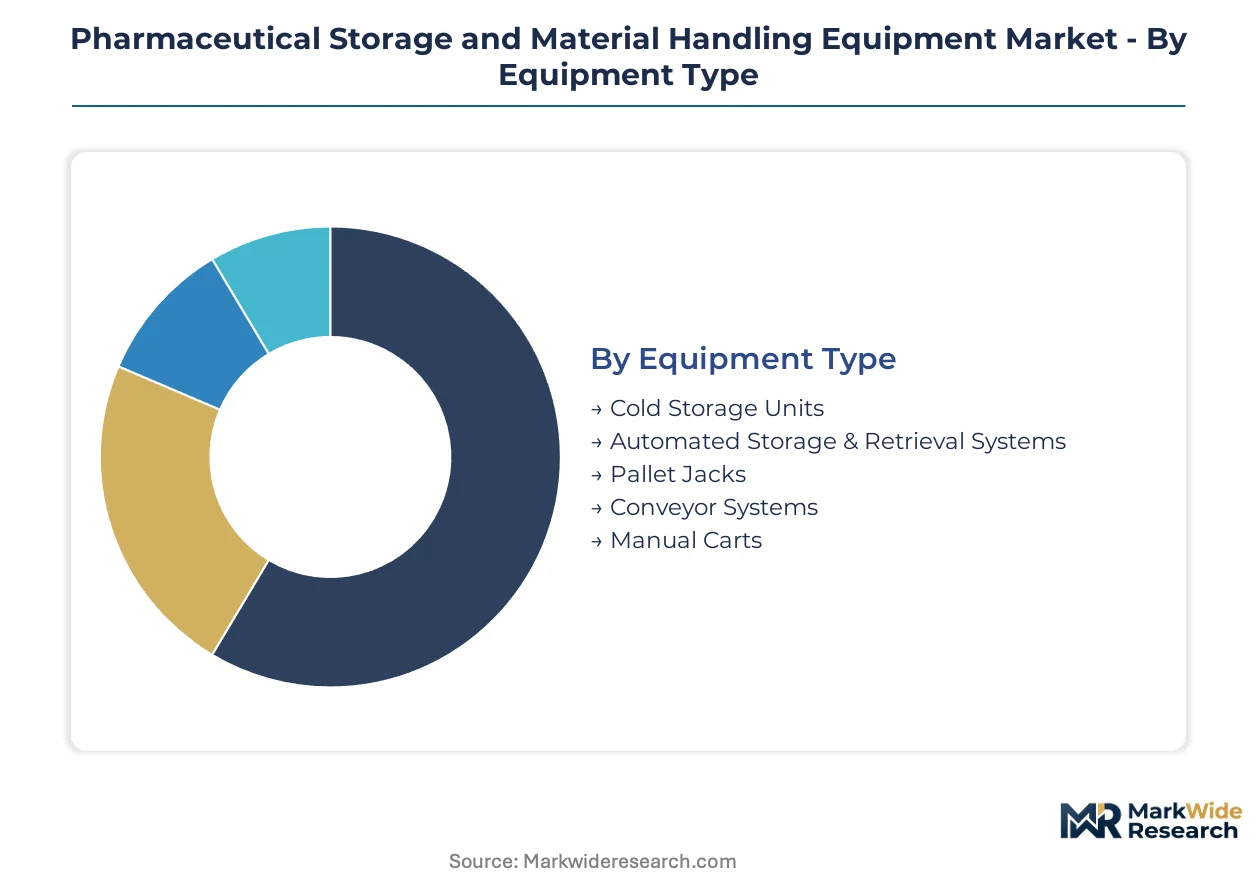
The pharmaceutical storage and material handling equipment market segments reflect the diverse requirements for maintaining product integrity and optimizing logistics across the drug development and distribution lifecycle. Understanding these distinctions allows vendors to tailor solutions to specific operational needs and regulatory mandates within the biopharmaceutical industry.
Equipment Type:
The equipment dimension outlines the physical systems deployed for pharmaceutical handling and preservation, ranging from temperature-controlled units to automated logistics machinery.
- Cold Storage Units:These systems encompass a range of temperature-controlled environments, including refrigerators, freezers, and ultra-low temperature freezers capable of reaching -80°C. Demand concentrates in biopharmaceutical development hubs in the United States and Ireland, driven by the need to preserve sensitive biologics and cell therapies.
- Automated Storage & Retrieval Systems:Robotic systems designed for high-density storage and rapid retrieval of pharmaceutical products, minimizing human intervention and maximizing space efficiency. Adoption is accelerating in large-scale manufacturing facilities and distribution centers to improve inventory accuracy and vaccine preservation protocols.
- Pallet Jacks:Manual or powered equipment used for lifting and moving pallets within warehouses and distribution centers.
- Conveyor Systems:Mechanical systems for moving materials, including packaged drugs and raw ingredients, along a fixed path within a facility.
- Manual Carts:Non-powered, wheeled platforms used for transporting smaller quantities of materials or samples over short distances.
Cold Storage Units hold significant installed capacity. Automated Storage & Retrieval Systems are rotating up the share rankings.
Storage Technology:
Storage technology categorizations highlight the specific environmental controls and preservation methods applied to pharmaceutical products.
- Cryogenic:Storage systems utilizing liquid nitrogen or mechanical freezers to achieve ultra-low temperatures, typically below -150°C, essential for long-term preservation of cell therapies and advanced biologics. This technology is critical for new biopharmaceutical facilities in Switzerland and the United States, supporting the expanding pipeline of personalized medicines.
- Refrigeration:Systems maintaining temperatures typically between 2°C and 8°C, widely used for vaccines, insulin, and various pharmaceutical intermediates requiring cold chain integrity. Demand remains consistently high across hospital pharmacies and contract manufacturing organizations for routine drug storage.
- Humidity Control:Equipment designed to maintain specific moisture levels, preventing degradation of hygroscopic pharmaceutical compounds and ensuring product stability.
- Vacuum Storage:Systems that remove air to create a vacuum, protecting oxygen-sensitive materials and preventing contamination.
- Dry Storage:Ambient temperature storage solutions for non-temperature-sensitive pharmaceutical raw materials, excipients, and finished products.
Cryogenic technology represents the fastest-growing trajectory. Refrigeration technology maintains a broad market presence.
Application:
The application segment delineates where the equipment is primarily utilized within the pharmaceutical supply chain and manufacturing process.
- Vaccine Preservation:Specialized storage and handling solutions ensuring the potency and stability of vaccines, often requiring ultra-low temperature conditions. This application drives significant demand for advanced cold chain equipment, particularly with the global distribution of mRNA vaccines.
- Inventory Management:Systems and processes for tracking, organizing, and controlling pharmaceutical stock levels, minimizing waste and ensuring product availability. Large pharmaceutical manufacturers increasingly adopt automated systems for enhanced accuracy and compliance.
- Drug Packaging:Equipment used in the final stages of pharmaceutical production for packaging finished drug products into vials, syringes, blisters, or bottles.
- Raw Material Storage:Storage solutions for active pharmaceutical ingredients, excipients, and other components before they enter the manufacturing process.
- Finished Goods Handling:Logistics and storage operations for completed pharmaceutical products prior to distribution to pharmacies or healthcare providers.
Vaccine Preservation applications are expanding most quickly. Inventory Management remains a core operational requirement.
End User:
End user segmentation identifies the primary organizations deploying pharmaceutical storage and material handling equipment.
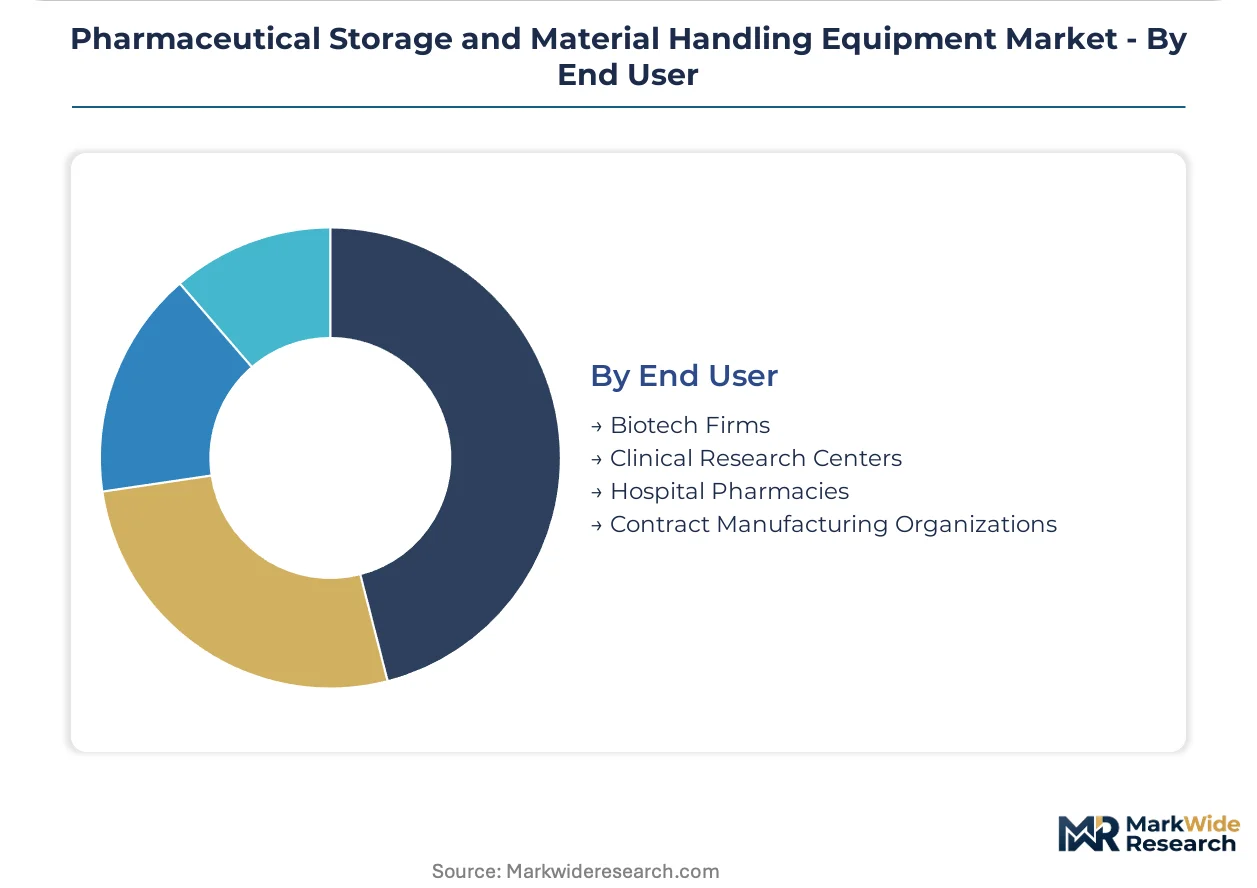
- Biotech Firms:Companies focused on developing and manufacturing biologics, cell therapies, and gene therapies, requiring highly specialized ultra-low temperature and cryogenic storage solutions. These firms, especially in established biopharma clusters, are significant investors in advanced equipment.
- Contract Manufacturing Organizations:Third-party companies providing manufacturing and packaging services for pharmaceutical clients, often investing in flexible, high-throughput storage and handling systems to serve diverse product portfolios. CMOs in Ireland and South Korea are rapidly upgrading their infrastructure.
- Clinical Research Centers:Facilities conducting clinical trials, necessitating secure and precise storage for investigational drugs and biological samples.
- Hospital Pharmacies:Pharmacies located within hospitals, responsible for storing and dispensing a wide range of medications, including those requiring specific temperature controls.
Biotech Firms are driving substantial equipment upgrades. Contract Manufacturing Organizations are gaining share in equipment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's Current Good Manufacturing Practice (CGMP) regulations in the United States anchor the pharmaceutical storage and material handling equipment market. These stringent standards influence equipment qualification and deployment across major biopharmaceutical regions. Investment concentrates in established biopharma development hubs, driving demand for advanced storage and handling solutions.
United States
The United States market for pharmaceutical storage equipment is significantly driven by the expanding pipeline of biologics and cell therapies. FDA's CGMP regulations mandate robust equipment qualification, ensuring product integrity and safety. The Boston/Cambridge biopharma cluster, a leading innovation hub, actively adopts advanced cryogenic storage and automated retrieval systems for sensitive therapeutics.
Germany
German pharmaceutical manufacturers require sophisticated storage solutions for sterile products, aligned with EU GMP Annex 1 requirements. CE marking compliance is also non-negotiable for market access and operational standards. Major pharmaceutical clusters in Bavaria and North Rhine-Westphalia consistently upgrade their logistics and cold chain infrastructure to support advanced drug production.
Switzerland
Switzerland's specialized biopharmaceutical sector, known for high-value precision medicines, fuels demand for ultra-low temperature and cryogenic storage. Swissmedic standards for quality and safety dictate stringent equipment performance. The Basel pharmaceutical industry, a global center for drug development, invests heavily in integrated systems combining bioprocessing with secure storage.
India
India's expanding pharmaceutical manufacturing capacity, particularly for vaccines and generics, drives significant demand for cold chain and material handling equipment. The CDSCO guidelines influence equipment design and operational protocols for drug preservation. Hyderabad and Ahmedabad pharmaceutical hubs are rapidly building out GMP-compliant infrastructure, including automated storage solutions.
South Korea
South Korea emerges as a key market due to its growing biopharmaceutical contract manufacturing organizations and advanced therapy development. MFDS regulations set high standards for drug quality and storage conditions. The Incheon Biocluster, a hub for biologics production, focuses on adopting advanced cold storage units and robotic handling systems to support its expanding operations.
Pharmaceutical Storage and Material Handling Equipment Market Key Industry Players
Integrated solution providers and specialized equipment manufacturers split the market for pharmaceutical storage and material handling equipment. The market exhibits a tiered structure, with larger players offering comprehensive portfolios and niche players focusing on specific technology segments. Companies actively pursue portfolio diversification and strategic partnerships to expand their market reach and technological capabilities.
Within the integrated solution provider tier, Thermo Fisher Scientific and Sartorius Stedim Biotech exemplify comprehensive offerings across the pharmaceutical value chain. Thermo Fisher Scientific, a global entity, provides extensive portfolios and end-to-end solutions to large pharmaceutical clients, addressing diverse storage and handling needs. Sartorius Stedim Biotech, a German-French biopharmaceutical supplier, differentiates through integrated systems that combine bioprocessing with secure storage and handling, supporting complex manufacturing workflows. Haier Biomedical, a Chinese manufacturer, anchors the specialized equipment segment. This company focuses on ultra-low temperature freezers and competes on energy efficiency and temperature stability, serving specific preservation requirements for sensitive products.
| Leading Market Players |
|---|
| Haier Biomedical |
| Summit Appliance |
| Cardinal Health |
| Darwin Chambers |
| Memmert |
| Azenta |
| Philipp Kirsch |
| Sartorius Stedim Biotech |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Regulatory qualification complexity significantly influences pricing tier spreads and shapes the pharmaceutical storage and material handling equipment supply chain. Stringent compliance requirements drive up development costs and limit the pool of qualified suppliers.
Pricing Analysis
Configured-to-order pricing for integrated storage and handling systems commands a premium over standard units. The dominant pricing model for large-scale deployments is project-based, often incorporating subscription-based software services for fleet management. Price differentiation stems from the level of customization, stringent certification requirements like CE marking, and comprehensive after-sales service. Pricing softness affects smaller contract manufacturing organizations due to their high capital outlay constraints, while large biotech firms exhibit lower price sensitivity.
Supply Chain Analysis
Upstream component sourcing for specialized refrigeration and robotic systems draws from a concentrated global base. Key manufacturing hubs for sophisticated equipment are found in Germany, the United States, and China for various sub-components like specialized compressors and precision mechanical parts. A significant supply chain risk involves single-source vulnerability for ultra-low temperature cryogenic components, particularly for advanced therapies. Distribution predominantly occurs via direct sales channels for large integrated systems and through specialized logistics providers for point-of-care solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a substitution defense challenge, as incumbents must navigate the threat of less specialized, lower-cost equipment from new entrants. Protecting market share requires continuous innovation in compliance and performance.
For Market Incumbents: Harden core competencies in integrated software and analytics to counter emerging threats from standalone solutions. Invest significantly in training specialized technicians to address the skilled technician scarcity, a critical operational bottleneck. Prioritize R&D in automation and AI-driven predictive maintenance to enhance equipment uptime and regulatory compliance. This strategy strengthens client relationships against competitive pressures.
For New Entrants and Emerging Players: Establish a beachhead in modular point-of-care solutions tailored for clinical trial sites and specialty pharmacies. Target emerging market infrastructure buildout in countries like India and South Korea with GMP-compliant, cost-effective equipment. Focus on providing validated, smaller-scale cold storage units with integrated data logging. This approach addresses unmet demand in rapidly expanding but capital-constrained segments.
For Investors and Strategic Acquirers: The market sits at a high-growth phase that favors specialized technology providers with strong regulatory compliance. Long-term viability is assured by the expanding pipeline of biologics and cell therapies, making this sector essential infrastructure. Target niche specialists in advanced cryogenic technology or integrated software-defined automation for strategic acquisitions. Watch for accelerated adoption rates of new regulatory frameworks like EU GMP Annex 1 as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Cryogenic R&D | Advances ultra-low temperature capabilities for sensitive biologics, enhancing product integrity. |
| Develop Modular Cold Storage | Captures demand from clinical trial sites and specialty pharmacies for distributed solutions. |
| Enhance Software Integration | Provides fleet management and predictive maintenance for large pharmaceutical manufacturers. |
| Expand Service Technician Training | Addresses skilled technician scarcity, ensuring operational uptime for complex robotic systems. |
| Pursue Emerging Market Partnerships | Facilitates GMP-compliant infrastructure buildout in regions like India and South Korea. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during primary research, combining in-depth interviews with secondary validation. Stakeholders included biopharma R&D heads, CMO logistics managers, regulatory compliance officers, and equipment engineers. Secondary data sources comprised FDA filings, EMA submissions, biopharma industry reports, and patent databases. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
The calibration approach integrated quantitative models with qualitative insights across the analysis window. Segmentation dimensions modeled included equipment type, storage technology, application, end user, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Key forecast inputs included the biopharmaceutical pipeline growth and new GMP-compliant facility build-out projections.
Stress conditions across regulatory shifts and energy cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding biopharma investment and technological adoption. Cross-checking against external biopharma capital expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market