
 Pharmaceutical Track and Trace Systems Market | 2026-2036
Pharmaceutical Track and Trace Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Track and Trace Systems Market Analytics
European serialization equipment producers are realigning capacity toward cloud-native verification platforms. Optel Vision leverages its Quebec-based manufacturing footprint to dominate North American hardware installations for vial and bottle serialization. Siemens AG sustains competitive positioning through its SIMATIC pharmaceutical suite, which anchors automated line integration across German and Swiss production sites. TraceLink Inc. differentiates via its network-tenancy model that controls data exchange across more than 290,000 supply chain endpoints.
Pharmaceutical track and trace systems comprise hardware, software, and services that assign unique identifiers to drug packages and verify their movement through supply chains, typically employing RFID tags, linear or 2D barcodes, or blockchain-anchored digital records at speeds exceeding 600 units per minute on high-volume packaging lines. Their primary commercial purpose is to prevent counterfeit infiltration, enable targeted recalls, and satisfy jurisdictional serialization mandates. Software and solutions segments capture the majority of recurring revenue as pharmaceutical manufacturers prioritize subscription-based compliance platforms over capital-intensive hardware purchases. RFID technology leads in high-value biologics tracking where read-range and environmental resilience justify unit cost premiums, while blockchain applications represent the fastest-expanding verification architecture for cross-border shipment authentication.
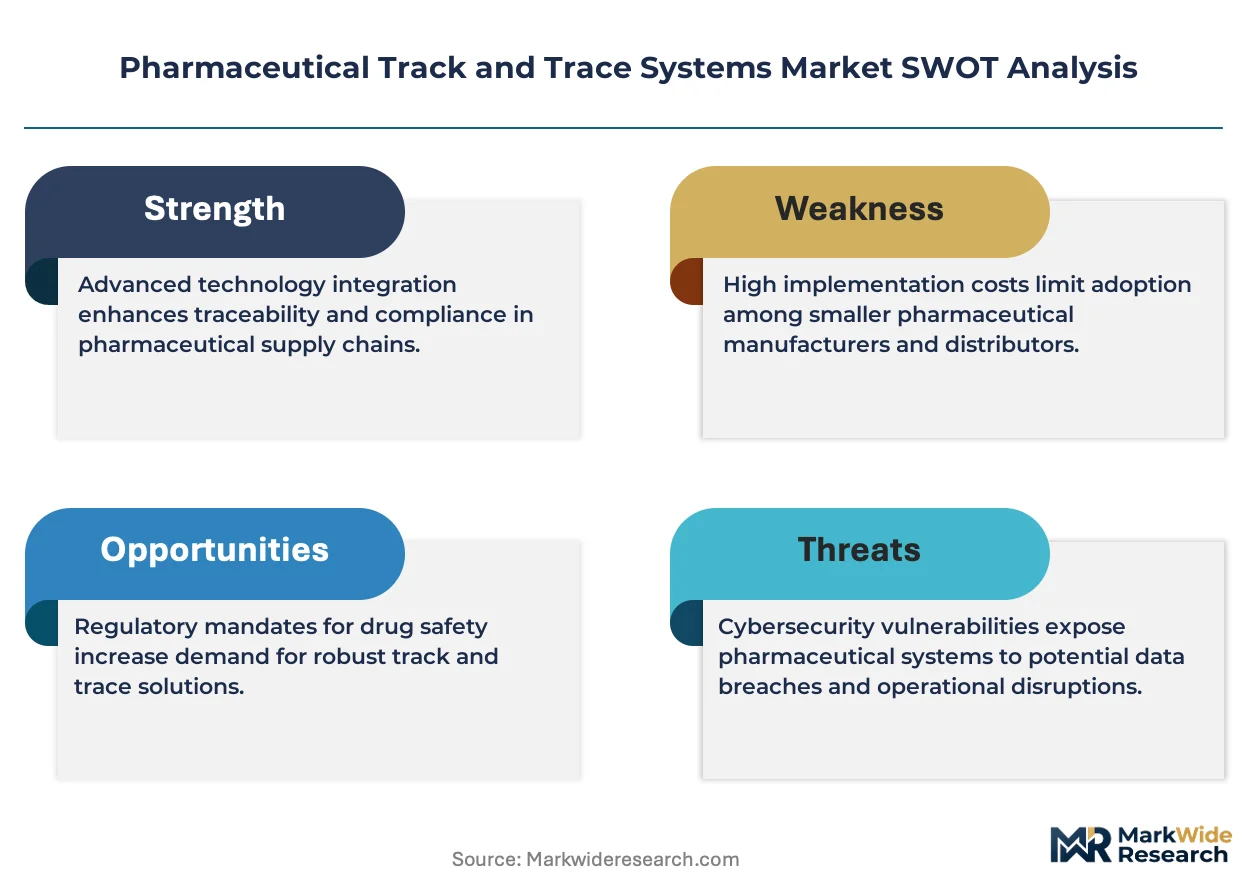
FDA's Drug Supply Chain Security Act mandates unit-level traceability, while the EU Falsified Medicines Directive enforces similar serialization standards across European Economic Area members, and India's CDSCO has tightened track and trace requirements for exported pharmaceuticals under its revised Schedule M guidelines. These frameworks collectively compel manufacturers to treat compliance infrastructure as non-discretionary operating expenditure rather than discretionary technology investment. Stakeholders must monitor emerging interoperability standards between national verification systems to anticipate integration costs and data governance obligations.
Market Dynamics
Blockchain-anchored verification architectures are compressing authentication timelines across cross-border pharmaceutical corridors, forcing incumbent serialization providers to reengineer data-exchange protocols or surrender network-tenancy positions to distributed-ledger entrants.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-level traceability mandates compel pharmaceutical manufacturers to deploy serialization infrastructure as non-discretionary operating expenditure, eliminating procurement delays.
- Biologics cold-chain expansion:Temperature-sensitive biologics require RFID-enabled environmental monitoring, creating hardware pull-through in North American manufacturing clusters.
- India CDSCO Schedule M revisions:Exported pharmaceutical track and trace requirements tighten verification standards for contract manufacturers serving regulated markets.
Market Restraints
- Cloud-native platform switching costs:Pharmaceutical manufacturers face data-migration friction when replacing legacy on-premise serialization suites with SaaS verification platforms.
- Silicon photonics component scarcity:High-speed barcode scanner production depends on specialized optical sensor supply concentrated in East Asian foundries.
- EU verification system fragmentation:National medicines verification organizations maintain non-harmonized data formats, multiplying integration complexity for pan-European distributors.
Strategic Opportunities
- German blockchain pilot zones:Federal Ministry of Health-sanctioned distributed-ledger testbeds offer first-mover positioning for pharmaceutical shipment authentication providers.
- Cell and gene therapy serialization:Personalized medicine batch sizes of one require adaptive identifier assignment systems absent from legacy packaging line architectures.
- Subscription-based compliance platforms:Recurring revenue models displace capital-intensive hardware purchases as pharmaceutical CFOs prioritize operational expenditure treatment.
Industry Challenges
- Serialization engineer scarcity:Pharmaceutical manufacturers compete for talent capable of integrating GS1 EPCIS standards with existing ERP architectures.
- Legacy line retrofit capex:High-volume packaging equipment installed before 2015 requires mechanical modification to achieve 600 units per minute serialization speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Track and Trace Systems Market |
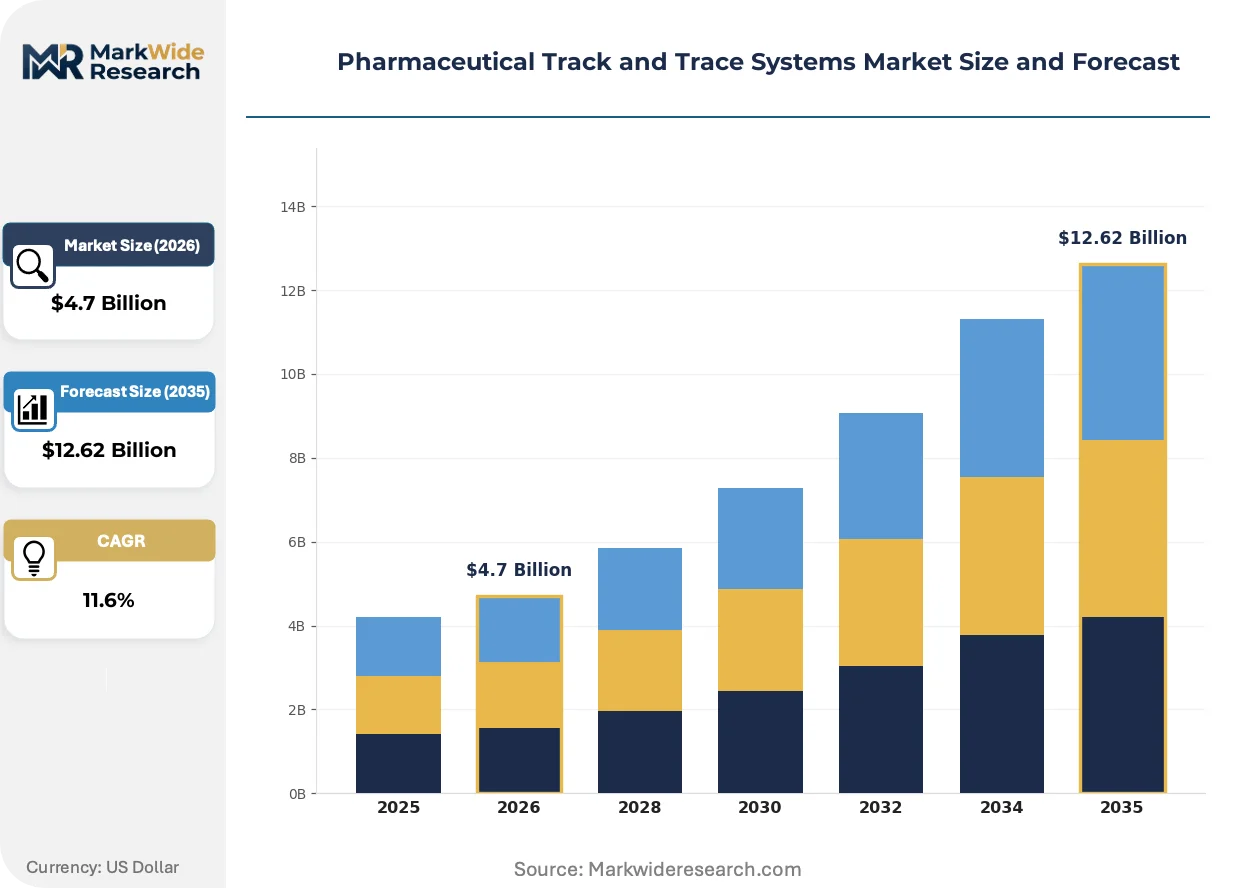
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Technology: RFID, Barcodes, QR Codes, Blockchain End User: Pharmaceutical Manufacturers, Distributors, Retail Pharmacies, Hospitals Application: Supply Chain Management, Inventory Control, Serialization, Compliance |
| Companies Covered | Optel Vision, Siemens AG, TraceLink Inc., SAP, Antares Vision, Zebra Technologies, Axway, Mettler-Toledo International, Systech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Track and Trace Systems Market Evolving Landscape
Distributed-ledger verification protocols are collapsing authentication latency from days to minutes, while cloud-native network tenancy models displace perpetual-license software economics across pharmaceutical supply chains.
Blockchain-anchored digital records is electrifying cross-border shipment authentication by creating immutable provenance trails. Indian and German customs authorities pilot interoperable ledger verification for high-value biologics exports. This architecture compresses clearance timelines and eliminates paper-based chain-of-custody documentation.
EU Falsified Medicines Directive enforcement tightens serialization requirements across European Economic Area members. National verification systems now mandate decommissioning at point-of-dispense, forcing hospital pharmacy IT upgrades. Wholesale distributors absorb integration costs to maintain access to reimbursed pharmaceutical volumes.
Buyer concentration among the ten largest pharmaceutical manufacturers now dictates serialization platform roadmaps. Mid-tier contract manufacturers adopt white-label network-tenancy solutions rather than building proprietary verification stacks. This procurement consolidation concentrates vendor influence in the United States and Switzerland.
Pharmaceutical Track and Trace Systems Market Segmentation
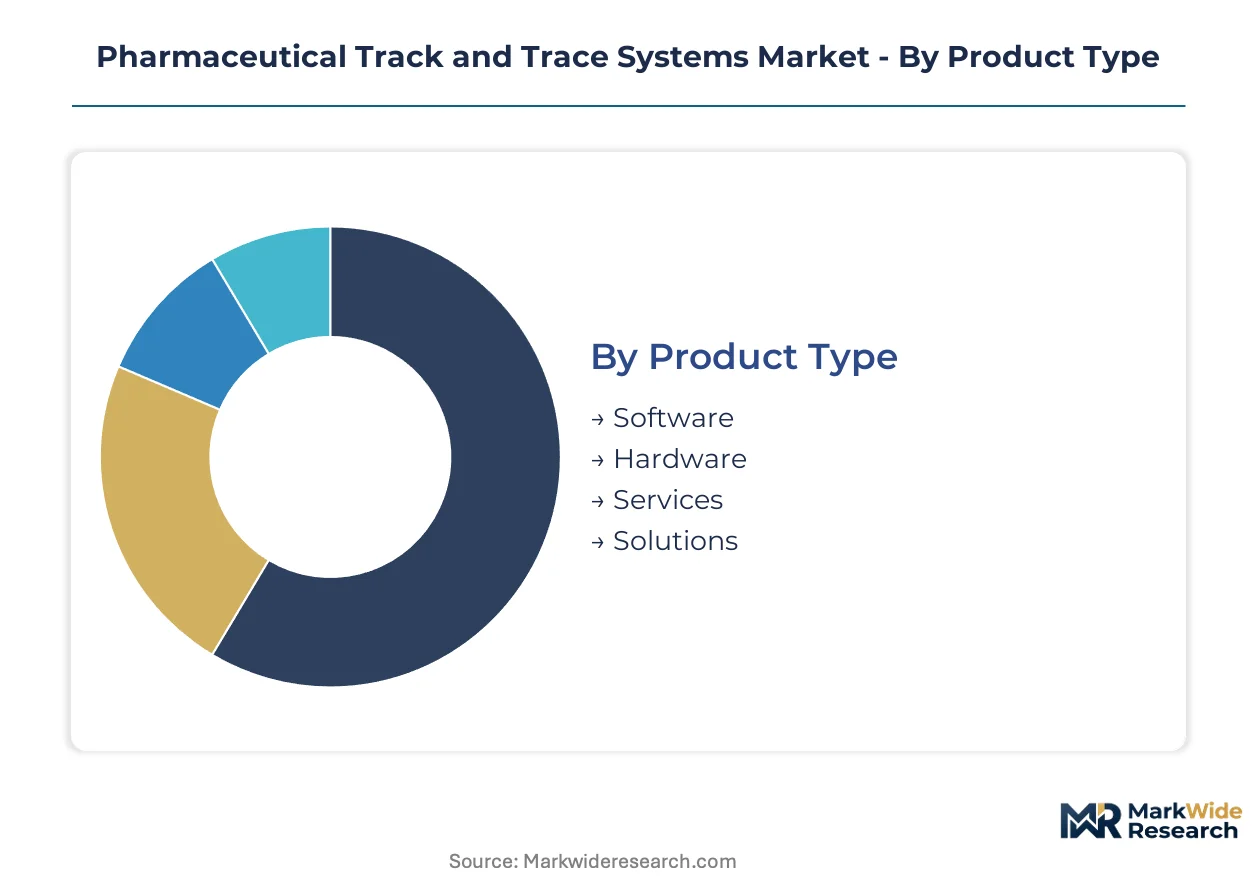
Pharmaceutical track and trace systems fragment across four critical dimensions that determine procurement priorities, integration complexity, and recurring revenue potential. Manufacturers configure solutions differently depending on whether they prioritize capital efficiency, regulatory coverage, or supply chain visibility depth.
Product Type:
Standardization dominates hardware procurement while software demands heavy customization to match legacy ERP architectures and jurisdiction-specific reporting formats.
- Software:Cloud-native verification platforms host GS1 EPCIS event repositories and manage data exchange across trading partner networks. Pharmaceutical manufacturers in the United States prioritize subscription-based deployment to convert capital expenditure into operational expenditure for FDA DSCSA compliance budgeting.
- Hardware:Line-mounted serialization equipment includes print-and-apply labelers, vision verification systems, and aggregation stations processing 600 units per minute. German packaging line integrators specify Siemens SIMATIC-compatible hardware to minimize retrofit downtime during EU FMD mandate deadlines.
- Services:Implementation consulting, validation documentation, and ongoing technical support.
- Solutions:Integrated hardware-software bundles with bundled maintenance contracts.
Leading the category by volume: Software. Growing fastest: Hardware.
Technology:
Cost tier structures segment adoption, with premium read-range capabilities commanding unit cost multiples over basic optical scanning.
- RFID:Ultra-high frequency tags enable non-line-of-sight reading across palletized biologics shipments with integrated temperature logging. Cold-chain operators in North American manufacturing clusters deploy RFID for environmental monitoring where barcode scanning fails in freezer conditions.
- Barcodes:Linear and 2D Data Matrix symbols remain the baseline for unit-level serialization under FDA and EU mandates. Indian contract manufacturers serving regulated markets standardize on barcode infrastructure to meet CDSCO Schedule M export verification requirements without RFID cost premiums.
- QR Codes:Consumer-facing authentication with smartphone-readable packaging.
- Blockchain:Distributed-ledger verification architectures creating immutable cross-border shipment records.
Highest margin concentration: RFID. Steepest expansion trajectory: Blockchain.
End User:
Application maturity varies sharply, with upstream supply chain participants operating decade-old systems while downstream dispensers face recent mandate-driven upgrade cycles.
- Pharmaceutical Manufacturers:Primary serialization obligation holders managing line-level encoding, aggregation, and verification reporting. Brand-name drug producers in Switzerland and the United States drive platform roadmap consolidation through concentrated procurement power.
- Distributors:Wholesale operations managing verification system connections to national medicine repositories. Pan-European distributors absorb integration complexity from non-harmonized data formats across German, French, and Italian verification organizations.
- Retail Pharmacies:Point-of-dispense decommissioning and authentication scanning.
- Hospitals:Inpatient pharmacy IT upgrades for unit-level tracking.
Deepest infrastructure investment: Pharmaceutical Manufacturers. Fastest compliance-driven upgrade cycle: Hospitals.
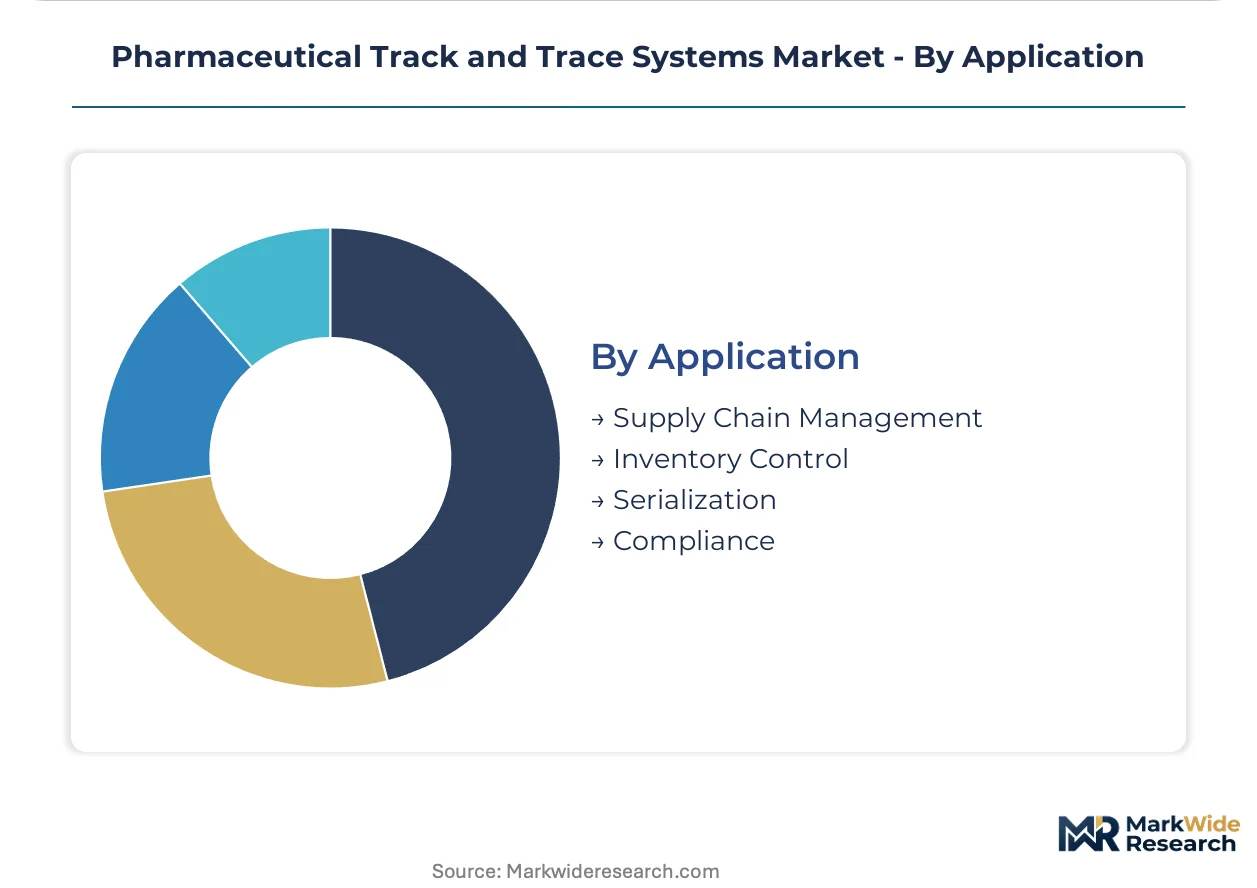
Application:
Supply concentration shapes competitive dynamics, with compliance applications commanding premium pricing due to non-discretionary procurement while operational efficiency tools face budget scrutiny.
- Supply Chain Management:End-to-end visibility platforms tracking pharmaceutical movement from manufacturing through dispensing. Network-tenancy models like TraceLink's control data exchange across more than 290,000 endpoints, consolidating vendor influence.
- Serialization:Unit-level identifier assignment, verification, and repository reporting to satisfy jurisdictional mandates. FDA DSCSA and EU FMD enforcement eliminate procurement delays by treating infrastructure as mandatory operating expenditure.
- Inventory Control:Warehouse management and stock rotation optimization.
- Compliance:Regulatory reporting, audit documentation, and mandate-specific verification workflows.
Largest addressable spend: Supply Chain Management. Tightest regulatory enforcement: Serialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon photonics foundries in East Asia supply optical sensors for high-speed barcode scanners, anchoring hardware production for pharmaceutical serialization equipment worldwide.
United States
FDA's Drug Supply Chain Security Act drives unit-level traceability investments across biologics manufacturers. Pharmaceutical supply chain security spending concentrates in New Jersey and Massachusetts manufacturing clusters where serialization infrastructure upgrades dominate capital allocation. Cloud-native verification platforms convert compliance expenditure from capex to opex for CFO budget planning.
Germany
EU Falsified Medicines Directive enforcement compels pharmaceutical packaging line retrofits across Bavarian and Baden-Württemberg production sites. Federal Ministry of Health-sanctioned blockchain pilot zones test distributed-ledger shipment authentication for cross-border biologics exports. Siemens SIMATIC-compatible hardware specifications dominate line integration standards.
India
CDSCO Schedule M revisions tighten track and trace requirements for contract manufacturers serving regulated export markets. Gujarat and Maharashtra pharmaceutical clusters deploy barcode infrastructure to meet verification standards without RFID cost premiums. Government PLI scheme incentives accelerate domestic serialization equipment adoption.
Switzerland
Swissmedic mandates anchor serialization compliance for high-value biologics and precision therapeutics. Basel and Zurich pharmaceutical manufacturing corridors concentrate brand-name drug production with concentrated procurement power driving platform roadmaps. Cold-chain RFID deployment dominates temperature-sensitive shipment monitoring.
Japan
PMDA serialization standards align with international GS1 EPCIS frameworks for pharmaceutical exports. Kanto and Kansai manufacturing belts integrate automated line verification systems for domestic and regulated market compliance. METI industrial policy supports pharmaceutical supply chain digitization investments.
Pharmaceutical Track and Trace Systems Market Competitive Landscape
Global majors compete with regional champions across verification platform architecture and hardware integration capabilities. Market structure tilts toward consolidated software platforms controlling network-tenancy data exchange, while hardware fabrication fragments across specialized optical equipment producers. Three archetypes dominate: cloud-native verification platform operators, line-integrated hardware specialists, and network-tenancy data exchange coordinators. Competitive moves concentrate on strategic partnerships between software platforms and packaging line integrators, plus geographic expansion through local validation service capabilities.
Within the network-tenancy tier, TraceLink Inc. occupies a position exemplifying data exchange scale across supply chain endpoints. Among hardware-integrated specialists, Optel Vision and Siemens AG represent archetypes of regional manufacturing footprint leverage and automated line integration standard-setting respectively. These three entities anchor competitive positioning without exhaustive market coverage.
| Leading Market Players |
|---|
| Optel Vision |
| Siemens AG |
| TraceLink Inc. |
| SAP |
| Antares Vision |
| Zebra Technologies |
| Axway |
| Mettler-Toledo International |
| Systech |
| Others |
Value Network & Pricing Analysis
Pharmaceutical manufacturer procurement consolidation around subscription-based compliance platforms is compressing hardware margins while elevating recurring revenue multiples for cloud-native verification providers. This demand-side shift forces serialization equipment suppliers to unbundle capital-intensive line hardware from software tenancy contracts, fragmenting pricing architectures across the vendor base.
Pricing Analysis
Service-bundling separates validation documentation and ongoing technical support from base hardware or platform subscriptions, with comprehensive implementation packages commanding premiums over bare-equipment procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by GS1 EPCIS certification grade and integration complexity with legacy ERP systems. Cost compression in economy-tier barcode infrastructure is intensifying because Indian contract manufacturers prioritize CDSCO Schedule M compliance at minimal unit cost. Mid-tier contract manufacturers exhibit highest price sensitivity, while Swiss biologics producers absorb premium RFID deployments for cold-chain resilience.
Supply Chain Analysis
FDA 21 CFR Part 11 qualification and EU Annex 11 validation requirements gate component sourcing for pharmaceutical serialization equipment, limiting supplier pools to pre-audited optical sensor and precision motion-control vendors. Hardware production draws from Taiwan and South Korea for silicon photonics components, Germany for precision line-integration equipment, and China for cost-optimized mechanical subassemblies. Specialized optical sensor supply concentrates in East Asian foundries, creating single-source vulnerability for high-speed barcode scanner production. Distribution runs through packaging line integrators and direct OEM relationships, with validation service capabilities determining regional market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pharmaceutical Track and Trace Systems Market functions as a cost-of-compliance arena where FDA DSCSA unit-level traceability mandates erect substantial barrier-to-entry moats for verified platform providers, entrenching incumbent positions against unvalidated competitors.
For Market Incumbents: Cement network-tenancy dominance by deepening GS1 EPCIS endpoint coverage beyond the 290,000-connection threshold, while acquiring specialized validation consultancies to capture implementation revenue streams. Blockchain-anchored verification entrants threaten data-exchange positions, demanding defensive patent filings around distributed-ledger interoperability protocols. Capacity addition in German blockchain pilot zones anchors European regulatory relationship leverage. For New Entrants and Emerging Players: Launch via white-label network-tenancy partnerships targeting mid-tier Indian contract manufacturers seeking CDSCO Schedule M compliance without proprietary infrastructure investment. Cell and gene therapy serialization presents the most penetrable application segment, with adaptive identifier assignment systems absent from legacy architectures. Go-to-market positioning should emphasize SaaS-based operational expenditure conversion for CFO budget planning. For Investors and Strategic Acquirers: The window for entry favors cloud-native verification platforms with established pharmaceutical manufacturer procurement relationships and recurring revenue visibility. Long-term viability rests on regulatory mandate durability rather than discretionary technology upgrade cycles. Watch FDA DSCSA enforcement escalation timelines as inflection indicators for compliance infrastructure spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Pilot Zone Expansion | Federal Ministry of Health-sanctioned testbeds in Germany validate distributed-ledger shipment authentication protocols. |
| Cell Therapy Serialization Development | Adaptive identifier systems for batch-size-one personalized medicine address unmet legacy packaging line gaps. |
| Cloud-Native Platform Migration | SaaS verification models convert FDA DSCSA compliance expenditure from capital to operational budget treatment. |
| RFID Cold-Chain Integration | Temperature-logging tag deployment captures biologics environmental monitoring premiums in North American clusters. |
| Validation Service Acquisition | Implementation consulting capabilities secure pharmaceutical manufacturer relationships during EU FMD mandate deadlines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving serialization platform engineers, pharmaceutical regulatory affairs leads, packaging line integration specialists, and hospital pharmacy IT directors. FDA 510(k) submissions, EMA marketing authorization applications, CDSCO manufacturing license records, and GS1 implementation guideline repositories provided compliance infrastructure tracking. Bottom-up equipment shipment analysis and top-down pharmaceutical manufacturer IT budget surveys underwent triangulation validation.
Data-stream reconciliation across hardware unit shipments, software subscription disclosures, and services contract values informed the analytical framework. Segmentation dimensions spanned product type, technology architecture, end-user category, and application function, with regional regulatory cluster differentiation across FDA, EMA, and CDSCO jurisdiction models. CAGRs derived from curve-fitting historical mandate-driven procurement waves against projected compliance deadline acceleration. Forecast inputs incorporated biologics cold-chain expansion trajectories and blockchain pilot program scaling assumptions across the analysis window.
Regulatory deadline delays, silicon photonics supply disruptions, and pharmaceutical manufacturer M&A consolidation are the dominant revision risks to modeled expenditure trajectories. Forecasts embed assumptions regarding mandate enforcement consistency and interoperability standard harmonization between national verification systems. A model refresh is warranted upon material change in FDA DSCSA implementation timeline announcements or EU FMD decommissioning requirement enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Cryogenic Ampoules Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market