
 Middle East and Africa Pharmacy Automation Market | 2026-2036
Middle East and Africa Pharmacy Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pharmacy Automation Market Foresight
High-reliability dispensing specifications is unwinding legacy manual workflows across hospital and retail pharmacy settings in the Middle East and Africa. Omnicell Inc leverages its installed base of automated dispensing cabinets to anchor long-term service contracts with Saudi hospital networks. Swisslog Healthcare AG competes through specialized robotic pharmacy systems designed for high-throughput regional medical cities. ARxIUM differentiates via integrated medication management platforms that extend from central fill to bedside administration.
Pharmacy automation encompasses electromechanical and software-controlled systems that dispense, package, track, and verify pharmaceuticals with throughput rates exceeding 300 doses per hour and error rates below 0.01%. These systems serve to eliminate manual compounding risks, enforce formulary compliance, and maintain cold-chain integrity for biologics in climates exceeding 40°C ambient temperature. Automated dispensing systems dominate current procurement volumes across the region's hospital sector, while artificial intelligence-enabled prescription validation represents the fastest-expanding technology layer as Gulf health systems pursue diagnostic-grade pharmacy decision support. Cloud-based inventory management solutions occupy the margin-rich middle tier, particularly among pharmacy chains seeking centralized multi-location visibility.
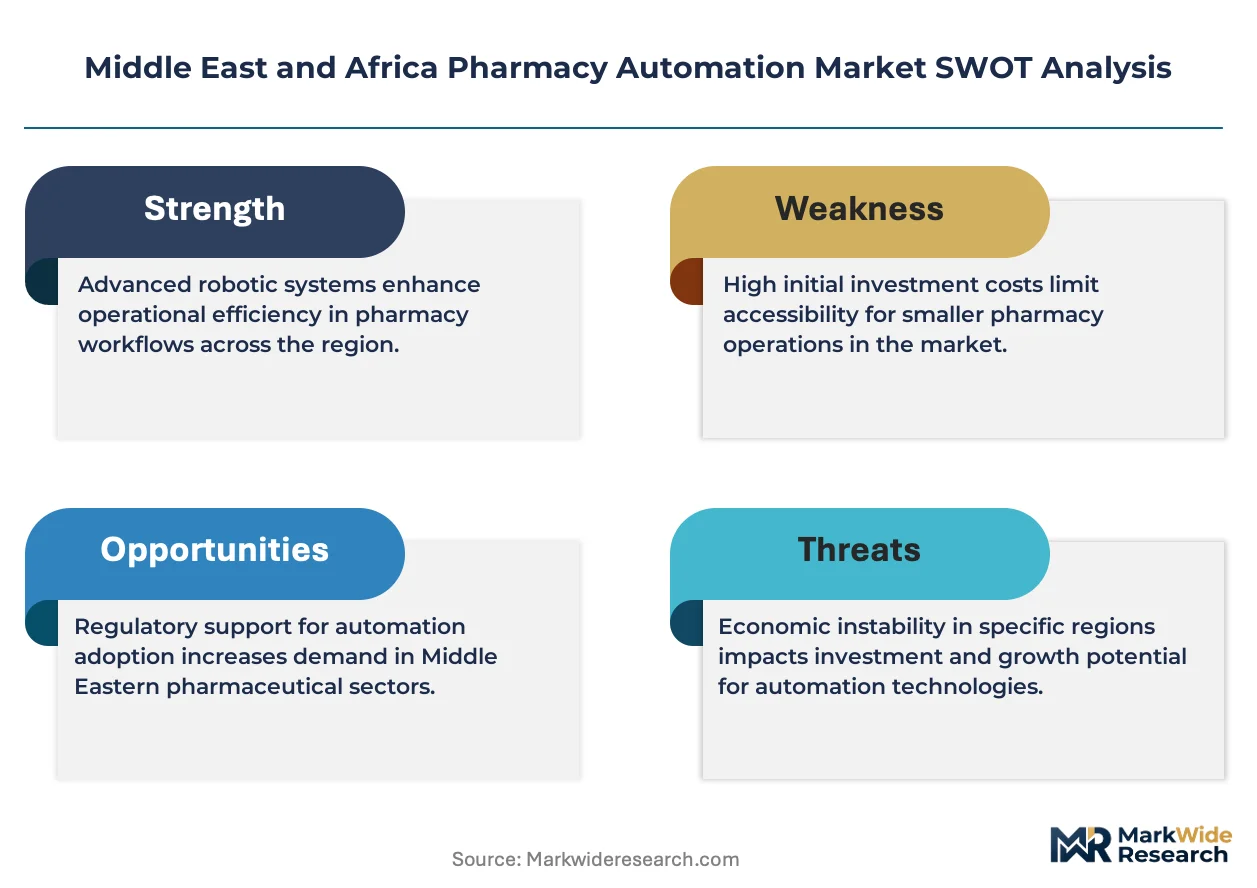
Saudi Food and Drug Authority traceability mandates and UAE Ministry of Health and Prevention barcode authentication requirements are reshaping procurement specifications toward integrated compliance monitoring modules. South Africa's Health Products Regulatory Authority applies medical device registration standards to automated dispensing hardware, creating market access friction for non-ISO 13485-certified suppliers. Stakeholders must weigh the capital intensity of robotic process automation against modular upgrade paths that preserve interoperability with existing hospital information systems.
Market Dynamics
SFDA traceability mandates and UAE barcode authentication requirements are forcing hospital pharmacy procurement toward integrated compliance modules that verify cold-chain integrity for biologics in ambient temperatures exceeding 40°C.
Growth Catalysts
- Robotic dispensing systems:Gulf hospital networks deploy automated dispensing cabinets to reduce medication errors below 0.01% while exceeding 300 doses per hour throughput.
- SFDA pharmaceutical distribution mandates:Saudi Arabia's tightened traceability requirements compel hospital pharmacies to upgrade legacy inventory management infrastructure.
- Dubai Health Authority automation push:UAE regulatory pressure accelerates robotic process adoption across hospital pharmacy workflows in Dubai's medical cluster.
Market Restraints
- Capital intensity of robotic installation:High upfront expenditure for automated dispensing hardware limits procurement to tier-1 hospital networks in Saudi Arabia and UAE.
- ISO 13485 certification friction:South Africa's Health Products Regulatory Authority applies medical device registration standards that exclude non-certified hardware suppliers.
- Legacy system interoperability gaps:Modular upgrade paths face technical barriers integrating with existing hospital information systems across fragmented procurement landscapes.
Strategic Opportunities
- AI-enabled prescription validation:Diagnostic-grade pharmacy decision support represents the fastest-expanding technology layer as Gulf health systems pursue clinical-grade automation.
- Cloud-based inventory centralization:Pharmacy chains across UAE and Saudi Arabia seek multi-location visibility through software-as-a-service inventory management platforms.
- Central fill-to-bedside integration:ARxIUM-style medication management platforms that extend automation from distribution hubs to patient administration points remain underdeployed in African hospital networks.
Industry Challenges
- Biologics cold-chain maintenance:Automated systems must enforce temperature integrity for temperature-sensitive pharmaceuticals in climates with sustained 40°C-plus ambient conditions.
- Interoperability with hospital information systems:Stakeholders face execution complexity preserving data exchange protocols across fragmented electronic health record environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pharmacy Automation Market |
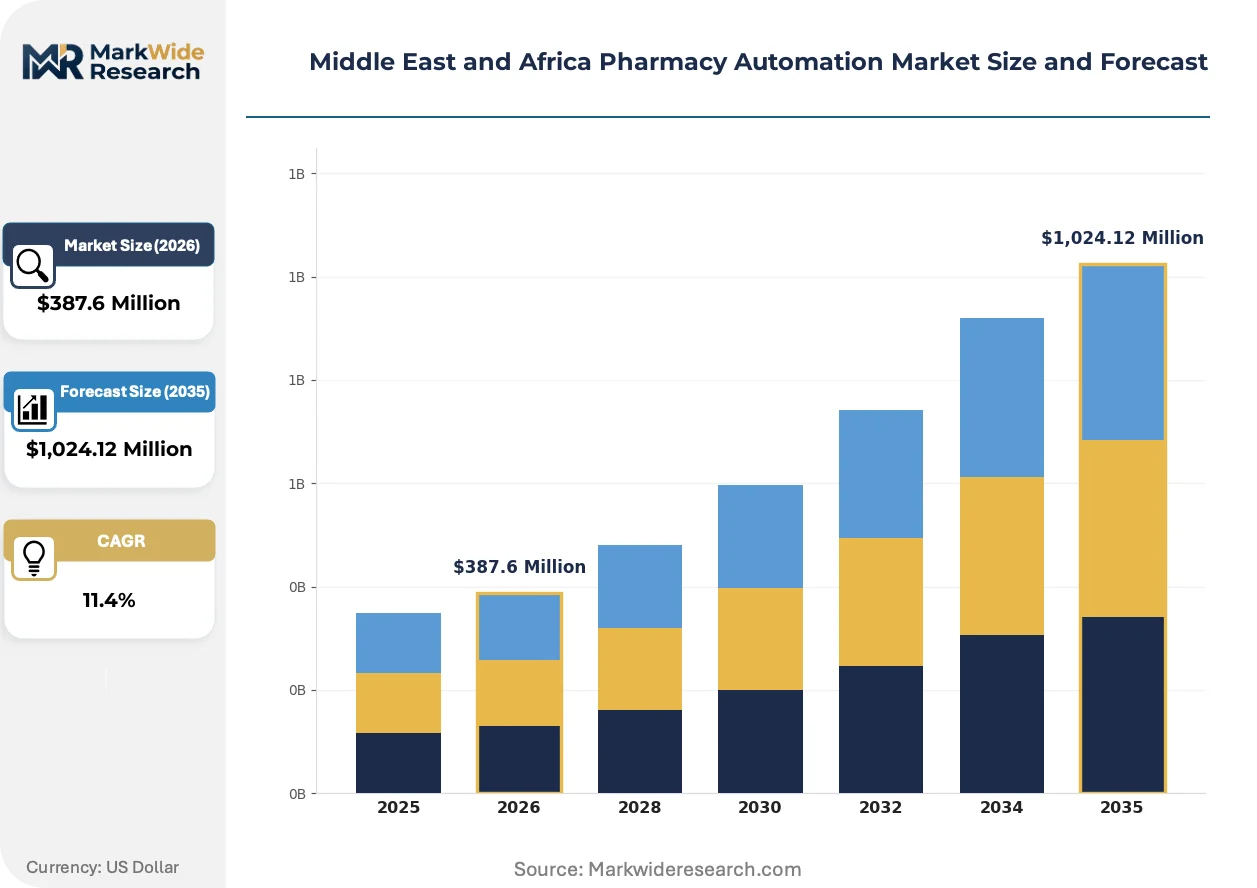
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensing Systems, Robotic Process Automation, Medication Management Systems, Inventory Management Solutions End User: Hospitals, Retail Pharmacies, Long-term Care Facilities, Pharmacy Chains Technology: Barcode Systems, RFID Technology, Cloud-based Solutions, Artificial Intelligence Application: Prescription Management, Inventory Control, Compliance Monitoring, Workflow Optimization |
| Companies Covered | Becton Dickinson and Co, Capsa Solutions LLC, Omnicell Inc, Oracle Corp, Veradigm LLC, Swisslog Healthcare AG, ARxIUM, ScriptPro LLC, RxSafe LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pharmacy Automation Market Shifts & Advancements
Automation is compressing manual pharmacy workflows across Middle Eastern hospital networks while artificial intelligence layers add clinical decision support to mechanical dispensing functions.
Robotic pharmacy systems is displacing manual compounding and verification workflows in Saudi Arabia's regional medical cities. High-throughput hospital networks in Riyadh and Jeddah deploy Swisslog-style specialized automation to handle volume surges from expanding patient populations. This displacement is compressing staffing requirements while enforcing formulary compliance through software-controlled verification protocols.
SFDA pharmaceutical traceability mandates now require serialized barcode authentication at every distribution node. Industrial consequence includes mandatory procurement of integrated compliance monitoring modules alongside core dispensing hardware. Saudi hospital pharmacies are responding by bundling traceability software into automated dispensing cabinet contracts, treating compliance infrastructure as non-negotiable specification.
Buying committees now unbundle hardware procurement from long-term service and software maintenance contracts. Hospital networks in UAE and Saudi Arabia negotiate multi-year service agreements separately from capital equipment purchases, compressing vendor switching costs. This pattern is most visible in Dubai Health Authority-affiliated facilities where robotic process automation contracts undergo competitive re-tendering at shorter cycles.
Middle East and Africa Pharmacy Automation Market Segmentation
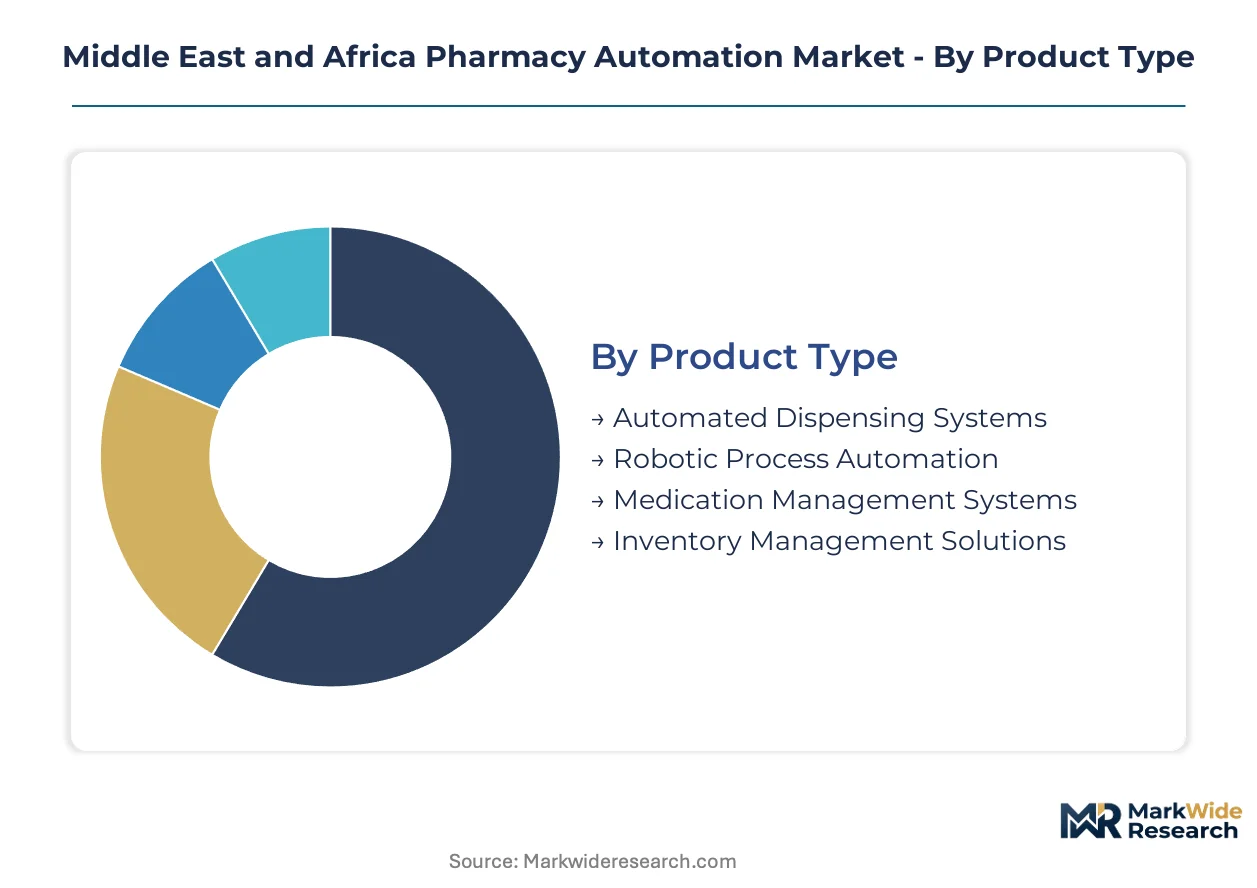
Pharmacy automation procurement across the Middle East and Africa fragments across hardware, software, and service layers that compete for capital allocation within constrained hospital budgets. Understanding segment substitution pressures clarifies where vendors face commoditization risk versus durable technology differentiation.
Product Type:
Automated dispensing hardware faces substitution pressure from modular software upgrades that extend legacy cabinet lifecycles without full replacement capex.
- Automated Dispensing Systems:Electromechanical cabinets with secure access controls and real-time inventory tracking serve as the anchor infrastructure in Saudi hospital networks. Dubai Health Authority-affiliated facilities concentrate procurement here, driven by medication error reduction mandates and throughput requirements exceeding 300 doses per hour.
- Medication Management Systems:Integrated platforms spanning central fill through bedside administration command premium pricing in UAE medical cities. ARxIUM-style deployments are expanding fastest here, propelled by formulary compliance enforcement and biologics cold-chain integrity requirements in ambient temperatures surpassing 40°C.
- Robotic Process Automation:Specialized high-throughput systems for regional medical cities in Riyadh and Jeddah.
- Inventory Management Solutions:Cloud-enabled multi-location visibility tools for pharmacy chains across UAE and Saudi Arabia.
Automated Dispensing Systems retain volume leadership; Medication Management Systems hold the steepest expansion curve.
End User:
Customer concentration tilts toward institutional buyers with regulatory compliance obligations that retail operators can defer.
- Hospitals:Tier-1 networks in Saudi Arabia and UAE dominate procurement, compelled by SFDA traceability mandates and MOHAP barcode authentication requirements. These buyers bundle compliance modules into long-term service contracts, treating integrated monitoring as non-negotiable specification.
- Pharmacy Chains:Multi-location operators across Gulf Cooperation Council states seek centralized inventory visibility through software-as-a-service platforms. Competitive re-tendering cycles are compressing here as buying committees unbundle hardware from service agreements.
- Retail Pharmacies:Independent operators with limited capital intensity for robotic installation.
- Long-term Care Facilities:Facilities with formulary compliance needs but lower throughput requirements.
Hospitals anchor absolute spending; Pharmacy Chains are expanding most quickly as cloud infrastructure penetrates regional retail networks.
Technology:
Legacy barcode infrastructure faces displacement from AI-enabled validation layers that upgrade decision support without hardware replacement.
- Artificial Intelligence:Diagnostic-grade prescription validation algorithms represent the fastest-expanding technology layer across Gulf health systems. Dubai Health Authority automation pushes are concentrating demand here, with clinical-grade decision support commanding premium positioning.
- Cloud-based Solutions:Software-as-a-service inventory management occupies the margin-rich middle tier among pharmacy chains seeking multi-location visibility. Saudi and UAE procurement specifications increasingly favor these platforms for interoperability with fragmented hospital information systems.
- Barcode Systems:Serialized authentication infrastructure mandated by SFDA and MOHAP traceability requirements.
- RFID Technology:Specialized tracking for high-value biologics in temperature-challenged environments.
Barcode Systems retain installed base dominance; Artificial Intelligence holds the steepest expansion curve.
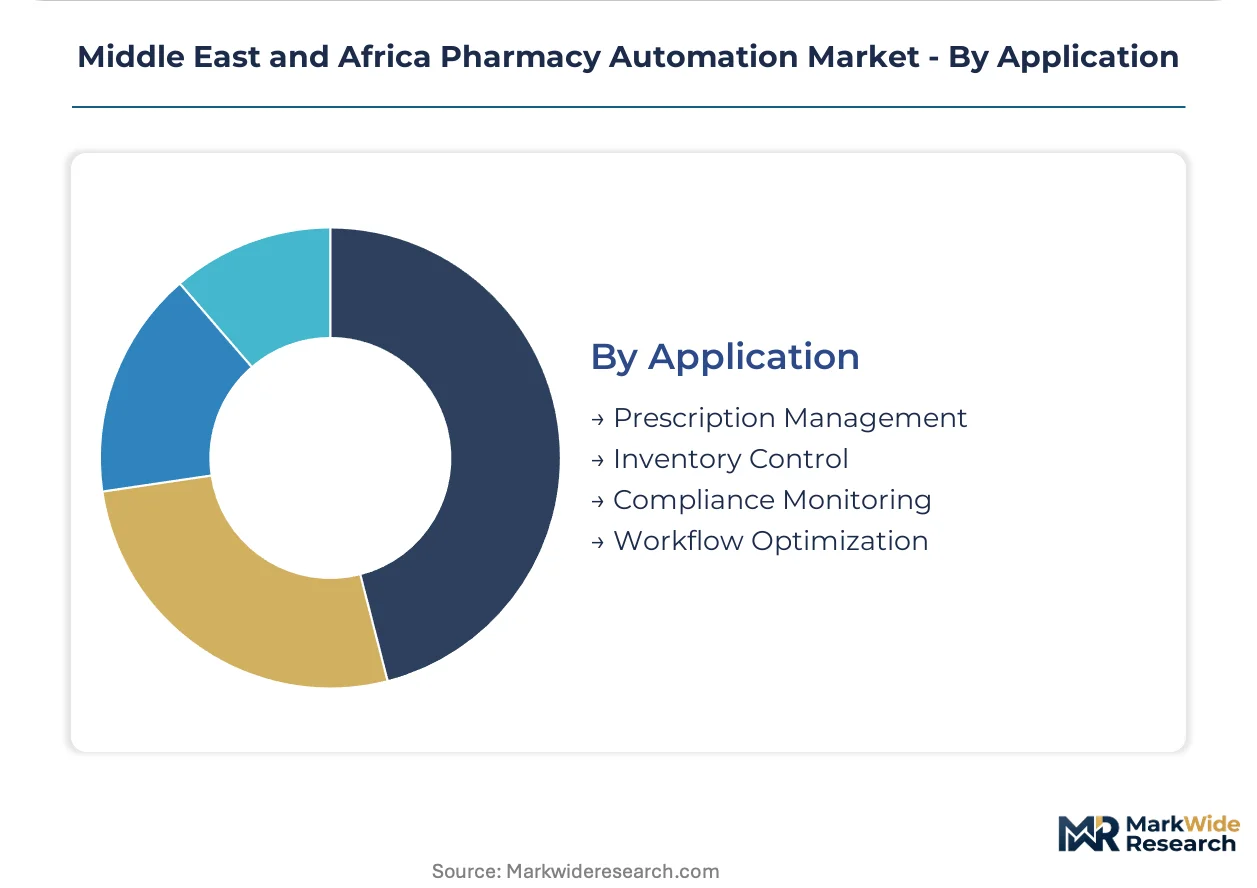
Application:
Workflow optimization software competes for budget against mandatory compliance modules that procurement committees cannot defer.
- Compliance Monitoring:Integrated modules verifying cold-chain integrity and serialized barcode authentication are now non-negotiable in Saudi hospital pharmacy specifications. SFDA mandates are forcing bundled procurement alongside core dispensing hardware, eliminating standalone software sales.
- Prescription Management:AI-enabled validation and verification protocols concentrate in UAE medical clusters pursuing diagnostic-grade pharmacy decision support. Dubai Health Authority regulatory pressure is accelerating robotic process adoption within these workflows.
- Inventory Control:Real-time tracking for formulary enforcement and stock optimization.
- Workflow Optimization:Staffing compression and throughput enhancement tools for high-volume dispensing.
Compliance Monitoring retains procurement priority; Prescription Management holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for pharmacy automation hardware runs high across the Middle East and Africa, with Gulf Cooperation Council states sourcing electromechanical dispensing systems primarily from European and North American manufacturers while South Africa maintains stricter local certification requirements that filter supplier access.
United Arab Emirates
Dubai Health Authority mandates robotic process automation across hospital pharmacy workflows, driving procurement of high-throughput dispensing cabinets. The country's Ministry of Health and Prevention enforces barcode authentication requirements that reshape vendor selection criteria. Dubai's medical city cluster concentrates deployment of AI-enabled prescription validation systems as regulatory pressure accelerates technology adoption.
Saudi Arabia
Saudi Food and Drug Authority traceability mandates compel hospital networks to upgrade legacy inventory infrastructure with serialized tracking capabilities. The Kingdom's Vision 2030 healthcare privatization program expands automated dispensing capacity in Riyadh and Jeddah regional medical cities. Eastern Province hospital networks bundle compliance monitoring modules into long-term service contracts with international suppliers.
South Africa
The Health Products Regulatory Authority applies ISO 13485 medical device registration standards that exclude non-certified automation hardware from public hospital procurement. Private hospital networks in Gauteng and Western Cape provinces lead adoption of medication management platforms. Cape Town's private healthcare cluster demonstrates concentrated demand for cloud-based inventory centralization across multi-location pharmacy operations.
Israel
Advanced hospital networks in Tel Aviv and Haifa deploy diagnostic-grade pharmacy decision support systems with embedded AI validation layers. The country's national health insurance framework incentivizes error reduction technologies that compress medication dispensing risks below 0.01%. Sheba Medical Center and Hadassah Hospital anchor regional demand for integrated central fill-to-bedside automation platforms.
Egypt
Public hospital modernization programs in Cairo and Alexandria generate procurement activity for basic automated dispensing cabinets as first-tier automation infrastructure. The country's pharmaceutical regulator emphasizes cold-chain integrity verification for temperature-sensitive biologics in ambient conditions exceeding 40°C. New administrative capital healthcare zone developments attract vendor interest for greenfield pharmacy automation installations.
Middle East and Africa Pharmacy Automation Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and service contract structures, creating a tiered competitive environment where public companies leverage balance sheet capacity for multi-year hardware deployments while private operators win on implementation flexibility. Market structure concentrates around three to five dominant automation platforms with established Gulf Cooperation Council reference sites. Strategic archetypes include full-stack medication management providers, specialized robotic dispensing fabricators, and software-centric inventory optimization platforms. Competitive moves center on unbundling hardware procurement from long-term service agreements and pursuing regulatory pre-certification in high-barrier jurisdictions.
Within the full-stack integration tier, Omnicell Inc and ARxIUM exemplify platform providers that anchor long-term hospital network relationships through comprehensive automation ecosystems spanning central fill to bedside administration. Swisslog Healthcare AG occupies a position among specialized robotic system fabricators targeting high-throughput regional medical city deployments. These three companies represent contrasting strategic postures: platform breadth versus robotic specialization versus modular upgrade pathways.
| Leading Market Players |
|---|
| Becton Dickinson and Co |
| Capsa Solutions LLC |
| Omnicell Inc |
| Oracle Corp |
| Veradigm LLC |
| Swisslog Healthcare AG |
| ARxIUM |
| ScriptPro LLC |
| RxSafe LLC |
| Others |
Supply & Pricing Matrix
Capacity utilization rates above 85% at European and North American dispensing cabinet manufacturers compress procurement timelines for Gulf hospital networks while establishing price floors that resist downward pressure from modular software alternatives. Tier-1 Saudi and UAE hospital buyers absorb premium positioning for integrated compliance modules, whereas African public health systems face extended delivery cycles that inflate total cost of ownership.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Middle East and Africa pharmacy automation market. Premium tiers bundle ISO 13485-certified hardware with multi-year service contracts and AI-enabled validation layers, while economy tiers offer basic dispensing cabinets without cold-chain monitoring. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from cloud-based SaaS alternatives that extend legacy hardware lifecycles. Pharmacy chains across the Gulf Cooperation Council states exhibit highest price sensitivity due to competitive re-tendering cycles, whereas Saudi regional medical cities demonstrate lowest sensitivity given Vision 2030 privatization budgets.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement planning as Gulf hospital networks buffer against eight-to-fourteen-week lead times for electromechanical dispensing hardware sourced from Germany, Switzerland, and the United States. Component dependencies center on precision servo motors, medical-grade stainless steel enclosures, and temperature control modules validated for 40°C-plus ambient operation. Supply chain risk concentrates in single-source vulnerability for AI-enabled prescription validation software licensed from specialized developers. Distribution runs through authorized regional distributors with SFDA and MOHAP pre-certification capabilities, creating tiered access that filters non-compliant suppliers from Saudi and UAE procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa pharmacy automation market sits in early-cycle recovery as Gulf health system privatization programs unlock deferred capital expenditure from pandemic-era budget freezes. Cyclical momentum builds from regulatory mandate compliance deadlines rather than discretionary technology refresh.
For Market Incumbents: Consolidate installed base relationships through unbundled service contract renegotiation before competitive re-tendering cycles accelerate across Dubai Health Authority-affiliated facilities. Threat substitution from cloud-native inventory platforms demands defensive certification investment in SFDA traceability pre-approval. Priority lever rests on backward integration into regional distribution infrastructure to compress lead times for African hospital networks. For New Entrants and Emerging Players: Anchor in Egyptian public hospital modernization programs where greenfield automation specifications lack legacy system interoperability constraints. Most penetrable segment spans basic automated dispensing cabinets for Cairo and Alexandria facilities with limited robotic installation capital. Go-to-market angle emphasizes cold-chain integrity modules validated for sustained 40°C ambient conditions, addressing regulatory emphasis without premium AI-enabled pricing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform providers with central fill-to-bedside integration capabilities spanning medication management software and hardware maintenance contracts. Long-term viability over the next decade favors acquisition targets with established Gulf Cooperation Council reference sites and MOHAP pre-certification status. Signal to watch is competitive re-tendering cycle compression in UAE pharmacy chains, indicating vendor switching cost erosion that pressures incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Pre-Certification Investment | Unlocks procurement eligibility across Saudi Vision 2030 hospital privatization programs. |
| Cloud-Native Inventory Platform Launch | Captures pharmacy chain demand for multi-location visibility without hardware replacement capex. |
| Regional Distribution Partnership | Compresses lead times for African hospital networks facing single-source vulnerability. |
| AI-Enabled Validation Module Integration | Addresses Dubai Health Authority diagnostic-grade pharmacy decision support mandates. |
| Long-Term Service Contract Unbundling | Defends incumbent positioning against competitive re-tendering in UAE medical clusters. |
Research Methodology
A standing panel of hospital pharmacy directors, biomedical engineering managers, GPO contracts specialists, and regulatory affairs leads provided ongoing calibration across primary interview rounds. Secondary validation drew from SFDA pharmaceutical distribution guidance documents, MOHAP barcode authentication specifications, hospital procurement databases, and ISO 13485 certification registries. Bottom-up demand modeling triangulated against top-down market sizing from automated dispensing system installation records.
Consistency checks validated volume and value outputs against external benchmarks including regional medical city expansion timelines and pharmacy chain cloud adoption disclosures. Segmentation dimensions spanned hardware-software-service layers, end-user institutional versus retail archetypes, deployment model on-premise versus SaaS, and regulatory framework clusters across Gulf Cooperation Council states. CAGRs derived from installed base growth rates weighted by procurement specification evolution toward AI-enabled and compliance-integrated systems.
Underlying assumptions cover sustained Gulf health system privatization momentum and stable SFDA traceability mandate enforcement timelines, with deviation risk concentrated in African public hospital budget volatility and ISO 13485 certification backlog at South Africa's Health Products Regulatory Authority. Revision becomes warranted when cloud-native inventory platform penetration in UAE pharmacy chains crosses threshold adoption rates that materially compress hardware replacement demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Medication Dispenser Market