
 Global Veterinary CT Scanner Market | 2026-2036
Global Veterinary CT Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary CT Scanner Market Foresight
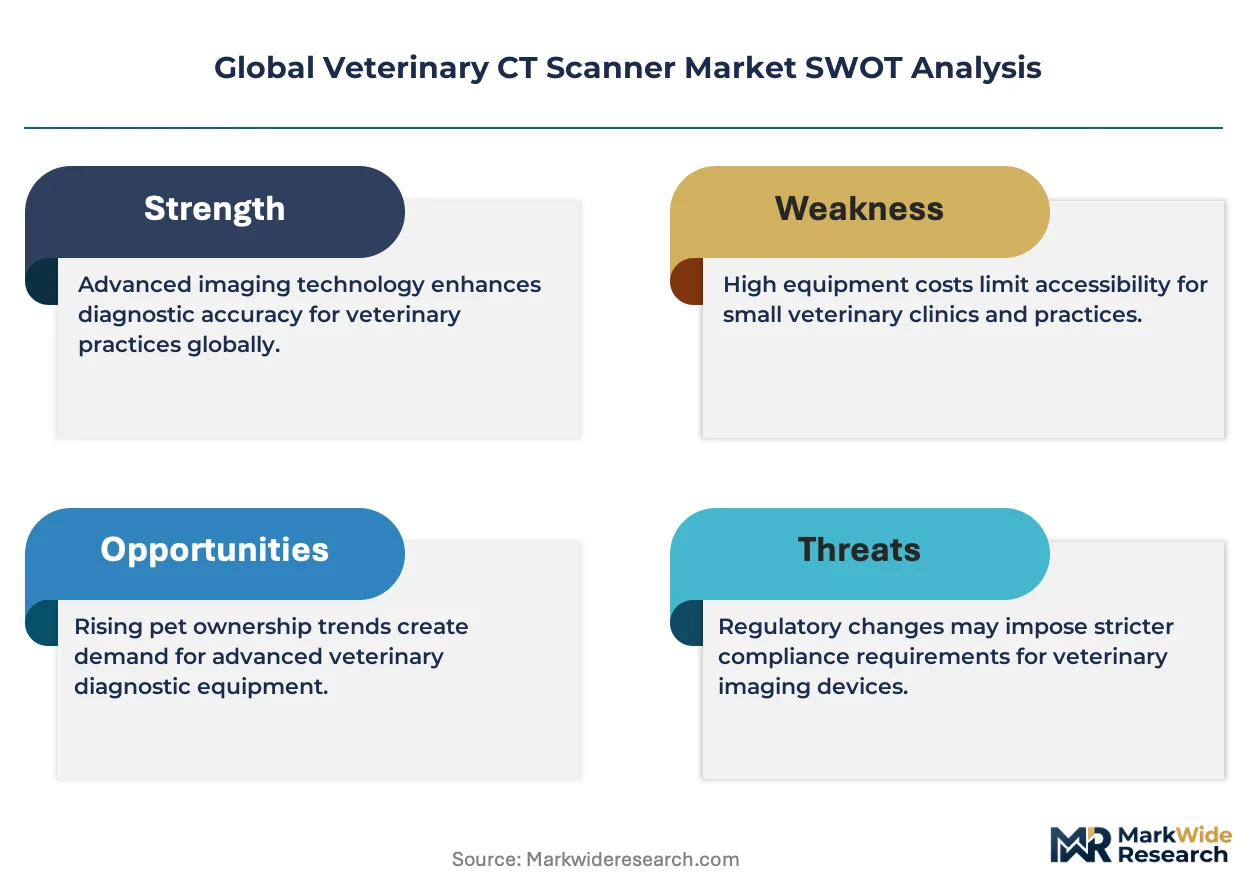
Subscription-based equipment leasing is tilting competitive dynamics toward asset-light operators that previously faced capital barriers. Siemens Healthineers leverages its installed base of human radiology platforms to cross-sell veterinary configurations. GE Healthcare sustains R&D intensity across helical and energy-discriminating CT architectures for species-specific imaging protocols. Canon Medical Systems Corporation anchors its position through flat-panel detector integration that reduces radiation dose in small animal scans.
Veterinary CT scanners are X-ray computed tomography systems engineered for non-human anatomies, typically operating at 80–140 kVp with modified reconstruction algorithms for species ranging from avian to equine. The equipment generates cross-sectional volumetric data to diagnose orthopedic, oncologic, and neurologic conditions in animals that standard radiography cannot resolve. Multi-slice systems currently lead the scanner type category due to throughput advantages at high-volume referral hospitals. Portable configurations represent the fastest-expanding segment as mobile clinics and equine field services seek deployable imaging without fixed-suite infrastructure. Energy-discriminating CT technology commands premium positioning where spectral imaging enables material decomposition for bone-implant assessment and contrast characterization.
FDA Center for Veterinary Medicine guidelines shape device clearance pathways for animal-specific CT systems in the United States, while EMA veterinary medicinal product frameworks indirectly influence imaging requirements for preclinical safety studies across Europe. Japan's PMDA maintains parallel standards for imported veterinary diagnostic equipment under METI industrial coordination. Stakeholders must monitor evolving national reimbursement policies for companion animal advanced diagnostics and the pace at which ISO standards for veterinary imaging equipment harmonize across major regulatory jurisdictions.
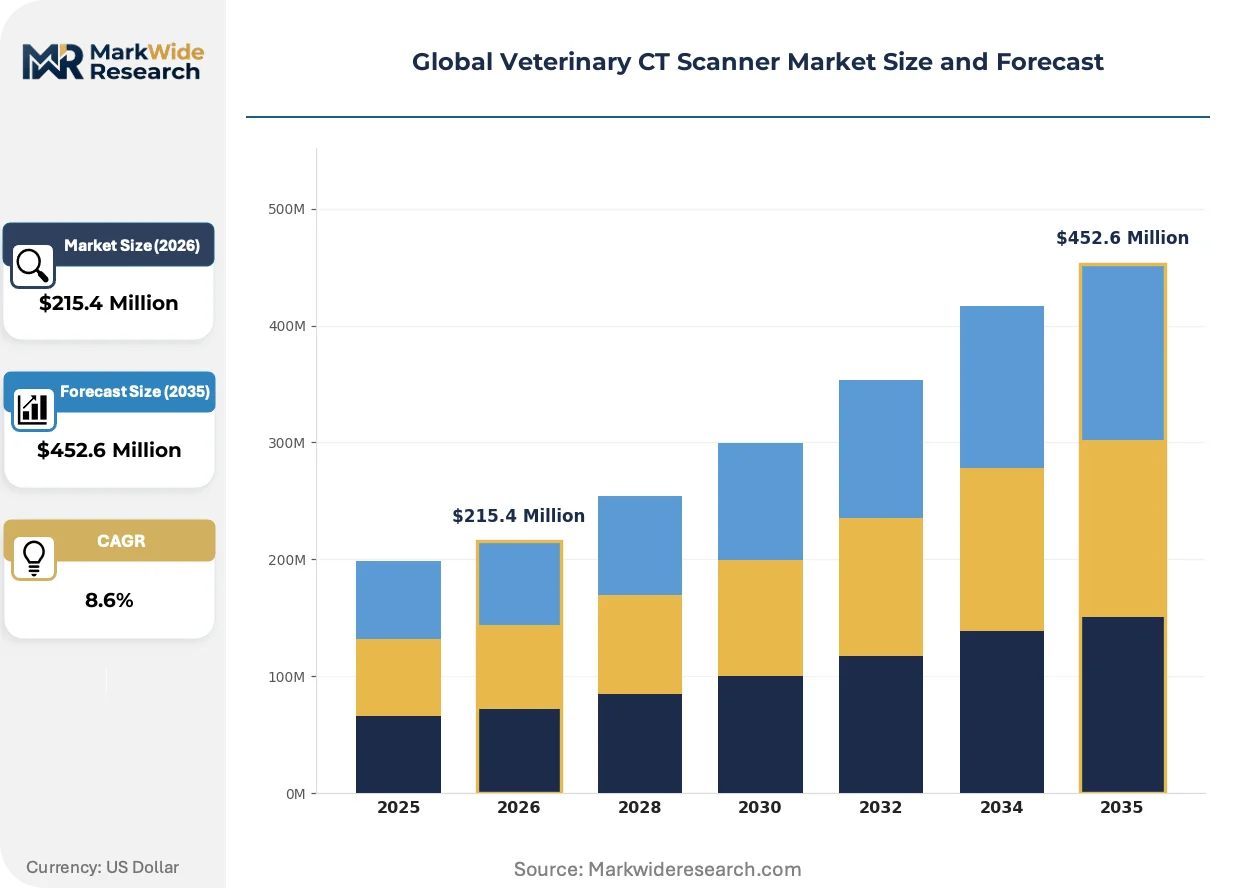
Market Dynamics
Subscription-based equipment leasing is compressing capital barriers for mid-tier veterinary groups, enabling asset-light expansion into advanced imaging services previously gated by six-figure hardware commitments.
Growth Catalysts
- Multi-site veterinary consolidation:Corporate hospital chains standardize CT protocols across networks, driving volume commitments that justify dedicated scanner installations over mobile service contracts.
- FDA Center for Veterinary Medicine clearance pathways:Streamlined 510(k) equivalency determinations for animal-specific CT configurations accelerate commercialization timelines versus de novo submissions.
- Helical CT throughput advantages:Continuous patient table movement reduces scan times for anesthetized companion animals, increasing daily caseload capacity at high-volume referral centers.
Market Restraints
- Specialized service engineer scarcity:Factory-trained CT field technicians concentrate in Germany, Japan, and the United States, creating maintenance response delays for installed bases in secondary markets.
- Isotope supply chain fragility:Molybdenum-99 production for contrast agents relies on aging research reactors in Canada and the Netherlands, exposing imaging schedules to radioisotope shortage risks.
- Species-specific algorithm development costs:Reconstruction software optimized for equine, avian, or exotic anatomies requires discrete R&D investment without guaranteed volume returns.
Strategic Opportunities
- Brazil's underpenetrated equine sports medicine sector:Thoroughbred racing and show jumping federations generate demand for portable CT field services at training facilities lacking fixed imaging infrastructure.
- Energy-discriminating CT convergence:Spectral imaging hardware from human radiology platforms adapts to veterinary bone-implant assessment and contrast material characterization applications.
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duty exposure for CT system components, lowering landed costs for regional veterinary distributors.
Industry Challenges
- Veterinary radiologist certification bottlenecks:European College of Veterinary Diagnostic Imaging residency positions fail to match scanner installation growth, creating interpretation backlogs.
- Legacy PACS integration friction:Hospital information systems designed for human healthcare require custom middleware to accommodate veterinary-specific DICOM metadata and taxonomic coding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary CT Scanner Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $452.6 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Scanner Type: Single-Slice, Multi-Slice, Cone Beam, Portable Application: Small Animal Diagnostics, Equine Imaging, Exotic Animal Care, Livestock Health Assessment End User: Veterinary Hospitals, Animal Research Centers, Mobile Clinics, Specialty Practices Technology: Helical CT, Spiral CT, Flat-Panel Detector, Energy-Discriminating CT |
| Companies Covered | Siemens Healthineers, GE Healthcare, Canon Medical Systems Corporation, Epica Animal Health, Xoran Technologies LLC, Hallmarq Veterinary Imaging, Animage LLC, Planmed Oy, Shenzhen Anke High-Tech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary CT Scanner Market Shifts & Advancements
Artificial intelligence reconstruction algorithms and flat-panel detector architectures are compressing radiation dose requirements while expanding species-appropriate imaging protocols beyond traditional companion animal focus.
Photon-counting CT detector technology is hybridizing spectral imaging capabilities into veterinary platforms originally engineered for conventional energy-integrating sensors. Academic veterinary teaching hospitals in the United States and Germany pilot these systems for orthopedic pre-surgical planning. The convergence is forcing equipment financing models to accommodate faster obsolescence cycles as spectral imaging becomes standard rather than premium-tier configuration.
Japan's PMDA under METI coordination tightened electromagnetic compatibility standards for imported diagnostic equipment in 2023, requiring additional shielding validation for veterinary CT systems. Manufacturers now submit parallel technical documentation for human and animal device variants to accelerate dual-market clearance. Small animal oncology centers in Tokyo and Osaka face the steepest compliance recertification timelines as they operate the densest installed bases of legacy systems.
Mobile imaging service contracts displace capital purchase preferences among independent veterinary practices with sub-15,000 annual caseloads. These operators lease scanner time from regional providers rather than assuming depreciation risk on fixed assets. The pattern concentrates most visibly in Australia's dispersed rural veterinary networks, where equine and large animal field services dominate diagnostic demand outside metropolitan referral clusters.
Global Veterinary CT Scanner Market Segmentation
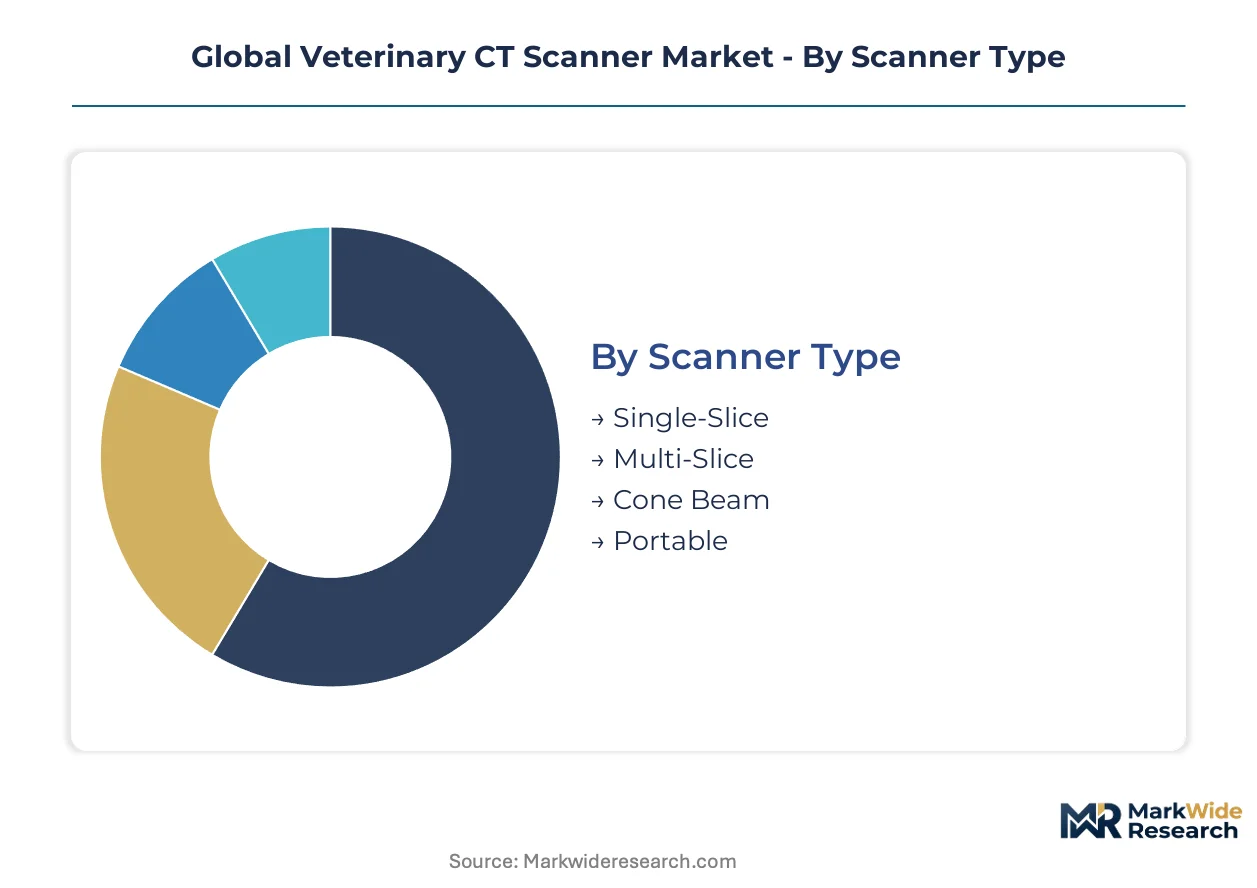
Veterinary CT scanner segmentation reveals distinct equipment lifecycles across scanner architectures and species applications. Cycle-time variation between fixed-suite installations and field-deployable units shapes replacement demand patterns and service contract structures.
Scanner Type:
Multi-slice systems turn over slowest due to capital intensity and installation permanence, while portable configurations refresh fastest as mobile operators prioritize technological currency for competitive differentiation.
- Multi-Slice:These systems deploy 16 to 128 detector rows for high-throughput companion animal diagnostics at referral hospitals. Demand concentrates in the United States and Germany where corporate veterinary chains standardize protocols across metropolitan networks. Capital recovery timelines extend to seven years, slowing replacement velocity despite software upgrade paths.
- Portable:Battery-powered or generator-tethered units with collapsible gantries serve equine field services and rural mobile clinics. Australia's dispersed veterinary networks drive procurement as practitioners lease scanner time rather than assuming fixed-asset depreciation. Rapid obsolescence cycles of three to four years dominate as hardware miniaturization accelerates.
- Single-Slice:Entry-level systems with rotating anode tubes serve budget-constrained independent practices. Japan's small animal general practitioners maintain installed bases despite throughput limitations.
- Cone Beam:Dental-focused variants with flat-panel detectors target maxillofacial imaging in specialty oral surgery practices. European veterinary dental specialists drive niche adoption.
Multi-slice dominates installed base. Portable is where expansion concentrates.
Application:
Cost tier stratification separates high-revenue companion animal diagnostics from capital-efficient livestock screening programs.
- Small Animal Diagnostics:Canine and feline oncology, neurology, and orthopedic pre-surgical planning consume the majority of scanner utilization hours. United States specialty practices in Boston, Chicago, and Los Angeles generate concentrated demand driven by pet insurance penetration and owner willingness-to-pay.
- Equine Imaging:Thoroughbred racing federations and sport horse breeding operations in Kentucky and Ireland commission portable CT for distal limb and cervical spine assessment. Field-deployable protocols avoid transport risks for high-value animals.
- Exotic Animal Care:Avian, reptile, and small mammal imaging requires modified anesthesia delivery and reconstruction algorithms. Zoological institutions and exotic specialty practices in Germany and Japan sustain niche equipment configurations.
- Livestock Health Assessment:Bovine and ovine pulmonary screening supports breeding stock valuation in Australian and Brazilian agricultural regions. Lower per-scan reimbursement constrains hardware specification.
Small animal diagnostics commands premium pricing tiers. Equine imaging is climbing the fastest as sports medicine protocols standardize.
End User:
Customer type determines procurement modality, with corporate entities favoring outright purchase and independent operators selecting subscription leasing.
- Veterinary Hospitals:Multi-site referral centers with 24-hour emergency services maintain dedicated CT suites for trauma and critical care. United States corporate chains including VCA and BluePearl drive standardization across 100-plus location networks.
- Mobile Clinics:Regional service providers deploy truck-mounted or trailer-based systems to serve practices without capital budgets. Australia's rural veterinary networks concentrate this model where population density precludes fixed installations.
- Animal Research Centers:Academic veterinary teaching hospitals and pharmaceutical toxicology facilities require preclinical imaging for regulatory submission. FDA Center for Veterinary Medicine guidelines shape equipment validation protocols.
- Specialty Practices:Neurology, oncology, and orthopedic-focused independents in Germany and Japan operate single-scanner facilities with interpretation expertise concentrated in board-certified radiologists.
Veterinary hospitals dominate installed base. Mobile clinics is where expansion concentrates.
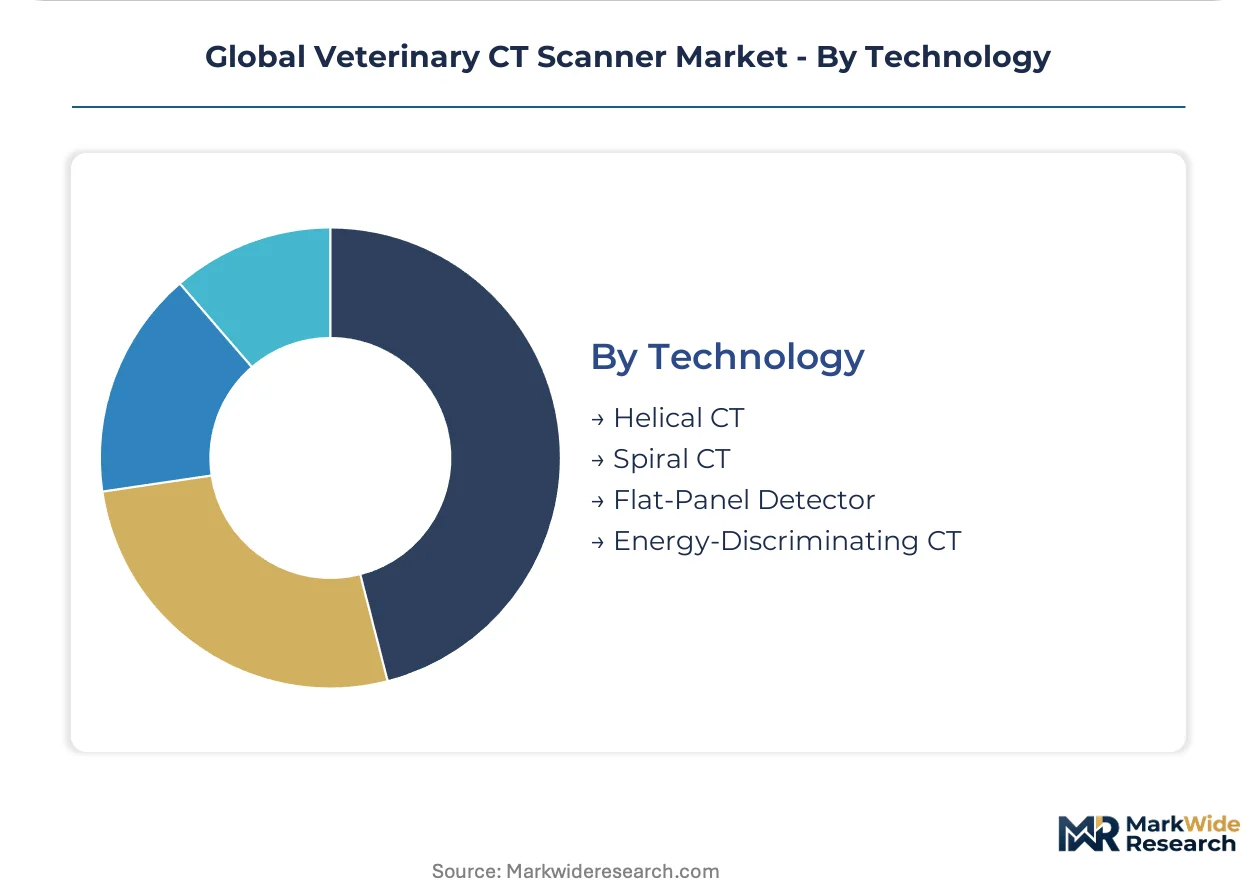
Technology:
Maturity curves separate legacy helical architectures from emerging photon-counting spectral platforms.
- Helical CT:Continuous table movement with slip-ring gantry technology enables sub-minute scan acquisition for anesthetized patients. High-volume United States referral centers prioritize throughput capacity for daily caseloads exceeding 15 studies.
- Energy-Discriminating CT:Spectral imaging with material decomposition algorithms supports bone-implant assessment and contrast characterization. Academic veterinary hospitals in the United States and Germany pilot these systems for orthopedic pre-surgical planning.
- Flat-Panel Detector:Solid-state digital receptors reduce radiation dose in small animal scans compared to image-intensifier chains. Canon Medical Systems anchors market position through integrated detector-vendor relationships.
- Spiral CT:Early-generation helical variants with slower rotation speeds persist in secondary markets where replacement capital remains constrained.
Helical CT dominates installed base. Energy-discriminating CT is gaining share fastest as spectral imaging converges from human radiology platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax incentives for veterinary equipment depreciation and pet insurance reimbursement policies are concentrating scanner deployment in high-income economies with established companion animal healthcare infrastructure.
United States
Corporate veterinary chains VCA and BluePearl operate 100-plus location networks that standardize CT protocols across metropolitan referral centers. FDA Center for Veterinary Medicine 510(k) clearance pathways accelerate commercialization timelines for animal-specific configurations. Boston, Chicago, and Los Angeles specialty practices generate concentrated demand driven by pet insurance penetration and owner willingness-to-pay.
Germany
Academic veterinary teaching hospitals pilot photon-counting CT systems for orthopedic pre-surgical planning alongside helical installations at high-volume referral networks. EMA veterinary medicinal product frameworks indirectly shape imaging requirements for preclinical safety studies. Munich and Berlin clusters concentrate the densest installed bases of energy-discriminating platforms in Europe.
Japan
PMDA under METI coordination tightened electromagnetic compatibility standards for imported diagnostic equipment in 2023, requiring additional shielding validation. Small animal oncology centers in Tokyo and Osaka face steep compliance recertification timelines as they operate the densest installed bases of legacy systems. General practitioners maintain single-slice configurations despite throughput limitations.
Australia
Dispersed rural veterinary networks concentrate mobile imaging service contracts as independent practitioners lease scanner time rather than assuming fixed-asset depreciation. TGA oversight of imported medical devices shapes distributor procurement patterns. Equine and large animal field services dominate diagnostic demand outside Sydney and Melbourne metropolitan referral clusters.
Brazil
Thoroughbred racing and show jumping federations generate demand for portable CT field services at training facilities lacking fixed imaging infrastructure. ANVISA registration requirements for imported diagnostic equipment create compliance complexity for regional distributors. São Paulo and Rio Grande do Sul agricultural regions sustain lower-specification livestock screening programs constrained by per-scan reimbursement limits.
Global Veterinary CT Scanner Market Competitive Landscape
On the supply side, the industry is consolidating around diversified medical imaging conglomerates with cross-market platform architectures. Human radiology equipment manufacturers leverage established manufacturing scale and regulatory expertise to enter veterinary configurations with modified software protocols. Three strategic archetypes dominate: diversified imaging conglomerates with dual-market platforms, specialized veterinary equipment pure-plays, and emerging regional fabricators with cost-optimized designs. Competitive moves center on spectral imaging technology licensing from human healthcare divisions and subscription-based equipment leasing partnerships with mid-tier veterinary groups.
Within the diversified imaging tier, Siemens Healthineers AG and GE Healthcare exemplify platform leverage strategies that adapt helical and energy-discriminating architectures for species-specific protocols. Canon Medical Systems Corporation anchors detector integration capabilities through vendor relationships that reduce radiation dose in small animal applications. Shenzhen Anke High-Tech Co., Ltd. occupies a position among emerging Chinese fabricators targeting cost-sensitive veterinary markets with streamlined hardware configurations.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Canon Medical Systems Corporation |
| Epica Animal Health |
| Xoran Technologies LLC |
| Hallmarq Veterinary Imaging |
| Animage LLC |
| Planmed Oy |
| Shenzhen Anke High-Tech Co., Ltd. |
| Others |
Supply & Pricing Matrix
Underutilized production capacity at German and Japanese CT component foundries is compressing supplier pricing power while accelerating subscription-model adoption among capital-constrained veterinary groups. This utilization gap feeds directly into equipment leasing terms that mid-tier operators now favor over outright purchase.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared configurations and economy-tier CE-marked alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with FDA 510(k) clearance commanding substantial premiums over European equivalents. Cost compression in the economy tier is intensifying because Chinese fabricators are flooding secondary markets with streamlined hardware. Independent rural practitioners exhibit the highest price sensitivity, while United States corporate hospital chains prioritize throughput specifications over unit cost.
Supply Chain Analysis
Export control restrictions on photon-counting detector arrays limit technology flows from United States and German suppliers to emerging market fabricators. Manufacturing gravity centers on Germany, Japan, and the United States for precision gantry assemblies, while China dominates flat-panel detector substrate production. Supply chain vulnerability rests on single-source dependency for molybdenum-99 radioisotope production in aging Canadian and Dutch research reactors. Distribution runs through authorized veterinary equipment distributors with factory-trained service engineer networks rather than direct manufacturer-to-hospital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary CT scanner market is exiting a capital-expenditure trough as corporate consolidation cycles drive replacement demand at multi-site hospital networks.
For Market Incumbents: Harden spectral imaging IP positions through accelerated patent filings in energy-discriminating reconstruction algorithms before Chinese competitors achieve technical parity. Consolidate service engineer networks in secondary markets to counter emerging pure-play veterinary specialists threatening maintenance contract renewals. Deepen backward integration into flat-panel detector supply to secure component allocation during semiconductor fabrication constraints. For New Entrants and Emerging Players: Brazil's underpenetrated equine sports medicine sector offers immediate white-space opportunity for portable CT field services at thoroughbred training facilities. India's PLI scheme for medical devices enables domestic assembly that sidesteps import duty exposure for regional veterinary distributors. Pursue mobile clinic leasing partnerships as the dominant go-to-market mechanism rather than fixed-suite capital sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable configurations as battery miniaturization reduces hardware bill-of-materials costs. Acquisition targets should emphasize veterinary-exclusive equipment pure-plays with established species-specific algorithm libraries rather than diversified imaging conglomerates. Watch subscription-model penetration rates at independent practices as the inflection signal for asset-light competitive viability.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting CT Platform Migration | Spectral imaging convergence from human radiology accelerates veterinary orthopedic pre-surgical planning capabilities. |
| Subscription-Based Equipment Leasing | Asset-light expansion enables mid-tier veterinary groups to bypass six-figure capital barriers. |
| Species-Specific Algorithm Development | Equine, avian, and exotic reconstruction protocols differentiate premium-tier system configurations. |
| Factory-Trained Service Network Consolidation | Maintenance response capabilities concentrate competitive positioning in secondary markets. |
| Dual-Market Regulatory Clearance Strategy | Parallel FDA and PMDA submissions accelerate commercialization timelines for imported systems. |
Research Methodology
Desk research of FDA 510(k) clearance databases, PMDA medical device registration filings, and EMA preclinical imaging guidelines preceded structured interviews with veterinary radiologists, hospital procurement managers, biomedical engineers, and GPO contracts specialists. Secondary validation drew from customs import records, veterinary equipment distributor financial disclosures, and ISO standards documentation for veterinary imaging equipment. Bottom-up scanner installation counts by country and top-down market sizing by equipment category were triangulated against manufacturer revenue segment disclosures.
Forecasts assumed stable regulatory clearance timelines across major jurisdictions, continuous helical CT dominance in high-volume referral centers, and portable configuration refresh cycles compressing to three-to-four years. Modeled dimensions included scanner architecture, species application, end-user type, and technology tier across the analysis window. CAGRs were derived from equipment replacement velocity curves, corporate hospital chain expansion plans, and pet insurance reimbursement policy trajectories. Veterinary radiologist certification bottlenecks and isotope supply chain fragility were incorporated as demand-side constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese cost-optimized fabricators would shift outcomes through accelerated price erosion in economy-tier segments. Material shifts in national companion animal diagnostic reimbursement policies or molybdenum-99 production reactor decommissioning schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Ultrasound Market
Medical Imaging
Europe Nuclear Imaging Devices Market