
 4-Valent HPV Vaccine (4vHPV) Market | 2026-2036
4-Valent HPV Vaccine (4vHPV) Market Size, Share, and Industry Trends Forecast 2026-2036
4-Valent HPV Vaccine (4vHPV) Market Insights
Premium-grade cold-chain specification is collapsing as a meaningful differentiator between originator and emerging-supplier 4vHPV products. Merck & Co., Inc. leverages its decades-long manufacturing scale to sustain cost advantages in high-volume tenders across Latin America. GlaxoSmithKline plc anchors its position through specialized adjuvant technology that commands preference in European procurement frameworks. Serum Institute of India Pvt. Ltd. competes aggressively on price while navigating complex WHO prequalification timelines for intramuscular formulations.
The 4-Valent HPV Vaccine (4vHPV) is a recombinant protein subunit vaccine containing virus-like particles targeting HPV types 6, 11, 16, and 18, produced through yeast or insect cell culture expression systems and formulated with aluminum-containing adjuvants to induce neutralizing antibodies against oncogenic and non-oncogenic strains. Its primary commercial purpose is preventing cervical, anal, and oropharyngeal cancers plus genital warts through prophylactic immunization prior to viral exposure. Licensed vaccines occupy the dominant margin pool as regulatory validation creates steep barriers to generic substitution, while clinical trials represent the fastest-expanding segment as Chinese and Indian developers advance modified 4vHPV candidates through Phase III programs. Adolescents constitute the core demand concentration for intramuscular administration in school-based delivery models, though adult catch-up campaigns are gaining traction in high-income markets where prior coverage gaps persist.
The FDA governs 4vHPV approval and labeling in the United States, while the EMA's centralized procedure shapes market access across European Union member states and the WHO prequalification program determines eligibility for Gavi-subsidized procurement in lower-middle-income countries. These frameworks collectively enforce potency assays, stability testing, and pharmacovigilance reporting that shape manufacturer R&D priorities and tender competitiveness. Stakeholders must monitor evolving national immunization technical advisory group recommendations on dose scheduling and gender-neutral coverage expansion as these policy shifts will redirect procurement volumes across supplier portfolios.
Market Dynamics
The transition from three-dose to two-dose and single-dose scheduling protocols is compressing total addressable volume while expanding eligible cohorts, fundamentally altering how manufacturers model long-term procurement contracts and manufacturing capacity.
Growth Catalysts
- Gavi-subsidized procurement frameworks:Eligibility expansion for lower-middle-income countries is unlocking public-sector tenders previously inaccessible to 4vHPV suppliers, with Indonesia and Vietnam scaling national immunization programs through partnership structures.
- Gender-neutral coverage mandates:National immunization technical advisory groups in Brazil and Mexico are recommending adolescent male inclusion, effectively doubling target population denominators within existing delivery infrastructure.
- FDA labeling harmonization:Streamlined post-marketing surveillance requirements are reducing regulatory compliance burdens for approved products, accelerating cycle times for label expansions and age indication updates.
Market Restraints
- Aluminum adjuvant input concentration:Supply of pharmaceutical-grade aluminum salts concentrates among three specialty chemical producers, creating price volatility exposure for formulation-dependent manufacturers.
- Yeast expression system lock-in:Merck's decades-optimized Saccharomyces cerevisiae platform generates manufacturing yield advantages that emerging insect-cell competitors cannot replicate without billion-dollar facility investments.
- WHO prequalification timelines:Intramuscular formulation review cycles for Indian and Chinese developers currently extend 24-36 months, freezing participation in Gavi-allocated tenders regardless of price competitiveness.
Strategic Opportunities
- Adult catch-up campaign white space:High-income markets including the United States and Germany exhibit persistent coverage gaps among women aged 26-45, creating demand for targeted healthcare provider education and pharmacy-based delivery channels.
- Thermostable formulation development:Convergence of lyophilization technology with novel stabilizer chemistries promises to relax cold-chain requirements, enabling last-mile distribution through existing Expanded Programme on Immunization infrastructure in sub-Saharan Africa.
- European adjuvant preference premium:EMA procurement frameworks increasingly weight immunogenicity head-to-head data, rewarding specialized adjuvant investments with preferential tender scoring in France and Germany.
Industry Challenges
- Pharmacovigilance signal detection capacity:Post-authorization safety monitoring for rare adverse events requires specialized epidemiology functions that contract research organizations struggle to staff at required scale.
- Multi-valent manufacturing line reconfiguration:Facilities producing 4vHPV alongside 9-valent candidates face complex changeover protocols and cleaning validation requirements that compress effective capacity utilization.
- Patent landscape navigation:Virus-like particle assembly IP and adjuvant formulation patents create licensing complexity for developers advancing modified candidates through Phase III programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-Valent HPV Vaccine (4vHPV) Market |
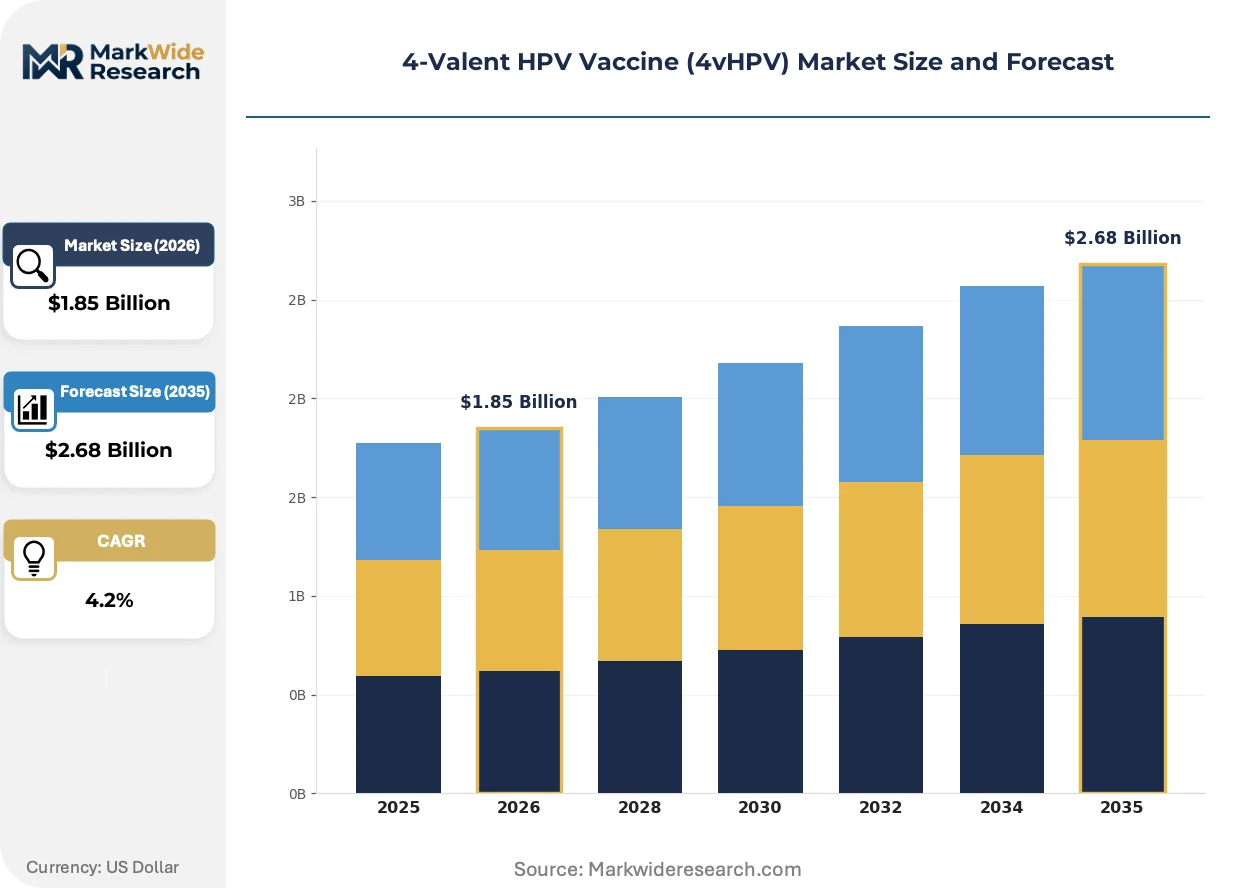
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Licensed Vaccines, Clinical Trials, Research Products, Post-Marketing Surveillance End User: Healthcare Providers, Patients, Pharmacies, Hospitals Age Group: Children, Adolescents, Adults, Elderly Administration Route: Intramuscular, Subcutaneous, Intradermal, Others |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Serum Institute of India Pvt. Ltd., Xiamen Innovax Biotech Co., Ltd., Walvax Biotechnology Co., Ltd., Sanofi S.A., AstraZeneca Plc, Bharat Biotech, Inovio Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Valent HPV Vaccine (4vHPV) Market Trends and Innovations
Yeast-based expression platforms are encountering displacement pressure from mammalian and plant-cell alternatives, while regulatory science advances and procurement model evolution are compressing traditional competitive moats around established suppliers.
Mammalian cell culture systems for VLP production are decomposing the manufacturing efficiency advantage historically concentrated in yeast platforms. Chinese developers including Walvax and Innovax are advancing CHO-based 4vHPV candidates through Phase III trials with comparable immunogenicity profiles. This technology is decomposing cost structures that previously protected incumbent positions in high-volume tenders.
The FDA's updated guidance on HPV vaccine labeling is compressing post-approval study requirements for established products while tightening evidentiary standards for new entrants. Manufacturers with existing approvals gain accelerated pathway access for age expansion indications. European developers leveraging EMA centralized procedures are responding by front-loading real-world evidence generation to preempt regulatory divergence.
School-based delivery models are fragmenting into mixed public-private channels as pharmacy and workplace vaccination programs gain traction among adult catch-up cohorts. Brazil's national immunization program is piloting employer-sponsored adolescent vaccination through occupational health networks. This behavioral shift is most visible in São Paulo state, where private sector absorption now complements public procurement without substituting it.
4-Valent HPV Vaccine (4vHPV) Market Segmentation
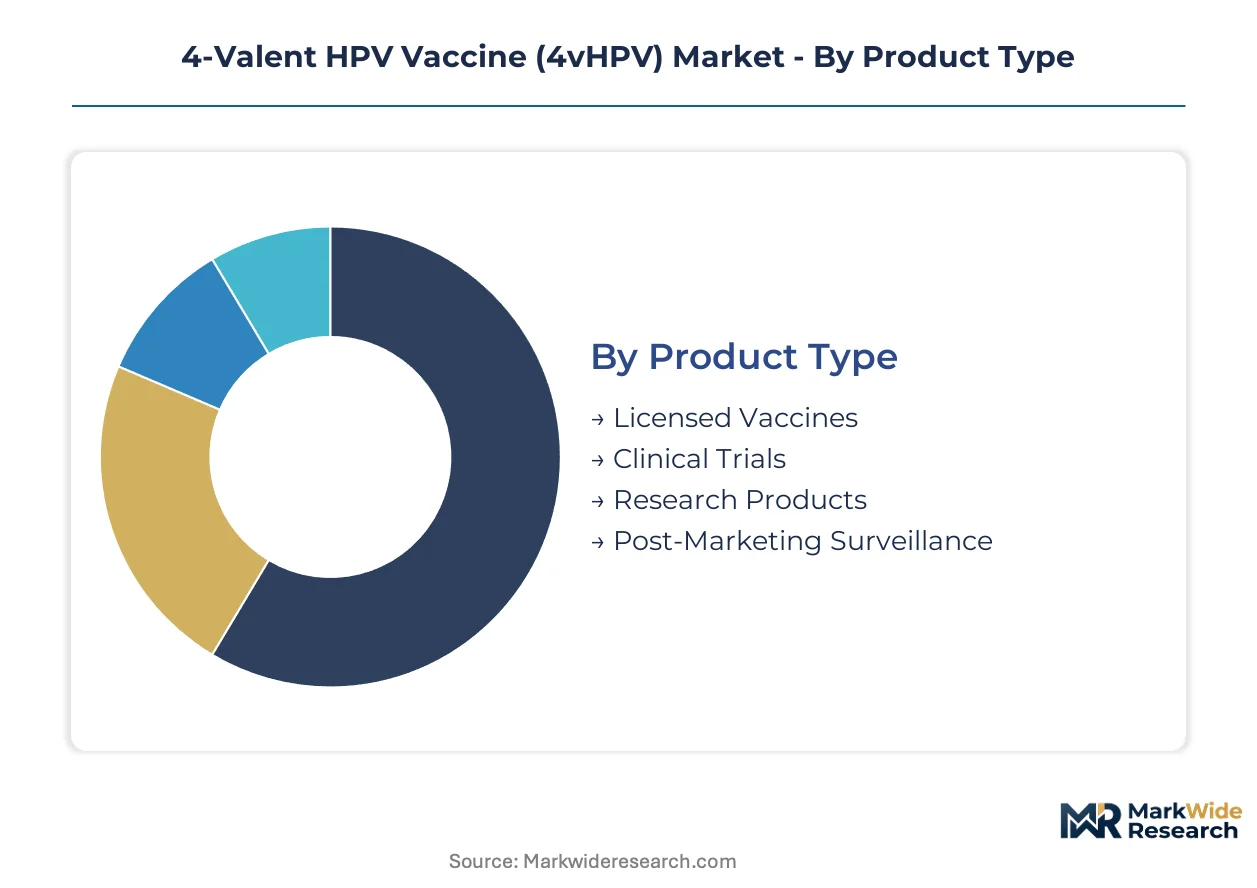
4vHPV market segmentation reveals divergent competitive dynamics across product maturity stages and delivery channels. Substitute pressure from 9-valent alternatives and single-dose protocols is reshaping volume allocation across every category.
Product Type:
Substitution pressure concentrates most intensely in licensed vaccines as national programs weigh 4-valent against 9-valent coverage economics.
- Licensed Vaccines:Regulatory-validated formulations containing aluminum-adjuvanted VLPs for HPV types 6, 11, 16, and 18. Procurement concentrates in Brazil and Mexico school-based programs where gender-neutral mandates expand eligible cohorts despite dose-schedule compression.
- Clinical Trials:Phase III programs for modified 4vHPV candidates advance through Chinese and Indian developer pipelines. Patient recruitment accelerates in Southeast Asia as Indonesia and Vietnam establish regional trial infrastructure for adolescent immunogenicity endpoints.
- Research Products:Investigational formulations for thermostable and adjuvant-modified candidates.
- Post-Marketing Surveillance:Pharmacovigilance systems tracking rare adverse events across distributed immunization networks.
Licensed vaccines anchors the volume base while clinical trials gains share at the steepest rate.
End User:
Cost tier stratification separates institutional procurement from retail pharmacy absorption, with pharmacy channels commanding premium pricing for adult catch-up segments.
- Healthcare Providers:Physician offices and community clinics administering adolescent doses through national immunization program contracts.
- Patients:Direct-pay consumers accessing vaccination through occupational health networks and private clinics, particularly in São Paulo state pilot programs.
- Pharmacies:Retail chains capturing adult catch-up demand in high-income markets where prior coverage gaps persist among women aged 26-45.
- Hospitals:Acute care facilities integrating 4vHPV into oncology prevention protocols and pre-surgical screening workflows.
Healthcare providers dominate contract volume while pharmacies expand most quickly as delivery channels fragment.
Age Group:
Application focus shifts from pediatric expansion toward adult catch-up as high-income markets address historical coverage deficiencies.
- Adolescents:Core target population for school-based delivery models. Brazil and Mexico national immunization programs concentrate procurement here, with male inclusion mandates effectively doubling addressable denominators within existing infrastructure.
- Adults:Catch-up cohorts aged 26-45 in the United States and Germany exhibit persistent coverage gaps. Pharmacy-based delivery and employer-sponsored programs are redirecting procurement volumes toward this segment.
- Children:Pre-adolescent dosing schedules in select national programs.
- Elderly:Limited indication scope given prophylactic mechanism requiring pre-exposure administration.
Adolescents anchors the volume base while adults gains share at the steepest rate.
Administration Route:
Supply concentration in intramuscular formulations creates barriers to alternative route penetration despite patient preference research.
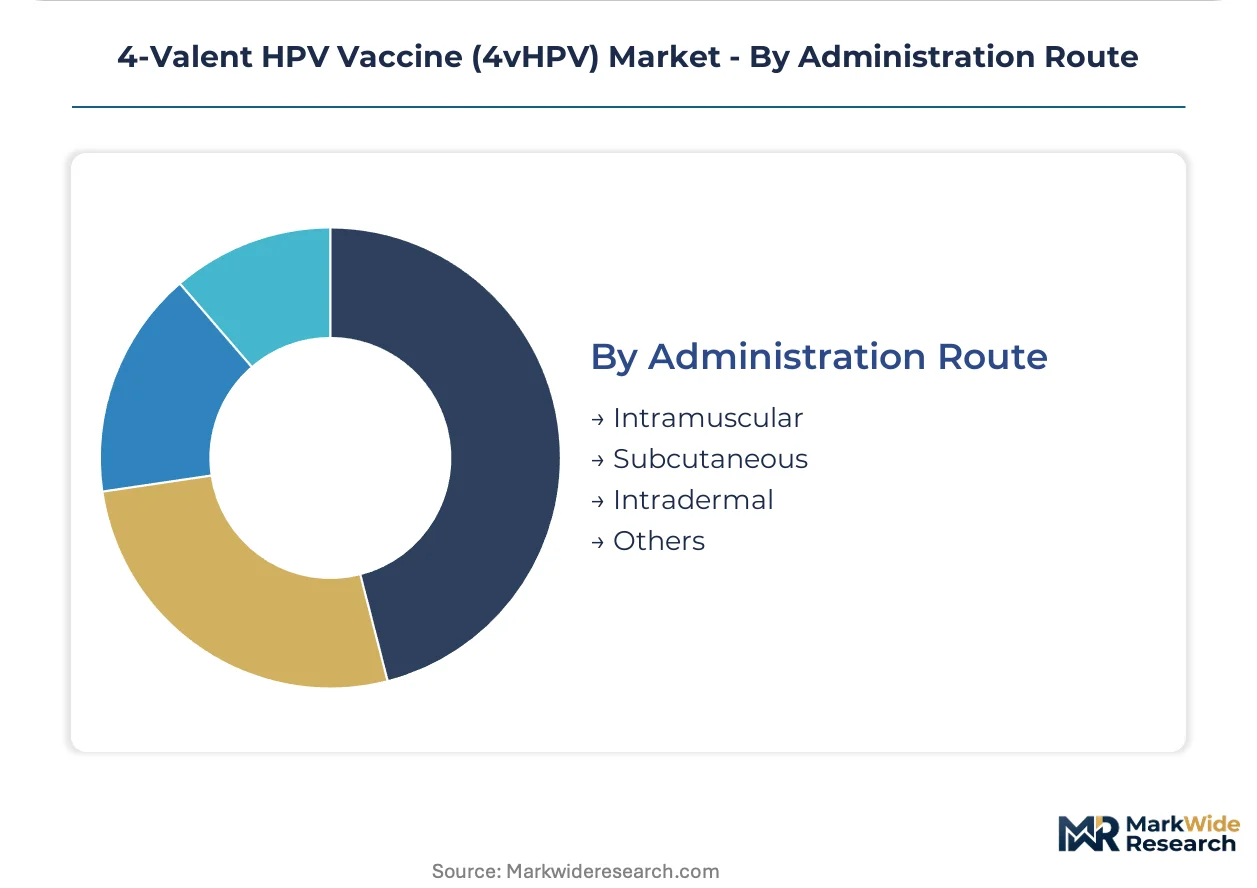
- Intramuscular:Standard delivery into deltoid or vastus lateralis muscle. WHO prequalification timelines for this formulation currently extend 24-36 months for Indian and Chinese developers, freezing Gavi tender participation regardless of price competitiveness.
- Subcutaneous:Alternative injection depth with potential for simplified cold-chain requirements. Development concentrates in thermostable formulation programs targeting sub-Saharan Africa last-mile distribution.
- Intradermal:Microinjection approaches under investigation for dose-sparing potential.
- Others:Experimental mucosal and transdermal delivery systems in early-phase research.
Intramuscular anchors the volume base while subcutaneous climbs the fastest as thermostable programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merck & Co., Inc. exports Gardasil formulations from its Pennsylvania manufacturing base to Gavi-procurement networks spanning Indonesia and Vietnam. This trade corridor channels approximately half of all 4vHPV doses reaching Southeast Asian national immunization programs.
United States
Adult catch-up campaigns among women aged 26-45 drive pharmacy-based demand. The FDA streamlined post-marketing surveillance requirements through updated labeling guidance. Texas and Florida health departments pilot employer-sponsored adolescent vaccination through occupational health networks.
Brazil
National immunization program expansion targets gender-neutral adolescent coverage. ANVISA regulates vaccine registration and pharmacovigilance reporting. São Paulo state absorbs private-sector doses alongside public procurement without substitution effects.
Germany
EMA centralized procedures shape procurement frameworks weighting immunogenicity head-to-head data. Adult coverage gaps persist despite school-based pediatric programs. Bavaria and North Rhine-Westphalia concentrate specialist adjuvant preference premiums in tender scoring.
Indonesia
Gavi partnership structures unlock public-sector tenders previously inaccessible to emerging suppliers. The national pharmaceutical regulator oversees WHO prequalification alignment for intramuscular formulations. Java-based distribution hubs scale last-mile delivery through existing Expanded Programme on Immunization infrastructure.
India
Domestic manufacturers compete aggressively on price while navigating complex WHO prequalification timelines. CDSCO governs clinical trial approvals for modified 4vHPV candidates. Maharashtra and Telangana host Phase III trial infrastructure for adolescent immunogenicity endpoints.
4-Valent HPV Vaccine (4vHPV) Market Competitive Landscape
Listed leaders compete with private specialists across regulatory validation and manufacturing scale dimensions. The supplier base concentrates around three strategic tiers: originator multinationals with decades-optimized expression platforms, emerging-market challengers advancing through Phase III programs, and regional fill-finish specialists. Archetypes include the regulatory-incumbent, the price-competitive prequalification-seeker, and the adjuvant-technology differentiator. Dominant competitive moves encompass strategic partnerships for Gavi tender access and manufacturing capacity reconfiguration between 4-valent and 9-valent product lines.
Within the originator tier, Merck & Co., Inc. and GlaxoSmithKline plc exemplify divergent competitive positioning. Merck occupies a position anchored in yeast-expression manufacturing scale advantages that generate cost competitiveness in high-volume Latin American tenders. GlaxoSmithKline represents the specialized adjuvant archetype commanding preference in European procurement frameworks. Among emerging-market challengers, Serum Institute of India Pvt. Ltd. sits within the price-aggressive prequalification-seeker category navigating extended WHO review timelines for intramuscular formulations.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Serum Institute of India Pvt. Ltd. |
| Xiamen Innovax Biotech Co., Ltd. |
| Walvax Biotechnology Co., Ltd. |
| Sanofi S.A. |
| AstraZeneca Plc |
| Bharat Biotech |
| Inovio Pharmaceuticals, Inc. |
| Others |
Pricing and Supply Chain Analysis
WHO prequalification status gates both supplier qualification for Gavi-subsidized tenders and the price premiums manufacturers can command in emerging markets, creating a dual-filter that concentrates procurement power among validated originators while compressing margins for aspirants locked in extended review cycles.
Pricing Analysis
Public-sector procurement anchors a three-tier pricing structure across premium, standard, and economy levels, with Merck and GSK commanding adjuvant-technology premiums in European EMA frameworks while Serum Institute competes on unit economics in price-sensitive Indian tenders. Price differentiation hinges on cold-chain specification and WHO prequalification status. Cost compression in the standard tier intensifies as Chinese developers advance CHO-based candidates through Phase III, eroding yeast-platform manufacturing advantages. Government immunization programs exhibit highest price sensitivity, while private pharmacy channels in São Paulo and Texas absorb modest premiums for adult catch-up convenience.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient and fill-finish capacity for aluminum-adjuvanted formulations, with the United States and Belgium hosting bulk VLP production for originator supply. The supply chain draws from pharmaceutical-grade aluminum salts concentrated among three specialty chemical producers, plus yeast and insect-cell culture media. Single-source vulnerability in adjuvant inputs creates price volatility exposure. Distribution runs through Gavi-coordinated procurement networks reaching Indonesia and Vietnam, complemented by direct national immunization program contracts in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story, where decades-optimized manufacturing platforms and validated pharmacovigilance systems create switching costs that freeze out aspirants regardless of price competitiveness.
For Market Incumbents: Fortify manufacturing scale advantages through capacity reconfiguration between 4-valent and 9-valent product lines, locking in high-volume Latin American tenders before CHO-based competitors achieve WHO prequalification. Deepen backward integration into aluminum adjuvant supply to neutralize input price volatility from specialty chemical producers. For New Entrants and Emerging Players: Anchor in thermostable formulation development targeting sub-Saharan Africa last-mile distribution, where cold-chain infrastructure gaps create procurement preference for novel delivery technologies. Pursue subcutaneous route validation through EMA centralized procedures to capture European adjuvant-preference premiums without replicating Merck's billion-dollar yeast facility investments. For Investors and Strategic Acquirers: FDA labeling harmonization reshapes the acquisition landscape by accelerating cycle times for approved products while tightening evidentiary standards for new entrants. Target prequalified manufacturers with established Gavi tender access over Phase III aspirants facing 24-36 month WHO review timelines. Watch for national immunization technical advisory group recommendations on gender-neutral coverage expansion as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks Gavi-subsidized procurement in Indonesia and Vietnam national immunization programs. |
| CHO Platform Investment | Decomposes yeast manufacturing cost advantages held by Merck in high-volume tenders. |
| Thermostable Formulation Development | Enables last-mile distribution through existing EPI infrastructure in sub-Saharan Africa. |
| Gender-Neutral Label Expansion | Doubles addressable denominators in Brazil and Mexico adolescent coverage mandates. |
| Adjuvant Technology Licensing | Captures preferential tender scoring in EMA procurement frameworks weighting immunogenicity data. |
Research Methodology
A standing panel of regulatory affairs leads, national immunization program directors, Gavi procurement specialists, and hospital pharmacy managers provided ongoing calibration across primary interview cycles, with secondary validation drawing from FDA filings, EMA centralized procedure assessments, WHO prequalification databases, and ClinicalTrials.gov protocol records. Bottom-up tender volume aggregation and top-down manufacturer capacity estimates underwent iterative reconciliation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning product maturity stage, administration route, age cohort, and regional regulatory cluster. CAGRs derived from manufacturer-reported capacity utilization and national immunization program procurement schedules, incorporating dose-schedule compression effects from two-dose and single-dose protocol transitions.
Material uncertainties — WHO prequalification timeline extensions, aluminum adjuvant supply disruptions, national immunization technical advisory group recommendation shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Gavi partnership expansion and gender-neutral coverage mandate adoption. Recalibration cycles align with material shifts in procurement framework evolution and regulatory pathway updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Alectinib Drugs Market