
 Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market | 2026-2036
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market Foresight
Biologics manufacturing capacity in South Korea is shifting toward mammalian cell culture platforms capable of producing antibody-drug conjugates at commercial scale. Samsung Biologics leverages its Songdo campus to anchor large-volume bioreactor output for global pharmaceutical clients. Lonza Group sustains specialized positions in microbial expression and cell-and-gene therapy modalities across Swiss and US facilities. WuXi Biologics competes through integrated discovery-to-commercial platforms that span China and Ireland.
Contract Development and Manufacturing Organization outsourcing encompasses the transfer of pharmaceutical development, analytical validation, and commercial production from sponsor companies to third-party service providers, typically governed by master service agreements that define quality metrics, intellectual property boundaries, and regulatory filing responsibilities. Drug Substance Development commands premium pricing due to complex cell line engineering and process optimization requirements, while Single-use Systems manufacturing technology leads capital efficiency by eliminating stainless steel cleaning validation cycles. Biopharmaceutical Companies represent the dominant client type, though Biotechnology Startups generate faster growth in early-phase clinical supply contracts.
FDA, EMA, and China's NMPA enforce divergent chemistry-manufacturing-controls documentation standards that determine market access timelines and facility inspection frequencies for CDMO operators. The EU AI Act and FDA's advancing digital validation guidance are introducing algorithmic quality control requirements that reshape analytical services procurement. Stakeholders must monitor regulatory divergence between major agencies to anticipate where compliance investments will concentrate and which manufacturing jurisdictions will gain competitive clearance advantages.
Market Dynamics
Biologics complexity is forcing pharmaceutical sponsors to externalize manufacturing risk, with antibody-drug conjugates and cell-and-gene therapies requiring specialized capabilities that strain in-house capital budgets. This structural dependency on external partners is reshaping contract negotiation terms and facility investment patterns.
Growth Catalysts
- FDA Quality-by-Design Framework:The agency's enhanced chemistry-manufacturing-controls documentation standards push sponsors toward CDMOs with established regulatory filing track records and pre-approved inspection histories.
- Antibody-Drug Conjugate Demand:Oncology pipelines concentrate on cytotoxic payload conjugation, requiring mammalian cell culture platforms with containment infrastructure that few pharmaceutical firms maintain internally.
- Switzerland Manufacturing Cluster:Basel-Zurich corridor investments in microbial expression and cell-and-gene therapy modalities attract sponsor companies seeking proximity to European regulatory expertise.
Market Restraints
- Stainless Steel Equipment Cost Volatility:Nickel alloy price fluctuations and extended lead times for custom bioreactor fabrication compress project margins for capital-intensive mammalian cell culture facilities.
- South Korean Supply Concentration:Three facilities control over half of global large-volume biologics capacity, creating geographic risk exposure for sponsors dependent on single-source commercial supply.
- EMA Facility Inspection Backlogs:Extended queue times for initial and re-inspection approvals delay product launch timelines and extend working capital cycles for contract manufacturers.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's streamlined biosimilar approval pathways and production-linked incentive schemes for biotechnology infrastructure attract early-stage capacity investments.
- Continuous Manufacturing Convergence:Integration of perfusion cell culture with real-time quality analytics enables smaller-footprint facilities with faster batch turnaround.
- EU AI Act Compliance Services:Algorithmic validation requirements for automated process control create new analytical services revenue streams for CDMOs with digital quality systems.
Industry Challenges
- Cell Line Development Talent Scarcity:Shortages of experienced molecular biologists with CRISPR engineering and clone selection expertise extend early-phase timelines.
- Multi-Product Facility Cross-Contamination Risk:Campaign changeover protocols for antibody-drug conjugates require extensive cleaning validation that strains operational throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market |
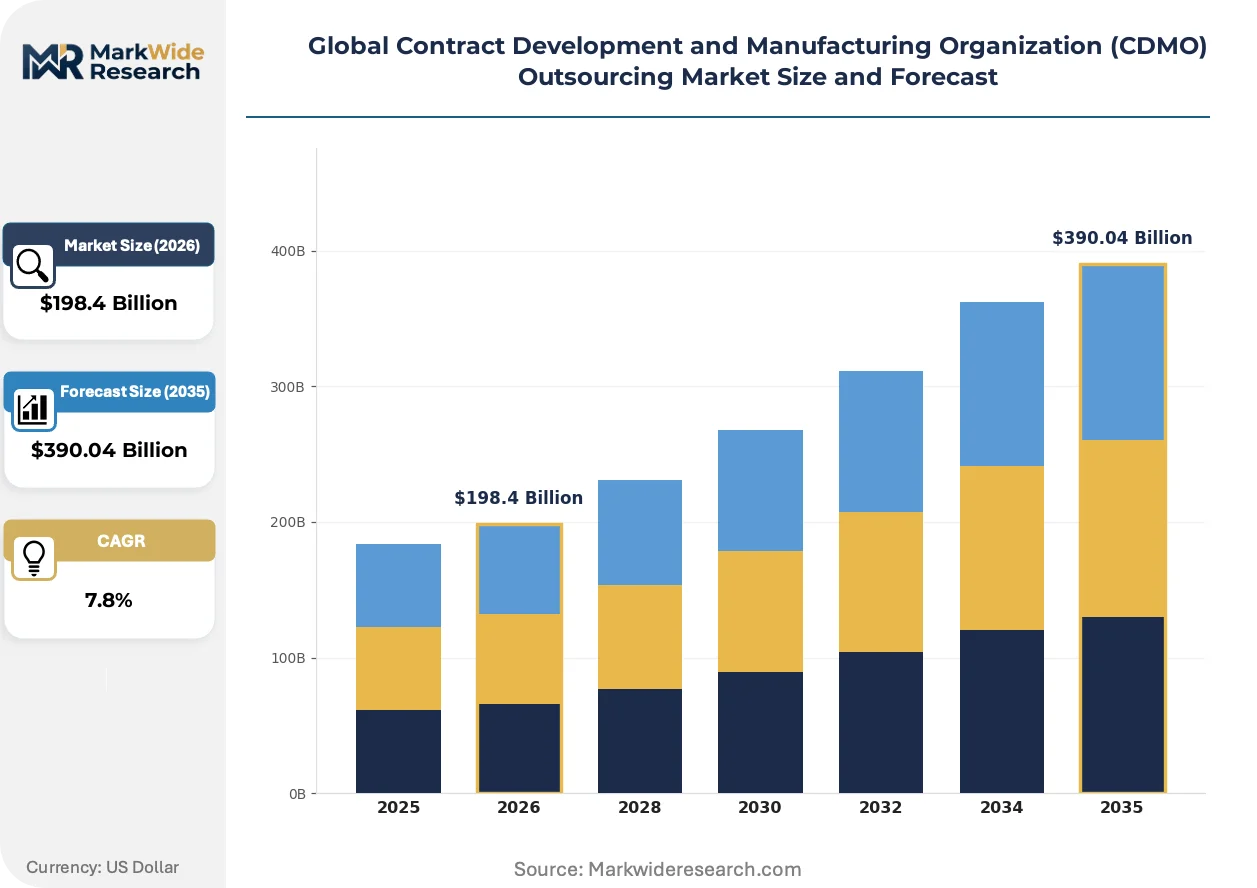
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $390.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drug Substance Development, Drug Product Manufacturing, Analytical Services, Regulatory Support, Clinical Trial Supply Therapy Area: Oncology, Cardiovascular, Central Nervous System, Infectious Diseases, Respiratory, Autoimmune Client Type: Biopharmaceutical Companies, Small Molecule Developers, Generic Manufacturers, Biotechnology Startups, Nutraceutical Firms Manufacturing Technology: Bioreactors, Fill & Finish, Lyophilization, Continuous Manufacturing, Single-use Systems |
| Companies Covered | Samsung Biologics, Boehringer Ingelheim International, Lonza Group, WuXi Biologics, Siegfried, Thermo Fisher Scientific, IQVIA, Fujifilm Biotechnologies, Catalent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market Shifts & Advancements
Process intensification technologies and regulatory digitization are compressing development timelines while elevating quality system requirements. These forces favor CDMOs with integrated analytical capabilities and automated manufacturing platforms.
Single-use bioreactor systems are consolidating market share in clinical and commercial mammalian cell culture. Biopharmaceutical sponsors with limited capital deployment capacity adopt disposable technologies to avoid stainless steel cleaning validation cycles. This shift is consolidating procurement decisions around bag-and-filter suppliers with validated extractables profiles.
EMA's advancing good manufacturing practice guidance on continuous process verification is mandating real-time release testing for commercial biologics. Contract manufacturers must integrate process analytical technology sensors with quality management systems. European facilities with legacy batch-release protocols face retrofit investments to maintain regulatory compliance.
Sponsor companies are unbundling discovery, development, and commercial manufacturing across multiple contract partners. Biotechnology startups fragment procurement across specialized cell line developers, clinical supply CDMOs, and commercial-scale manufacturers. This pattern concentrates in the United States, where venture-backed firms prioritize speed over vertical integration.
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market Segmentation
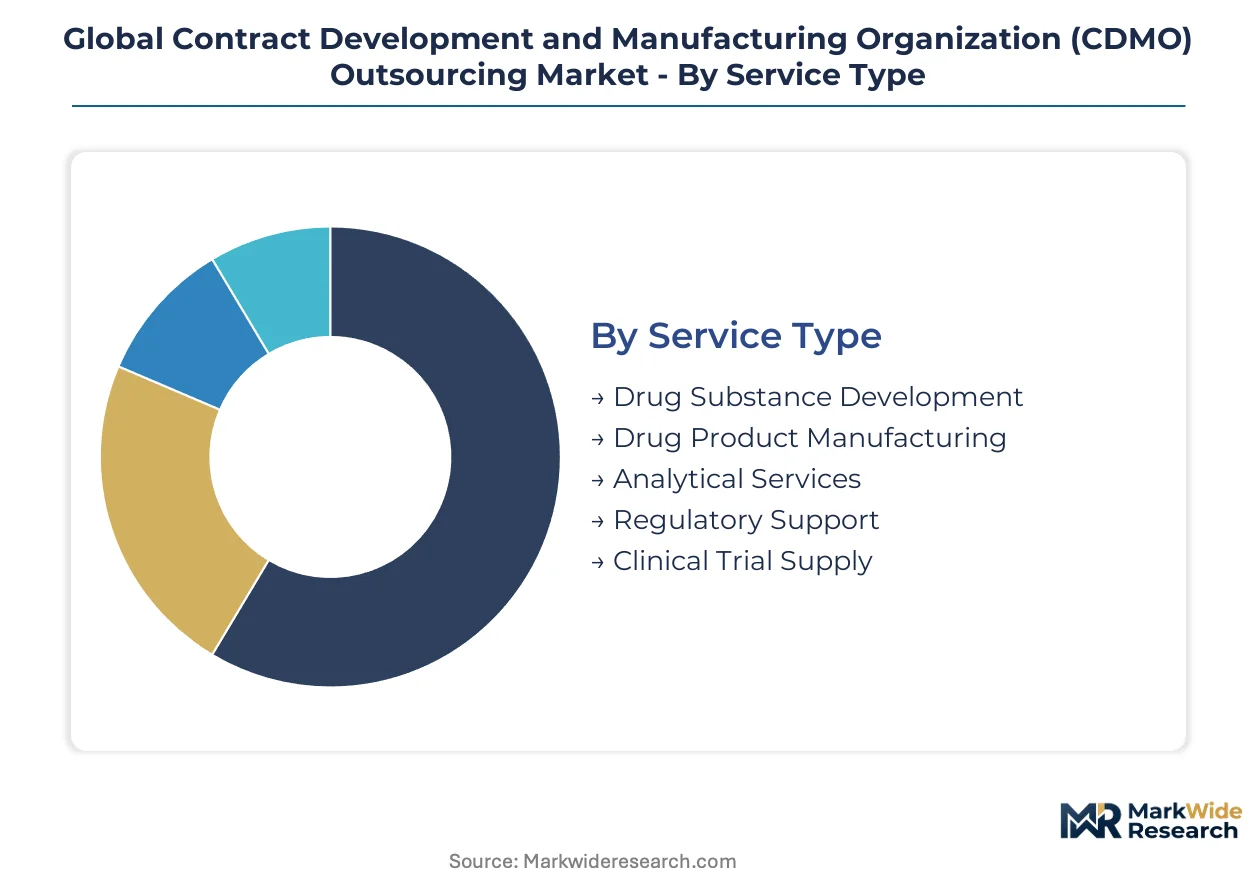
CDMO procurement decisions fragment across service depth, therapeutic specialization, and manufacturing modality. Each segmentation axis carries distinct margin profiles and capital requirements that determine competitive positioning.
Service Type:
Capital intensity peaks in segments requiring specialized containment infrastructure and extended process validation timelines.
- Drug Substance Development:Cell line engineering, upstream process optimization, and master cell bank establishment demand multi-year development cycles. Oncology sponsors in the United States concentrate procurement here due to complex antibody-drug conjugate requirements and FDA chemistry-manufacturing-controls scrutiny.
- Drug Product Manufacturing:Sterile fill-finish operations and formulation development for parenteral delivery command premium pricing. Swiss facilities near Basel draw European biopharmaceutical clients seeking proximity to EMA regulatory expertise and just-in-time supply chains.
- Analytical Services:Method development, stability testing, and release assays support quality-by-design frameworks.
- Regulatory Support:Chemistry-manufacturing-controls documentation and agency filing preparation accelerate approval timelines.
- Clinical Trial Supply:Comparator sourcing, packaging, and distribution for investigational phases.
Most installed capacity flows through Drug Product Manufacturing. Expansion is steepest in Drug Substance Development.
Therapy Area:
Clinical pipeline concentration and reimbursement dynamics determine which therapeutic categories absorb the highest contract manufacturing premiums.
- Oncology:Antibody-drug conjugates, bispecific antibodies, and cell therapies require mammalian cell culture platforms with cytotoxic containment. South Korean facilities in Songdo anchor commercial-scale production for global pharmaceutical sponsors facing MFDS and FDA dual-filing requirements.
- Autoimmune:Monoclonal antibody blockers and emerging bispecific formats drive demand for high-titer cell line development. Ireland-based operations serve European and North American sponsors seeking EMA-aligned manufacturing with English-language regulatory documentation.
- Cardiovascular:Recombinant proteins and peptide therapeutics for metabolic indications.
- Central Nervous System:Blood-brain barrier penetration challenges favor specialized formulation partnerships.
- Infectious Diseases:Vaccine bulk manufacturing and pandemic preparedness contracts.
- Respiratory:Inhaled biologics and nebulized formulations requiring specialized device integration.
Contract value concentrates in Oncology. Autoimmune is gaining share fastest among emerging biologics categories.
Client Type:
Balance sheet capacity and risk tolerance separate clients seeking full-service partnerships from those fragmenting procurement across specialized vendors.
- Biopharmaceutical Companies:Large-cap sponsors with approved portfolios outsource commercial manufacturing to free capital for R&D. They prioritize CDMOs with FDA pre-approval inspection histories and multi-product facility flexibility in the United States and Switzerland.
- Biotechnology Startups:Venture-backed firms lack internal manufacturing infrastructure and demand speed-to-clinic above cost optimization. They cluster procurement in Boston-San Francisco corridor CDMOs with integrated discovery-to-IND platforms.
- Small Molecule Developers:Traditional pharmaceutical chemistry requiring high-pressure hydrogenation and controlled substance handling.
- Generic Manufacturers:Cost-optimized biosimilar production with emphasis on yield improvement and regulatory parity.
- Nutraceutical Firms:Dietary supplement and functional food ingredient manufacturing with lower compliance thresholds.
Biopharmaceutical Companies anchor existing capacity utilization. Biotechnology Startups are expanding most quickly in early-phase clinical supply.
Manufacturing Technology:
Equipment depreciation schedules and cleaning validation burdens determine which technology platforms attract capital deployment.
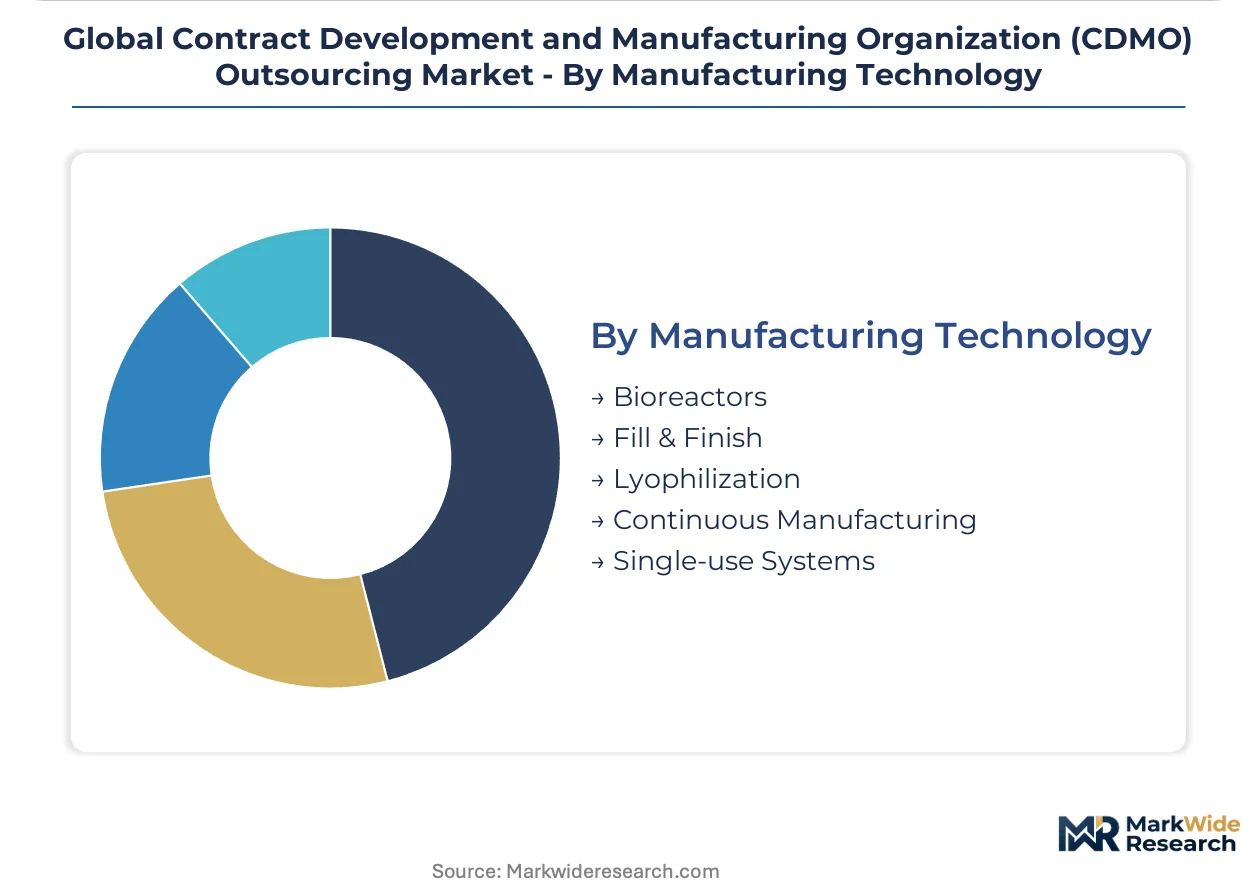
- Single-use Systems:Disposable bioreactors, mixing bags, and sterile connectors eliminate stainless steel cleaning validation and campaign changeover downtime. Biopharmaceutical sponsors with limited capital budgets in the United States and Europe favor this modality for clinical and early commercial phases.
- Continuous Manufacturing:Perfusion cell culture integrated with real-time process analytical technology enables smaller-footprint facilities with faster batch turnaround. EMA's advancing good manufacturing practice guidance on continuous process verification is mandating adoption for new commercial filings in Europe.
- Bioreactors:Stainless steel and single-use vessel systems for upstream cell culture expansion.
- Fill & Finish:Aseptic processing for final drug product vialing and packaging.
- Lyophilization:Freeze-drying for thermally sensitive biologics requiring extended shelf stability.
Single-use Systems dominate new capacity installations. Continuous Manufacturing is climbing the fastest among next-generation platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting biologics manufacturing investment toward jurisdictions with streamlined chemistry-manufacturing-controls pathways and production-linked incentive schemes. Sponsors now site commercial capacity where FDA, EMA, and NMPA filing efficiencies converge with government-backed infrastructure support.
United States
FDA's quality-by-design framework and pre-approval inspection histories attract commercial-stage outsourcing for antibody-drug conjugates. The Boston-San Francisco corridor anchors integrated discovery-to-IND platforms serving venture-backed biotechnology startups. Massachusetts and California facilities concentrate mammalian cell culture capacity for oncology sponsors requiring rapid clinical supply turnaround.
Switzerland
Swissmedic-aligned regulatory expertise and proximity to EMA headquarters draw European biopharmaceutical commercial manufacturing decisions. The Basel-Zurich corridor specializes in microbial expression and cell-and-gene therapy modalities with multi-product facility flexibility. Canton Basel-Stadt facilities serve sponsors seeking just-in-time supply chains with English-language documentation standards.
South Korea
MFDS dual-filing capabilities and government-backed biologics clusters concentrate large-volume mammalian cell culture capacity for global pharmaceutical clients. The Songdo district anchors 200,000-liter bioreactor installations serving oncology sponsors with FDA and EMA parallel submission requirements. Incheon Free Economic Zone incentives support continuous manufacturing technology adoption for perfusion cell culture platforms.
India
CDSCO streamlined biosimilar approval pathways and production-linked incentive schemes for biotechnology infrastructure attract early-stage capacity investments. Karnataka and Telangana states host mammalian cell culture facilities targeting cost-optimized biosimilar production for emerging markets. Hyderabad's Genome Valley cluster concentrates process development talent for cell line engineering and upstream optimization services.
Ireland
EMA-aligned manufacturing with English-language regulatory documentation attracts North American sponsors seeking European commercial supply. Dublin and Cork regions host drug substance and drug product facilities serving autoimmune and oncology therapeutic categories. IDA Ireland tax incentives and skilled bioprocessing workforce availability support continuous manufacturing platform investments.
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cell-and-gene therapy specialization and continuous manufacturing platform differentiation. Market structure consolidates around three capability tiers: large-volume mammalian cell culture specialists, integrated discovery-to-commercial platform operators, and niche microbial expression providers. Strategic archetypes include scale-driven commodity manufacturers, technology-differentiated platform companies, and regulatory-navigation service bundlers. Dominant competitive moves center on multi-product facility flexibility investments and strategic partnerships for algorithmic quality control capabilities.
Within the large-volume biologics tier, Samsung Biologics exemplifies scale-driven positioning through its Korean corporate structure. Lonza Group represents Swiss-based specialization across microbial and cell-and-gene therapy modalities. WuXi Biologics occupies the integrated platform archetype with China-rooted discovery-to-commercial service bundling.
| Leading Market Players |
|---|
| Samsung Biologics |
| Boehringer Ingelheim International |
| Lonza Group |
| WuXi Biologics |
| Siegfried |
| Thermo Fisher Scientific |
| IQVIA |
| Fujifilm Biotechnologies |
| Catalent |
| Others |
Supply & Pricing Matrix
Oncology sponsors demanding antibody-drug conjugate manufacturing with cytotoxic containment infrastructure are consolidating procurement around CDMOs with validated mammalian cell culture platforms and dual FDA-EMA filing histories. This buyer concentration elevates pricing power for contract manufacturers with established regulatory track records while squeezing margins for facilities lacking specialized containment capabilities.
Pricing Analysis
Direct-to-sponsor contracting with volume-based discounts dominates the CDMO pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates dedicated facility campaigns from multi-product suites and shared equipment batches. Price differentiation rests on GMP certification tier and clinical versus commercial scale. Cost compression in early-phase clinical supply is intensifying because biotechnology startups prioritize speed-to-clinic over cost optimization. Biotechnology startups show highest price sensitivity; large-cap biopharmaceutical companies prioritize regulatory assurance over unit economics.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive biologics and specialized freight for cytotoxic materials anchor supply chain economics. Manufacturing capacity concentrates in South Korea, Switzerland, and the United States for large-volume mammalian cell culture. Raw material dependencies include cell culture media, single-use bioreactor bags, and chromatography resins. Single-source vulnerability in South Korean large-volume biologics capacity creates geographic concentration risk. Distribution runs through direct sponsor-CDMO master service agreements with just-in-time clinical supply and scheduled commercial batch release.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CDMO outsourcing market functions as a stable compounder anchored by irreversible biologics complexity that perpetuates external manufacturing dependency. FDA quality-by-design mandates and EMA continuous process verification requirements institutionalize demand for specialized contract manufacturing capabilities.
For Market Incumbents: Extend multi-product facility flexibility investments to capture fragmented procurement from biotechnology startups unbundling discovery, development, and commercial manufacturing. Deepen regulatory filing expertise across FDA, EMA, and MFDS jurisdictions to defend against emerging entrants with single-agency specialization. Prioritize continuous manufacturing platform retrofits to maintain EMA compliance as legacy batch-release protocols face obsolescence.
For New Entrants and Emerging Players: Single-use system integration with real-time process analytical technology offers a technology-first wedge into early-phase clinical supply contracts where capital-constrained sponsors prioritize disposable infrastructure. White-space targets include cell-and-gene therapy modalities with limited existing capacity and India's emerging biosimilar manufacturing cluster under CDSCO streamlined approval pathways. A go-to-market angle emphasizing algorithmic quality control capabilities addresses EU AI Act compliance requirements that incumbent facilities are slow to adopt.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated discovery-to-commercial platform operators with China-rooted cost structures and Western regulatory filing capabilities. Long-term viability over a multi-year horizon favors CDMOs with mammalian cell culture specialization for oncology and autoimmune therapeutic categories. Acquisition target archetype: mid-scale facilities with FDA pre-approval inspection histories and underutilized capacity in the Boston-San Francisco corridor. The signal to watch is MFDS inspection queue clearance rates as an indicator of South Korean supply concentration risk realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Platform Investment | EMA's advancing GMP guidance on continuous process verification mandates real-time release testing adoption. |
| Cell-and-Gene Therapy Capacity Buildout | Specialized viral vector manufacturing and electroporation capabilities address pipeline concentration in personalized medicine. |
| Regulatory Filing Capability Expansion | Dual FDA-EMA submission expertise attracts oncology sponsors with parallel commercial launch requirements. |
| Single-Use System Technology Adoption | Disposable bioreactor platforms eliminate cleaning validation cycles and accelerate campaign changeover for clinical supply. |
| Algorithmic Quality Control Development | EU AI Act compliance for automated process control creates differentiated analytical services revenue streams. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's biopharmaceutical manufacturing clusters. The approach combines primary interviews with drug development executives, regulatory affairs leads, and CDMO procurement managers with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and customs trade data. Bottom-up facility capacity assessments and top-down sponsor outsourcing spend estimates undergo triangulation to reconcile supply-side and demand-side perspectives.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. The analytical framework models segmentation dimensions including service type, therapeutic area, client type, and manufacturing technology alongside regional regulatory cluster variations. CAGRs derive from facility expansion announcements, sponsor pipeline disclosures, and regulatory filing velocity trends. Forecast inputs incorporate cell line development timeline benchmarks and single-use system adoption curves.
The model holds under stable regulatory divergence between FDA, EMA, and NMPA; deviation in accelerated harmonization or sudden inspection backlog clearance would shift capacity investment patterns. Forecasts reflect assumptions about continued biologics pipeline concentration in oncology and sustained venture capital deployment into biotechnology startups. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
CMO/CDMO Market