
 Pharmaceutical Anti-Counterfeiting Technologies Market | 2026-2036
Pharmaceutical Anti-Counterfeiting Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Anti-Counterfeiting Technologies Market Analysis
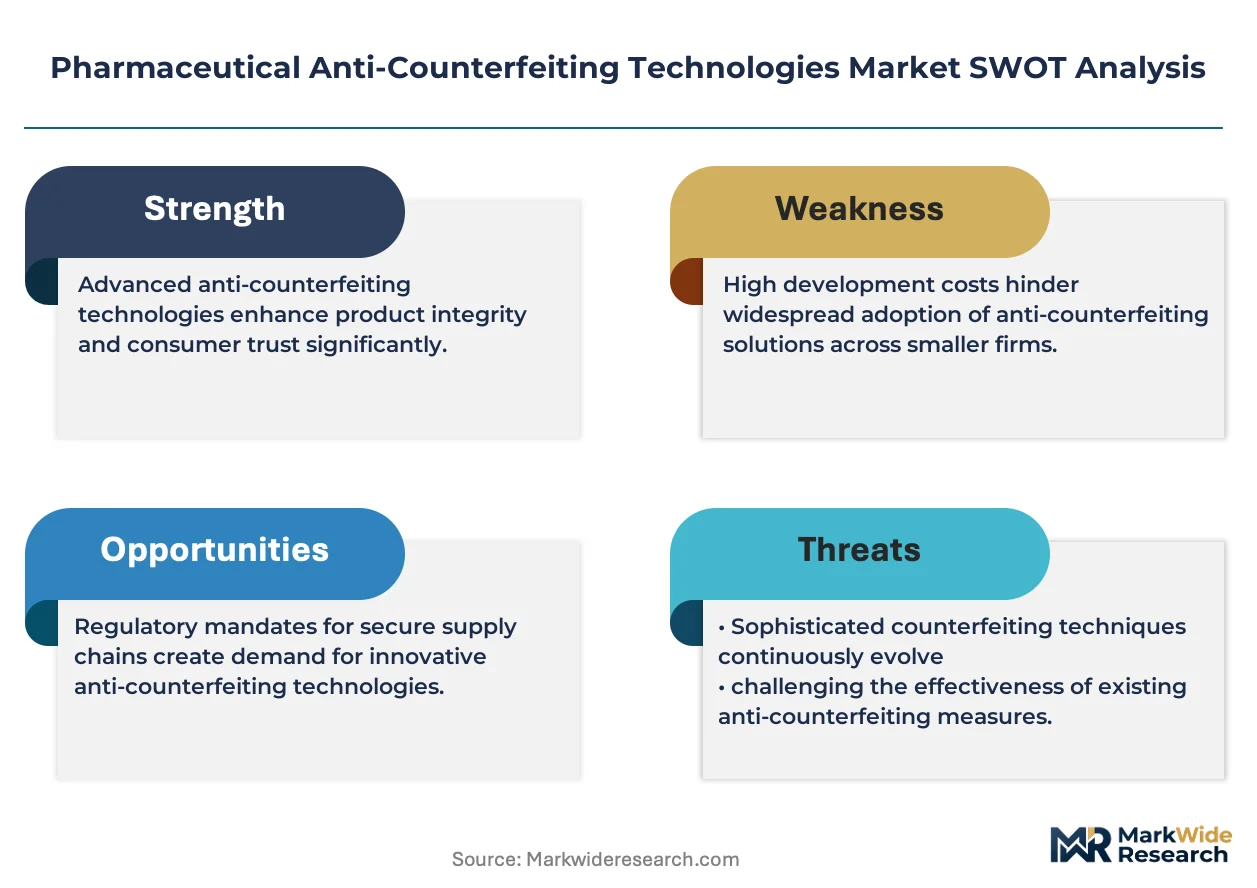
Modular authentication—separating overt holographic labels from covert forensic taggants—is decoupling what buyers purchase from how they deploy it. SICPA Holdings SA leverages its ink chemistry expertise to anchor high-security tax stamp and pharma authentication supply chains across multiple continents. Authentix specializes in layered security architectures that combine physical markers with digital verification, allowing it to compete on implementation flexibility rather than single-feature dominance.
Pharmaceutical anti-counterfeiting technologies encompass physical, chemical, and digital systems engineered to verify product authenticity, with specifications ranging from sub-micron forensic taggants readable only by laboratory instruments to item-level RFID inlays operating at 860-960 MHz UHF bands for automated supply chain scanning. Their primary commercial purpose is to intercept falsified medicines before they reach patients while creating evidentiary trails for enforcement action. Track and trace systems now dominate capital expenditure flows as regulatory deadlines harden, while hologram adoption matures into a baseline rather than differentiating feature across packaging portfolios. RFID occupies a narrower but higher-margin niche where cold-chain biologics require real-time environmental and location verification beyond simple authentication.
The FDA's Drug Supply Chain Security Act and the EU's Falsified Medicines Directive together reshape product standards by mandating unit-level serialization, with the EMA enforcing verification architecture requirements that lock non-compliant manufacturers out of legitimate distribution channels. Health Canada and the TGA in Australia have begun harmonizing their pedigree requirements with these frameworks, extending compliance gravity beyond the originating jurisdictions. Stakeholders must now decide whether to build interoperable verification platforms capable of spanning multiple regulatory regimes or to accept fragmented regional systems that inflate operational complexity.
Market Dynamics
Serialization mandates from the FDA and EMA are compressing implementation timelines, forcing wholesale distributors to replace batch-level verification with unit-level track-and-trace infrastructure before statutory deadlines arrive.
Growth Catalysts
- FDA Drug Supply Chain Security Act:The 2023 enforcement deadline for lot-level tracing compelled wholesale distributors to upgrade verification systems, creating concentrated procurement cycles for serialization hardware.
- Biologics cold-chain requirements:Temperature-sensitive biologics manufacturers now embed RFID inlays operating at 860-960 MHz UHF bands directly into vial packaging rather than relying solely on carton-level authentication.
- India's pharmaceutical export sector:Domestic manufacturers supplying regulated markets in North America and Europe are pre-emptively adopting EU Falsified Medicines Directive standards to maintain market access.
Market Restraints
- Specialized substrate costs:Holographic and color-shifting inks require proprietary metallized films whose supply concentrates among European specialty chemical suppliers, creating input cost volatility.
- Interoperability fragmentation:Divergent national data formats between the FDA's EPCIS standards and EMA's EMVS verification architecture force manufacturers to maintain parallel serialization systems.
- Legacy packaging line retrofitting:Existing carton printing and labeling equipment lacks the precision for 2D Data Matrix serialization, requiring complete line replacement rather than modular upgrades.
Strategic Opportunities
- Blockchain-anchored verification:Distributed ledger technology combined with cryptographic product identifiers is creating tamper-evident audit trails that extend beyond regulatory minimums into brand protection.
- Over-the-counter pharmaceutical segment:Consumer-facing authentication apps using smartphone-readable covert markers remain underdeployed relative to prescription drug serialization, representing white-space demand.
- Brazil's ANVISA serialization roadmap:The phased implementation timeline for the country's national medicine control system creates predictable procurement windows for verification infrastructure vendors.
Industry Challenges
- Serialization data management talent:The shortage of professionals capable of integrating EPCIS repository systems with enterprise ERP platforms is delaying compliance project timelines.
- Multi-jurisdiction certificate harmonization:Manufacturers must simultaneously satisfy FDA 21 CFR Part 11, EU GMP Annex 11, and WHO good distribution practice requirements for electronic records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Anti-Counterfeiting Technologies Market |
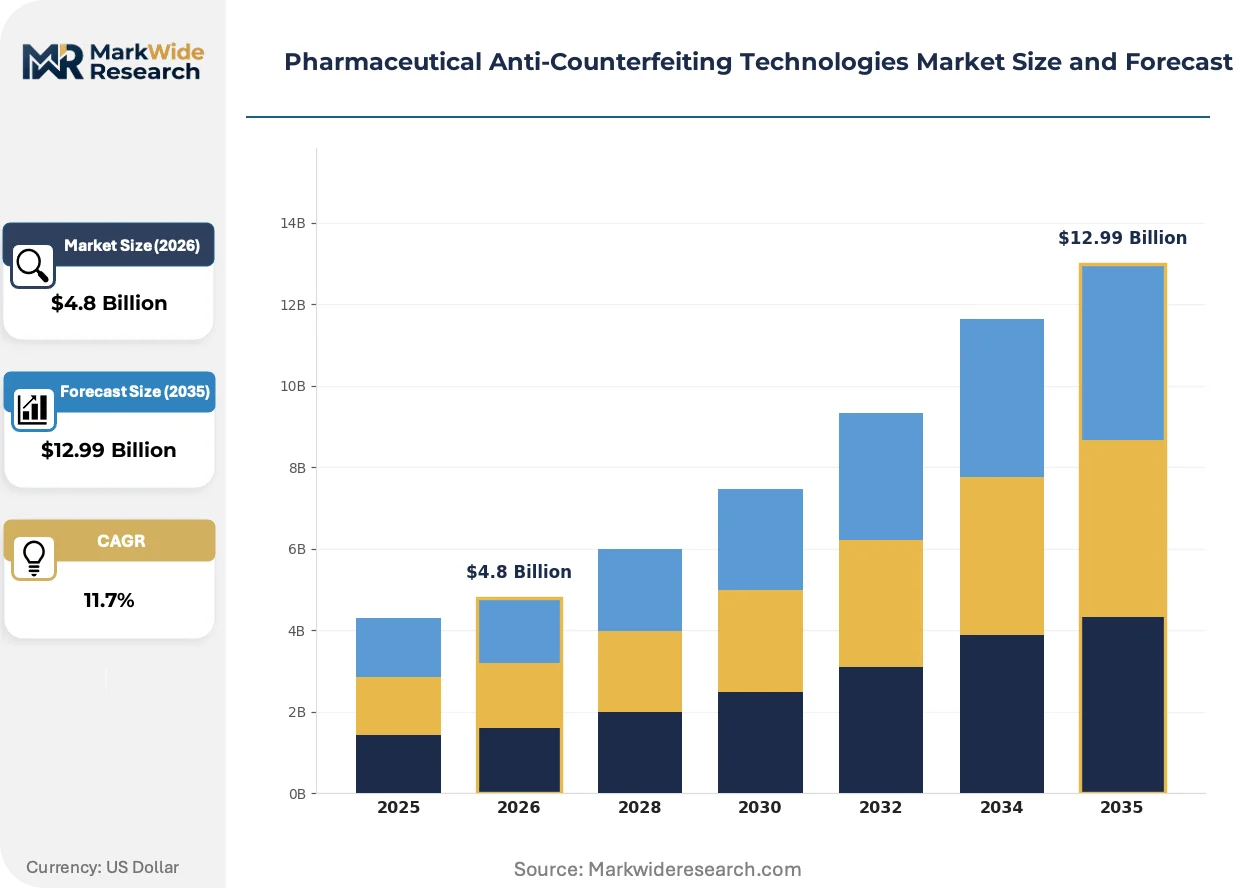
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Holograms, Watermarks, RFID, Track & Trace Product Type: Labels, Inks, Packaging, Security Features End User: Pharmaceutical Manufacturers, Regulatory Authorities, Distributors, Retailers Application: Antitheft Measures, Brand Protection, Market Surveillance, Consumer Safety |
| Companies Covered | SICPA Holdings SA, Avery Dennison, 3M, AlpVision, TraceLink, Zebra Technologies, Authentix, Inksure Technologies, Alien Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Anti-Counterfeiting Technologies Market Emerging Trajectories
Authentication technology is bifurcating between visible consumer-facing markers and machine-readable supply-chain verification, with deployment decisions increasingly separating brand protection from regulatory compliance functions.
Artificial intelligence-powered optical character recognition is automating the verification of serialized codes at distribution checkpoints, eliminating manual scanning bottlenecks. Third-party logistics providers in the United States are deploying these systems at warehouse receiving docks to meet FDA verification deadlines. The technology is automating compliance workflows that previously required dedicated quality assurance personnel, compressing operating costs for high-volume distributors.
The EU's Falsified Medicines Directive verification architecture now requires end-to-end authentication from manufacturer to dispensing pharmacy, with EMA enforcing technical standards that lock non-compliant products out of legitimate channels. Wholesale distributors must connect to the European Medicines Verification System by 2025 or forfeit authorization. Small and mid-sized generic manufacturers in Eastern Europe are consolidating serialization service contracts to spread compliance costs across product portfolios.
Hospital pharmacy procurement departments are consolidating authentication requirements into centralized tenders that specify both physical security features and digital verification capabilities. This bundling displaces the previous practice of separate packaging and IT procurement decisions. The shift is most visible in Germany's hospital sector, where regional purchasing cooperatives now mandate ISO 16678-compliant verification systems as a baseline qualification criterion.
Pharmaceutical Anti-Counterfeiting Technologies Market Segmentation
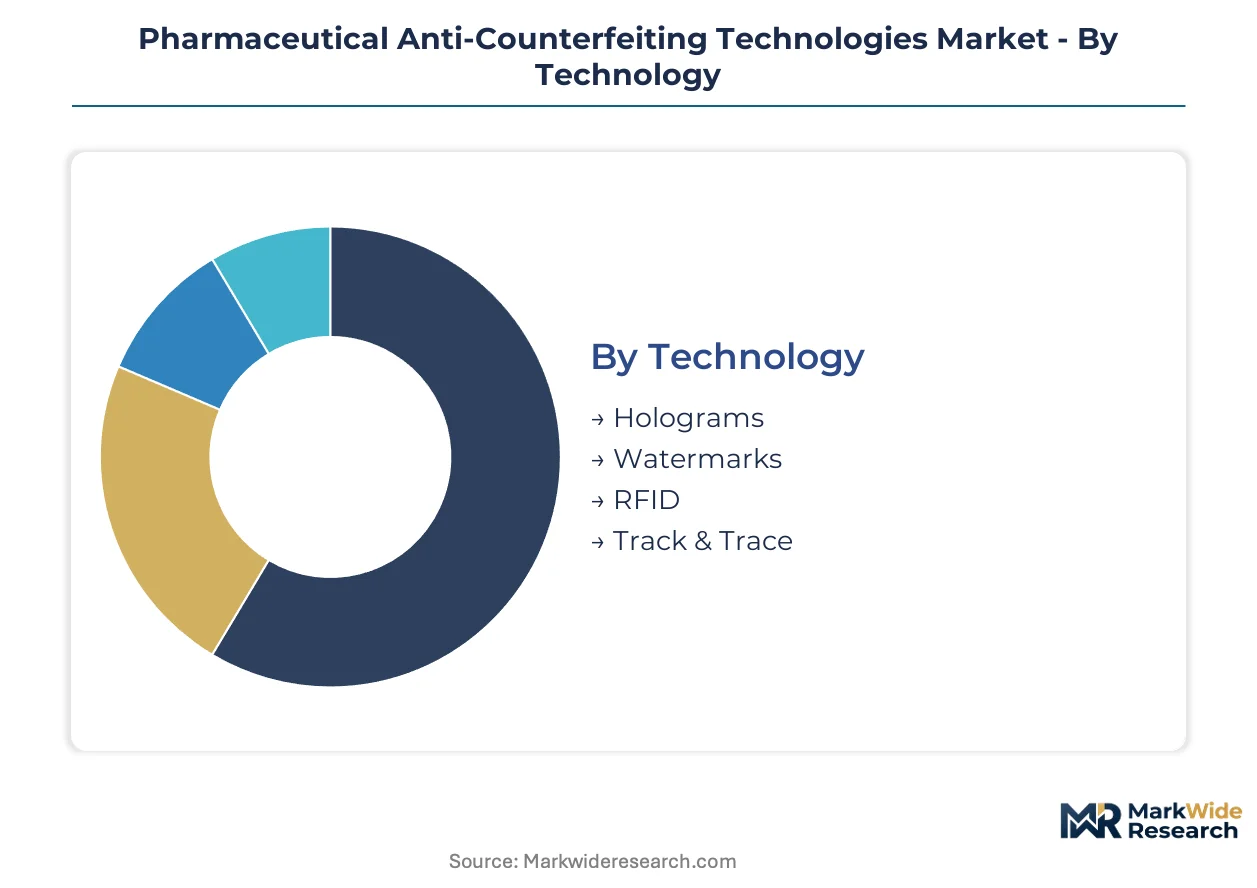
Technology choices in pharmaceutical anti-counterfeiting hinge on whether authentication operates at the packaging surface or integrates into supply-chain infrastructure. Procurement patterns diverge sharply between manufacturers seeking regulatory compliance and those layering brand protection atop baseline verification.
Technology:
RFID and track-and-trace systems embed directly into automated supply-chain infrastructure, while holograms and watermarks often deploy as standalone authentication markers without backend integration.
- Holograms:Opaque metallized films with diffraction patterns create visible authentication cues readable without specialized equipment. Demand concentrates among generic pharmaceutical manufacturers in India supplying regulated export markets, where hologram costs satisfy budget constraints for high-volume, low-margin products. FDA pedigree requirements have compressed hologram adoption timelines as manufacturers race to meet lot-level tracing mandates.
- Track & Trace:Unit-level serialization systems generate unique identifiers linked to centralized verification databases, requiring substantial IT infrastructure investment. Biologics manufacturers in the United States embed these systems at vial level rather than carton level to satisfy cold-chain integrity requirements under DSCSA enforcement. Integration complexity and data management talent scarcity constrain deployment speed.
- RFID:Inlays operating at 860-960 MHz UHF bands enable automated scanning without line-of-sight requirements. Temperature-sensitive biologics producers favor RFID for real-time environmental monitoring alongside location verification.
- Watermarks:Covert fiber patterns or digital watermarking embed authentication into substrate or printed imagery. Cost-sensitive applications in emerging markets deploy watermarks where holographic films prove prohibitively expensive.
Track & Trace leads volumes today; RFID is gaining share fastest.
Product Type:
Cost tiers separate premium security substrates from commodity authentication materials, with margin structures determining supplier consolidation patterns.
- Labels:Pressure-sensitive adhesives carry serialized 2D Data Matrix codes or holographic overlays, serving as the primary interface between physical product and digital verification systems. Pharmaceutical manufacturers in Germany specify ISO 16678-compliant label systems in centralized hospital procurement tenders.
- Packaging:Tamper-evident cartons and vial-level containers integrate multi-layer authentication from production through dispensing. Cold-chain biologics drive demand for packaging that combines thermal insulation with embedded RFID inlays.
- Inks:Color-shifting or taggant-laden formulations require proprietary metallized inputs from European specialty chemical suppliers. Input cost volatility constrains pricing flexibility for authentication service providers.
- Security Features:Forensic taggants readable only by laboratory instruments provide evidentiary-grade authentication for enforcement actions. High-value biologics and oncology therapeutics concentrate demand for sub-micron taggant integration.
Labels dominate procurement volumes; packaging is expanding most quickly.
End User:
Customer type determines whether authentication investment serves regulatory compliance, enforcement authority, or commercial differentiation objectives.
- Pharmaceutical Manufacturers:Brand-name and generic producers deploy authentication to satisfy FDA DSCSA and EU FMD serialization mandates while protecting market access. Indian export-oriented manufacturers pre-emptively adopt EU standards to maintain European distribution channels.
- Distributors:Wholesale operators in the United States upgrade verification infrastructure to meet lot-level tracing deadlines, creating concentrated procurement cycles for serialization hardware.
- Regulatory Authorities:FDA, EMA, and Health Canada mandate verification architecture standards that lock non-compliant products out of legitimate distribution. Enforcement agencies leverage forensic taggants for criminal prosecution evidence.
- Retailers:Hospital pharmacy procurement departments consolidate authentication requirements into centralized tenders specifying both physical and digital verification capabilities.
Pharmaceutical manufacturers account for the largest procurement volumes; distributors are climbing the fastest.
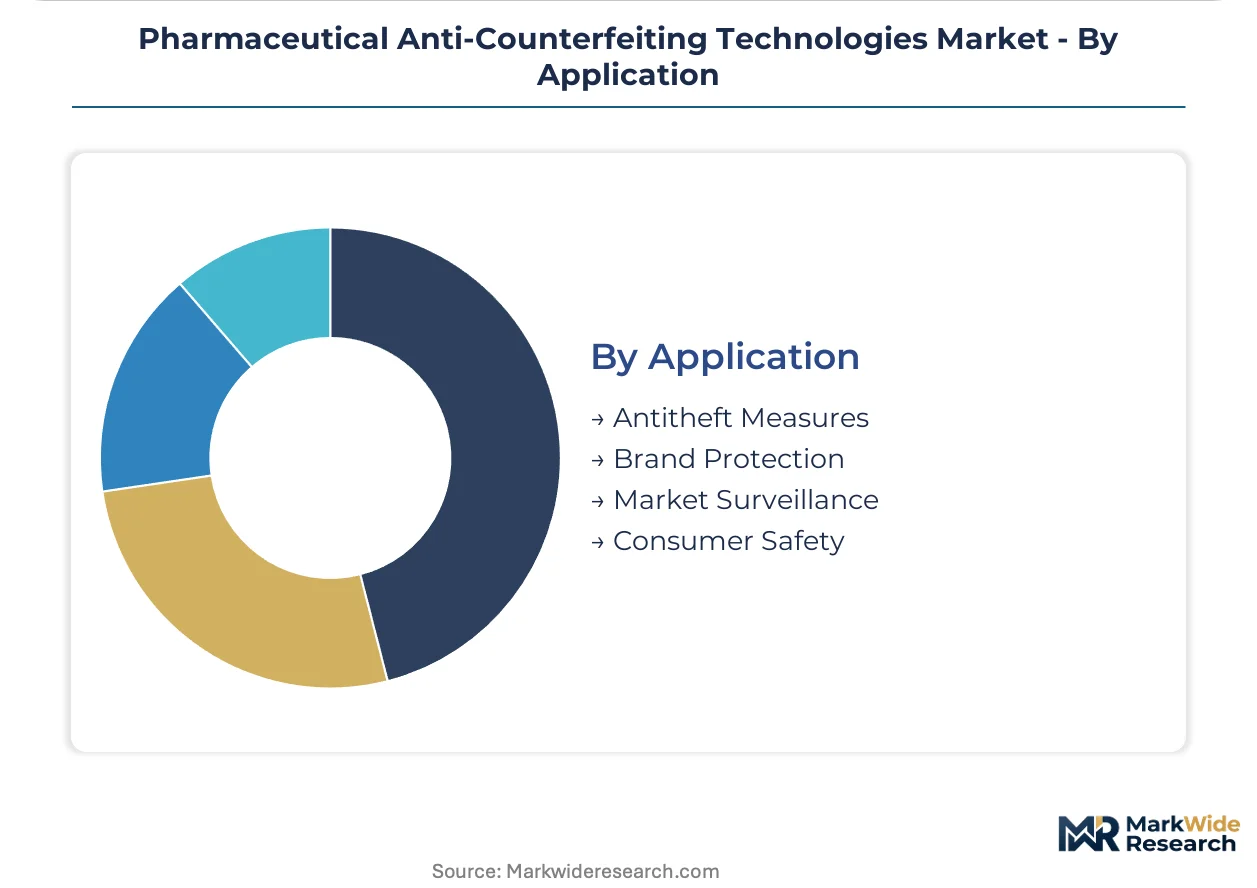
Application:
Maturity gradients separate established regulatory compliance applications from emerging consumer-facing deployment modes.
- Brand Protection:Authentication markers defend against revenue loss from falsified products entering parallel distribution channels. Luxury pharmaceutical brands in Switzerland deploy layered security architectures combining overt and covert features.
- Consumer Safety:Patient-facing verification systems prevent ingestion of falsified medicines through smartphone-readable authentication. Over-the-counter segments remain underdeployed relative to prescription drug serialization.
- Antitheft Measures:Tamper-evident features and serialized tracking deter diversion and cargo theft in high-risk distribution corridors.
- Market Surveillance:Verification data feeds enforcement intelligence on counterfeit distribution patterns and origin identification.
Brand protection leads application spending; consumer safety represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical anti-counterfeiting technologies originated in European security printing traditions before scaling through North American regulatory mandates. The industry's geographic footprint now tracks compliance gravity across major pharmaceutical manufacturing and distribution hubs.
United States
FDA Drug Supply Chain Security Act deadlines compress implementation timelines for wholesale distributors upgrading verification infrastructure. State-level pedigree laws in California and Florida created early procurement precedents that federal mandates now harmonize. The Philadelphia-New Jersey pharmaceutical corridor concentrates serialization service providers serving generic manufacturers.
Germany
Hospital pharmacy procurement cooperatives mandate ISO 16678-compliant verification systems as baseline qualification criteria. EMA enforcement of Falsified Medicines Directive standards locks non-compliant manufacturers out of legitimate European distribution. The Rhine-Ruhr industrial region hosts authentication ink specialists supplying metallized film substrates.
Switzerland
Luxury pharmaceutical brands deploy layered security architectures combining overt holographic markers with covert forensic taggants. Swissmedic maintains verification architecture requirements that exceed EU minima for domestic market access. Basel's biologics cluster embeds track-and-trace systems at vial level for cold-chain integrity.
India
Export-oriented generic manufacturers pre-emptively adopt EU Falsified Medicines Directive standards to maintain European distribution channels. CDSCO alignment with international serialization protocols accelerates domestic infrastructure investment. Gujarat's pharmaceutical manufacturing belt concentrates hologram adoption for high-volume, low-margin products.
Brazil
ANVISA's phased national medicine control system implementation creates predictable procurement windows for verification infrastructure vendors. Temperature-sensitive biologics distribution drives RFID adoption in São Paulo's hospital pharmacy networks. The country's pharmaceutical import dependency amplifies authentication requirements at port-of-entry inspection points.
Pharmaceutical Anti-Counterfeiting Technologies Market Vendor Landscape
The competitive structure tilts toward specialized security technology providers with chemistry and digital infrastructure capabilities. Market participants cluster around three strategic archetypes: ink chemistry specialists leveraging metallized film expertise, digital track-and-trace platform operators, and integrated packaging-automation vendors. Consolidation pressure concentrates among serialization service providers seeking geographic coverage, while technology licensing agreements proliferate between hardware manufacturers and software verification platforms.
Within the chemistry-anchored tier, SICPA Holdings SA exemplifies metallized ink specialists whose tax stamp heritage transfers to pharmaceutical authentication supply chains. Authentix occupies a position representing layered security architects combining physical markers with digital verification capabilities. Avery Dennison sits within the materials-science segment bridging adhesive label substrates with serialized data matrix integration.
| Leading Market Players |
|---|
| SICPA Holdings SA |
| Avery Dennison |
| 3M |
| AlpVision |
| TraceLink |
| Zebra Technologies |
| Authentix |
| Inksure Technologies |
| Alien Technology |
| Others |
Supply Flow & Price Mechanics
Proprietary metallized film substrates from European specialty chemical suppliers cascade through three distinct pricing tiers before reaching pharmaceutical manufacturers. Input cost volatility in these concentrated upstream markets compresses margins for authentication service providers while forcing tiered pricing stratification downstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates forensic-grade taggant integration from holographic overlays and basic watermarking. Price differentiation hinges on ISO 16678 certification status and serialization data management capabilities bundled with physical markers. Pricing pressure stems from wholesale distributor procurement consolidation in the United States as FDA deadlines compress implementation windows. Generic manufacturers in India exhibit highest price sensitivity, while Swiss biologics producers absorb premium tier costs for cold-chain integrity requirements.
Supply Chain Analysis
Dual-sourcing requirements mandated by EMA verification architecture force manufacturers to qualify parallel suppliers for serialized label substrates and RFID inlay components. Metallized ink production concentrates in Germany, Switzerland, and Belgium, while RFID chip fabrication draws from Taiwan, South Korea, and China. Single-source vulnerability persists in forensic taggant chemistry where sub-micron formulation expertise anchors in limited European facilities. Distribution runs through pharmaceutical wholesale networks in North America and hospital procurement cooperatives in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical anti-counterfeiting technologies constitute a late-cycle quality market where hospital procurement departments now mandate ISO 16678-compliant verification systems as baseline qualification criteria. This specification creep toward premium authentication architectures displaces commodity hologram suppliers.
For Market Incumbents: Deploy serialization platform consolidation to capture wholesale distributor upgrade cycles before statutory deadlines arrive. Incumbents should deepen backward integration into metallized film substrate production to defend against European specialty chemical supplier price volatility. Channel control through exclusive service contracts with India's export-oriented generic manufacturers locks out emerging authentication competitors.
For New Entrants and Emerging Players: Direct-to-manufacturer SaaS verification platforms offer the most penetrable route into mid-sized generic producers in Eastern Europe seeking to spread compliance costs across product portfolios. White-space demand concentrates in over-the-counter pharmaceutical segments where consumer-facing authentication apps remain underdeployed relative to prescription drug serialization. New entrants should pursue API-integration partnerships with existing label converters rather than building captive manufacturing capacity.
For Investors and Strategic Acquirers: Consolidation pressure builds where serialization service providers lack geographic coverage across FDA, EMA, and Health Canada regulatory jurisdictions. Long-term viability favors integrated platform operators combining physical authentication chemistry with digital verification infrastructure. Acquisition targets should display dual-competency in ink formulation and EPCIS repository integration. Watch for ANVISA implementation timeline acceleration in Brazil as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallized Substrates | Captive supply of proprietary ink chemistry inputs reduces exposure to European specialty chemical price volatility. |
| Blockchain-Anchored Verification Platform Launch | Distributed ledger authentication extends beyond EMA regulatory minimums into brand protection for high-value biologics. |
| ISO 16678 Certification Investment | Hospital procurement cooperatives in Germany mandate compliant systems as baseline qualification criteria. |
| Serialization Service Contract Consolidation | Eastern European generic manufacturers spread DSCSA compliance costs across product portfolios through bundled agreements. |
| Direct-to-Consumer Authentication App Development | Smartphone-readable covert markers address underpenetrated over-the-counter pharmaceutical verification demand. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region balanced against secondary validation. Primary interviews engaged regulatory affairs leads at pharmaceutical manufacturers, hospital procurement managers in Germany, wholesale distributor compliance officers in the United States, and serialization platform engineers at track-and-trace providers. Secondary sources included FDA DSCSA guidance documents, EMA verification architecture technical specifications, CDSCO alignment protocols, ANVISA implementation roadmaps, and customs trade data on authentication substrate imports. Bottom-up demand modeling triangulated against top-down regulatory mandate timelines.
Rate-of-change decomposition across the analysis window separates volume expansion from value migration between technology tiers. Segmentation dimensions encompass authentication technology type, product format, end-user archetype, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to compliance-driven procurement cycles and biologics cold-chain expansion. Industry-specific inputs include FDA enforcement deadline schedules, EMA EMVS connection mandates, and RFID adoption rates in temperature-sensitive distribution networks.
Regulatory deadline delays, metallized substrate supply disruptions, and interoperability standard fragmentation are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions on statutory enforcement consistency and hospital procurement centralization trajectories. Deviation in FDA DSCSA verification requirement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market