
 Vials and Ampoules Market | 2026-2036
Vials and Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Vials and Ampoules Market Intelligence
Contract sterilization and ready-to-use (RTU) packaging services are restructuring how pharmaceutical buyers procure vials and ampoules, shifting capital from in-house washing and depyrogenation to outsourced validated supply. Schott AG leverages its FIOLAX borosilicate glass platform to dominate high-purity pharmaceutical tubing supply across North America and Europe. Gerresheimer AG anchors its position through integrated mold-to-vial production, controlling quality from glass melt to final container closure. West Pharmaceutical Services differentiates via its NovaPure elastomeric closure systems paired with RTU vial formats, capturing value at the drug-container interface.
Vials and ampoules constitute primary pharmaceutical packaging systems designed to maintain sterility, chemical stability, and mechanical integrity for parenteral drug products, with borosilicate glass Type I tubing specified for its hydrolytic resistance below 0.7 ml extracted water per gram. These containers serve as the critical barrier between biologic or small-molecule therapies and external contamination during storage, transport, and administration. Glass vials retain the dominant share in high-value biologics due to their inertness and regulatory acceptance, while plastic vials compete in cost-sensitive generics and veterinary applications where extractables profiles permit polymer alternatives. Prefilled syringes represent the fastest-growing format as self-administration trends and combination product regulations shift dosing convenience from the clinic to the patient.
The FDA enforces Container Closure Systems guidance requiring extractables and leachables data for all new drug applications, directly shaping material selection and supplier qualification timelines for vial manufacturers. The European Medicines Agency implements Annex 1 revisions mandating barrier isolation and closed systems in aseptic processing, elevating demand for RTU vials and ampoules that reduce human intervention. ISO 15378 quality management standards for primary packaging materials create baseline compliance thresholds that filter smaller suppliers from tenders by multinational pharmaceutical companies. Stakeholders must monitor how USP <665> and <1665> plastic packaging system qualification standards expand to capture novel polymer vial materials entering biologics applications.
Market Dynamics
The Vials and Ampoules Market is restructuring around sterilization outsourcing and ready-to-use formats, as pharmaceutical manufacturers divest in-house washing and depyrogenation capacity to concentrate capital on drug development rather than primary packaging infrastructure.
Growth Catalysts
- Biologics expansion:Temperature-sensitive therapies require borosilicate glass Type I tubing with hydrolytic resistance below 0.7 ml extracted water per gram, pulling specialized vial supply into fill-finish operations.
- EU Annex 1 revisions:Barrier isolation mandates in sterile manufacturing elevate demand for pre-sterilized RTU containers that eliminate human intervention during aseptic processing.
- Glass cluster concentration:Specialized production hubs in Germany anchor European pharmaceutical packaging supply, creating procurement efficiencies for multinational drug manufacturers.
Market Restraints
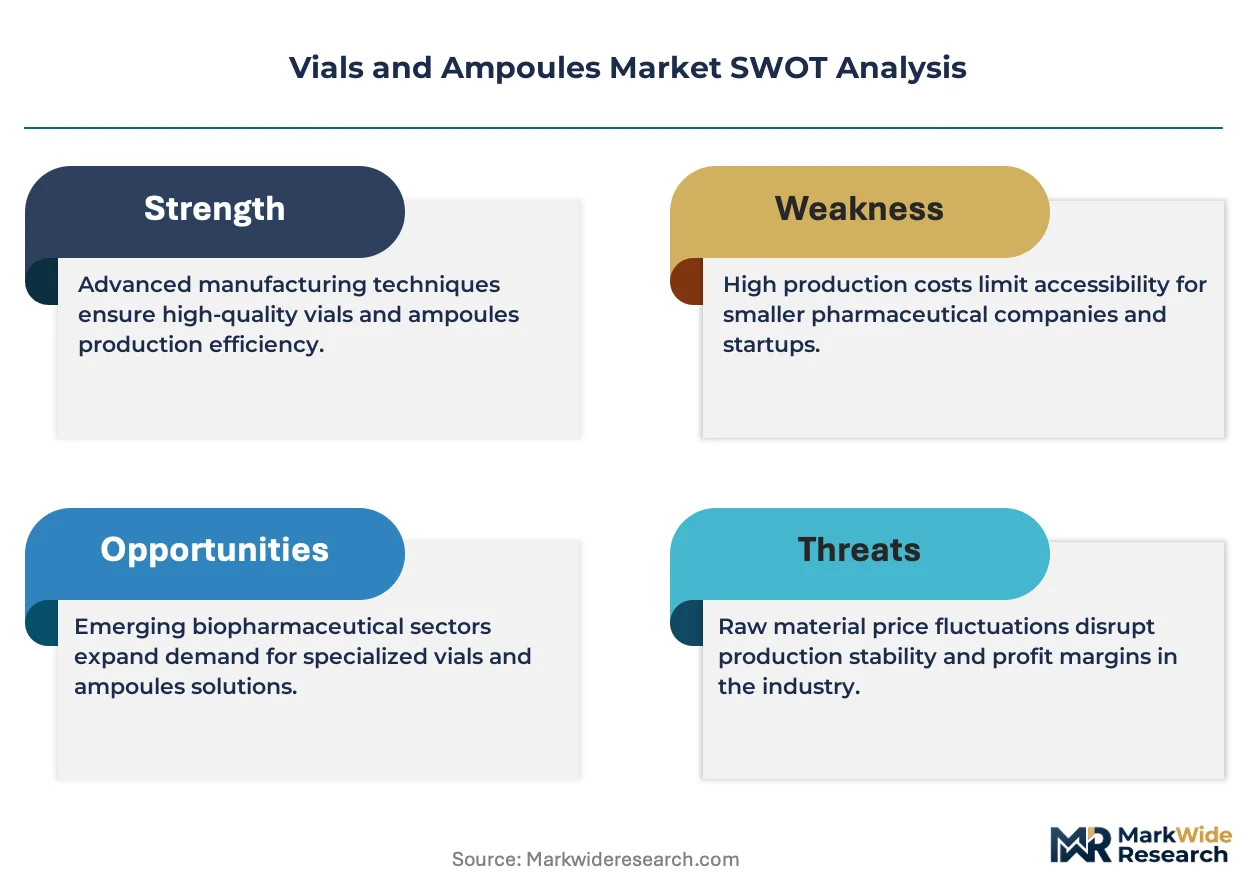
- Borosilicate glass supply concentration:Limited qualified tubing manufacturers create single-source dependencies for high-purity pharmaceutical glass, exposing buyers to allocation risk during demand spikes.
- Extractables testing burden:FDA Container Closure Systems guidance requires comprehensive leachables data for every new drug application, extending supplier qualification timelines by 12-18 months.
- Polymer substitution limits:Plastic vials face restricted adoption in biologics due to USP <665> and <1665> qualification gaps for novel polymer materials, constraining cost-reduction pathways.
Strategic Opportunities
- Self-administration formats:Prefilled syringes and combination products for home injection are displacing traditional vial-and-syringe protocols in chronic disease management.
- ISO 15378 certification gaps:Smaller regional suppliers lack quality management certification for primary packaging materials, creating acquisition targets for quality-compliant mid-cap players.
- Veterinary polymer adoption:Less stringent extractables requirements in animal health applications permit cyclic olefin polymer vials to capture share from glass in cost-sensitive generic markets.
Industry Challenges
- Depyrogenation capacity scarcity:Validated endotoxin-free washing and sterilization services concentrate among contract providers, creating bottlenecks for RTU vial supply expansion.
- Glass-to-metal seal integrity:Elastomeric closure compatibility with high-viscosity biologics requires specialized NovaPure-grade formulations that extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vials and Ampoules Market |
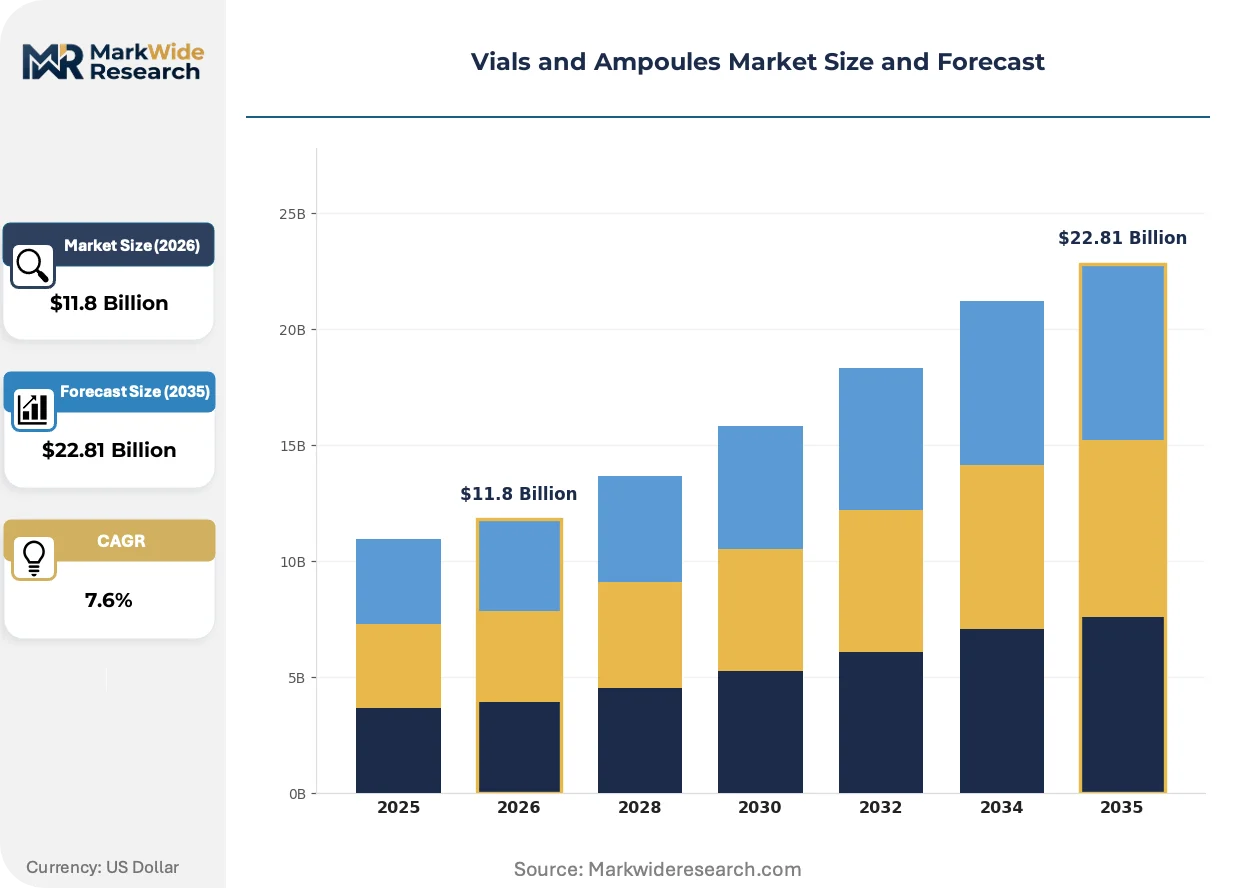
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $22.81 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Ampoules, Prefilled Syringes Material: Polypropylene, Borosilicate Glass, Polyethylene, PVC End User: Hospitals, Clinics, Pharmacies, Research Labs Capacity: 1ml, 5ml, 10ml, 20ml |
| Companies Covered | Schott AG, Gerresheimer AG, West Pharmaceutical Services, Nipro Corporation, Stevanato Group, SGD Pharma, Bormioli Pharma, Corning Incorporated, DWK Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vials and Ampoules Market Strategic Shifts & Innovations
Container closure systems are converging with drug delivery platforms, eroding the historical separation between primary packaging and administration device design. This integration is compressing supplier qualification timelines and elevating technical collaboration requirements.
Ready-to-use sterile vial formats are rewriting procurement patterns across parenteral drug manufacturing. Biologics producers in North America and Europe are adopting pre-sterilized, pre-capped containers to eliminate in-house washing and depyrogenation. This technology is compressing facility capital requirements and accelerating batch release timelines for aseptic fill-finish operations.
EMA Annex 1 revisions mandating closed systems in sterile processing are forcing barrier technology investments across European fill-finish networks. Isolator-based filling lines require RTU vial formats compatible with robotic handling systems. High-value biologics manufacturing in Germany, Switzerland, and Ireland is most affected, with facility retrofits prioritizing pre-sterilized container supply chains.
Pharmaceutical buyers are consolidating supplier relationships around integrated mold-to-vial producers capable of controlling quality from glass melt through final container closure. This pattern displaces fragmented procurement across tubing converters and finishers. The shift is most visible in monoclonal antibody manufacturing, where single-source accountability reduces regulatory risk exposure.
Vials and Ampoules Market Segmentation
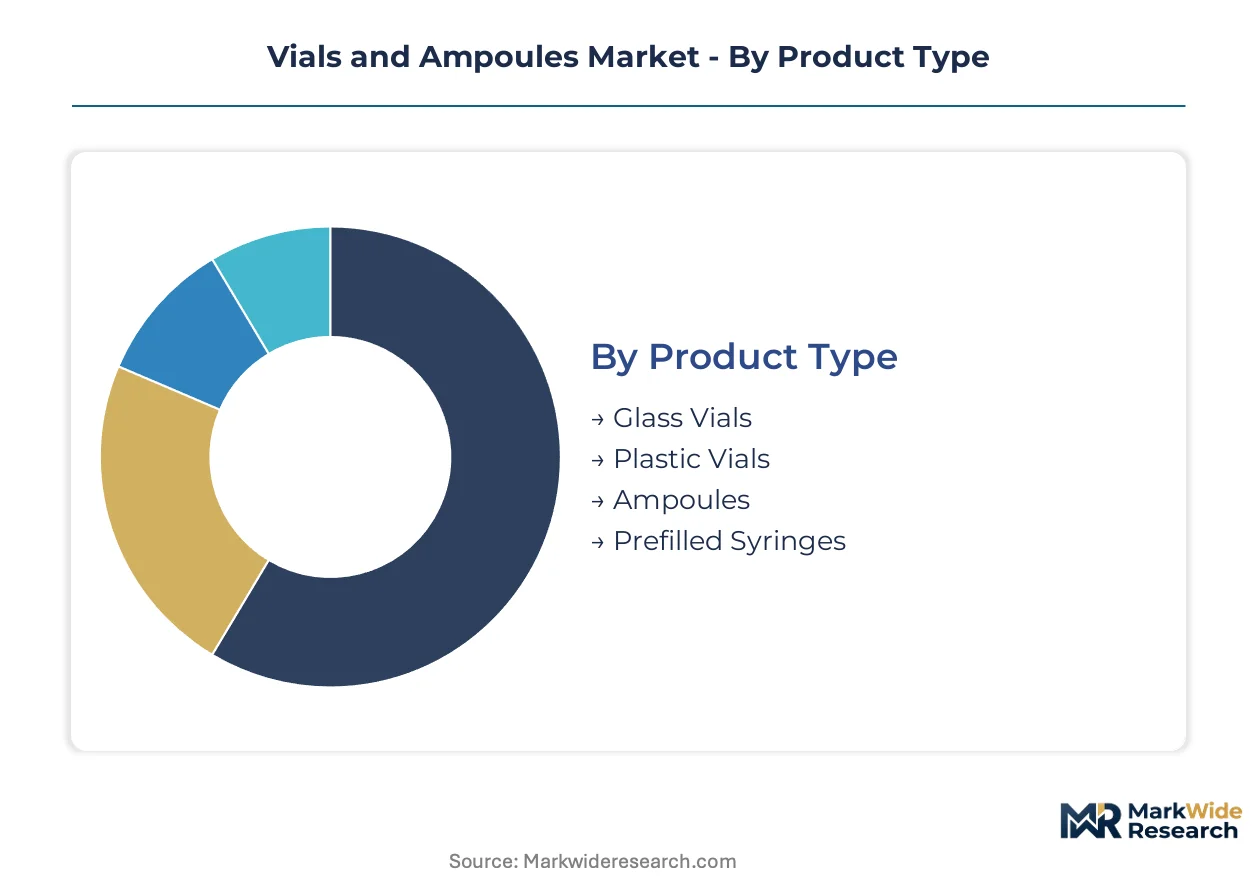
Segmentation in vials and ampoules reveals how packaging economics bifurcate between high-value biologics demanding material purity and cost-sensitive generics accepting polymer alternatives. Each dimension—product format, material composition, end-user workflow, and fill volume—creates distinct procurement patterns that reshape supplier qualification requirements.
Product Type:
Glass vials operate as standalone primary packaging systems requiring separate closure and administration components, while prefilled syringes embed drug delivery functionality into the container itself.
- Glass Vials:Borosilicate Type I tubing delivers hydrolytic resistance below 0.7 ml extracted water per gram, making these containers mandatory for monoclonal antibodies and temperature-sensitive biologics in German and Swiss fill-finish networks. FDA Container Closure Systems guidance and EMA Annex 1 barrier isolation mandates cement glass dominance in regulated parenteral applications where extractables profiles demand material inertness.
- Prefilled Syringes:These combination products integrate primary container with patient-ready administration, capturing chronic disease management protocols where self-injection replaces clinic visits. Demand concentrates in North American and European markets where combination product regulations and convenience-driven dosing protocols accelerate displacement of traditional vial-and-syringe workflows.
- Plastic Vials:Cyclic olefin polymers and polypropylene alternatives serve veterinary and cost-sensitive generic markets where USP <665> qualification gaps matter less than unit economics.
- Ampoules:Single-dose glass containers persist in emergency medicine and anesthetic applications requiring immediate access without reconstitution steps.
Glass vials lead volumes today; prefilled syringes are gaining share fastest.
Material:
Material selection stratifies across hydrolytic resistance tiers, with borosilicate glass commanding premium positioning for sensitive biologics while polymers compete on cost in less regulated applications.
- Borosilicate Glass:Schott AG's FIOLAX platform and Gerresheimer's specialized tubing supply define pharmaceutical-grade borosilicate with thermal shock resistance and chemical durability specifications exceeding USP <660> container glass standards. German production clusters anchor European supply, with qualification timelines of 12-18 months for new drug applications reinforcing incumbent supplier positions.
- Polypropylene:This polymer captures veterinary and diagnostic reagent markets where moisture barrier requirements permit flexible alternatives to glass, with lower breakage rates during transport justifying adoption despite limited biologics acceptance.
- Polyethylene:Low-density formulations serve buffer and diluent containment where chemical compatibility profiles accommodate less inert materials.
- PVC:Plasticized and unplasticized variants persist in specific blood collection and diagnostic applications despite regulatory pressure on plasticizer extractables.
Borosilicate glass dominates value capture; polypropylene shows steepest expansion trajectory in animal health segments.
End User:
End-user segmentation tracks institutional purchasing power and regulatory exposure, with hospital systems demanding validated supply chains that smaller clinical settings cannot replicate.
- Hospitals:Integrated health systems in Germany, Switzerland, and the United States consolidate procurement around RTU formats and ISO 15378-certified suppliers, with aseptic processing requirements from EMA Annex 1 revisions and FDA sterile manufacturing guidance mandating pre-sterilized container supply.
- Clinics:Outpatient infusion centers prioritize prefilled and ready-to-use formats that minimize pharmacy compounding steps and reduce medication error risk in high-volume injection protocols.
- Pharmacies:Retail and specialty pharmacy channels handle patient-directed biologics where cold chain integrity and patient counseling requirements shape packaging preferences.
- Research Labs:Preclinical and clinical trial supply demands small-batch flexibility and rapid qualification timelines that differ from commercial manufacturing procurement patterns.
Hospitals command the largest procurement volumes; clinics are expanding fastest as site-of-care administration shifts from inpatient to ambulatory settings.
Capacity:
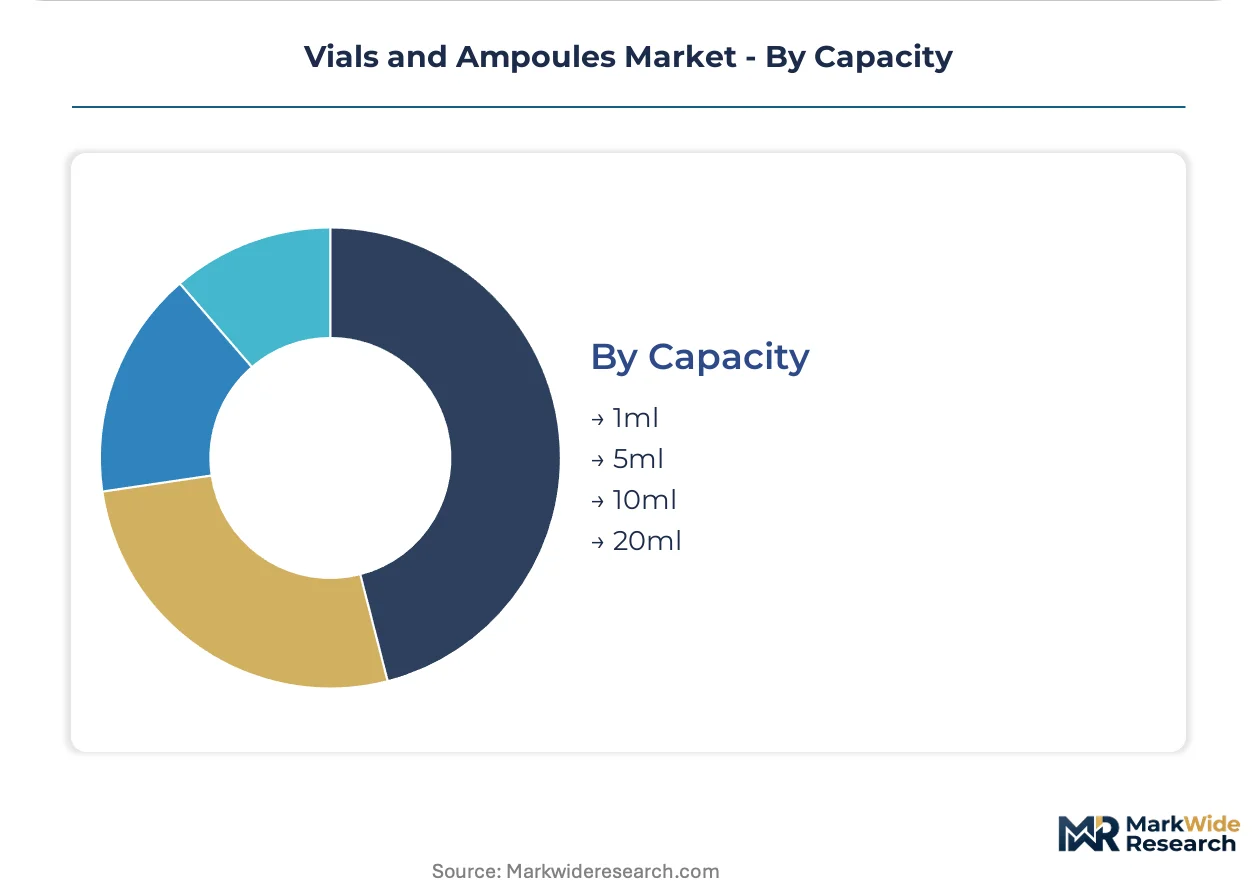
Fill volume segmentation aligns with dosing regimens across therapeutic categories, with biologics concentration trends pushing demand toward smaller formats that minimize waste in high-cost therapies.
- 1ml:High-concentration biologics and ophthalmic preparations utilize this format, with precision fill requirements and minimal headspace specifications demanding specialized closure systems from West Pharmaceutical Services and comparable suppliers.
- 5ml:This capacity captures the majority of injectable antibiotics, vaccines, and diagnostic reagents where standard dosing volumes align with established administration protocols.
- 10ml:Diluent and reconstitution volumes for lyophilized biologics occupy this segment, with dual-chamber systems and vial transfer devices creating combination product complexity.
- 20ml:Large-volume parenterals, irrigation solutions, and contrast media utilize this format where single-dose containment exceeds standard injection volumes.
5ml capacities maintain the broadest installed base; 1ml formats are climbing fastest as biologics concentration intensifies and waste minimization pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vial and ampoule manufacturing geography, as producers migrate toward jurisdictions offering streamlined qualification pathways and concentrated pharmaceutical demand clusters.
Germany
EMA Annex 1 revisions on barrier isolation and sterile processing drive specialized glass demand from Mainz-based Schott AG and Düsseldorf-area Gerresheimer AG facilities. The German Medicines Act and national pharmaceutical manufacturing standards enforce material traceability requirements that filter out non-ISO 15378-certified suppliers. Bavarian and North Rhine-Westphalian production clusters anchor European borosilicate tubing supply, with validated depyrogenation services concentrating around Frankfurt-Rhine-Main logistics corridors.
United States
FDA Container Closure Systems guidance and USP <660> glass standards create compliance thresholds that extend supplier qualification timelines for domestic biologics manufacturers. The agency's sterile manufacturing guidance and combination product regulations elevate demand for RTU formats in Massachusetts and North Carolina biotech corridors. Pennsylvania-based West Pharmaceutical Services anchors elastomeric closure supply, while New Jersey and California fill-finish networks drive pre-sterilized container procurement.
China
NMPA pharmaceutical packaging material regulations and national drug administration standards are tightening material certification requirements for domestic vaccine and biologics producers. The country's dual carbon goals and energy efficiency mandates press glass furnace operations toward consolidation in Shandong and Jiangsu provinces. Yangtze River Delta pharmaceutical manufacturing clusters are absorbing capacity from fragmented regional converters unable to meet upgraded hydrolytic resistance specifications.
India
CDSCO's phased alignment with ICH Q3D elemental impurity guidelines and revised Schedule M manufacturing standards are elevating primary packaging qualification burdens for export-oriented injectable producers. The PLI scheme for pharmaceuticals incentivizes integrated glass-to-vial capacity in Gujarat and Maharashtra. Mumbai-Pune and Hyderabad-Visakhapatnam corridors concentrate fill-finish operations serving regulated export markets, with domestic borosilicate tubing supply lagging specialized import dependence.
Switzerland
Swissmedic's stringent container closure system requirements and proximity to German glass supply clusters position Basel and Zurich pharmaceutical operations at the premium end of vial procurement. The country's pharmaceutical manufacturing ordinance mandates material qualification documentation that favors established FIOLAX-certified tubing sources. Swiss biologics fill-finish networks in Basel-Land and Vaud cantons concentrate demand for high-purity Type I glass in monoclonal antibody and cell therapy applications.
Vials and Ampoules Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated mold-to-vial producers capturing premium biologics procurement while regional converters serve cost-sensitive generics. The vendor base concentrates around three strategic archetypes: German-engineered glass specialists with captive tubing supply, integrated device-and-container combination product platforms, and Asian-scale converters leveraging polymer substitution in veterinary markets. Dominant competitive moves include backward integration into borosilicate furnace operations and strategic partnerships with fill-finish equipment manufacturers to secure RTU format compatibility.
Within the German-engineered archetype, Schott AG and Gerresheimer AG exemplify integrated production models controlling quality from glass melt through final container closure. West Pharmaceutical Services occupies a distinct position at the drug-container interface, pairing elastomeric closure systems with pre-sterilized vial formats. These three entities anchor distinct competitive vectors—glass purity, integrated mold-to-vial production, and combination product integration—rather than competing directly on identical specifications.
| Leading Market Players |
|---|
| Schott AG |
| Gerresheimer AG |
| West Pharmaceutical Services |
| Nipro Corporation |
| Stevanato Group |
| SGD Pharma |
| Bormioli Pharma |
| Corning Incorporated |
| DWK Life Sciences |
| Others |
Cost & Logistics Intelligence
Pharmaceutical buyer consolidation around RTU formats and ISO 15378-certified suppliers forces borosilicate glass producers to absorb depyrogenation costs while maintaining FIOLAX-grade purity specifications, compressing margins at the tubing conversion layer and amplifying price premiums for validated supply chains.
Pricing Analysis
Distributor margins on pharmaceutical glass tubing range from 12-18 percent for standard borosilicate grades to 25-35 percent for FIOLAX-certified specialty batches, with direct-to-OEM contracts commanding 8-12 point discounts for annual volume commitments above 50 million units. Three-tier pricing structure across premium, standard, and economy levels separates FIOLAX-certified biologics-grade tubing from USP Type II diagnostic grades and unqualified generic vial stock, with certification tier and volume scale as primary differentiation drivers. Cost compression in standard-grade segments is intensifying because Indian and Chinese converters are absorbing European furnace capacity, while biologics manufacturers show least price sensitivity due to regulatory requalification costs exceeding any material savings.
Supply Chain Analysis
Dual-sourcing mandates from FDA and EMA qualified supplier programs require pharmaceutical buyers to maintain active relationships with at least two borosilicate tubing producers, typically pairing German FIOLAX supply with secondary Japanese or domestic US furnace sources. Geographic supply concentration centers on Germany, Japan, and the United States, with raw material dependencies on high-purity silica sand from Belgium and soda ash from Wyoming and Kenya. Single-source vulnerability persists in pharmaceutical-grade borosilicate furnace operations, where only four qualified producers globally meet hydrolytic resistance specifications below 0.7 ml extracted water per gram. Distribution runs through specialized pharmaceutical packaging distributors in Frankfurt-Rhine-Main and New Jersey corridors, with direct mill-to-fill-finish contracts displacing spot market procurement for biologics applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in vials and ampoules rests on RTU format premiums and captive depyrogenation capacity, with sterilization outsourcing trends allowing integrated producers to capture value previously lost to contract service providers.
For Market Incumbents: Cement supply security through backward integration into borosilicate furnace operations or long-term offtake agreements with German tubing producers, while expanding validated depyrogenation capacity to capture RTU format premiums before contract sterilization providers consolidate. Polymer substitution in veterinary markets and cyclic olefin vial entrants from Asia pose emerging threats to glass dominance in cost-sensitive segments, requiring certification investments in ISO 15378 quality management systems to maintain tender eligibility. For New Entrants and Emerging Players: Launch via veterinary pharmaceutical channels in Brazil and Mexico, where ANVISA and COFEPRIS extractables requirements permit polymer vial alternatives without the 12-18 month qualification timelines mandated for human biologics. The most penetrable white space sits in 1-5ml cyclic olefin polymer vials for diagnostic reagents and animal health applications, with go-to-market acceleration through private-label partnerships with established distributors rather than direct pharmaceutical qualification campaigns. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap RTU format specialists possessing ISO 15378 certification but lacking captive glass supply, as these entities become acquisition targets for integrated producers seeking sterilization capacity without greenfield construction. Long-term viability favors mold-to-vial producers controlling quality from glass melt through final container closure, with the signal to watch being EMA Annex 1 enforcement actions that disqualify non-RTU supply chains and accelerate industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Furnace Operations | Captive FIOLAX-grade tubing supply eliminates allocation risk during biologics demand spikes and secures 12-18 month qualification timelines. |
| RTU Sterilization Capacity Expansion | Validated depyrogenation services command 40-60 percent premiums over standard vial supply and anchor long-term pharmaceutical contracts. |
| ISO 15378 Quality Management Certification | Regulatory compliance threshold filters regional competitors from multinational pharmaceutical tenders and creates acquisition premiums. |
| Prefilled Syringe Platform Development | Combination product regulations shift dosing convenience from clinic to patient, displacing traditional vial-and-syringe workflows in chronic disease management. |
| Veterinary Polymer Vial Launch | Reduced extractables requirements in animal health applications permit cyclic olefin polymer alternatives to capture share from glass in cost-sensitive generic markets. |
Research Approach
Bottom-up pharmaceutical fill-finish modeling reconciled against top-down borosilicate glass supply tracking forms the analytical core of this study, combining primary interviews with regulatory affairs leads at biologics manufacturers, procurement managers at German fill-finish networks, and technical directors at glass tubing converters with secondary validation from FDA Container Closure Systems guidance documents, EMA Annex 1 revision filings, ISO 15378 certification databases, and pharmaceutical packaging trade customs records.
Input-output matrices map borosilicate tubing furnace capacity through conversion, sterilization, and final vial assembly against biologics fill-finish demand across the analysis window, with CAGRs derived from segment-level volume trajectories and value-per-unit shifts in RTU versus conventional formats. Segmentation dimensions include product type, material grade, end-user workflow, and fill volume, with forecast inputs incorporating EMA Annex 1 barrier isolation mandates and FDA combination product regulations as demand accelerators.
Several conditions sit outside the modeled scope, including specific patent litigation outcomes affecting prefilled syringe formats and unannounced pharmaceutical facility closures that could abruptly shift regional demand patterns. Deviation in EMA Annex 1 enforcement intensity or NMPA regulatory alignment timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market