
 Flip Top Vials Market | 2026-2036
Flip Top Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Flip Top Vials Market Foresight
Pharmaceutical-grade borosilicate specification is rotating toward higher thermal shock resistance and reduced extractables profiles. Gerresheimer AG leverages its European furnace network to sustain captive glass tubing supply for premium vial output. Schott AG anchors quality leadership through FIOLAX borosilicate formulations optimized for biologic drug stability. West Pharmaceutical Services differentiates via integrated elastomer closure systems paired with flip top vial platforms.
Flip top vials are small-volume cylindrical containers with hinged polypropylene or polyethylene closures that snap open for single-hand dispensing, typically manufactured from Type I borosilicate glass or cyclic olefin polymers to achieve USP <660> and EP 3.2.1 compliance for parenteral applications. Glass vials occupy the dominant value share due to inertness requirements for protein-based therapeutics, while plastic vials represent the fastest-expanding category as polymer barrier technologies advance for non-injectable formulations. Pharmaceutical packaging commands the largest application segment by revenue, though laboratory testing generates higher unit velocity through research consumables procurement.
The US FDA enforces 16 CFR 1700 child-resistant packaging standards that mandate specific flip top torque and reclosure performance for over-the-counter liquid formulations. The European MDR and REACH frameworks impose extractables testing and substance restriction protocols that elevate compliance costs for imported vial assemblies. EMA guidelines on primary packaging stability are pushing manufacturers toward documented leachable profiles across batch release protocols. Stakeholders must monitor evolving polymer qualification requirements as regulators tighten material characterization expectations for combination product submissions.
Market Dynamics
Pharmaceutical packaging regulations are compressing supplier margins while concentrating demand among certified manufacturers capable of documented extractables testing and batch-level traceability for biologic drug stability.
Growth Catalysts
- EMA Primary Packaging Stability Guidelines:European mandates for leachable profile documentation across batch release protocols are filtering out uncertified suppliers and consolidating procurement among qualified vendors.
- Biologics Cold Chain Expansion:Protein-based therapeutics require Type I borosilicate inertness, creating dedicated demand for thermal shock-resistant vial specifications in mRNA vaccine storage applications.
- German Glass Tubing Clusters:Specialized furnace networks in Mainz and Mitterteich sustain captive supply chains for premium pharmaceutical-grade tubing, anchoring regional production advantages.
Market Restraints
- Energy-Intensive Borosilicate Melting:Natural gas price volatility directly pressures furnace operating economics, compressing margins for glass-dependent manufacturers.
- European REACH Substance Restrictions:ECHA protocols impose escalating compliance costs on imported vial assemblies, creating non-tariff barriers for Asian suppliers.
- Cyclic Olefin Polymer Barrier Limitations:Oxygen and moisture transmission rates in plastic alternatives remain insufficient for long-dated parenteral biologics, constraining material substitution.
Strategic Opportunities
- India CDSCO Accelerated Approval Pathways:Domestic vaccine production incentives are creating demand for child-resistant flip top formats in emerging pharmaceutical manufacturing hubs.
- Pre-filled Syringe Convergence:Integration of elastomer closure systems with vial-to-syringe drug transfer devices opens combination product categories with higher value capture.
- Laboratory Automation:High-throughput screening facilities are adopting color-coded polypropylene flip tops for single-hand dispensing in robotic liquid handling workflows.
Industry Challenges
- USP <660> and EP 3.2.1 Dual Certification Timelines:Harmonized compliance for glass grain count and hydrolytic resistance testing extends qualification cycles for new furnace outputs.
- Specialized Borosilicate Metallurgy Talent:Furnace operation and glass chemistry expertise concentrates among aging workforces in traditional European manufacturing centers.
- Legacy Molding Equipment Retrofit Complexity:Converting existing lines for hinged closure snap-fit tolerances requires precision tooling investments that strain mid-capitalization producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip Top Vials Market |
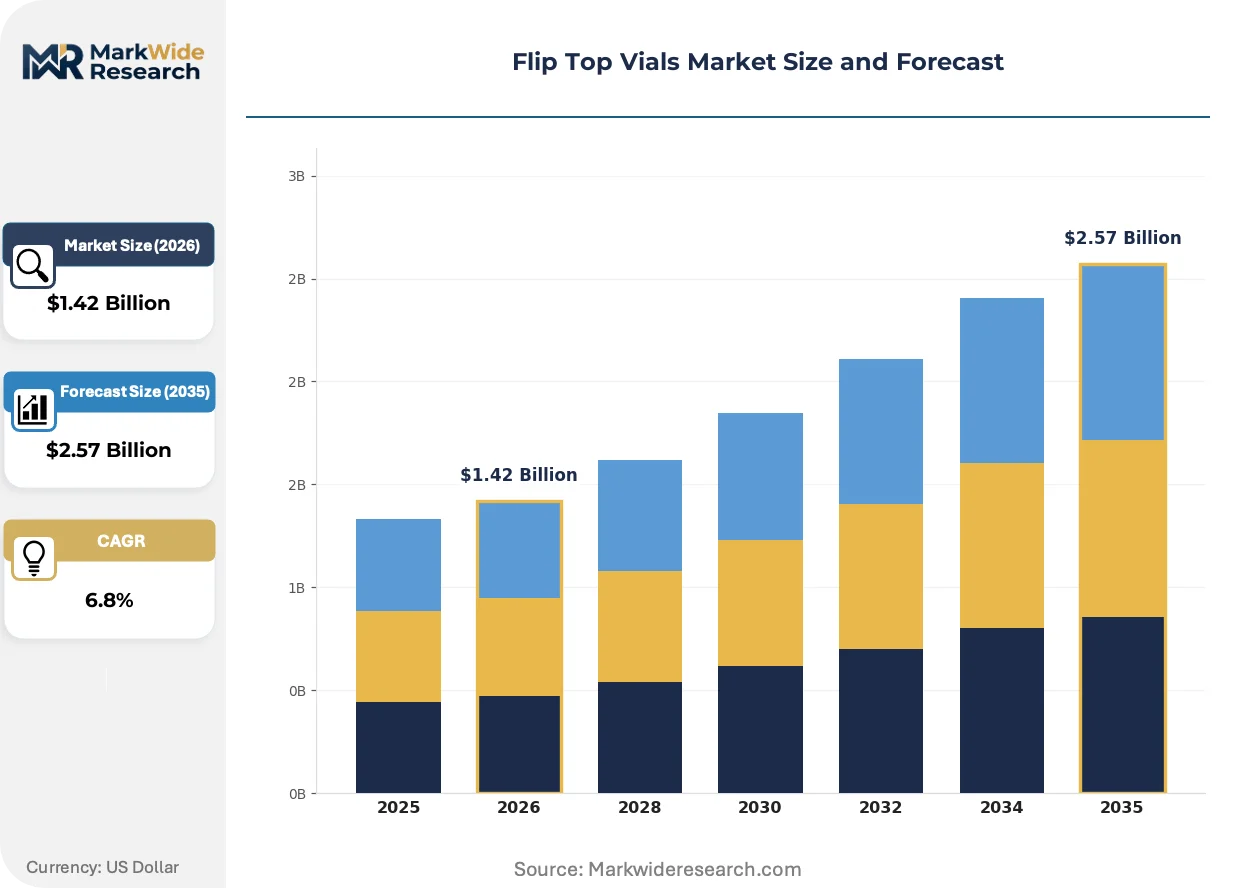
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Amber Vials, Clear Vials Application: Pharmaceutical Packaging, Cosmetic Storage, Chemical Sampling, Laboratory Testing, Food Additives End User: Medical Facilities, Research Laboratories, Cosmetic Manufacturers, Chemical Plants Packaging Type: Bulk Packs, Single Units, Tamper-Evident Packs, Sterile Packs, Reusable Kits |
| Companies Covered | Schott AG, Gerresheimer AG, Thermo Fisher Scientific, AptarGroup, 3M, West Pharmaceutical Services, Amcor, Corning, Eppendorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip Top Vials Market Shifts & Advancements
Material science advances and regulatory documentation requirements are restructuring competitive advantage around certified supply chains rather than unit cost optimization alone.
Silicon dioxide surface coating technologies for borosilicate vials are fragmenting the barrier enhancement landscape. Biologic drug manufacturers in Switzerland and the Netherlands are adopting plasma-activated deposition methods to reduce protein adsorption. This capability compression is fragmenting supplier tiers between coating-equipped specialists and commodity glass converters.
REACH Annex XVII substance restrictions on phthalate plasticizers are tightening elastomer closure specifications. European compounders must reformulate polyisoprene and bromobutyl formulations to maintain compliance. Parenteral packaging applications face the steepest reformulation timelines, with German manufacturers accelerating alternative plasticizer qualification programs.
Consolidated procurement through group purchasing organizations is compressing supplier negotiation leverage. Hospital systems and contract research organizations in the United States are centralizing vial sourcing through preferred vendor agreements. This channel concentration is most visible in vaccine distribution networks, where single-source contracts now dominate multi-year supply arrangements.
Flip Top Vials Market Segmentation
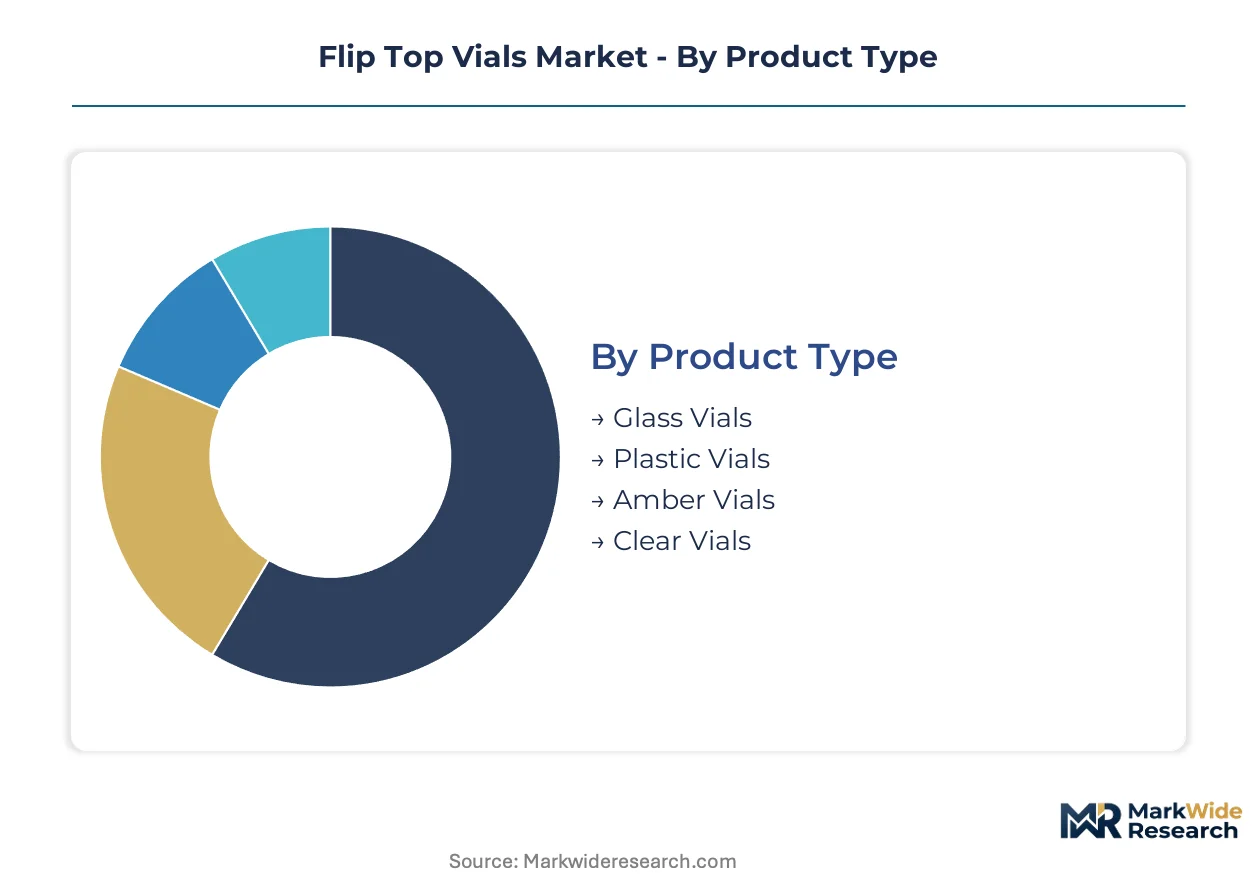
Flip top vial segmentation reflects divergent material science requirements across parenteral drug stability, cold chain logistics, and single-use laboratory automation. Substitution pressures between glass and polymer formats reshape procurement patterns as regulatory documentation standards tighten.
Product Type:
Glass formulations face the most acute substitution pressure from cyclic olefin polymers in non-injectable applications, though barrier limitations constrain displacement in biologics.
- Glass Vials:Type I borosilicate construction delivers USP <660> hydrolytic resistance and thermal shock tolerance for protein-based therapeutics. Demand concentrates in German furnace clusters serving mRNA vaccine cold chain requirements where inertness is non-negotiable.
- Plastic Vials:Polypropylene and cyclic olefin polymer formats achieve single-hand dispensing in high-throughput screening workflows. Research laboratories in the Netherlands and Switzerland are adopting color-coded hinged closures for robotic liquid handling integration.
- Amber Vials:Iron-doped borosilicate attenuates UV transmission for light-sensitive formulations. Photostability requirements in European dermatological preparations sustain niche demand.
- Clear Vials:Standard borosilicate without colorant enables visual inspection of parenteral solutions. Hospital pharmacies prioritize clarity for particulate detection during compounding operations.
Glass vials anchor the volume base while plastic vials gain share at the steepest rate.
Application:
Cost tier stratification separates validated pharmaceutical packaging from commodity laboratory consumables, with certification overhead creating margin divergence.
- Pharmaceutical Packaging:Primary packaging for injectable drugs demands documented extractables profiles and batch-level traceability under EMA stability guidelines. German and Swiss manufacturers dominate qualified supplier lists for biologic drug sponsors.
- Laboratory Testing:Research consumables procurement generates higher unit velocity through automated high-throughput facilities. Polypropylene flip tops with hinged snap closures integrate with robotic deck configurations.
- Cosmetic Storage:Premium skincare formulations utilize amber glass for UV protection combined with child-resistant flip top mechanisms. French and Italian cosmetic houses specify European-sourced borosilicate for brand positioning.
- Chemical Sampling:Inert borosilicate containment for analytical reagents and reference standards. Industrial laboratories prioritize chemical resistance over extractables documentation.
- Food Additives:Flavor and colorant sampling in quality control applications. Lower regulatory burden permits polypropylene alternatives with basic USP compliance.
Pharmaceutical packaging commands premium pricing tiers while laboratory testing drives highest shipment velocity.
End User:
Customer type determines validation depth, with medical facilities imposing the most stringent qualification protocols and research laboratories prioritizing dispensing ergonomics.
- Medical Facilities:Hospital pharmacies and infusion centers require child-resistant flip tops meeting 16 CFR 1700 torque specifications for OTC liquid formulations. US FDA enforcement concentrates procurement among certified closure system integrators.
- Research Laboratories:Academic and contract research organizations source color-coded polypropylene formats for single-hand operation in biosafety containment. Procurement centralization through group purchasing organizations compresses supplier margins.
- Cosmetic Manufacturers:European luxury brands specify amber glass with custom hinge geometries for shelf differentiation. REACH Annex XVII compliance elevates compounder qualification requirements.
- Chemical Plants:Process analytical chemistry and quality control operations utilize clear borosilicate for visual inspection. Volume procurement emphasizes unit cost over extractables documentation.
Medical facilities enforce the strictest certification barriers while research laboratories expand volume most aggressively.
Packaging Type:
Supply concentration in sterile pack sterilization services creates bottleneck risks for parenteral drug launch timelines.
- Sterile Packs:Gamma-irradiated or ethylene oxide-sterilized vial-closure combinations for aseptic filling operations. German sterilization service providers anchor regional supply security for European biologic manufacturers.
- Tamper-Evident Packs:Hinged closures with breakaway rings or shrink-band integration for distribution integrity. FDA and EMA mandates for over-the-counter liquid formulations sustain dedicated demand.
- Bulk Packs:Unsterilized vial trays for downstream aseptic processing by pharmaceutical manufacturers. Furnace-direct sourcing from Mainz and Mitterteich clusters optimizes glass tubing economics.
- Single Units:Individual primary packaging for clinical trial materials and specialty pharmacy dispensing. Serialization requirements under EU MDR and US DSCSA elevate label integration complexity.
- Reusable Kits:Autoclavable polypropylene formats for research environments with sustainability mandates. Academic institutions in the Netherlands pilot closed-loop washing and resterilization programs.
Bulk packs anchor manufacturing input volumes while sterile packs capture the steepest value expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in laboratory consumables procurement contrasts sharply with premium tolerance for pharmaceutical-grade vial certification. Buyers in research settings prioritize unit economics and ergonomic dispensing, while drug manufacturers absorb compliance overhead for documented extractables profiles.
Germany
Biologic drug stability requirements sustain demand for Type I borosilicate inertness. EMA primary packaging stability guidelines filter procurement toward qualified vendors with batch-level traceability systems. Mainz and Mitterteich furnace clusters anchor captive glass tubing supply for premium pharmaceutical-grade output.
United States
mRNA vaccine cold chain expansion drives thermal shock-resistant vial specifications. FDA enforcement of 16 CFR 1700 child-resistant standards concentrates procurement among certified closure system integrators. Greater Boston and Research Triangle Park biotech corridors sustain specialized demand for documented leachable profiles.
Switzerland
Plasma-activated silicon dioxide coating adoption reduces protein adsorption for biologic manufacturers. Swissmedic guidelines on combination product submissions elevate material characterization expectations. Basel and Zurich pharmaceutical manufacturing zones fragment supplier tiers between coating-equipped specialists and commodity converters.
India
Domestic vaccine production incentives under CDSCO accelerated approval pathways create demand for child-resistant flip top formats. Central government PLI scheme allocations for pharmaceutical manufacturing strain qualified supplier capacity. Hyderabad and Ahmedabad emerging pharma hubs concentrate procurement expansion for export-oriented sterile pack sterilization.
Netherlands
High-throughput screening facilities adopt color-coded polypropylene flip tops for robotic liquid handling integration. REACH Annex XVII substance restrictions on phthalate plasticizers tighten elastomer closure specifications. Eindhoven and Rotterdam laboratory automation corridors pilot closed-loop washing and resterilization programs for reusable kit formats.
Flip Top Vials Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with certified supply chain documentation separating premium-tier vendors from commodity converters. The vendor base stratifies around furnace-captive glass specialists, integrated elastomer closure system providers, and polymer-format research consumables suppliers. Strategic moves concentrate on backward integration into glass tubing supply and qualification program acceleration for dual USP-EP certification.
Among European furnace-network operators, Schott AG and Gerresheimer AG exemplify the technology-intensive archetype through FIOLAX borosilicate formulations and specialized glass chemistry expertise. West Pharmaceutical Services occupies a distinct position as an integrated closure system architect pairing elastomer technologies with flip top platform engineering.
| Leading Market Players |
|---|
| Schott AG |
| Gerresheimer AG |
| Thermo Fisher Scientific |
| AptarGroup |
| 3M |
| West Pharmaceutical Services |
| Amcor |
| Corning |
| Eppendorf |
| Others |
Supply & Pricing Matrix
EMA primary packaging stability guidelines gate both supplier qualification and price differentiation simultaneously, filtering procurement toward documented extractables profiles that command premium positioning while excluding uncertified competitors from pharmaceutical-grade tiers.
Pricing Analysis
After-sales service contracts for extractables documentation and batch-level traceability drive lifetime value capture in pharmaceutical-grade segments. Three-tier pricing structure across premium certified, standard validated, and economy unqualified levels separates biologic drug sponsors from research laboratories from industrial sampling buyers. Cost compression in laboratory consumables procurement is intensifying because group purchasing organization centralization strips negotiation leverage from polypropylene format suppliers. Research laboratories exhibit highest price sensitivity, while pharmaceutical manufacturers absorb compliance overhead for leachable profile documentation.
Supply Chain Analysis
Inbound logistics costs from Mainz and Mitterteich furnace clusters to European aseptic filling sites hinge on specialized glass tubing transport fragility and just-in-time delivery requirements. German, Swiss, and US production nodes anchor pharmaceutical-grade borosilicate supply, drawing from quartz sand, boron oxide, and alumina feedstocks. Single-source vulnerability concentrates in gamma-irradiated sterilization services for vial-closure combinations. Distribution runs through direct furnace-to-filler relationships for bulk glass tubing and medical device distributors for sterile pack formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified furnace operation expertise concentrates among aging workforces in traditional European manufacturing centers, constraining capacity expansion and sustaining margin capture for incumbents with captive talent pipelines.
For Market Incumbents: Compound defensive positioning through accelerated dual USP-EP certification programs for new furnace outputs, locking out Asian competitors facing REACH compliance barriers. Deepen captive glass tubing supply through furnace network expansion in German clusters, neutralizing energy cost volatility that compresses margin for glass-dependent converters. For New Entrants and Emerging Players: Lead with robotic liquid handling integration for color-coded polypropylene flip tops in Netherlands and Swiss high-throughput screening facilities, where ergonomic dispensing specifications outrank extractables documentation requirements. Target research consumables procurement through direct e-commerce channels that bypass group purchasing organization intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European glass converters lacking silicon dioxide coating capabilities, creating roll-up opportunities as biologic manufacturers fragment supplier tiers between coating-equipped specialists and commodity producers. Monitor plasma-activated deposition adoption rates among Swiss and Dutch drug sponsors as inflection signal for premium-tier vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Acceleration | USP-EP harmonized qualification compresses competitor entry timelines for German furnace operators. |
| Silicon Dioxide Coating Deployment | Plasma-activated deposition capabilities fragment supplier tiers between specialists and commodity converters. |
| Sterile Pack Sterilization Expansion | Gamma-irradiation capacity additions in Hyderabad de-risk parenteral drug launch timelines for CDSCO pathway sponsors. |
| Color-Coded Polypropylene Launch | Robotic liquid handling integration captures Netherlands laboratory automation procurement centralization. |
| Backward Integration into Glass Tubing | Captive furnace networks in Mainz and Mitterteich neutralize natural gas price volatility exposure. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical packaging engineers, regulatory affairs specialists, hospital procurement managers, and contract research organization supply chain directors and refined through secondary validation against FDA 483 inspection observations, EMA quality defect reports, USP documentary standards, and European pharmacopoeia monographs. Bottom-up triangulation across vial-closure system bill-of-materials and top-down reconciliation against pharmaceutical packaging expenditure flows anchored volume estimates.
Variance decomposition across material type, application tier, end-user validation depth, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro pharmaceutical production indices and biologics cold chain expansion trajectories. Forecast inputs incorporated mRNA vaccine storage specification evolution and REACH Annex XVII substance restriction timelines.
The analysis sits within stated boundaries; outcomes outside sustained EMA stability guideline enforcement or German furnace network capacity constraints would require recalibration. Forecasts reflect assumptions regarding qualified supplier consolidation and extractables documentation standardization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
US Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market