
 Fertility Testing Devices Market | 2026-2036
Fertility Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Fertility Testing Devices Market Analysis
Home-based self-trackers is bifurcating from clinic-dependent patients as the dominant demand archetype in fertility testing. SPD Swiss Precision Diagnostics GmbH leverages its European manufacturing base to sustain premium ovulation test kit output across pharmacy chains. Abbott Laboratories anchors its position through broad diagnostic infrastructure that extends into fertility hormone assays. Quidel Corporation differentiates via rapid-test expertise that competes in both clinical and over-the-counter channels.
Fertility testing devices comprise instruments and consumables that detect luteinizing hormone surges, basal body temperature shifts, or sperm concentration to predict or confirm reproductive status, typically achieving sensitivity thresholds of 25-50 mIU/mL for urinary LH detection. Their primary commercial purpose centers on enabling timed conception or early identification of subfertility without immediate clinical intervention. Ovulation test kits occupy the largest volume position due to low unit cost and pharmacy ubiquity, while wearable devices represent the fastest-expanding margin pool as continuous temperature and hormone monitoring commands subscription pricing. App-based monitoring sits at a regulatory inflection point where FDA Software as a Medical Device enforcement will separate validated algorithms from consumer wellness tools.
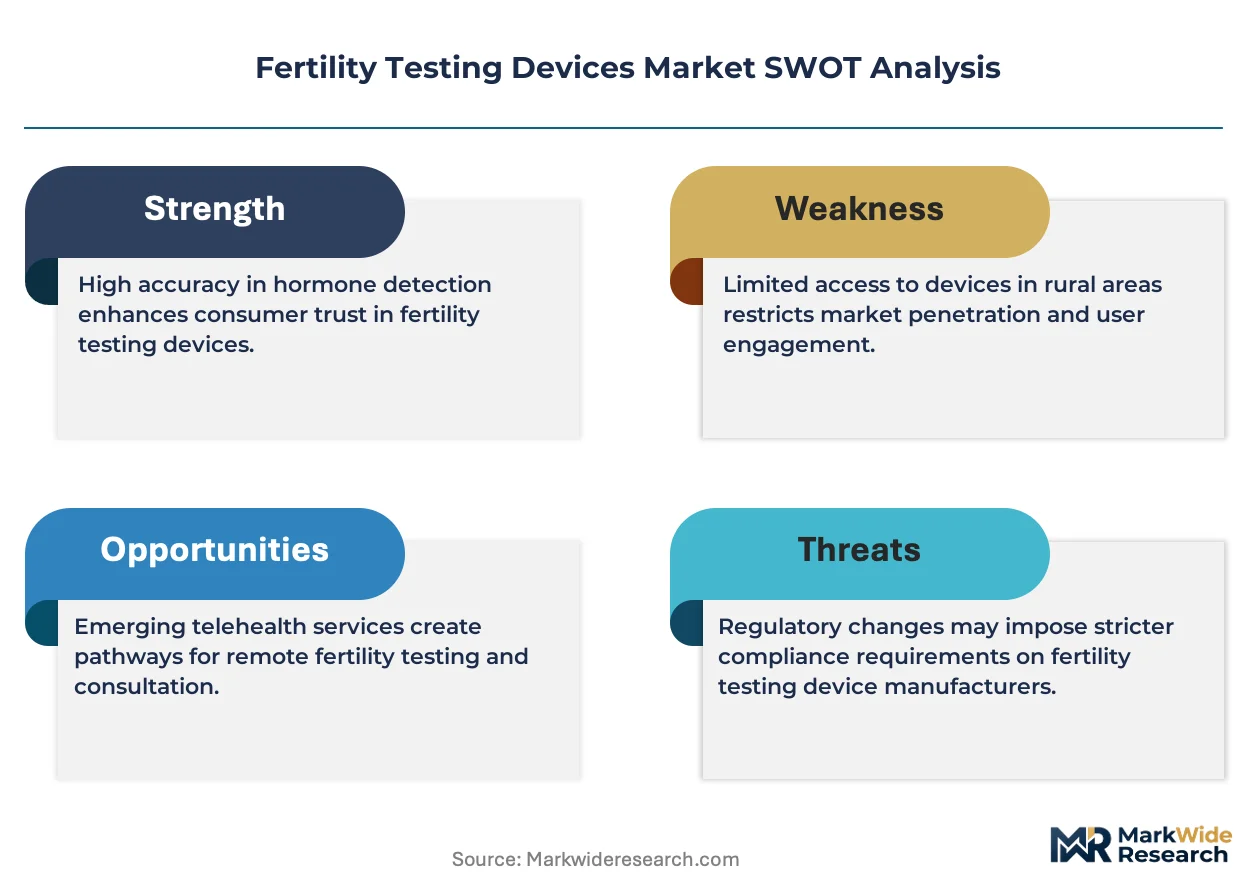
The FDA governs home-use fertility tests through 510(k) premarket notification pathways while the EPA oversees chemical reagent disposal from manufacturing facilities. Europe's MDR and CE marking requirements impose clinical evidence standards that delay market entry for novel connected devices. Stakeholders must monitor how FDA algorithm-validation enforcement and EU MDR notified body capacity constraints reshape competitive access for app-integrated fertility platforms.
Market Dynamics
FDA Software as a Medical Device enforcement is bifurcating fertility apps into validated clinical tools and unregulated wellness trackers, forcing algorithm developers to submit 510(k) premarket notifications or exit the medical claims space entirely.
Growth Catalysts
- Employer fertility benefits expansion:Large US employers now subsidize ovulation tracking kits and hormone assays as standard health plan inclusions, normalizing home-based fertility monitoring among working-age women.
- MDR clinical evidence pathways:Europe's Medical Device Regulation mandates post-market surveillance for connected fertility devices, creating competitive moats for manufacturers with established notified body relationships.
- Continuous biosensor miniaturization:Wearable temperature and hormone sensors now achieve medical-grade accuracy at consumer price points, enabling subscription-based fertility coaching platforms.
Market Restraints
- Reagent supply concentration:Antibody and enzyme suppliers for urinary LH detection concentrate in Germany and Switzerland, exposing test kit manufacturers to single-source dependency risks.
- Algorithm validation costs:FDA 510(k) submissions for ovulation prediction software require prospective clinical studies costing manufacturers upward of eighteen months and substantial capital outlay.
- Smartwatch substitution threat:Apple and Samsung fertility tracking features in consumer wearables capture basal body temperature data without dedicated device purchases, compressing standalone sensor margins.
Strategic Opportunities
- India's underpenetrated pharmacy channel:CDSCO medical device rules now permit over-the-counter fertility test sales, opening direct distribution through India's 850,000 retail pharmacy outlets.
- AI-integrated sperm analysis:Smartphone-based semen microscopy apps combining computer vision with WHO morphology standards address male factor infertility screening without clinical laboratory infrastructure.
- Telehealth platform integration:Fertility testing APIs embedded into Maven, Progyny, and Carrot Health interfaces create recurring revenue through remote monitoring subscriptions.
Industry Challenges
- ISO 13485 quality management certification:Small connected device startups lack documented design controls and risk management files required for European market access, delaying CE marking timelines.
- Cross-platform data interoperability:Proprietary fertility app ecosystems resist HealthKit and Google Fit integration, frustrating users seeking consolidated reproductive health dashboards across multiple sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertility Testing Devices Market |
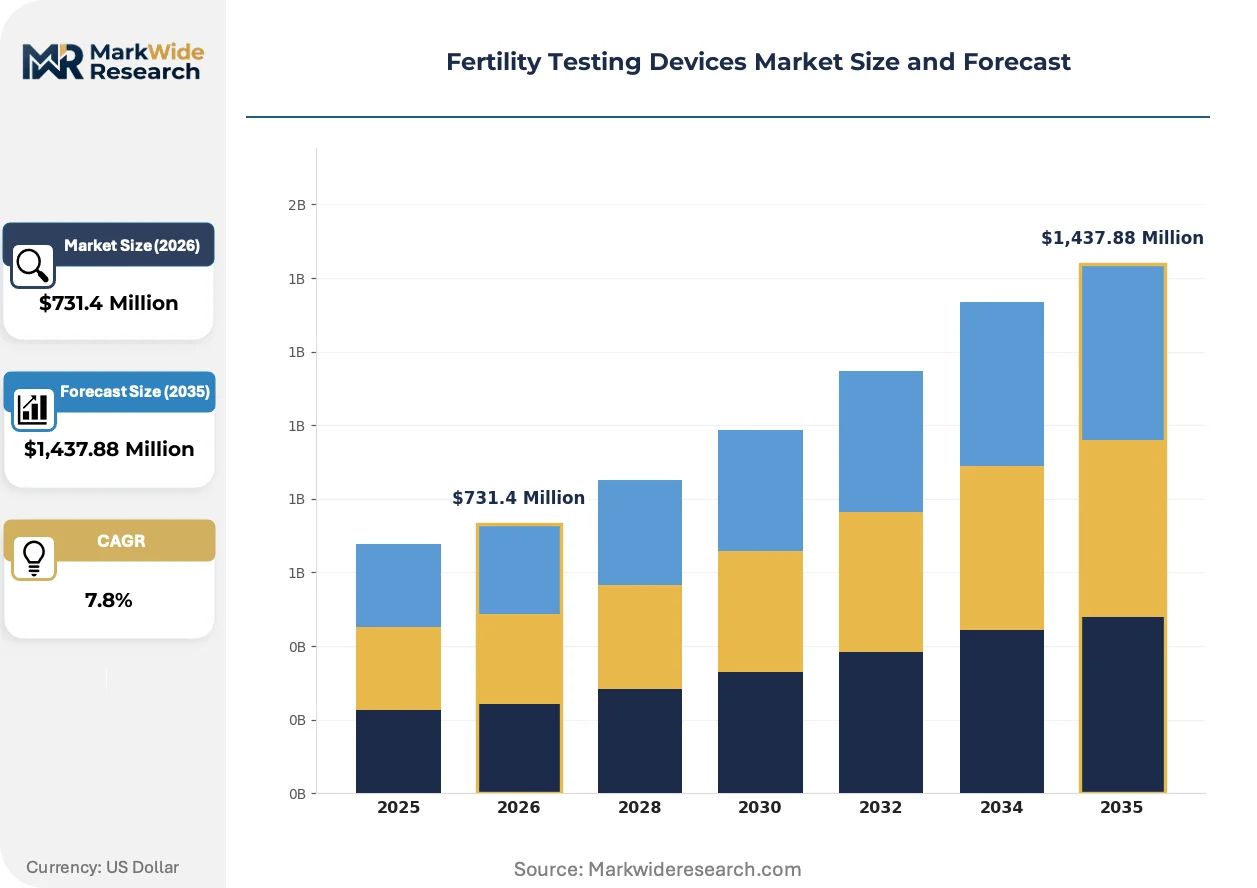
| Market Size in 2026 | $731.4 Million |
| Market Size in 2035 | $1,437.88 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovulation Test Kits, Fertility Monitors, Sperm Test Kits, Hormone Level Tests Technology: Urine Analysis, Blood Test, App-Based Monitoring, Wearable Devices End User: Individuals, Clinics, Hospitals, Fertility Centers Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct-to-Consumer |
| Companies Covered | Church & Dwight Co., Inc., SPD Swiss Precision Diagnostics GmbH, Prestige Consumer Healthcare, Inc., Quidel Corporation, Geratherm Medical AG, bioZhena Corporation, Mira, Fairhaven Health, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertility Testing Devices Market Emerging Trajectories
Continuous hormone monitoring through microneedle patch arrays is replacing discrete urinary test strips as the dominant technical trajectory, enabling real-time luteinizing and progesterone tracking without user-initiated sample collection.
Photonic biosensors using surface plasmon resonance are displacing lateral flow immunoassays in premium ovulation tracking devices. Women aged 30-40 seeking conception windows now demand laboratory-grade precision without clinic visits. This displacement compresses the addressable market for single-use test strips while expanding recurring revenue from durable sensor hardware paired with algorithm subscriptions.
Europe's MDR notified body capacity constraints extend CE marking timelines for novel fertility wearables to fourteen to twenty-four months. Manufacturers with legacy device certifications under the Medical Device Directive receive transitional relief, while new entrants face extended market exclusion. Connected temperature monitors with cloud-based cycle prediction algorithms bear the heaviest documentation burden, prompting some developers to deprioritize European launch sequencing.
Direct-to-consumer subscription models now bypass pharmacy and clinic channels entirely. Fertility testing kit vendors ship personalized hormone panels monthly, with algorithm-adjusted testing schedules replacing fixed-calendar ovulation prediction. This channel disintermediation concentrates most visibly in the United States, where employer-sponsored fertility benefits normalize at-home diagnostic spending without insurance pre-authorization friction.
Fertility Testing Devices Market Segmentation
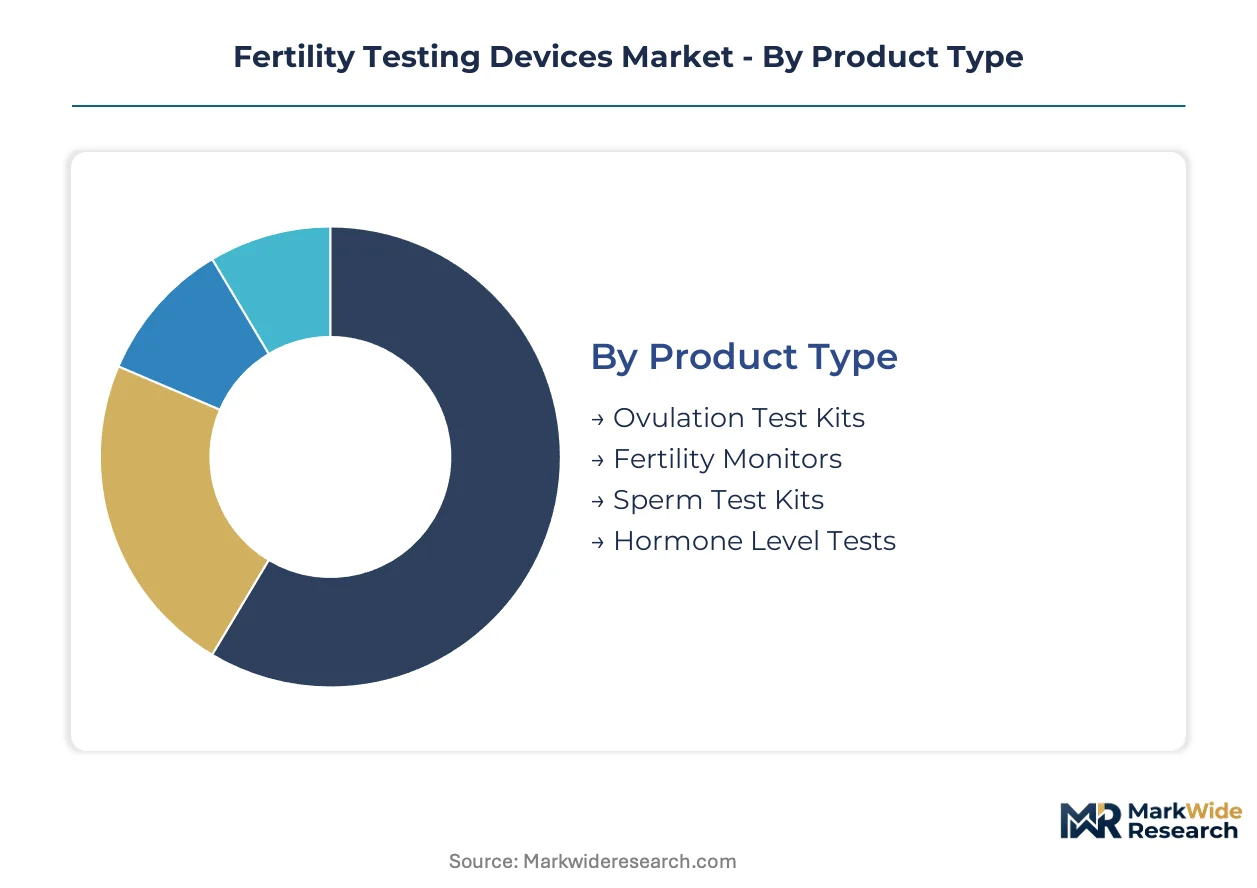
Fertility testing devices fragment across product formats, sensing technologies, and procurement channels that face divergent substitution pressures from consumer electronics and telehealth platforms. Understanding these segment boundaries clarifies where algorithm validation costs and wearable miniaturization investments concentrate competitive returns.
Product Type:
Smartwatch fertility tracking features exert the strongest substitution pressure on single-use consumables, forcing kit manufacturers to defend pharmacy shelf space through price compression while premium sensor hardware pursues subscription monetization.
- Ovulation Test Kits:Lateral flow immunoassay strips detecting urinary LH surges at 25-50 mIU/mL sensitivity thresholds. Demand concentrates in United States pharmacy chains where employer fertility benefits normalize bulk purchasing; FDA 510(k) clearance requirements protect incumbent manufacturers from unvalidated imports.
- Fertility Monitors:Durable hardware combining basal body temperature sensors with cloud-based cycle prediction algorithms. Expansion concentrates among women aged 30-40 in direct-to-consumer channels; continuous biosensor miniaturization enables medical-grade accuracy at consumer price points.
- Sperm Test Kits:Smartphone microscopy attachments applying computer vision to WHO morphology standards for home-based semen analysis.
- Hormone Level Tests:Quantitative progesterone and estradiol assays requiring laboratory infrastructure or connected reader devices.
Ovulation test kits retain volume leadership; fertility monitors hold the steepest expansion curve.
Technology:
Cost tier stratification separates disposable reagent-based methods from capital-intensive connected platforms, with reimbursement policy determining where clinical-grade precision penetrates consumer markets.
- Urine Analysis:Colorimetric and immunochromatographic detection of LH, hCG, and estrogen metabolites in single-use strip format. Volume concentrates in Germany and Switzerland manufacturing clusters; antibody supplier concentration creates single-source dependency risks for test kit assemblers.
- Wearable Devices:Skin-worn temperature and bioimpedance sensors transmitting continuous data to fertility prediction algorithms. Adoption accelerates in United States employer-sponsored benefit programs; subscription pricing models capture lifetime value beyond hardware margins.
- Blood Test:Finger-prick capillary sampling for quantitative hormone panels analyzed via desktop reader or mail-in laboratory services.
- App-Based Monitoring:Software-only cycle tracking relying on user-inputted symptoms and calendar algorithms; FDA Software as a Medical Device enforcement bifurcates this segment into validated clinical tools and unregulated wellness trackers.
Urine analysis retains volume leadership; wearable devices hold the steepest expansion curve.
End User:
Customer type determines regulatory pathway complexity, with clinical procurement requiring ISO 13485 documentation and notified body relationships that exclude unqualified entrants.
- Individuals:Direct purchasers seeking conception timing or early subfertility identification without clinical intervention. United States demand dominates through telehealth platform integration; Maven and Progyny APIs embed fertility testing into remote monitoring subscriptions.
- Fertility Centers:Specialized clinics requiring quantitative hormone assays and semen analysis for treatment planning. Europe's MDR post-market surveillance mandates create competitive moats for manufacturers with established notified body relationships.
- Clinics:General practice and obstetric settings employing rapid fertility screening as referral triage.
- Hospitals:Acute care settings with centralized laboratory infrastructure for comprehensive reproductive endocrinology panels.
Individuals retain volume leadership; fertility centers hold the steepest expansion curve.
Distribution Channel:
Geography shapes channel viability, with pharmacy density and e-commerce logistics maturity determining where direct-to-consumer disintermediation outperforms traditional retail.
- Online Retail:Third-party marketplace and dedicated e-commerce fulfillment of test kits and sensor hardware. India's 850,000 retail pharmacy outlets now permit over-the-counter fertility test sales under CDSCO medical device rules; direct distribution bypasses fragmented wholesale layers.
- Direct-to-Consumer:Subscription models shipping personalized hormone panels with algorithm-adjusted testing schedules. United States employer fertility benefits normalize at-home diagnostic spending without insurance pre-authorization friction.
- Pharmacies:Brick-and-mortar retail chains stocking ovulation test kits adjacent to pregnancy and family planning categories.
- Medical Supply Stores:Professional distributors serving clinical procurement with bulk pricing and equipment service contracts.
Online retail retains volume leadership; direct-to-consumer holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics hub underwrites Europe's fertility testing distribution, while the Port of Long Beach anchors Pacific Rim supply chains into the United States. These maritime gateways determine where regulatory batch releases and cold-chain hormone reagents reach consumer markets fastest.
United States
Employer-sponsored fertility benefits at Fortune 500 companies now subsidize ovulation tracking kits as standard health plan inclusions. FDA 510(k) premarket notification pathways govern home-use fertility tests, tightening validation requirements for algorithm-based ovulation predictors. The Greater Boston corridor hosts connected device startups developing subscription-based fertility coaching platforms with medical-grade biosensor accuracy.
Germany
Antibody and enzyme suppliers for urinary LH detection concentrate in German manufacturing clusters, creating single-source dependency risks for European test kit assemblers. REACH chemical safety regulations and MDR clinical evidence standards impose post-market surveillance mandates on connected fertility devices. The Rhine-Ruhr industrial belt sustains precision diagnostics manufacturing for pharmacy chain distribution across the continent.
Switzerland
Premium ovulation test kit output flows from Swiss manufacturing bases to pharmacy chains throughout Europe and export markets. Swissmedic medical device regulations align with MDR requirements while maintaining distinct notified body relationships for CE marking. The Basel-Zurich corridor anchors precision diagnostics production with established quality management certifications.
India
CDSCO medical device rules now permit over-the-counter fertility test sales, opening direct distribution through India's 850,000 retail pharmacy outlets. The country's national pharmaceutical regulator has streamlined import licensing for diagnostic reagents while tightening post-market surveillance for software-integrated devices. Maharashtra's Mumbai-Pune industrial corridor hosts contract manufacturing for lateral flow immunoassay assembly serving domestic and export markets.
United Kingdom
Telehealth platform integration through Maven and Progyny APIs embeds fertility testing into remote monitoring subscriptions for working-age women. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit, creating parallel conformity assessment pathways to EU MDR. The Oxford-Cambridge arc concentrates algorithm development for cycle prediction software seeking dual regulatory clearance.
Fertility Testing Devices Market Vendor Landscape
Concentration sits with diversified diagnostics conglomerates and precision manufacturing specialists rather than pure-play fertility device vendors. The vendor base spans three tiers: multinational conglomerates with broad diagnostic infrastructure, European precision manufacturers with established notified body relationships, and venture-backed connected device startups pursuing subscription monetization. Two competitive moves dominate: strategic partnerships with telehealth platforms for API integration, and geographic expansion into India's newly liberalized pharmacy channel.
Among diversified diagnostics conglomerates, Abbott Laboratories and Quidel Corporation represent scale-driven archetypes with clinical and over-the-counter channel presence. SPD Swiss Precision Diagnostics GmbH exemplifies the European precision manufacturing tier, leveraging Swiss-based production for premium ovulation test kit output. Within the specialty consumer health segment, Church & Dwight Co., Inc. and Prestige Consumer Healthcare, Inc. occupy positions adjacent to pharmacy retail distribution, while Geratherm Medical AG and bioZhena Corporation represent mid-cap specialists in temperature-based fertility monitoring.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| SPD Swiss Precision Diagnostics GmbH |
| Prestige Consumer Healthcare, Inc. |
| Quidel Corporation |
| Geratherm Medical AG |
| bioZhena Corporation |
| Mira |
| Fairhaven Health |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with German and Swiss antibody suppliers lock in ovulation test kit manufacturers against raw material price volatility while securing multi-year supply visibility for FDA 510(k) cleared product lines. These arrangements concentrate pricing power with incumbent diagnostic conglomerates that can commit to volume minimums, forcing smaller assemblers toward spot-market reagent sourcing with compressed margins.
Pricing Analysis
Volume-discount tiering separates enterprise fertility benefit contracts from individual pharmacy purchases. Three-tier pricing structure across premium connected monitors, standard lateral flow kits, and economy strip formats reflects ISO 13485 certification status and algorithm validation depth. Pricing pressure stems from smartwatch fertility features capturing basal body temperature data without dedicated hardware purchases. Employer-sponsored programs show lowest price sensitivity; uninsured direct consumers face highest cost elasticity.
Supply Chain Analysis
Inventory lead times for European MDR CE marking extend to fourteen months for novel connected devices, forcing manufacturers to pre-position finished goods ahead of regulatory approval. Antibody and enzyme production concentrates in Germany, Switzerland, and the United States, with single-source dependencies for urinary LH detection reagents. Supply chain risk centers on notified body capacity constraints delaying market entry. Distribution runs through pharmacy chains in developed markets and direct-to-consumer subscription platforms in employer benefit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large US employers that negotiate enterprise fertility benefit contracts, fragmenting price-setting authority away from individual consumers and toward procurement committees at Fortune 500 companies.
For Market Incumbents: Shield algorithm-validated product lines from smartwatch substitution by embedding fertility monitors into telehealth platform APIs at Maven and Progyny. Deepen backward integration into Swiss and German antibody supply through long-term offtake agreements that exclude emerging competitors from critical reagent access. For New Entrants and Emerging Players: Differentiate on AI-integrated sperm analysis for male factor infertility screening, a segment with minimal incumbent presence and lower regulatory burden than hormone monitoring. Target India's 850,000 retail pharmacy outlets under CDSCO over-the-counter rules, using direct distribution partnerships to bypass fragmented wholesale layers. For Investors and Strategic Acquirers: Connected device startups with established FDA 510(k) clearances and recurring subscription revenue represent the most defensible acquisition archetype. Watch FDA Software as a Medical Device enforcement intensity as the signal indicating whether algorithm-based platforms warrant premium valuations or face wellness-tracker compression.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform API Integration | Embedding fertility testing into Maven and Progyny interfaces creates recurring subscription revenue streams. |
| FDA 510(k) Submission Acceleration | Validated algorithm claims separate clinical tools from unregulated wellness trackers under SaMD enforcement. |
| Indian Pharmacy Channel Expansion | CDSCO over-the-counter rules enable direct distribution through 850,000 retail outlets without wholesale friction. |
| Antibody Supplier Backward Integration | In-house production of LH detection reagents insulates against German and Swiss single-source dependencies. |
| Continuous Biosensor Miniaturization | Medical-grade accuracy at consumer price points enables subscription-based fertility coaching platforms. |
Methodological Framework
Cross-validation between regulatory filing analysis and clinical validation databases anchors the qualitative findings on algorithm accuracy claims. Primary interviews with reproductive endocrinologists, fertility clinic laboratory directors, employer benefits managers, and connected device product managers combined with secondary review of FDA 510(k) clearances, CDSCO medical device registrations, and European MDR notified body documentation. Bottom-up demand modeling triangulates against top-down diagnostic spending estimates.
Sensitivity analysis across adoption rate scenarios and reimbursement policy shifts informs the projection framework. Segmentation dimensions include product format, sensing technology, end-user setting, and distribution channel, with geographic regulatory clusters treated as distinct demand environments. CAGRs derive from fitted growth curves against historical penetration patterns, with continuous biosensor cost curves and employer benefit expansion rates as key fertility-specific inputs.
Material uncertainties — regulatory enforcement intensity, notified body capacity constraints, and smartwatch feature expansion — sit outside the modeled envelope. Forecasts reflect assumptions about algorithm validation timelines and subscription retention rates. Revision becomes warranted when FDA SaMD enforcement crosses thresholds that bifurcate the app-based monitoring segment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Global Immunoassay Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Veterinary Chemistry Analyzers Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market