
 Cryogenic Ampoules Market | 2026-2036
Cryogenic Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Ampoules Market Outlook
ISO 13485 certification is bifurcating the competitive landscape into qualified medical device suppliers and general laboratory vendors. Thermo Fisher Scientific leverages its vertically integrated cold chain portfolio to sustain dominance in validated cryogenic storage systems. DWK Life Sciences anchors European supply through specialized borosilicate glass manufacturing capabilities. Eppendorf competes on precision filling technology integration for automated biobanking workflows.
Cryogenic ampoules are sealed, sterile containers engineered from borosilicate glass or fluoropolymer resins to withstand thermal cycling between ambient and liquid nitrogen temperatures, typically rated for storage at minus 196 degrees Celsius. Glass ampoules dominate pharmaceutical applications due to inert surface properties and USP Type I compliance, while plastic variants gain traction in transport-intensive biologics logistics where breakage risk governs material selection. Automatic filling technology captures the fastest expansion as cell and gene therapy manufacturers scale cryopreservation throughput, whereas manual filling persists in research institutions where batch flexibility outweighs speed requirements.
FDA 21 CFR Part 820 quality system regulation and EU MDR technical documentation requirements shape material qualification timelines and supplier audit intensity for cryogenic ampoule manufacturers entering clinical-grade markets. ISO 20387 biobanking standards and WHO guidance on specimen transport further define performance benchmarks for thermal integrity and sterility assurance across international distribution networks. Stakeholders must monitor evolving cell therapy regulatory pathways to align ampoule validation protocols with commercial manufacturing scale-up timelines.
Market Dynamics
Cell therapy commercialization timelines are compressing validation cycles for cryogenic ampoules, forcing manufacturers to reconcile laboratory-scale flexibility with pharmaceutical-grade reproducibility under intensifying FDA and EMA scrutiny.
Growth Catalysts
- CAR-T manufacturing scale-up:Autologous cell therapy production lines in the United States and Germany are multiplying demand for validated, traceable cryogenic storage vessels.
- EU MDR technical documentation mandates:Stricter biocompatibility and sterilization validation requirements are filtering out unqualified suppliers and consolidating procurement toward certified medical device vendors.
- Liquid nitrogen infrastructure expansion:Biobank construction in Japan and South Korea is extending the addressable base for minus 196 degrees Celsius rated containment systems.
Market Restraints
- Borosilicate glass supply concentration:Specialty glass feedstock production clusters in Germany and China, creating geographic vulnerability to energy cost spikes or export restrictions.
- ISO 13485 certification timelines:Eighteen to twenty-four month quality system implementation periods delay market entry for new entrants targeting clinical-grade applications.
- Fluoropolymer resin cost volatility:Perfluoroalkoxy (PFA) and polytetrafluoroethylene (PTFE) raw material prices fluctuate with semiconductor industry demand cycles, squeezing margins on plastic ampoule variants.
Strategic Opportunities
- India biologics manufacturing:CDSCO regulatory harmonization efforts and PLI scheme incentives for biotechnology are attracting cold chain infrastructure investment from multinational ampoule suppliers.
- Automated filling system integration:Convergence of precision robotics with cryogenic handling protocols is opening specification partnerships with cell therapy equipment OEMs.
- WHO prequalification pathway:Compliance with international specimen transport guidance is enabling access to vaccine and diagnostic sample distribution networks in low- and middle-income countries.
Industry Challenges
- Cryogenic engineering talent scarcity:Cross-disciplinary expertise spanning materials science, sterile processing, and regulatory affairs remains concentrated among senior specialists at established manufacturers.
- Legacy biobank system interoperability:Automated retrieval and inventory management platforms from the 2000s require custom adapter development for modern ampoule form factors and barcode standards.
- Validation documentation burden:Customer-specific extractables and leachables studies for each drug-ampoule combination extend sales cycles and strain analytical chemistry capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Ampoules Market |
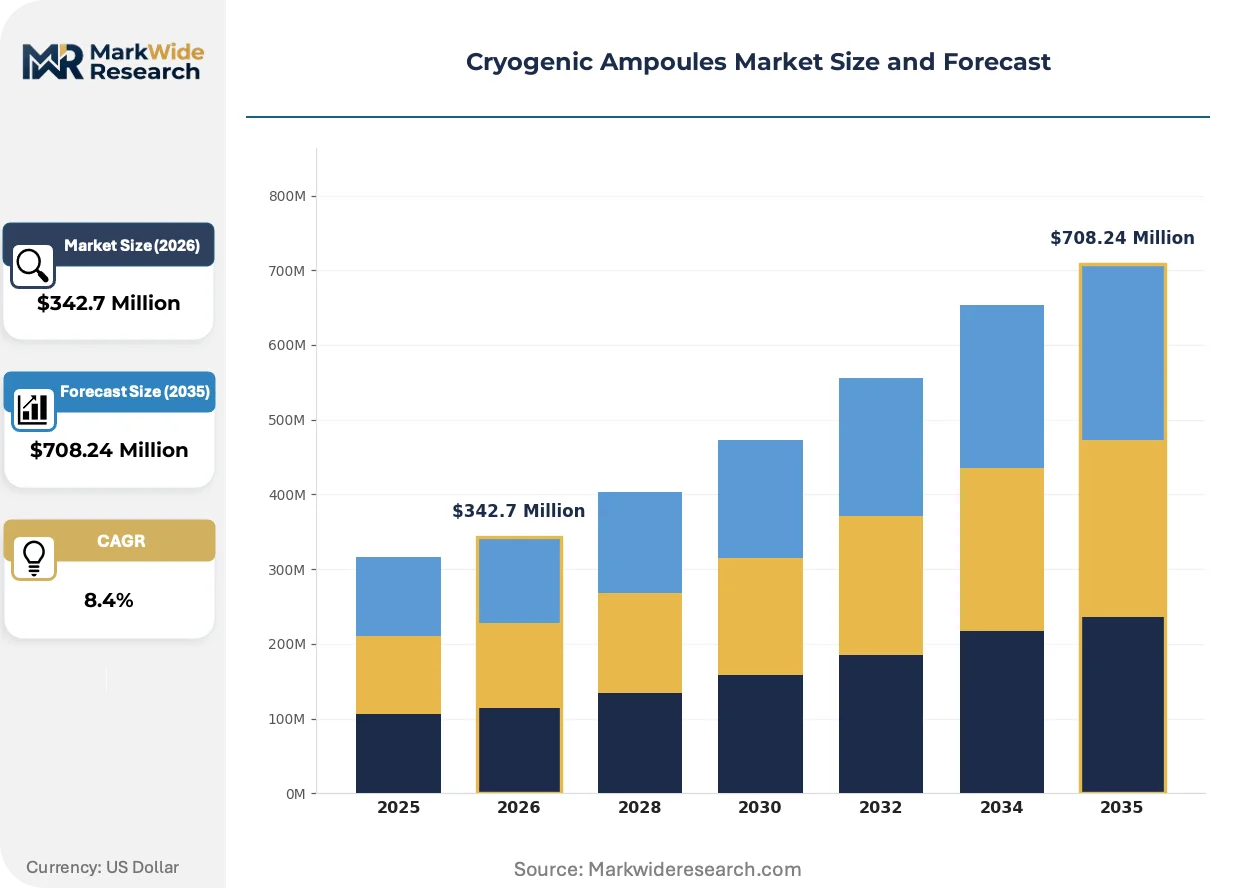
| Market Size in 2026 | $342.7 Million |
| Market Size in 2035 | $708.24 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Metal, Composite End User: Pharmaceuticals, Biotechnology, Research Institutions, Laboratories Application: Storage, Transport, Sample Preservation, Cryopreservation Technology: Manual Filling, Automatic Filling, Semi-Automatic Filling, Freeze-Drying |
| Companies Covered | Thermo Fisher Scientific, Corning Incorporated, DWK Life Sciences, Nalgene, Sumitomo Bakelite, CellPath, Greiner Bio-One, Eppendorf, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Ampoules Market Strategic Shifts
Material science advances and regulatory digitization are restructuring competitive advantage around thermal performance validation and supply chain transparency rather than commodity manufacturing scale.
Fluoropolymer resin formulations are bifurcating the product architecture between pharmaceutical-grade glass and transport-optimized plastics. Cell therapy logistics providers in the United States are specifying PFA ampoules for international courier networks where breakage rates exceed one percent. This material shift is compressing addressable margins for general laboratory glassware suppliers while rewarding resin compounders with medical device master files.
EMA's F-Gas Regulation phase-down schedules are accelerating refrigerant infrastructure decisions across European biobanking operations. Liquid nitrogen generation and distribution systems face upgrade timelines that synchronize with ampoule procurement cycles, creating bundled specification opportunities. German and Swiss biorepositories are prioritizing suppliers with documented carbon footprint accounting for transport packaging.
Biopharmaceutical procurement departments are consolidating vendor panels around integrated cold chain service contracts rather than discrete component purchasing. Cell therapy developers in Boston, San Francisco, and Basel are negotiating multi-year supply agreements that bundle ampoules with liquid nitrogen dewar leasing and temperature monitoring telemetry. This contract restructuring favors manufacturers with captive logistics partnerships or backward integration into cryogenic equipment.
Cryogenic Ampoules Market Segmentation
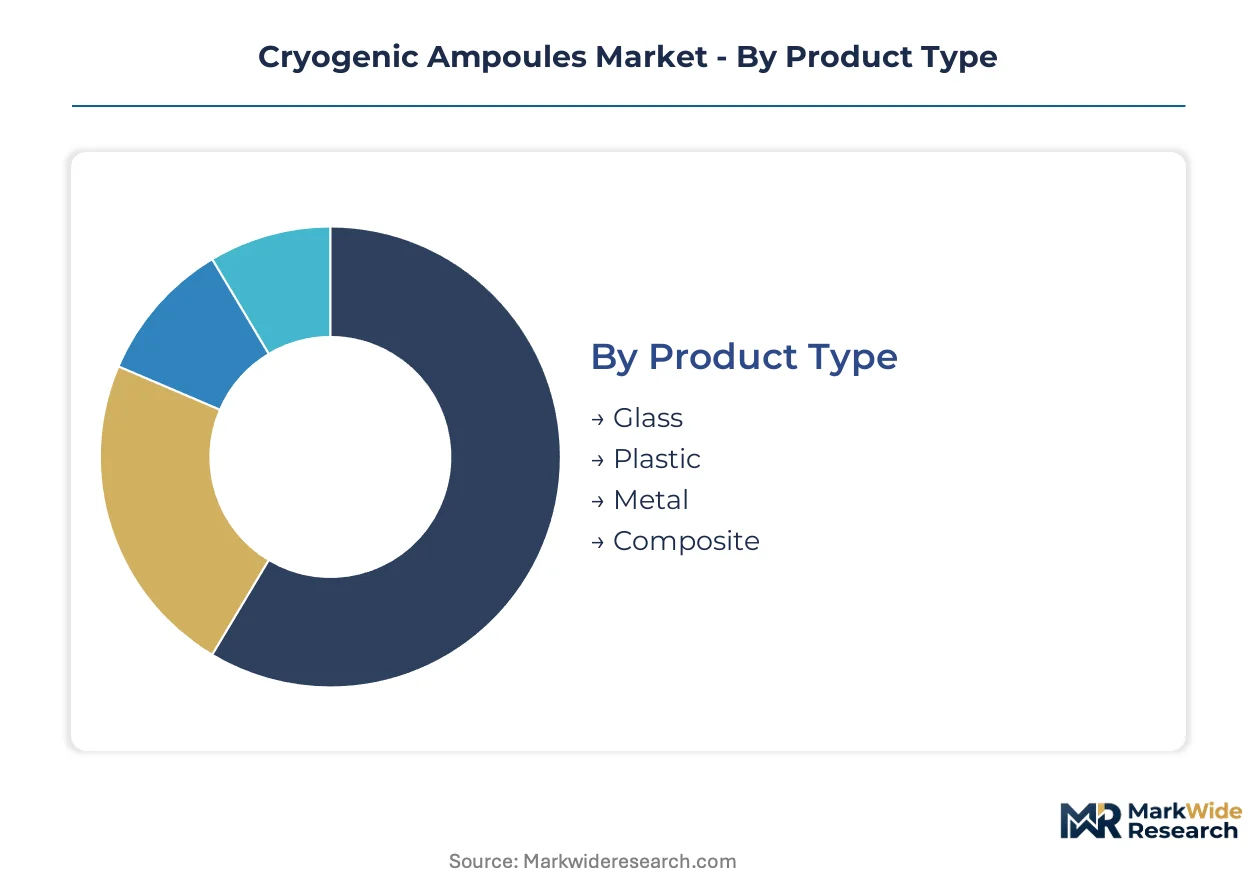
Cryogenic ampoule procurement splits sharply between validated clinical-grade specifications and research-grade flexibility. Material selection, filling automation, and end-use regulatory requirements create distinct margin tiers that reshape supplier positioning across the value chain.
Product Type:
Glass ampoules command premium pricing in pharmaceutical applications where USP Type I compliance and extractables documentation justify material costs. Plastic variants capture transport-intensive segments where breakage risk governs total cost of ownership calculations.
- Glass:Borosilicate formulations rated for minus 196 degrees Celsius thermal cycling dominate cell therapy storage in the United States and Germany. FDA 21 CFR Part 820 quality system requirements and EU MDR technical documentation mandates filter procurement toward ISO 13485-certified glass manufacturers with validated sterilization protocols.
- Plastic:Fluoropolymer resins including PFA and PTFE withstand mechanical stress in international courier networks where glass breakage rates exceed operational thresholds. Perfluoroalkoxy ampoules are gaining specification from logistics providers serving Boston and San Francisco cell therapy clusters despite raw material cost volatility tied to semiconductor industry demand cycles.
- Metal:Stainless steel containment systems serve specialized industrial cryogenics applications outside biopharmaceutical primary use cases.
- Composite:Hybrid material constructions address niche thermal-mechanical performance requirements in aerospace and defense specimen preservation.
Glass holds installed capacity. Plastic is rotating up the share rankings.
End User:
Pharmaceutical manufacturers drive specification complexity through drug-master file requirements and supplier audit intensity. Research institutions prioritize batch flexibility and catalog availability over validation documentation depth.
- Pharmaceuticals:Commercial cell therapy producers in Germany and Japan require lot-level traceability, sterility assurance, and extractables studies for each drug-ampoule combination. EMA and PMDA submission timelines compress procurement decisions toward pre-qualified medical device vendors.
- Biotechnology:Venture-stage developers in Basel and Cambridge balance clinical-grade validation preparation with research-scale flexibility, often dual-sourcing from qualified and general laboratory suppliers during scale-up transitions.
- Research Institutions:Academic biobanks and university laboratories prioritize manual filling compatibility and small-batch availability over automated throughput specifications.
- Laboratories:Contract research organizations and analytical testing facilities source commodity-grade ampoules for non-GMP sample handling workflows.
Pharmaceuticals anchor revenue concentration. Biotechnology is climbing the fastest.
Application:
Storage applications concentrate value in long-term containment reliability, while transport segments prioritize mechanical durability and temperature monitoring integration.
- Storage:Minus 196 degrees Celsius rated systems for liquid nitrogen biobanks represent the core revenue pool, with Japanese and South Korean infrastructure expansion extending addressable demand. ISO 20387 biobanking standards define thermal integrity benchmarks that filter supplier qualification.
- Transport:International specimen distribution networks specify breakage-resistant containment with integrated temperature loggers, particularly for CAR-T therapy logistics between the United States and European treatment centers.
- Sample Preservation:Diagnostic and vaccine specimen repositories require WHO-compliant transport packaging for distribution to low- and middle-income countries.
- Cryopreservation:Cell and gene therapy manufacturing workflows demand validated freezing and thawing protocols with documented thermal profiles.
Storage dominates installed base. Transport is gaining share fastest.
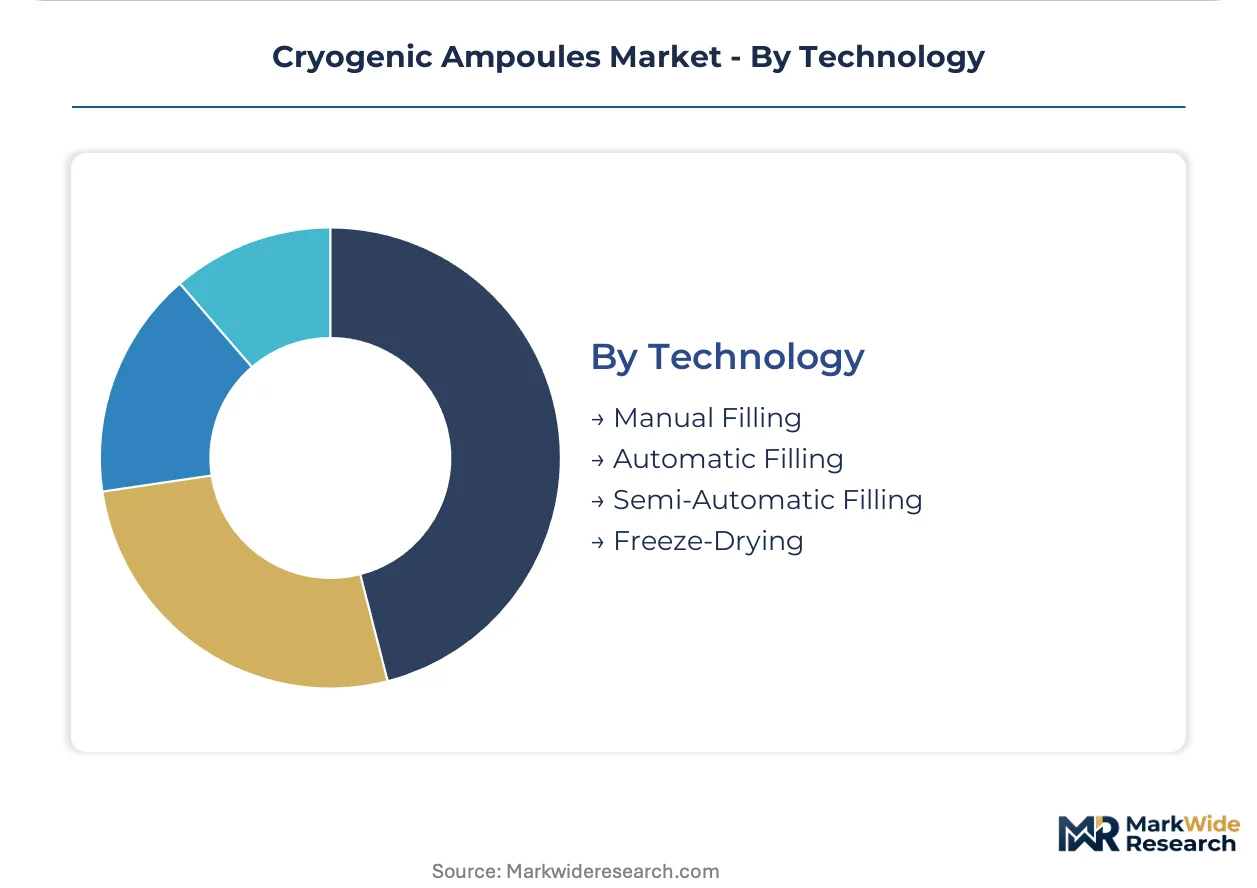
Technology:
Automation level determines throughput scalability and regulatory validation burden, with automatic filling systems capturing investment from commercial-scale cell therapy manufacturers.
- Manual Filling:Research institutions and early-stage developers maintain batch flexibility through hand-operated sealing and labeling workflows where speed requirements remain modest.
- Automatic Filling:Precision robotics integration with cryogenic handling protocols supports CAR-T manufacturing scale-up in the United States and Germany. Cell therapy equipment OEMs are specifying ampoule formats compatible with automated biobanking retrieval systems.
- Semi-Automatic Filling:Mid-scale biotechnology operations balance throughput gains with capital expenditure constraints through partially automated workflows.
- Freeze-Drying:Lyophilization-compatible ampoule designs address specialized biologics stabilization requirements outside standard cryogenic liquid storage protocols.
Manual filling retains volume leadership. Automatic filling is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government biotechnology incentives and specialized cold chain infrastructure investments are concentrating cryogenic ampoule procurement in five national markets. Each jurisdiction applies distinct regulatory frameworks that filter supplier qualification toward certified medical device manufacturers.
United States
FDA 21 CFR Part 820 quality system requirements govern commercial cell therapy manufacturing in Boston and San Francisco. CAR-T production scale-up in these clusters multiplies demand for validated, traceable cryogenic storage vessels with lot-level documentation. Autologous therapy developers are consolidating procurement toward ISO 13485-certified suppliers with established drug master files.
Germany
EU MDR technical documentation mandates and EMA's F-Gas Regulation phase-down schedules are synchronizing biobank infrastructure decisions with ampoule procurement cycles. DWK Life Sciences anchors European borosilicate glass supply through specialized manufacturing capabilities in the country. German biorepositories are prioritizing suppliers with documented carbon footprint accounting for transport packaging.
Japan
PMDA submission timelines for regenerative medicine products compress procurement decisions toward pre-qualified medical device vendors. Liquid nitrogen biobank construction is extending the addressable base for minus 196 degrees Celsius rated containment systems. Tokyo and Osaka cell therapy clusters specify ampoules with integrated automated retrieval compatibility.
South Korea
MFDS regulatory harmonization with international standards is attracting cold chain infrastructure investment from multinational suppliers. National biobank expansion programs are creating bundled specification opportunities for cryogenic storage systems. Seoul metropolitan area biorepositories are integrating precision robotics with cryogenic handling protocols.
India
CDSCO regulatory harmonization efforts and PLI scheme incentives for biotechnology are attracting multinational ampoule suppliers to establish local distribution. Maharashtra and Karnataka biologics manufacturing clusters are developing cold chain capabilities to serve export markets. Domestic procurement is shifting from research-grade flexibility toward clinical-grade validation preparation.
Cryogenic Ampoules Market Competitive Environment
Player mix skews toward diversified laboratory equipment conglomerates with captive cryogenic portfolios and specialized glassware manufacturers with medical device certifications. Market structure exhibits tiered consolidation around ISO 13485-certified suppliers for clinical applications and fragmented competition in research-grade segments. Strategic archetypes include vertically integrated cold chain providers, specialized borosilicate glass fabricators, and precision filling technology specialists. Dominant competitive moves encompass strategic partnerships with cell therapy equipment OEMs and backward integration into fluoropolymer resin compounding.
Among diversified laboratory conglomerates, Thermo Fisher Scientific occupies a position exemplifying the integrated cold chain archetype through its vertically structured portfolio. DWK Life Sciences represents the specialized glassware manufacturer tier with European manufacturing concentration. Eppendorf sits within the precision technology specialist category, anchoring automated biobanking workflow integration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning Incorporated |
| DWK Life Sciences |
| Nalgene |
| Sumitomo Bakelite |
| CellPath |
| Greiner Bio-One |
| Eppendorf |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month ISO 13485 certification timelines concentrate pricing power among established German and US medical device suppliers, while research-grade buyers face softer negotiations with fragmented laboratory vendors. This lead-time differential bifurcates procurement into validated clinical tiers with locked-in contracts and flexible research segments exposed to spot-market volatility.
Pricing Analysis
Certification level creates the primary spread between premium ISO 13485-validated clinical tiers and economy research-grade offerings. Three-tier pricing structure across premium, standard, and economy levels reflects USP Type I compliance depth, extractables documentation bundles, and sterilization validation scope. Cost compression in plastic variants intensifies because fluoropolymer resin prices fluctuate with semiconductor demand cycles. Academic biobanks and early-stage developers exhibit highest price sensitivity, whereas commercial cell therapy manufacturers prioritize qualification depth over unit economics.
Supply Chain Analysis
Strategic stockpiling of borosilicate glass feedstock dominates German and Chinese supplier strategies against energy cost volatility, while just-in-time resin procurement prevails among plastic ampoule specialists. Manufacturing gravity centers on Germany for specialty glass and China for fluoropolymer resin compounding, with secondary fabrication in the United States and Japan. Single-source vulnerability concentrates in German borosilicate feedstock production clusters exposed to export restriction risk. Distribution runs through medical device distributors for clinical-grade volumes and laboratory supply catalogs for research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy commercialization timelines fragment procurement into distinct validation tiers, creating white-space opportunities for specialists bridging laboratory flexibility and pharmaceutical-grade reproducibility.
For Market Incumbents: Secure backward integration into fluoropolymer resin compounding to insulate margins from semiconductor industry demand cycles. Deepen ISO 20387 biobanking certification portfolios to defend against automated filling equipment OEMs expanding into consumables. Capacity addition in South Korea and India anchors regional procurement relationships before CDSCO and MFDS harmonization matures. For New Entrants and Emerging Players: Automated retrieval compatibility gaps in legacy biobank infrastructure from the 2000s offer specification partnership opportunities with upgrade-focused Japanese and German repositories. Target research institutions transitioning toward clinical-grade validation preparation in Basel and Cambridge clusters. Go-to-market leverage rests on extractables study bundling that compresses customer analytical chemistry burdens. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ISO 13485 certification barriers and customer-specific validation documentation requirements favor scaled medical device platforms over fragmented laboratory suppliers. Acquisition target archetypes include precision filling technology specialists and regional borosilicate glass fabricators with dormant medical device master files. Signal to watch is EMA F-Gas Regulation enforcement intensity synchronizing biobank infrastructure replacement cycles with ampoule procurement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Filters procurement toward qualified suppliers under EU MDR and FDA 21 CFR Part 820 timelines. |
| Automated Filling System Integration | Opens specification partnerships with CAR-T manufacturing equipment OEMs in Boston and Germany. |
| Fluoropolymer Resin Backward Integration | Captures margin compression from semiconductor demand cycle volatility in PFA and PTFE feedstocks. |
| Carbon Footprint Accounting Documentation | Aligns with German and Swiss biorepository procurement priorities under EU Green Deal pressures. |
| WHO Prequalification Pathway Compliance | Enables access to vaccine and diagnostic specimen distribution networks in low- and middle-income countries. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with cell therapy manufacturing executives, biobank operations directors, regulatory affairs specialists, and laboratory procurement managers; and secondary validation against FDA 21 CFR Part 820 filings, EMA MDR technical documentation databases, ISO 20387 biobanking standards, and customs trade records for borosilicate glass and fluoropolymer resin flows. Bottom-up demand modeling from end-user segment procurement patterns triangulated against top-down supply-side capacity assessments across certified medical device manufacturers.
Across the projection horizon, the analytical framework modeled volume and value trajectories through product type segmentation by material grade, automation technology tier, end-use regulatory classification, and regional cold chain infrastructure maturity. CAGRs derived from segment-level growth rate distributions weighted by addressable base expansion in cell therapy clusters and biobank construction programs. Forecast inputs incorporated liquid nitrogen infrastructure investment pipelines and evolving EMA F-Gas Regulation phase-down schedules.
Forecasts assume regulatory continuity in FDA, EMA, PMDA, and CDSCO regimes; material policy shifts affecting sterilization validation protocols or biocompatibility testing requirements would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market