
 US and Europe Pharmaceutical Manufacturing Market | 2026-2036
US and Europe Pharmaceutical Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
US and Europe Pharmaceutical Manufacturing Market Intelligence
Multi-sourced biologics supply is realigning contract manufacturing relationships across the Atlantic. Lonza anchors cell-culture capacity in Switzerland and the United States through dedicated large-scale facilities. Pfizer leverages integrated small-molecule and mRNA platforms to sustain vertical control over critical therapies. Novartis competes through specialized radioligand manufacturing networks that serve narrow patient populations.
US and Europe pharmaceutical manufacturing encompasses the industrial production of active pharmaceutical ingredients, finished dosage forms, and biologic drug substances under current Good Manufacturing Practice standards, with batch sizes ranging from kilogram-scale chemical synthesis to multi-thousand-liter mammalian cell cultures. Its primary purpose is to convert raw materials into safe, effective, and quality-assured medicines for regulated health systems. Innovative drugs command the deepest margin pools due to patent-protected pricing and complex synthesis requirements, while biopharmaceuticals represent the fastest-expanding technology category as cell-culture titers improve and biosimilar competition intensifies. Generic drugs operate as a mature, volume-driven segment where continuous processing technology is displacing traditional batch methods to recover eroding margins.
FDA current Good Manufacturing Practice enforcement and EMA's Falsified Medicines Directive serialization requirements shape facility capital allocation and product traceability investments across both markets. The EPA and national environmental regulators in Germany and France impose solvent-recovery and waste-stream limits that filter out smaller chemical synthesis operations. Stakeholders must monitor how the EU AI Act and FDA's emerging guidance on artificial intelligence in manufacturing quality systems will reshape validation protocols and inspection priorities.
Market Dynamics
FDA's Quality Management Maturity program and EMA's accelerated assessment pathways are forcing manufacturers to front-load compliance investments before facility commissioning, compressing project timelines and reshaping capital deployment priorities across both markets.
Growth Catalysts
- Oncology biologics demand:Health systems in Germany and the United States are shifting toward precision medicine, expanding manufacturing capacity for patient-specific therapies.
- EMA accelerated pathways:Faster regulatory timelines for breakthrough therapies are pulling forward capacity investments in radioligand and cell-culture facilities.
- Continuous processing technology:Chemical synthesis operations are replacing batch methods to recover margins in generic drug production.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing clusters heavily in South Asian contract manufacturers, exposing Atlantic supply chains to single-point disruption risks.
- Specialized talent scarcity:Cell-culture process engineers and quality assurance specialists with biologics experience command premium compensation, constraining facility expansion pace.
- Environmental compliance costs:EPA solvent-recovery mandates and German waste-stream limits filter out smaller chemical synthesis operations unable to fund abatement infrastructure.
Strategic Opportunities
- AI-enabled quality systems:The EU AI Act and emerging FDA guidance on artificial intelligence in manufacturing are creating first-mover advantages for validated machine-learning process control.
- Radioligand therapy networks:Short half-life isotopes require distributed manufacturing close to treatment centers, opening regional hub opportunities in France and the northeastern United States.
- Serialization integration:EMA's Falsified Medicines Directive is driving demand for track-and-trace system upgrades across secondary packaging operations.
Industry Challenges
- Validation timeline compression:Concurrent process validation for accelerated approval pathways compresses traditional three-phase qualification schedules, increasing batch failure risk.
- Legacy system integration:Paper-based batch records and isolated process control systems resist migration to integrated digital manufacturing platforms, delaying real-time release implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Europe Pharmaceutical Manufacturing Market |
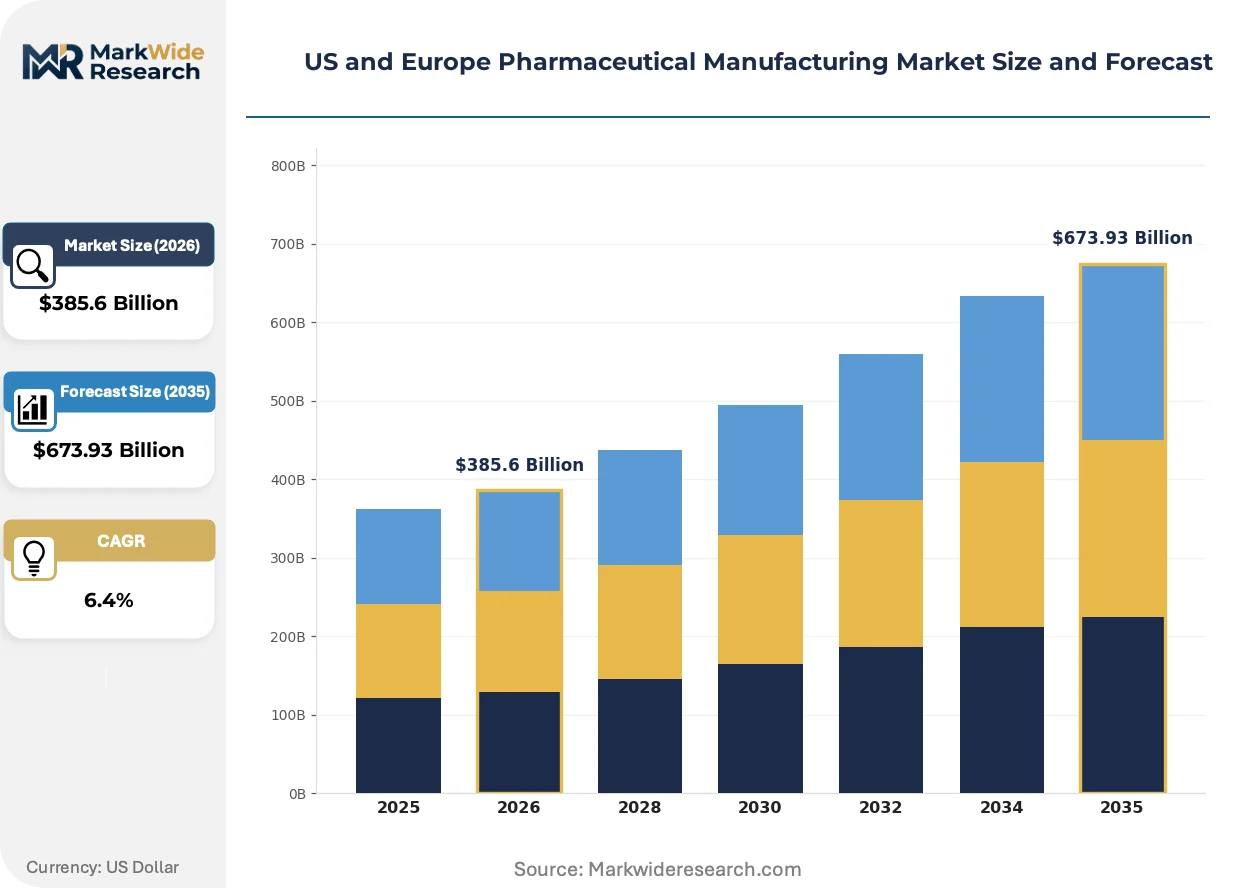
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $673.93 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innovative Drugs, Generic Drugs, Biopharmaceuticals, Over-the-Counter Technology: Batch Processing, Continuous Processing, Aseptic Processing, Cell Culture End User: Contract Manufacturers, Pharmaceutical Companies, Research Institutions, Hospitals Distribution Channel: Wholesale Distributors, Direct Sales, Retail Pharmacies, Online Pharmacies |
| Companies Covered | Pfizer Inc, Novartis AG, F. Hoffmann-La Roche Ltd, AbbVie Inc, Merck & Co., Inc, Johnson & Johnson Services, Inc, GSK plc, Sanofi, Lonza, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Europe Pharmaceutical Manufacturing Market Strategic Shifts & Innovations
Digital manufacturing architectures and modular facility designs are overtaking traditional stick-built construction approaches, enabling faster reconfiguration between product classes and reducing capital-at-risk for uncertain pipeline candidates.
Continuous manufacturing is overtaking batch processing in small-molecule oral solid dosage production. Generic manufacturers in Ireland and North Carolina are retrofitting legacy facilities with direct compression and hot-melt extrusion lines. This technology compression is enabling real-time release testing and shrinking quality control hold times from weeks to hours.
EMA's F-Gas Regulation and the EPA's phasedown of hydrofluorocarbon propellants are forcing respiratory drug manufacturers to reformulate metered-dose inhalers. The industrial consequence is a surge in investment in dry powder inhaler platforms and novel propellant alternatives. European facilities in the United Kingdom and Netherlands are leading this transition due to earlier regulatory deadlines.
Hospital procurement consortia are consolidating purchasing power for biosimilars and complex generics, displacing traditional wholesaler-mediated distribution in oncology and immunology categories. This concentration is most visible in Germany's university hospital networks and the United States' group purchasing organizations serving integrated delivery networks.
US and Europe Pharmaceutical Manufacturing Market Segmentation
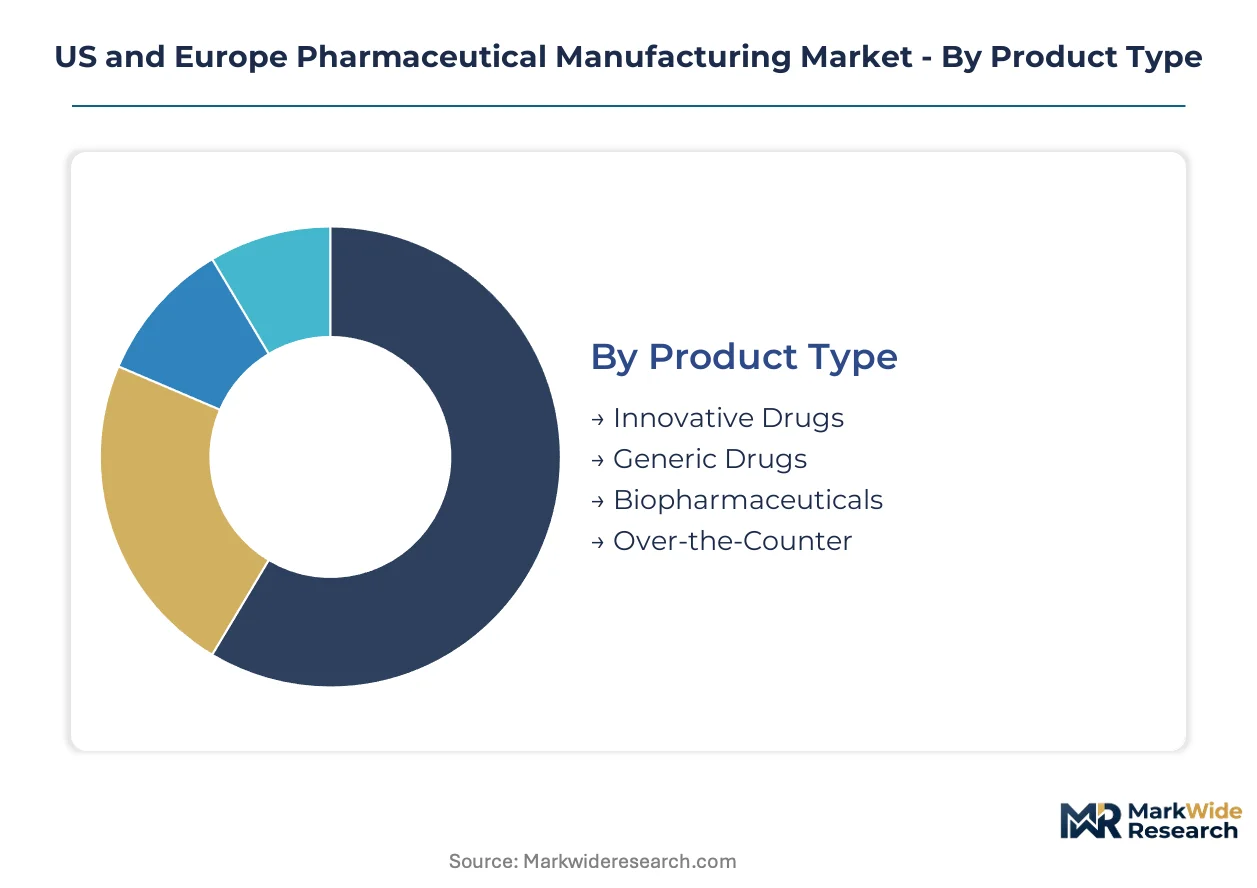
Segmentation reveals how capital allocation and facility design diverge across product classes and production technologies in the US and Europe pharmaceutical manufacturing market. Manufacturers must match process capabilities to specific therapeutic categories and customer procurement patterns to capture margin pools effectively.
Product Type:
Replacement cycles for manufacturing platforms accelerate as patent cliffs and biosimilar entry reshape portfolio economics across Atlantic facilities.
- Biopharmaceuticals:Protein-based therapeutics and monoclonal antibodies require mammalian cell-culture suites with single-use bioreactor systems. Demand concentrates in Massachusetts and Switzerland as oncology biologics pipelines expand and FDA's Quality Management Maturity program raises facility qualification standards.
- Innovative Drugs:Patent-protected small molecules and novel molecular entities command premium pricing through complex synthesis routes and specialized containment infrastructure. German chemical-pharma clusters and North Carolina's Research Triangle anchor capacity investments for high-potency active pharmaceutical ingredients.
- Generic Drugs:Off-patent small molecules compete on manufacturing efficiency and procurement scale. Continuous processing retrofits in Ireland and India-owned facilities in New Jersey recover margins eroded by hospital purchasing consortium consolidation.
- Over-the-Counter:Self-medication products including analgesics and digestive remedies utilize standardized oral solid dosage lines with high-throughput packaging operations.
Generic drugs sit at the top of the volume ranking, with biopharmaceuticals climbing the fastest as cell-culture titers improve and precision medicine pipelines mature.
Technology:
Capital deployment tilts toward platforms that compress batch cycle times and reduce quality control hold periods in regulated Atlantic markets.
- Cell Culture:Mammalian and microbial fermentation systems produce therapeutic proteins, viral vectors, and cell therapy substrates. Lonza's Switzerland and Maryland facilities anchor multi-thousand-liter stainless steel and single-use capacity for contract biologics production.
- Continuous Processing:Direct compression and hot-melt extrusion lines replace batch oral solid dosage manufacturing. Irish generic manufacturers and North Carolina facilities lead retrofits that enable real-time release testing and shrink quality assurance timelines from weeks to hours.
- Aseptic Processing:Isolator-based filling lines for injectable and ophthalmic products maintain sterility assurance through closed barrier systems and automated decontamination cycles.
- Batch Processing:Traditional chemical synthesis and blending operations persist for low-volume specialty compounds and legacy product portfolios with stable demand curves.
Batch processing retains the largest installed base, though continuous processing is gaining share fastest as generic manufacturers pursue margin recovery.
End User:
Procurement concentration among integrated health systems and research consortia is fragmenting the traditional pharmaceutical company-dominated demand profile.
- Contract Manufacturers:Outsourced development and manufacturing organizations provide flexible capacity for pipeline candidates and commercial supply. Pfizer's integrated network and specialized radioligand facilities compete with independent players for biologics and small-molecule contracts.
- Pharmaceutical Companies:Vertically integrated manufacturers retain in-house production for blockbuster therapies and platform technologies. Novartis maintains captive radioligand manufacturing networks to serve narrow patient populations with short half-life isotopes.
- Research Institutions:Academic medical centers and translational research facilities require small-scale GMP suites for early-phase clinical trial materials and investigator-initiated studies.
- Hospitals:In-house compounding and 503B outsourcing facilities prepare patient-specific formulations, particularly for oncology and parenteral nutrition protocols.
Pharmaceutical companies command the deepest capital reserves, while contract manufacturers are expanding most quickly as pipeline risk drives outsourcing preference.
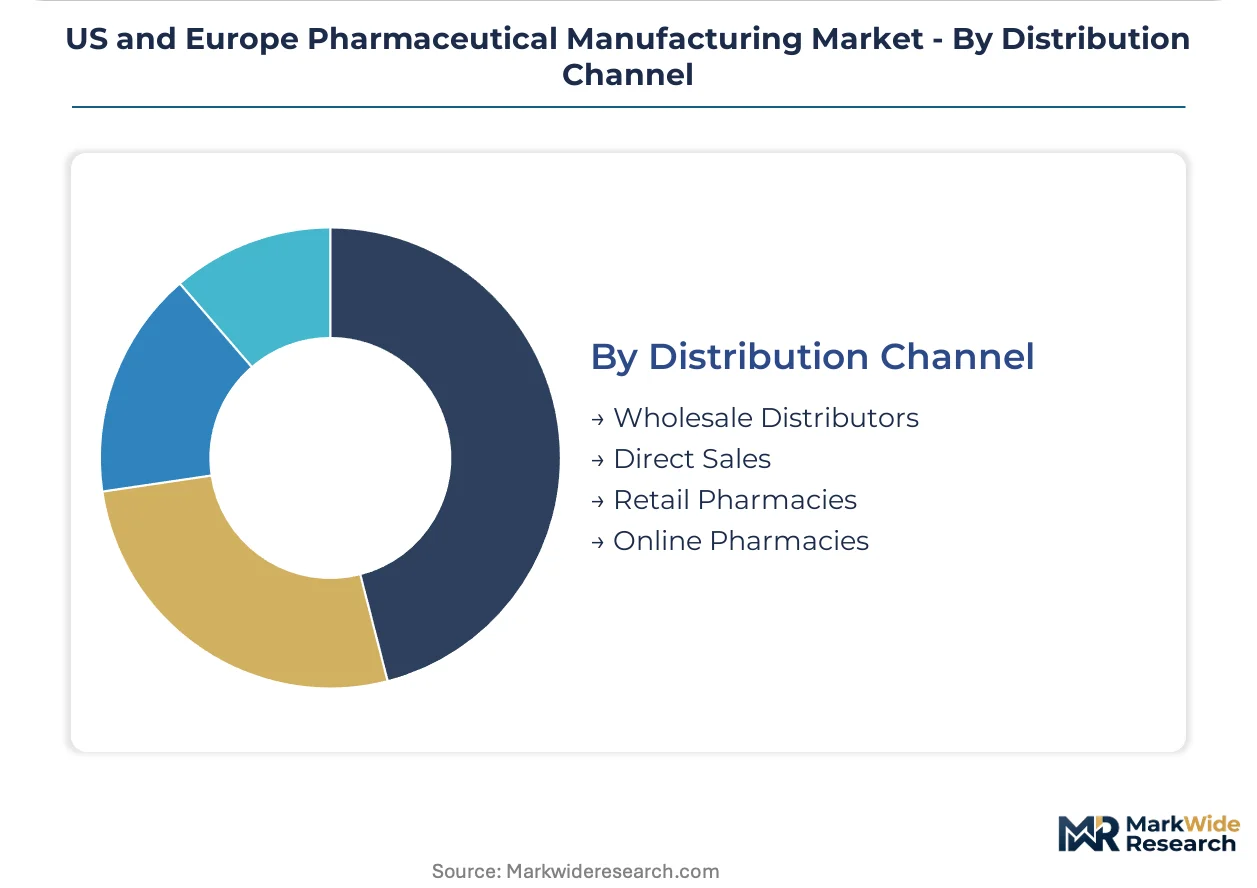
Distribution Channel:
Channel selection determines serialization investment requirements and cold-chain infrastructure specifications under EMA and FDA track-and-trace mandates.
- Wholesale Distributors:McKesson, AmerisourceBergen, and regional European wholesalers aggregate volume for pharmacy and hospital dispensing. EMA's Falsified Medicines Directive and the Drug Supply Chain Security Act mandate unit-level traceability investments across secondary packaging operations.
- Direct Sales:Manufacturer-to-hospital and manufacturer-to-specialty pharmacy shipments bypass wholesale intermediaries for high-value biologics and controlled substances. Germany's university hospital networks and United States integrated delivery networks concentrate purchasing power through direct procurement.
- Retail Pharmacies:Community and chain pharmacy dispensing requires regional distribution centers with temperature-controlled storage for refrigerated and frozen products.
- Online Pharmacies:Mail-order and digital-first dispensers expand last-mile delivery capabilities for chronic disease maintenance therapies and over-the-counter categories.
Wholesale distributors handle the largest transaction volumes, with direct sales channels climbing fastest as hospital procurement consolidation displaces traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is reshaping pharmaceutical production geography as manufacturers weigh FDA enforcement intensity against EMA's accelerated pathways. Facilities migrate toward jurisdictions where quality system investments yield faster market access.
United States
Oncology biologics and mRNA platform expansion drive capital deployment toward Massachusetts and North Carolina. FDA's Quality Management Maturity program front-loads compliance spending before facility commissioning. The Boston-Cambridge corridor concentrates cell-culture capacity as precision medicine pipelines mature.
Germany
Radioligand therapy networks and high-potency API synthesis anchor manufacturing investment in the Rhine-Main biotechnology cluster. EMA's accelerated assessment pathways pull forward capacity commitments for breakthrough therapies. Bavaria's chemical-pharma hubs specialize in containment infrastructure for complex small molecules.
Switzerland
Contract biologics manufacturing and mammalian cell-culture platforms concentrate around Basel and Visp. Swissmedic alignment with EMA standards reduces dual-registration burden for Atlantic-market products. Lonza's Visp facility anchors multi-thousand-liter stainless steel capacity for monoclonal antibody production.
United Kingdom
Dry powder inhaler platform transitions and respiratory drug reformulation dominate post-Brexit manufacturing strategy. EMA's F-Gas Regulation deadlines force earlier propellant phaseout than US EPA schedules. The Golden Triangle research corridor maintains early-phase clinical trial material capacity.
France
Short half-life isotope distribution networks and regional radioligand hubs serve dispersed oncology treatment centers. ANSM enforcement of EU serialization mandates drives secondary packaging traceability upgrades. The Paris-Saclay cluster concentrates specialized containment for potent compound handling.
US and Europe Pharmaceutical Manufacturing Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular facility architectures and AI-enabled quality systems. Market structure consolidates around vertically integrated pharmaceutical conglomerates and specialized contract manufacturing organizations. Three archetypes dominate: platform-technology owners, regional capacity specialists, and radioligand network operators. Competitive intensity manifests through strategic partnerships for pipeline access and geographic expansion into underserved therapeutic areas.
Among Swiss-based contract manufacturers, Lonza anchors multi-modal biologics capacity across Atlantic markets. Pfizer Inc represents integrated platform control spanning small-molecule and mRNA production. Novartis AG occupies a specialized position in radioligand therapy networks serving narrow patient populations with distributed manufacturing requirements.
| Leading Market Players |
|---|
| Pfizer Inc |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| AbbVie Inc |
| Merck & Co., Inc |
| Johnson & Johnson Services, Inc |
| GSK plc |
| Sanofi |
| Lonza |
| Others |
Cost & Logistics Intelligence
Captive biologics manufacturing networks in Switzerland and Massachusetts anchor supply security for precision oncology therapies while commanding premium pricing through FDA Quality Management Maturity qualification standards. This vertical integration pattern insulates innovators from API supply volatility and sustains margin pools unavailable to generic competitors dependent on South Asian contract manufacturers.
Pricing Analysis
Distributor margin compression in wholesale channels is intensifying as hospital procurement consortia in Germany and United States integrated delivery networks consolidate purchasing power for biosimilars and complex generics. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected biologics from authorized biosimilars and commodity generics, with price differentiation driven by FDA certification tier and volume scale commitments. Cost compression in oral solid dosage manufacturing is eroding margins for Irish and North Carolina facilities retrofitting to continuous processing. Generic drug manufacturers exhibit highest price sensitivity due to procurement consolidation, while radioligand therapy networks maintain pricing power through short half-life isotope logistics barriers.
Supply Chain Analysis
Returns and waste-stream flows from expired radioligand isotopes create specialized reverse-logistics requirements that constrain distribution radius and reinforce regional hub economics. Active pharmaceutical ingredient supply draws from India, China, and selected European facilities for high-potency compounds, with fermentation media and specialized containment equipment as critical input dependencies. Single-source vulnerability in South Asian API concentration exposes Atlantic formulation facilities to geopolitical disruption risks. Distribution runs through McKesson and AmerisourceBergen for wholesale aggregation, with direct-to-hospital channels expanding for temperature-controlled biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on continuous processing retrofits that compress quality control hold times and radioligand network proximity advantages that capture premium pricing for short half-life therapies.
For Market Incumbents: Acquire specialized radioligand manufacturing assets in France and the northeastern United States to defend against Novartis network expansion and emerging contract manufacturing entrants. Backward integration into single-use bioreactor supply chains reduces exposure to delivery bottlenecks for Massachusetts and Switzerland cell-culture capacity. FDA Quality Management Maturity certification investments create switching costs that lock in biologics outsourcing relationships. For New Entrants and Emerging Players: The premium-to-economy price gap in generic oral solid dosage manufacturing offers entry opportunity through continuous processing retrofits in Ireland and North Carolina secondary markets. Target hospital procurement consortia with real-time release testing capabilities that shrink inventory carrying costs for Germany's university hospital networks. Lead with modular facility architectures that reconfigure between product classes faster than legacy stick-built competitors. For Investors and Strategic Acquirers: Roll-up economics work for specialized radioligand network operators because EMA accelerated assessment pathways concentrate demand in distributed manufacturing assets with regulatory moats. Five-to-ten year viability favors platform-technology owners with mRNA and cell-culture capabilities over pure-play generic manufacturers facing procurement consolidation. Monitor FDA enforcement intensity shifts and EMA F-Gas Regulation implementation timelines as inflection indicators for facility geography arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Retrofit | Enables real-time release testing that shrinks quality control hold times from weeks to hours for Irish generic manufacturers. |
| Radioligand Hub Expansion | Positions regional facilities to capture short half-life isotope logistics premiums across France and northeastern United States oncology centers. |
| AI-Enabled Quality Systems | Creates first-mover validation advantages under EU AI Act and emerging FDA manufacturing guidance for process control. |
| Serialization Integration | Drives track-and-trace system upgrades meeting EMA Falsified Medicines Directive mandates across secondary packaging operations. |
| API Supply Diversification | Reduces single-point disruption exposure from South Asian concentration through European high-potency synthesis investments. |
Research Approach
Bottom-up biopharmaceutical demand modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Cross-referencing bottom-up pipeline analysis against top-down facility capacity announcements enables supply-demand balance assessment.
Input-output matrices map active pharmaceutical ingredient flows through formulation and finished dosage manufacturing to end-use demand across therapeutic categories. Segmentation dimensions include product type, technology platform, end user archetype, and regional regulatory cluster. CAGRs derive from facility investment announcements, patent expiration schedules, and biosimilar entry timelines analyzed across the projection horizon. Forecast inputs incorporate EMA accelerated pathway approval rates and FDA Quality Management Maturity program adoption curves.
Caveats apply where FDA enforcement intensity shifts, EMA regulatory timeline changes, or API supply disruptions could materially shift the outlook. Practitioners should monitor EMA F-Gas Regulation implementation progress and South Asian contract manufacturer geopolitical risk indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Radiosynthesis Equipment Market
Pharmaceutical Equipment
Automated Drug Kiosk Market