
 Global Patient Warming Systems Market | 2026-2036
Global Patient Warming Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Warming Systems Market Intelligence
China's expanding medical device manufacturing capacity is rewriting the supply dynamics for patient warming components. 3M Company leverages its deep material science expertise for its forced-air warming consumables. Stryker Corporation specializes in integrated solutions for modern operating rooms, while Medtronic plc focuses on patient monitoring and temperature management integration.
Patient warming systems are medical devices designed to maintain a patient's core body temperature, or normothermia. These systems utilize convective, conductive, or radiant heat transfer to prevent perioperative hypothermia. Forced air warmers continue to dominate the product segment due to their clinical effectiveness. Surgical procedures constitute the primary application, with hospitals and ambulatory surgery centers being the largest end-user categories.
Device approval and market access are governed by bodies like the US FDA, which requires 510(k) clearance, and Europe's CE marking process under the Medical Device Regulation (MDR). These regulations enforce strict performance, safety, and electrical standards for all patient-contact devices. The key decision for healthcare providers now revolves around balancing the clinical efficacy of single-use consumables with the operational costs of reusable systems.
Market Dynamics
The market's central dynamic is the tension between the clinical imperative for single-use consumables to prevent surgical site infections and the operational cost pressures on healthcare providers. This conflict shapes procurement decisions in hospitals, particularly in developed systems where quality metrics are paramount.
Growth Catalysts
- Strict Perioperative Guidelines:The implementation of stringent perioperative care protocols, aimed at reducing surgical site infections and mandated by healthcare quality bodies, directly drives the adoption of normothermia management systems in operating rooms.
- Surgical Volume Expansion:A rising global volume of surgical procedures, especially in specialties like orthopedics and cardiology, creates a consistent, volume-driven demand for patient warming systems to maintain normothermia during long operations.
- Healthcare Infrastructure Upgrades:Modernization of surgical suites in emerging economies and ambulatory surgery centers, aiming to meet international standards, is expanding the installed base for advanced patient warming technologies.
Market Restraints
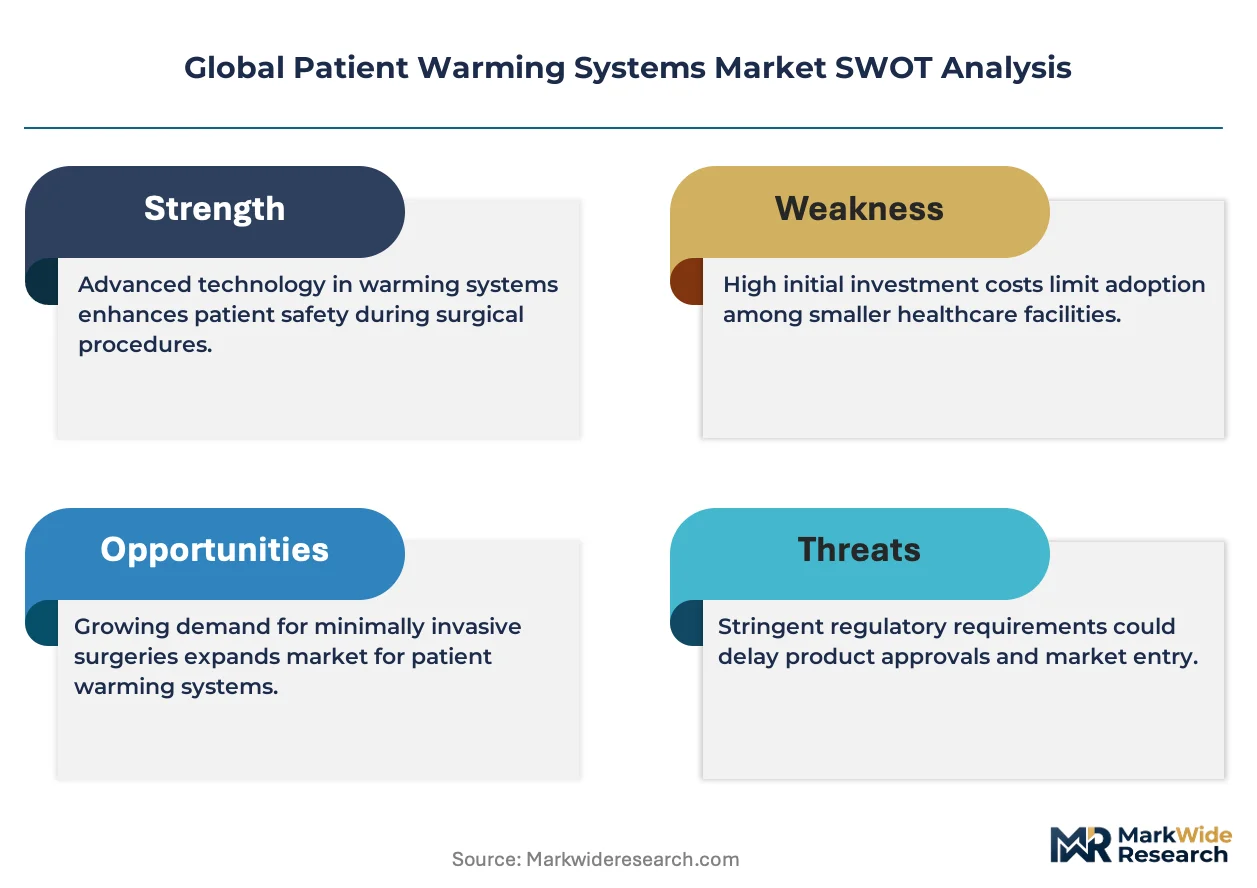
- Consumable Cost Burden:The high recurring cost of single-use consumables, such as forced-air warming blankets, presents a significant budgetary challenge for hospitals, particularly in public healthcare systems with fixed budgets.
- Competition from Alternative Methods:The availability of lower-cost, traditional warming methods like heated cotton blankets or intravenous fluid warmers, while less effective, can be perceived as sufficient in cost-sensitive environments.
- Stringent Regulatory Hurdles:Navigating the complex and lengthy device approval pathways, such as the US FDA's 510(k) clearance and Europe's Medical Device Regulation (MDR), creates high barriers to entry for new manufacturers.
Strategic Opportunities
- Integrated OR Systems:Developing patient warming systems that integrate with patient monitoring platforms and electronic health records offers an opportunity to provide data-driven, automated temperature management and improve clinical workflows.
- Expansion into Non-Surgical Applications:There is an opportunity to expand system use into non-surgical settings, including emergency departments, intensive care units, and neonatal care, where maintaining normothermia is also clinically important.
- Ambulatory Surgery Centers:The rapid growth of ambulatory surgery centers as a lower-cost alternative to hospitals for outpatient procedures creates a new, fast-growing end-user segment for compact and efficient warming systems.
Industry Challenges
- Staff Training and Compliance:Ensuring consistent and correct use of patient warming systems, particularly single-use consumables, requires continuous staff training and adherence to protocols, which can be a logistical challenge for large hospitals.
- Interoperability with Legacy Equipment:Integrating new, smart patient warming devices with existing legacy equipment and diverse IT infrastructure within hospitals presents significant technical and compatibility challenges for healthcare providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Warming Systems Market |
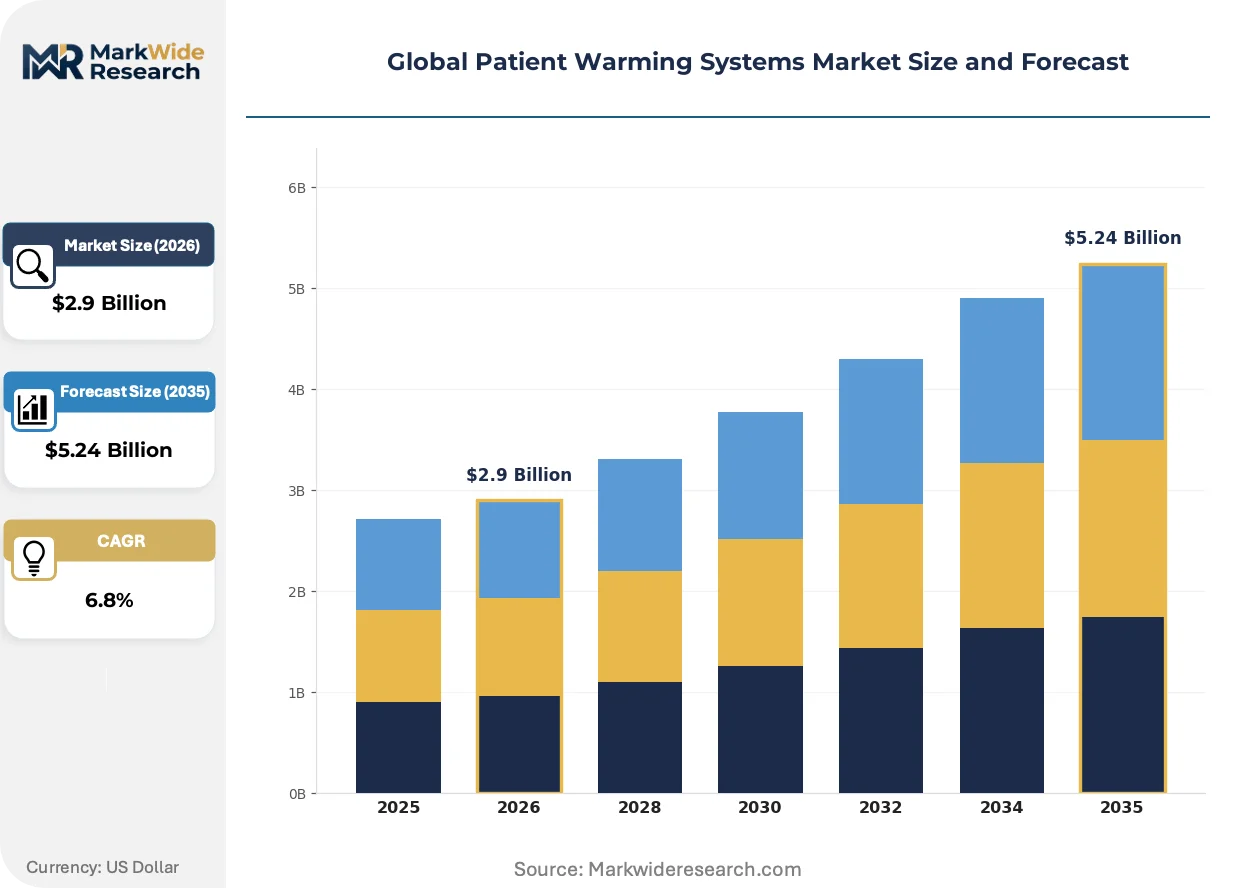
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forced Air Warmers, Electric Heating Pads, Fluid Warmers, Radiant Warmers, Conductive Mattresses Application: Surgical Procedures, Emergency Care, Neonatal Care, Postoperative Recovery, Intensive Care Units End User: Hospitals, Ambulatory Surgery Centers, Trauma Centers, Specialty Clinics, Home Care Providers Deployment: Mobile Units, Fixed Installations, Portable Devices, Integrated Systems, Standalone Equipment |
| Companies Covered | 3M Company, Medtronic plc, Stryker Corporation, Becton Dickinson and Company, GE Healthcare, Philips Healthcare, ZOLL Medical Corporation, Smiths Medical, Inc., Cincinnati Sub-Zero Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Warming Systems Market Strategic Shifts & Innovations
Patient warming systems are evolving from standalone hardware into connected components of the digital operating room. This shift emphasizes data integration and automated control to improve patient outcomes and operational efficiency.
Smart sensors embedded within warming blankets provide real-time temperature feedback from the patient-device interface. Hospitals are adopting these technologies for more precise temperature control and automated quality reporting. This feedback loop is digitizing perioperative temperature management, moving it from a manual process to a data-driven function.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance. This regulation increases the compliance burden, demanding more rigorous data collection from manufacturers. The product segment for reusable systems with robust tracking capabilities is gaining attention as a way to meet MDR's documentation demands.
A notable shift in hospital acquisition involves moving away from large upfront capital expenditures for warming units. Healthcare providers are favoring bundled purchasing that combines equipment with multi-year contracts for single-use consumables. This model is prominent in US hospital networks, allowing for predictable operational budgeting.
Global Patient Warming Systems Market Segmentation
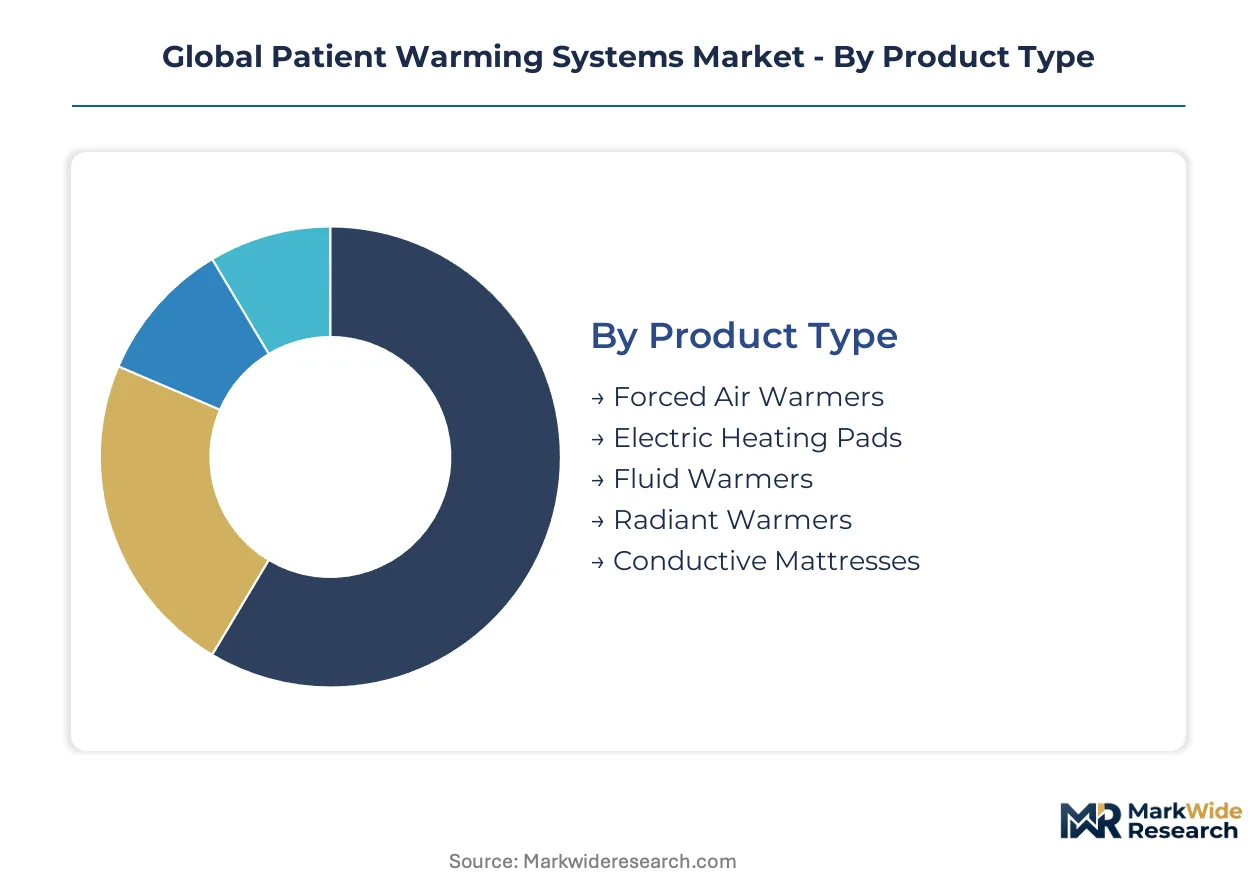
The Global Patient Warming Systems Market segmentation reveals the diverse technological approaches and application areas driving product development and adoption. Understanding these segments is crucial for manufacturers to tailor solutions that meet specific clinical needs and operational requirements across various healthcare settings.
Product Type:
The use-case spectrum for patient warming systems spans from direct contact heat transfer to ambient air modulation for core temperature maintenance.
- Forced Air Warmers:These systems circulate heated air over a patient via specialized single-use blankets, offering rapid and effective rewarming. Demand is highest in hospital surgical suites, driven by established clinical protocols for preventing perioperative hypothermia during complex procedures.
- Conductive Mattresses:Conductive Mattresses provide direct heat transfer through contact with the patient's body surface, ensuring stable and continuous temperature regulation. Growing adoption in intensive care units and neonatal settings is driven by the need for precise thermal management for vulnerable patient populations.
- Electric Heating Pads:Electric Heating Pads offer localized warming through resistive heating elements, often used for smaller body areas or less critical rewarming needs. These are commonly found in recovery rooms and for non-surgical applications.
- Fluid Warmers:Fluid Warmers heat intravenous fluids or blood products before administration, preventing hypothermia induced by cold infusions. This product type is critical in trauma centers and during extensive surgical procedures involving significant fluid replacement.
- Radiant Warmers:Radiant Warmers provide heat from an overhead source, typically used for newborns and infants to maintain stable body temperatures. Neonatal care units represent the primary application for this warming technology.
Established volume favors Forced Air Warmers; emerging adoption favors Conductive Mattresses.
Application:
The application focus delineates where patient warming systems are most critically deployed across various healthcare settings.
- Surgical Procedures:Surgical Procedures represent the largest application area, ensuring normothermia during operations to prevent complications like surgical site infections. Hospitals in developed healthcare systems, such as Germany, prioritize these systems for stringent quality metrics.
- Intensive Care Units:Intensive Care Units utilize warming systems for critically ill patients to stabilize core body temperature and improve physiological outcomes. Demand here is driven by the necessity for precise thermal management in prolonged care scenarios.
- Emergency Care:Emergency Care settings use warming systems for trauma victims or patients presenting with accidental hypothermia, requiring rapid rewarming interventions. These systems are crucial for immediate patient stabilization upon arrival.
- Neonatal Care:Neonatal Care specifically employs patient warming systems to maintain stable body temperatures in premature infants and newborns. Specialized radiant warmers and conductive mattresses are vital in these sensitive environments.
- Postoperative Recovery:Postoperative Recovery units deploy warming systems to rewarm patients after surgery, mitigating discomfort and reducing recovery time. These applications focus on patient comfort and preventing shivering.
High-volume utilization centers on Surgical Procedures; specialized patient populations increasingly benefit from Intensive Care Units applications.
End User:
Patient warming system demand varies significantly across different end-user types, reflecting diverse operational scales and patient populations.
- Hospitals:Hospitals constitute the primary end-user segment, integrating patient warming into perioperative care across multiple departments. Their large patient volumes and complex surgical caseloads drive consistent procurement of both capital equipment and consumables.
- Ambulatory Surgery Centers:Ambulatory Surgery Centers are a rapidly expanding end-user segment, focusing on outpatient procedures requiring efficient warming solutions. The need for quick patient turnover and cost-effectiveness influences their warming system selections.
- Trauma Centers:Trauma Centers specifically utilize patient warming systems for emergency rewarming of severely injured patients to prevent hypothermia-related complications. Rapid deployment and robust performance are key requirements in these critical environments.
- Specialty Clinics:Specialty Clinics, such as those for cardiology or orthopedics, employ warming systems for specific procedures that may induce hypothermia. These clinics often require compact and user-friendly devices.
- Home Care Providers:Home Care Providers increasingly use patient warming systems for long-term care or post-discharge recovery, especially for elderly or vulnerable patients. Simplicity of operation and portability are important considerations for this segment.
Large-scale procurement is dominated by Hospitals; Ambulatory Surgery Centers exhibit the steepest expansion trajectory.
Deployment:
The deployment category highlights the range of physical configurations and integration levels for patient warming technologies.
- Integrated Systems:Integrated Systems combine warming capabilities with patient monitoring platforms and electronic health records for automated data capture and control. Hospitals are increasingly adopting these for enhanced workflow efficiency and data-driven temperature management.
- Mobile Units:Mobile Units offer flexibility for patient transport and use across various hospital departments without fixed infrastructure. Their versatility makes them essential in emergency departments and for intra-hospital transfers.
- Fixed Installations:Fixed Installations refer to patient warming equipment permanently installed in specific operating rooms or ICU bays. These setups provide dedicated warming capabilities for high-volume areas.
- Portable Devices:Portable Devices are compact, lightweight warming units designed for easy movement between patient rooms or for use in remote settings. Emergency medical services and smaller clinics often favor these solutions.
- Standalone Equipment:Standalone Equipment operates independently without integration into larger hospital IT or monitoring systems. These units are often chosen for their simplicity and lower initial cost.
Traditional installations remain significant for Fixed Installations; sophisticated integration drives adoption of Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global supply of patient warming systems increasingly focuses on specialized manufacturing hubs and advanced healthcare markets. Demand concentration in developed systems drives innovation and adoption. Germany, in particular, shows strong demand due to strictly implemented perioperative care protocols.
United States
Demand for patient warming systems in the United States stems from high surgical volumes and stringent quality metrics. The US FDA's 510(k) clearance process mandates rigorous safety and performance standards for medical devices. Major medical device clusters in places like Minnesota and Massachusetts drive product development and market penetration.
Germany
Germany's demand for patient warming systems is significant due to its advanced healthcare infrastructure and strict perioperative guidelines. The European Medical Device Regulation (MDR) enforces comprehensive clinical evidence and post-market surveillance requirements. Bavarian medical technology firms, including those near Munich, contribute to specialized warming solutions.
China
China's expanding medical device manufacturing capacity and growing surgical procedure volume fuel its patient warming system market. The National Medical Products Administration (NMPA) regulates device approval, focusing on safety and efficacy. Industrial parks in the Yangtze River Delta, particularly around Shanghai, are central to component and system production.
Japan
Japan exhibits strong demand for patient warming systems, driven by its aging population and high standards for patient care. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, emphasizing product quality and clinical utility. Medical technology innovation centers in Tokyo and Osaka focus on advanced integrated warming solutions.
India
India's market for patient warming systems is expanding with significant healthcare infrastructure upgrades and increasing surgical volumes. The Central Drugs Standard Control Organization (CDSCO) manages medical device regulations and market access. Major medical device manufacturing zones in Gujarat and Karnataka are developing localized warming technology.
Global Patient Warming Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the patient warming market. The market exhibits a tiered structure, with large diversified medical technology companies alongside specialized niche providers. Strategic archetypes include comprehensive solution providers, focused consumable manufacturers, and regional device innovators. Portfolio diversification and strategic partnerships represent dominant competitive moves.
Within the integrated solutions segment, Stryker Corporation exemplifies a company providing comprehensive operating room technologies, often bundling warming systems with other surgical equipment. Medtronic plc occupies a position focused on patient monitoring and temperature management integration, reflecting its broader medical device portfolio and clinical focus. 3M Company, known for its material science expertise, anchors the consumables segment with specialized forced-air warming blankets essential for clinical effectiveness. These companies represent distinct approaches to market leadership, from broad system integration to specialized consumable innovation, influencing procurement decisions across healthcare providers.
| Leading Market Players |
|---|
| 3M Company |
| Medtronic plc |
| Stryker Corporation |
| Becton Dickinson and Company |
| GE Healthcare |
| Philips Healthcare |
| ZOLL Medical Corporation |
| Smiths Medical, Inc. |
| Cincinnati Sub-Zero Products, Inc. |
| Others |
Cost & Logistics Intelligence
Industrial parks in the Yangtze River Delta, central to component production, leverage China's expanding medical device manufacturing capacity. This reshapes the cost structure for patient warming components, directly influencing global pricing strategies.
Pricing Analysis
Europe's Medical Device Regulation (MDR) dictates the pricing tier structure, emphasizing a hybrid model combining transactional consumables with contract-based bundled systems. Price differentiation stems from clinical efficacy, regulatory compliance like CE marking, and comprehensive after-sales service. Pricing pressure intensifies for single-use consumables due to their high recurring cost burden on public healthcare systems. Developed hospitals prioritizing stringent quality metrics, particularly in Germany, exhibit lower price sensitivity for advanced warming solutions.
Supply Chain Analysis
Specialized material science components and advanced electronics form the upstream feedstock for patient warming systems. Supply concentration centers in China for manufacturing, with innovation hubs in the United States and Germany. The supply chain relies on specialized textiles for blankets and precise sensor technologies. A structural risk involves navigating stringent regulatory hurdles like the US FDA's 510(k) clearance for market entry. Distribution runs through direct sales teams and bundled purchasing contracts with hospital networks and GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patient warming systems market requires incumbents to mount a strong substitution defense. Lower-cost traditional warming methods, like heated cotton blankets, present a persistent threat by offering perceived sufficiency in budget-constrained environments.
For Market Incumbents: Insulate core market share by deepening integration with operating room platforms and patient monitoring systems. Develop advanced smart sensors for real-time feedback, justifying premium pricing against the consumable cost burden. Leverage bundled purchasing contracts and GPO relationships to secure long-term revenue streams. This strategy mitigates the threat from lower-cost alternative warming methods.
For New Entrants and Emerging Players: Establish a beachhead in the rapidly expanding Ambulatory Surgery Centers segment with compact, efficient, and cost-effective warming solutions. Focus on non-surgical applications like emergency departments and neonatal care, where normothermia is critical but current solutions may be less integrated. A go-to-market angle emphasizing ease of use and rapid deployment for quick patient turnover will differentiate offerings.
For Investors and Strategic Acquirers: Long-term, this sits as a defensible medical device play because stringent perioperative guidelines and increasing surgical volumes ensure consistent demand. Seek acquisition targets among specialized technology firms offering advanced sensor integration or those with strong intellectual property in conductive warming. The signal to watch is the accelerating adoption rate of integrated OR systems, indicating a shift towards data-driven temperature management.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated OR Systems | Enhances workflow efficiency and data capture for hospitals, aligning with digital operating room trends. |
| Expand into Non-Surgical Applications | Diversifies revenue streams by addressing critical normothermia needs in ICUs and emergency care. |
| Secure Bundled Purchasing Contracts | Establishes predictable revenue streams and strengthens market position with hospital networks. |
| Invest in Advanced Sensor Technology | Improves precision temperature control and provides real-time patient feedback for better outcomes. |
| Pursue CE Marking and FDA 510(k) Clearances | Ensures broad market access and compliance with strict performance and safety standards for devices. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, CE marking databases, hospital procurement records, and industry association reports. Primary interviews involved clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. This approach ensured a robust bottom-up and top-down triangulation of market data. The analysis integrated qualitative insights with quantitative metrics.
Forecast inputs considered surgical procedure volumes, healthcare infrastructure investment, and evolving perioperative care guidelines across the analysis window. The analytical framework modeled market dynamics across product type, application, end-user, deployment, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and projected adoption rates. This framework accounts for both demand-side and supply-side factors.
Stress conditions across global healthcare spending and regulatory enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding continued healthcare infrastructure upgrades and surgical volume expansion. Material shifts in global economic stability or major regulatory revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Drainage Catheters Market
Medical Devices
Water Flosser Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Vaginal Specula Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Urometer Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Low Flux Single-Use Dialyzers Market