
 Interactive Patient Care Systems Market | 2026-2036
Interactive Patient Care Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Patient Care Systems Market Outlook
North American health system procurement is realigning around integrated virtual care infrastructure. Epic Systems Corporation leverages its dominant EHR footprint to embed interactive patient tools directly into clinical workflows. Cerner Corporation anchors its position through cloud-based platform architectures that span acute and ambulatory settings. Siemens Healthineers differentiates via hardware-software convergence in patient room displays and monitoring integration.
Interactive patient care systems encompass networked hardware and software platforms that deliver education, entertainment, communication, and clinical interaction services directly to patients at the bedside or in remote settings, typically operating through in-room terminals, wearable sensors, and mobile interfaces with real-time data exchange to electronic health records. Patient engagement platforms command the widest deployment footprint among product types as hospitals prioritize bedside education and satisfaction metrics. Cloud-based delivery modes are expanding fastest among deployment options, though hybrid architectures retain margin strength in security-sensitive acute care environments. AI-powered systems within the technology dimension are attracting disproportionate R&D investment as natural language processing and predictive analytics mature for personalized patient interaction.
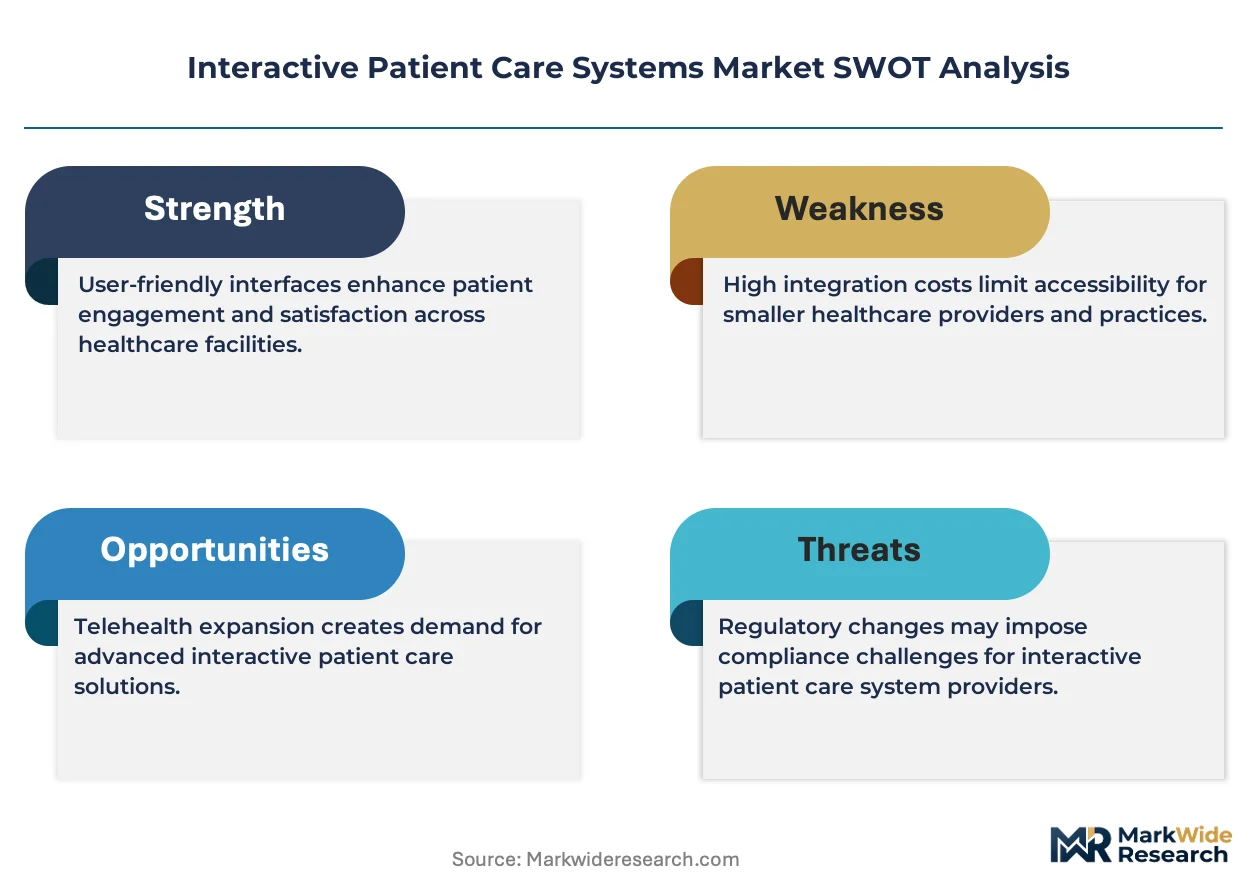
FDA digital health pre-certification and HIPAA security requirements shape product validation timelines and data architecture decisions for vendors seeking US market access. EMA medical device regulations and GDPR data governance standards in Europe impose parallel compliance burdens that influence multinational platform design. Stakeholders must monitor evolving CMS reimbursement definitions for remote patient monitoring, as payment policy clarity will determine which interactive care modalities achieve sustainable health system budgets.
Market Dynamics
Hospital procurement committees now mandate bidirectional EHR integration as a non-negotiable requirement, forcing vendors to rearchitect legacy platforms around real-time clinical data exchange rather than standalone entertainment consoles.
Growth Catalysts
- CMS Remote Monitoring Reimbursement:Medicare payment codes for chronic care remote monitoring create direct revenue streams that justify capital investment in interactive bedside systems. Hospital CFOs recoup platform costs through billable monitoring hours.
- AI-Natural Language Processing Convergence:Voice-enabled patient interfaces reduce nursing documentation burden while capturing patient-reported outcomes at the point of care. Health systems deploy these tools to address workforce compression.
- Japan's Super-Aged Society Infrastructure:METI funding for patient-centered medical homes drives demand for home-based interactive care terminals that bridge acute and post-acute settings. Regional health authorities procure at scale.
Market Restraints
- Semiconductor Component Concentration:Touchscreen controller and medical-grade display panel supply concentrates among Taiwanese and South Korean fabricators. Geopolitical friction threatens hardware delivery timelines.
- HIPAA Technical Safeguards Complexity:Encryption, access control, and audit trail requirements for cloud-hosted patient data extend sales cycles by 8-14 months. Smaller vendors lack compliance infrastructure.
- Substitution by Consumer Tablets:iOS and Android devices with hardened enterprise management offer 60-70% cost reduction for basic education and entertainment functions. Budget-constrained community hospitals default to these alternatives.
Strategic Opportunities
- Germany's Hospital Future Act (KHZG) Incentives:Federal digitization subsidies cover 15-30% of interactive patient system investments for qualifying infrastructure. Vendors align product roadmaps with KHZG certification requirements.
- Behavioral Health Integration:Psychiatric and addiction treatment facilities represent an underserved vertical with distinct workflow needs. Specialized content libraries and safety-hardened hardware address this gap.
- Edge Computing and 5G Convergence:Low-latency local processing enables real-time clinical decision support without cloud dependency. Rural hospitals with unreliable broadband adopt these architectures first.
Industry Challenges
- Clinical Informatics Talent Scarcity:Health systems lack staff who bridge bedside nursing workflows with API integration and data governance. Vendors must embed implementation specialists in every deployment.
- FDA 510(k) Software as Medical Device Classification:Determining whether predictive analytics features trigger regulatory submission creates legal uncertainty. Product managers delay feature releases pending FDA guidance clarification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Patient Care Systems Market |
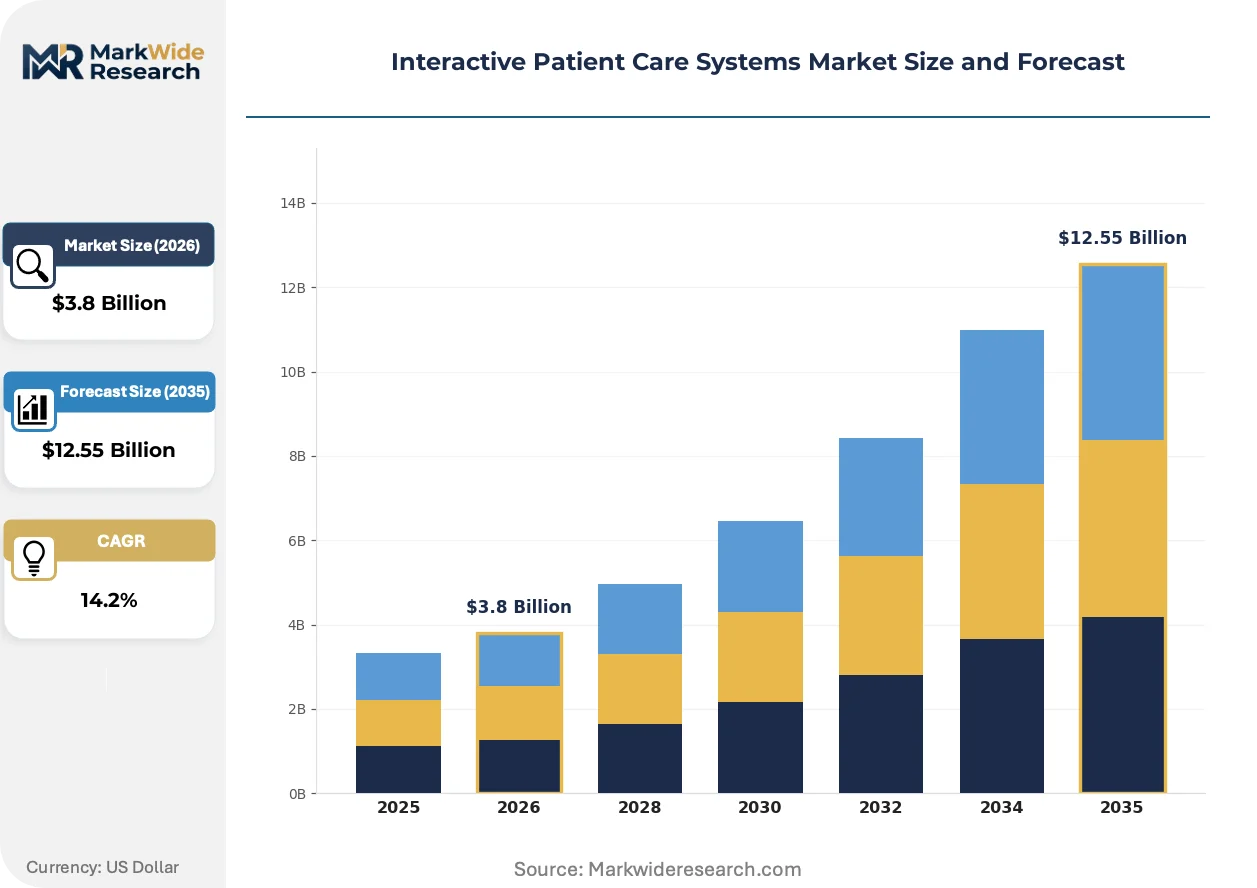
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telehealth Solutions, Remote Monitoring Devices, Patient Engagement Platforms, Virtual Care Applications Delivery Mode: Cloud-Based, On-Premise, Hybrid Systems, Mobile Solutions End User: Hospitals, Outpatient Clinics, Long-Term Care Facilities, Home Healthcare Providers Technology: AI-Powered Systems, Wearable Technology, Mobile Health Apps, Video Conferencing Tools |
| Companies Covered | GetWellNetwork, SONIFI Health, Epic Systems Corporation, Cerner Corporation, Siemens Healthineers, Hospedia, Allscripts Healthcare, PDi Communications Systems Corp., Onyx Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Patient Care Systems Market Strategic Shifts
Artificial intelligence is rewriting the functional boundary between passive patient entertainment and active clinical intervention. Three developments dominate vendor R&D prioritization and health system evaluation criteria.
Ambient clinical intelligence is expanding into interactive patient platforms through always-on microphone arrays and natural language processing engines. Academic medical centers in the United States pilot these systems to automate nursing documentation and detect patient deterioration signals. The technology is compressing the gap between patient room infrastructure and continuous clinical surveillance.
Europe's Medical Device Regulation (MDR) and AI Act create overlapping compliance obligations for systems that algorithmically triage patient requests or predict readmission risk. Manufacturers serving EU markets must maintain dual technical documentation for hardware safety and algorithmic transparency. Class IIa and IIb device classifications now capture previously unregulated software modules.
Hospital supply chain directors now bundle interactive patient systems into enterprise-wide digital transformation contracts rather than point-solution purchases. Epic and Cerner EHR implementations increasingly include bedside terminal specifications in master service agreements. This concentration is visible most acutely in US health system consolidation markets where IDNs standardize across 10-50 facility footprints.
Interactive Patient Care Systems Market Segmentation
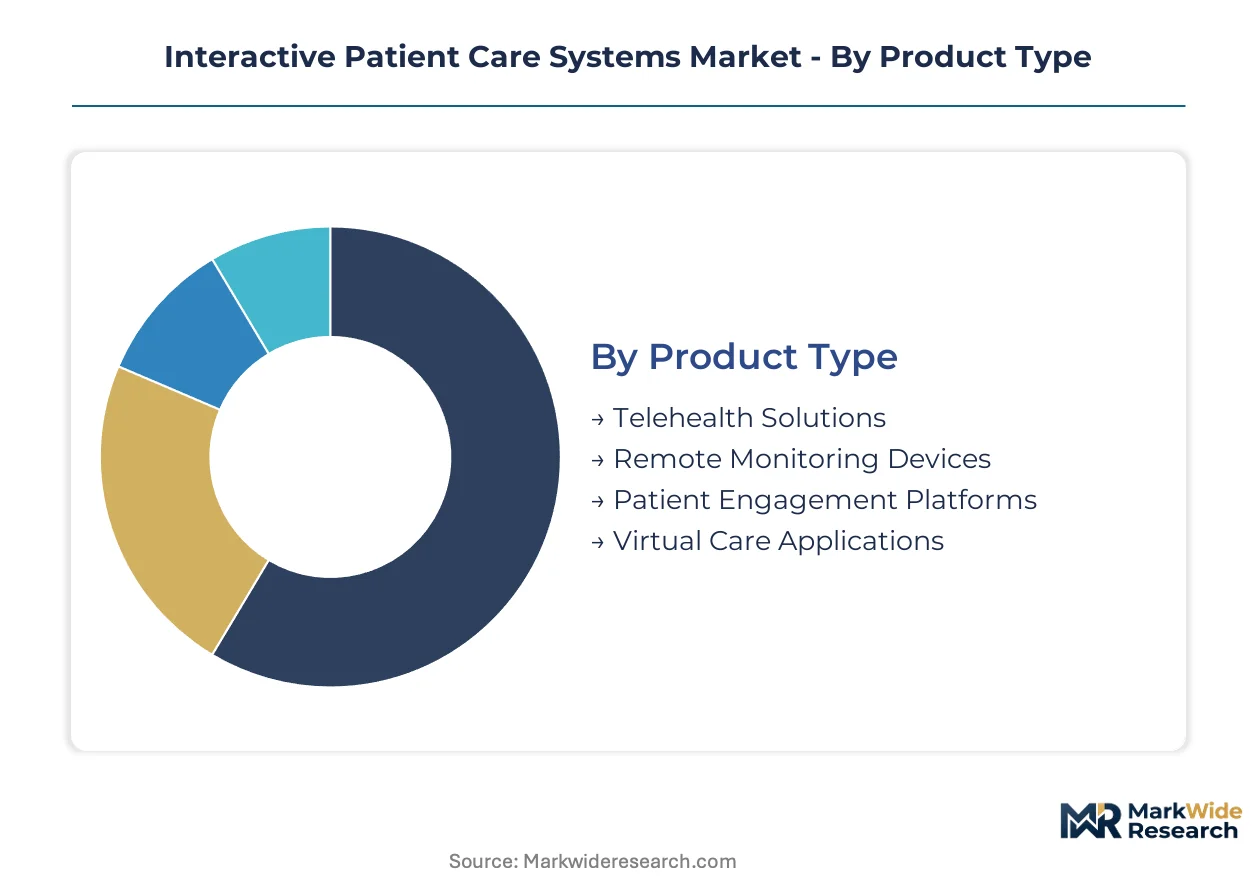
Product architecture decisions in interactive patient care systems cascade across deployment economics, clinical workflow integration, and regulatory validation pathways. Vendors must align segment-specific capabilities with distinct buyer procurement criteria and infrastructure maturity levels.
Product Type:
Hospital procurement committees weight clinical outcome metrics against capital recovery timelines when evaluating product categories.
- Patient Engagement Platforms:Bedside terminals and software suites deliver education, entertainment, and communication services with bidirectional EHR integration. United States health systems prioritize these platforms for HCAHPS score improvement and nursing workflow efficiency.
- Remote Monitoring Devices:Connected sensors and peripherals capture physiological data for transmission to clinical teams. Germany's Hospital Future Act subsidies accelerate deployment in post-acute settings where federal digitization funds offset hardware costs.
- Telehealth Solutions:Synchronous video and audio infrastructure for virtual consultations.
- Virtual Care Applications:Software modules enabling asynchronous patient-provider interaction and care plan management.
Volume sits with Patient Engagement Platforms; growth tilts toward Remote Monitoring Devices.
Delivery Mode:
IT infrastructure maturity and cybersecurity risk tolerance separate buyers across deployment architectures.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and elastic scaling. Outpatient clinic networks in Japan favor this mode for rapid deployment across dispersed sites without on-site server infrastructure.
- Hybrid Systems:Local edge processing with cloud analytics and backup. Acute care hospitals in the United States select this architecture to satisfy HIPAA technical safeguards while enabling predictive analytics capabilities.
- On-Premise:Dedicated hardware and software installations within facility data centers.
- Mobile Solutions:Smartphone and tablet-native applications for patient and provider access.
Margin strength concentrates in Hybrid Systems; Cloud-Based deployment is climbing the fastest.
End User:
Reimbursement model and patient acuity determine functional requirements and purchasing authority structures.
- Hospitals:Integrated delivery networks with 500+ beds drive enterprise contract values and EHR interoperability mandates. IDN consolidation in the United States bundles bedside terminal procurement into Epic and Cerner implementation agreements.
- Home Healthcare Providers:Post-acute agencies managing chronic populations under value-based contracts. Japan's METI-funded patient-centered medical home initiatives expand demand for home-based interactive terminals bridging acute and community care.
- Outpatient Clinics:Ambulatory settings with lower patient volume and simpler workflow needs.
- Long-Term Care Facilities:Skilled nursing and assisted living environments with distinct safety and usability requirements.
Revenue concentration remains with Hospitals; Home Healthcare Providers are gaining share fastest.
Technology:
R&D investment intensity and regulatory classification risk differentiate technology categories.
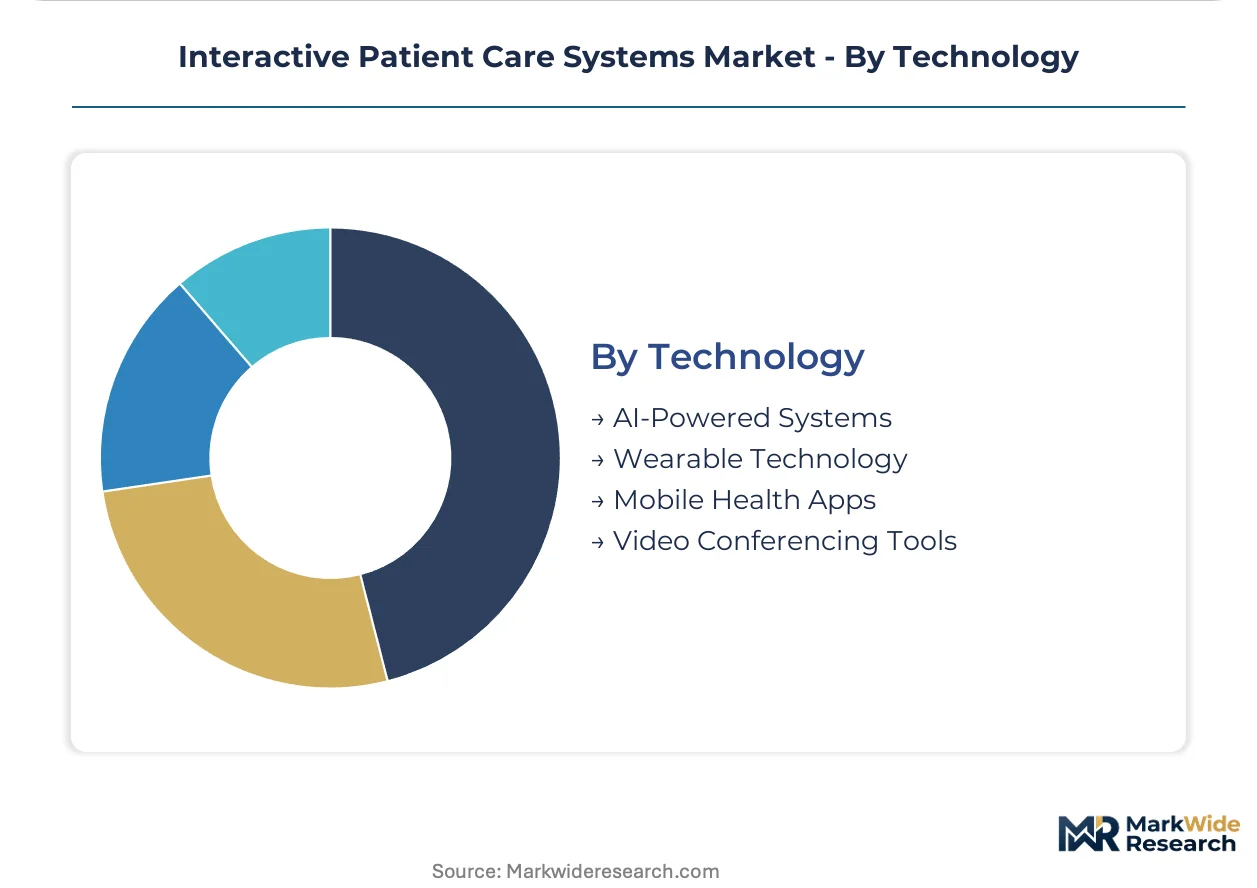
- AI-Powered Systems:Natural language processing engines and predictive analytics for personalized patient interaction and clinical decision support. Academic medical centers in the United States pilot ambient intelligence for automated documentation and deterioration detection.
- Wearable Technology:Body-worn sensors for continuous physiological monitoring with wireless data transmission. Chronic care programs leverage these devices for remote patient monitoring reimbursement under CMS payment codes.
- Mobile Health Apps:Smartphone applications for patient engagement and self-management.
- Video Conferencing Tools:Real-time audiovisual infrastructure for synchronous virtual encounters.
Capital deployment favors AI-Powered Systems; Wearable Technology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in Taiwan and South Korea anchor hardware supply for touchscreen controllers and medical-grade displays that power interactive patient terminals worldwide.
United States
Epic Systems Corporation and Cerner Corporation dominate EHR-integrated patient engagement deployments across integrated delivery networks. FDA digital health pre-certification pathways and CMS remote monitoring reimbursement codes shape vendor product roadmaps and hospital procurement timelines. Academic medical centers in Boston and the San Francisco Bay Area pilot ambient clinical intelligence for automated nursing documentation.
Germany
Siemens Healthineers leverages hardware-software convergence in patient room displays and monitoring integration across university hospitals. The Hospital Future Act (KHZG) provides federal digitization subsidies covering 15-30% of interactive patient system investments for qualifying infrastructure. Medical technology clusters in Bavaria and Baden-Württemberg concentrate vendor engineering and health system pilot programs.
Japan
METI funding for patient-centered medical homes drives demand for home-based interactive care terminals bridging acute and post-acute settings. PMDA medical device regulations and JIS standards govern product validation for systems with predictive analytics capabilities. Regional health authorities in Kanto and Kansai procure at scale for super-aged society infrastructure.
United Kingdom
NHS digital transformation programs prioritize cloud-based patient engagement platforms with interoperability mandates. GDPR data governance and MHRA medical device regulations impose parallel compliance burdens on vendors serving English and devolved health systems. London and Manchester health innovation clusters host pilot deployments of AI-powered bedside interaction systems.
South Korea
Domestic display panel and semiconductor fabrication capabilities support medical-grade touchscreen manufacturing for export markets. MFDS medical device approval pathways and national health insurance reimbursement definitions influence product feature prioritization. Seoul metropolitan area hospitals serve as testbeds for 5G-enabled edge computing architectures in patient room infrastructure.
Interactive Patient Care Systems Market Competitive Environment
Global majors compete with regional champions across EHR integration depth and hardware-software convergence capabilities. The vendor landscape organizes around three tiers: enterprise EHR incumbents with embedded patient tools, specialized patient engagement platform vendors, and industrial conglomerates with medical device portfolios. Strategic moves concentrate on bidirectional EHR interoperability certification and cloud-to-edge architecture transitions.
Among specialized patient engagement platform vendors, GetWellNetwork and SONIFI Health occupy positions emphasizing bedside education and entertainment workflows. Epic Systems Corporation and Cerner Corporation exemplify the EHR-anchored archetype, leveraging dominant clinical data infrastructure to embed interactive tools directly into provider workflows. Siemens Healthineers represents the industrial medical technology conglomerate model, converging patient room displays with monitoring hardware and diagnostic imaging ecosystems.
| Leading Market Players |
|---|
| GetWellNetwork |
| SONIFI Health |
| Epic Systems Corporation |
| Cerner Corporation |
| Siemens Healthineers |
| Hospedia |
| Allscripts Healthcare |
| PDi Communications Systems Corp. |
| Onyx Healthcare |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks with 500-plus beds command enterprise-scale procurement leverage that compresses per-unit pricing for interactive patient terminals while elevating subscription-based SaaS tiers for EHR-integrated platforms.
Pricing Analysis
Warranty and implementation service bundling separates premium vendor tiers from stripped hardware-only transactions in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels aligns with EHR interoperability depth, FDA pre-certification status, and dedicated clinical informatics support. Cost compression in the economy tier intensifies because consumer tablet substitutes erode margins for basic education-entertainment configurations. Community hospitals and outpatient clinics exhibit highest price sensitivity, while academic medical centers prioritize clinical workflow integration over per-terminal cost.
Supply Chain Analysis
Touchscreen controller and medical-grade display panel supply rests on Taiwanese and South Korean fabrication clusters. Semiconductor components, capacitive touch sensors, and antimicrobial enclosure materials feed from concentrated East Asian manufacturing hubs. Single-source vulnerability in advanced display driver ICs exposes delivery timelines to geopolitical friction. Distribution runs through authorized medical device distributors and direct health system contracts, with EHR-embedded procurement channels gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interactive patient care systems are becoming a vertical-integration race where control over EHR interoperability layers and edge-computing hardware determines margin capture.
For Market Incumbents: Anticipate substitution pressure from hardened consumer tablets by deepening clinical workflow integration and ambient intelligence capabilities. Defensive consolidation moves include acquiring specialized NLP engine developers and securing exclusive GPO contracts with tier-one health systems. The priority lever centers on embedding patient engagement tools directly into dominant EHR architectures. For New Entrants and Emerging Players: Behavioral health facilities and post-acute home care agencies represent the most penetrable segments with distinct safety and content requirements. Regional hospital networks outside major IDN consolidation markets offer white-space entry points with lighter EHR integration mandates. A channel partner strategy through biomedical engineering distributors accelerates pilot deployments without direct health system sales infrastructure. For Investors and Strategic Acquirers: The window for entry favors specialized AI-powered bedside interaction platforms with FDA pre-certification progress and proven hospital pilot data. Long-term viability hinges on sustainable reimbursement pathway clarity from CMS and parallel European agencies. The signal to watch is CMS expansion of remote monitoring billing codes to cover predictive analytics features.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates market access for AI-powered clinical decision support features under FDA digital health guidance. |
| Hospital System Partnership | Secures embedded procurement status within Epic and Cerner master service agreements across IDN footprints. |
| Edge Computing Architecture | Enables real-time clinical surveillance without cloud dependency for rural hospitals with unreliable broadband. |
| Reimbursement Strategy | Aligns product roadmaps with CMS remote monitoring codes and Germany's KHZG federal digitization subsidies. |
| Software Companion Development | Extends hardware platforms with ambient NLP engines for automated nursing documentation capture. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this interactive patient care systems analysis. Primary interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and health system CIOs combined with secondary validation from FDA 510(k) databases, CMS Medicare reimbursement bulletins, and hospital procurement platform records. Bottom-up terminal deployment estimates and top-down health system IT budget allocations underwent cross-triangulation.
Granularity-level modeling operated at the intersection of delivery mode, end-user facility type, EHR integration complexity, and regional regulatory cluster across the analysis window. CAGRs derived from segment-level volume trajectories weighted by reimbursement policy momentum and health system consolidation patterns. Forecast inputs incorporated CMS remote monitoring code expansion scenarios and METI-funded patient-centered medical home deployment schedules.
Caveats apply where FDA software-as-medical-device classification clarifications or geopolitical disruption of Taiwanese semiconductor supply could materially shift the outlook. Forecasts reflect assumptions around sustained federal digitization subsidy continuity in Germany and Japan. A small set of named triggers—CMS reimbursement rulemaking, EMA MDR enforcement intensity, and health system cybersecurity incident frequency—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Global Electronic Trial Master File (ETMF) Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Epharmacy Market
Healthcare IT
North America Long-Term Care Software Market