
 Patient Warming Devices Market | 2026-2036
Patient Warming Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Warming Devices Market Outlook
Ambulatory surgical centers is redrawing procurement patterns across the patient warming landscape. 3M Company leverages its extensive hospital supply chain to sustain dominant placement of forced-air warming units in operating rooms. Stryker Corporation differentiates through integrated surgical table and warming system bundles that anchor premium positioning in academic medical centers. Medtronic plc competes on connected device platforms that extend its footprint into temperature monitoring workflows.
Patient warming devices are active thermal management systems that maintain normothermia through surface convection, conductive contact, or radiant heat transfer, typically operating between 32°C and 43°C with integrated temperature feedback controls to prevent thermal injury. These systems serve primarily to reduce surgical site infections, minimize blood loss, and shorten recovery times in perioperative and critical care settings. Forced-air warming dominates product type revenue due to established clinical evidence and broad OR compatibility, while hybrid systems represent the fastest-growing technology segment as manufacturers combine convection and conductive modalities for precision control. Blood warmers command concentrated margins in trauma and massive transfusion protocols, whereas electric blankets occupy a mature, price-sensitive position in post-acute and home care channels.
The FDA governs device classification and 510(k) clearance pathways for patient warming systems in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations for CE-marked products sold across Europe. ISO 80601-2-35 establishes particular safety standards for warming equipment, shaping design specifications and international market access conditions. Stakeholders must monitor evolving cybersecurity mandates and sustainability pressures around single-use forced-air warming components as procurement criteria harden across integrated delivery networks.
Market Dynamics
The FDA's updated medical device cybersecurity guidance is forcing manufacturers to redesign connected warming platforms with embedded encryption and real-time threat monitoring, compressing development timelines while elevating compliance costs across the supplier base.
Growth Catalysts
- Outpatient procedure volume acceleration:Ambulatory surgical centers are expanding forced-air warming procurement as same-day surgery protocols become standard across United States health systems.
- Perioperative infection control mandates:Joint Commission temperature management standards are embedding normothermia maintenance into accreditation requirements for hospital operating rooms.
- Hybrid modality convergence:Manufacturers combining convection and conductive heat transfer are capturing precision-controlled warming demand in cardiac and neurosurgical suites.
Market Restraints
- Single-use component cost structure:Forced-air warming disposable blankets carry recurring material costs that strain ambulatory center budgets versus reusable conductive alternatives.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations for CE-marked devices are extending approval timelines and elevating regulatory spend for European market entry.
- Electrosurgical interference limitations:Electromagnetic compatibility constraints with operating room equipment restrict placement flexibility and require shielding investments.
Strategic Opportunities
- Home care channel underpenetration:Post-acute and recovery settings present expansion potential for portable warming blankets as hospital-at-home programs proliferate in the United States.
- Massive transfusion protocol expansion:Trauma centers and emergency departments are standardizing blood warmer deployment for rapid infusion scenarios.
- ISO 80601-2-35 harmonization:International safety standard alignment is streamlining multi-country registration pathways for manufacturers with compliant design platforms.
Industry Challenges
- Cybersecurity engineering talent scarcity:Connected device platform development requires specialized firmware security expertise that competes with broader medical device and consumer electronics sectors.
- Legacy OR integration complexity:New warming systems must interface with existing surgical tables, patient monitors, and anesthesia workstations without disrupting established workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Warming Devices Market |
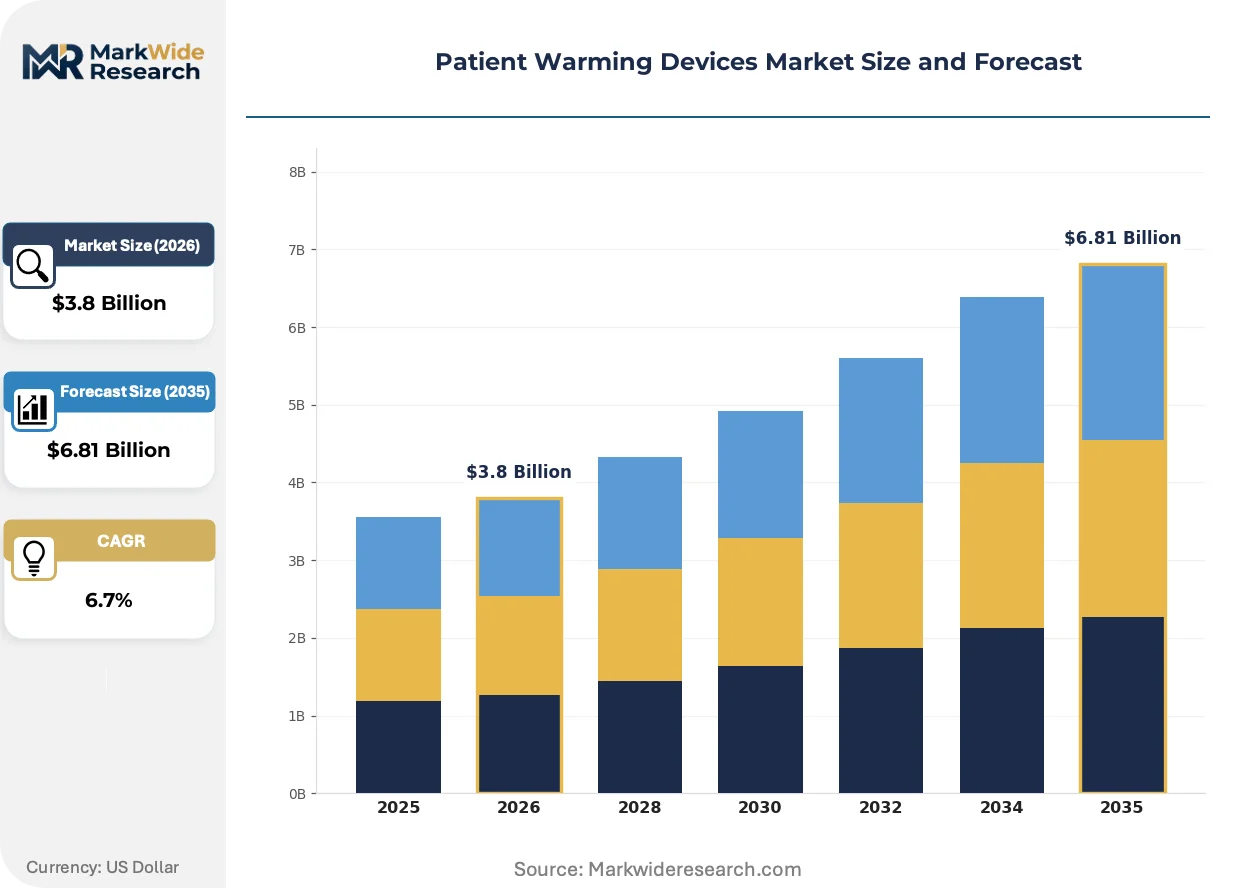
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forced-Air Warming, Electric Blankets, Blood Warmers, Heat Packs Application: Surgery, Neonatal Care, Intensive Care, Trauma Care End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Emergency Services Technology: Convection, Conduction, Radiant Heating, Hybrid Systems |
| Companies Covered | Solventum, 3M Company, Medtronic plc, Stryker Corporation, GE Healthcare, Gentherm Incorporated, ZOLL Medical Corporation, Smiths Medical, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Warming Devices Market Strategic Shifts
Connected platform architecture is redefining competitive differentiation as manufacturers embed temperature monitoring workflows into broader perioperative data ecosystems, shifting value capture from hardware placement toward integrated system contracts.
Hybrid warming technology is fragmenting the traditional product taxonomy by combining forced-air convection with conductive surface panels in single-platform configurations. Academic medical centers in the United States are piloting these systems for procedures requiring precise core-to-peripheral temperature gradients. This convergence is fragmenting vendor market positions previously anchored to single-modality dominance.
The EU Medical Device Regulation's post-market surveillance obligations are compressing product lifecycle planning for CE-marked warming systems sold across Europe. Manufacturers must now maintain active clinical follow-up registries and periodic safety update reporting. Blood warmer categories face the steepest compliance burden due to their critical care classification and higher risk profile under MDR Annex VIII rules.
Integrated delivery networks are consolidating vendor relationships around enterprise-wide temperature management contracts that bundle capital equipment, disposables, and service across multiple facilities. United States health systems including Kaiser Permanente and Mayo Clinic are negotiating multi-hospital agreements that displace site-by-site procurement. This concentration is most visible in the Southeast and Midwest regions where hospital consolidation has advanced furthest.
Patient Warming Devices Market Segmentation
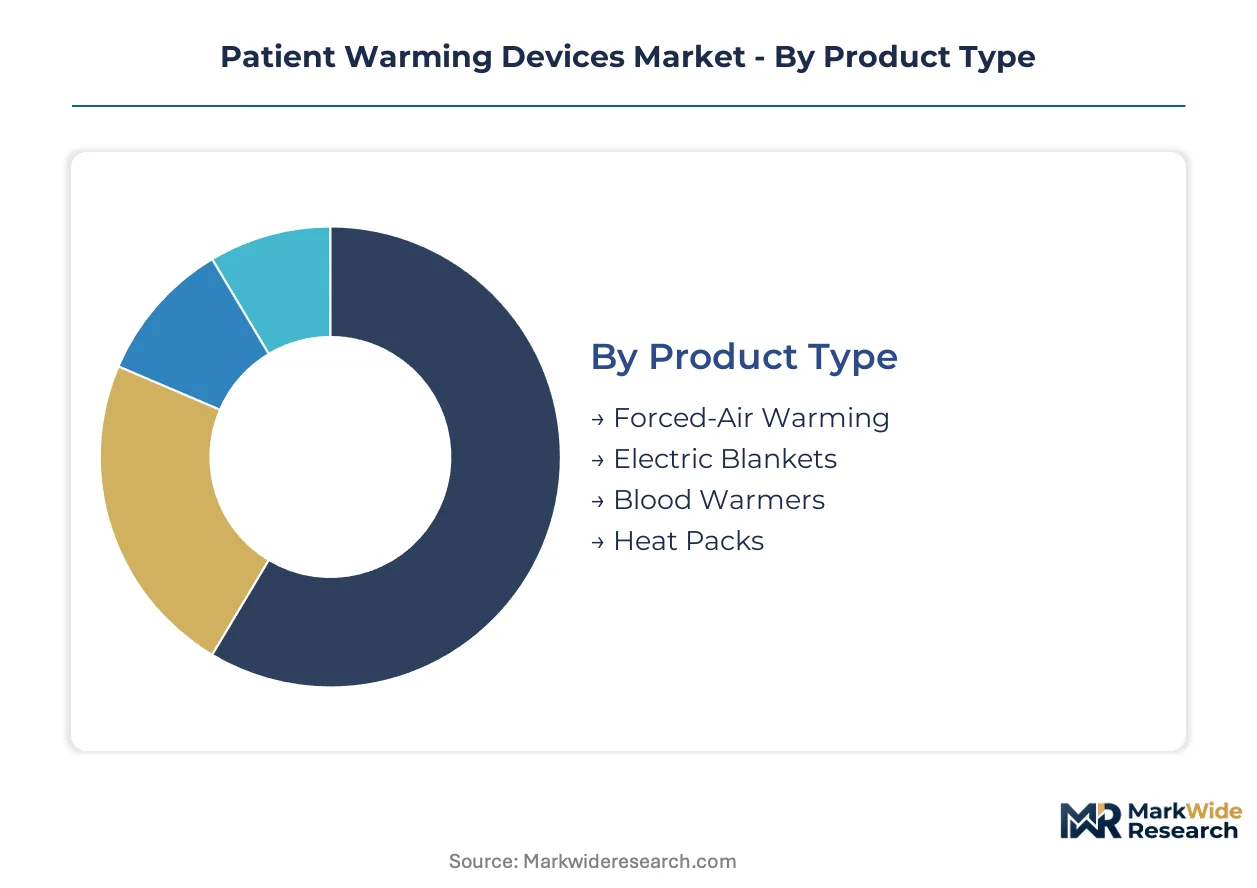
Segmentation reveals how margin pools concentrate around procedural specificity and care setting infrastructure. Manufacturers align R&D and commercial resources against the intersection of product modality and clinical application to capture premium positioning.
Product Type:
Forced-air warming systems command the largest margin pools due to disposable blanket recurring revenue and established OR placement. Electric blankets occupy a defensible mid-tier position in post-acute channels with lower acquisition barriers.
- Forced-Air Warming:Surface convection systems utilizing filtered heated air distributed through single-use blankets. Demand concentrates in United States ambulatory surgical centers executing same-day orthopedic and general surgery protocols where Joint Commission temperature standards apply.
- Electric Blankets:Conductive polymer or resistive wire heating elements embedded in reusable fabric surfaces. Home care settings in the United States are standardizing these for hospital-at-home recovery programs where capital equipment procurement is constrained.
- Blood Warmers:Counter-current or dry heat exchangers maintaining infusion temperatures between 37°C and 42°C for transfusion protocols.
- Heat Packs:Chemical or phase-change passive warming devices for pre-hospital and limited-resource environments.
Forced-air warming holds installed capacity across United States health systems. Hybrid system configurations are rotating up the share rankings in cardiac and neurosurgical suites.
Application:
Surgery generates the highest absolute revenue per procedure due to mandatory normothermia maintenance and bundled payment incentives. Neonatal care commands concentrated margins from precision temperature control requirements and critical care classification.
- Surgery:Perioperative thermal management across pre-operative, intra-operative, and post-operative phases. United States academic medical centers are mandating continuous temperature monitoring for all procedures exceeding 60 minutes to reduce surgical site infection rates.
- Neonatal Care:Incubator and radiant warmer systems maintaining thermoregulation for premature infants. Level III and IV neonatal intensive care units in the United States are upgrading to servo-controlled platforms with skin-probe feedback loops.
- Intensive Care:Continuous normothermia maintenance for sedated or paralyzed patients with compromised thermoregulatory response.
- Trauma Care:Rapid warming for hypothermic patients in emergency departments and field transport scenarios.
Surgery anchors capital equipment placement decisions. Trauma care is climbing the fastest as massive transfusion protocols expand across United States trauma center verification requirements.
End User:
Hospitals concentrate procurement volume through enterprise-wide standardization contracts. Ambulatory surgical centers represent the steepest expansion trajectory as outpatient migration accelerates procedure volume displacement from inpatient settings.
- Hospitals:Integrated delivery networks negotiating multi-facility temperature management agreements. Kaiser Permanente and Mayo Clinic are bundling capital equipment, disposables, and service across their United States hospital portfolios.
- Ambulatory Surgical Centers:Freestanding facilities performing same-day procedures requiring rapid patient throughput. Southeast and Midwest United States regions show the highest concentration of new center development with forced-air warming as standard equipment.
- Home Care Settings:Post-acute recovery environments with portable or rental-based warming solutions.
- Emergency Services:Pre-hospital and emergency department deployment for trauma and environmental exposure cases.
Hospitals retain vendor relationship control. Ambulatory surgical centers are displacing site-by-site procurement with group purchasing organization aggregation.
Technology:
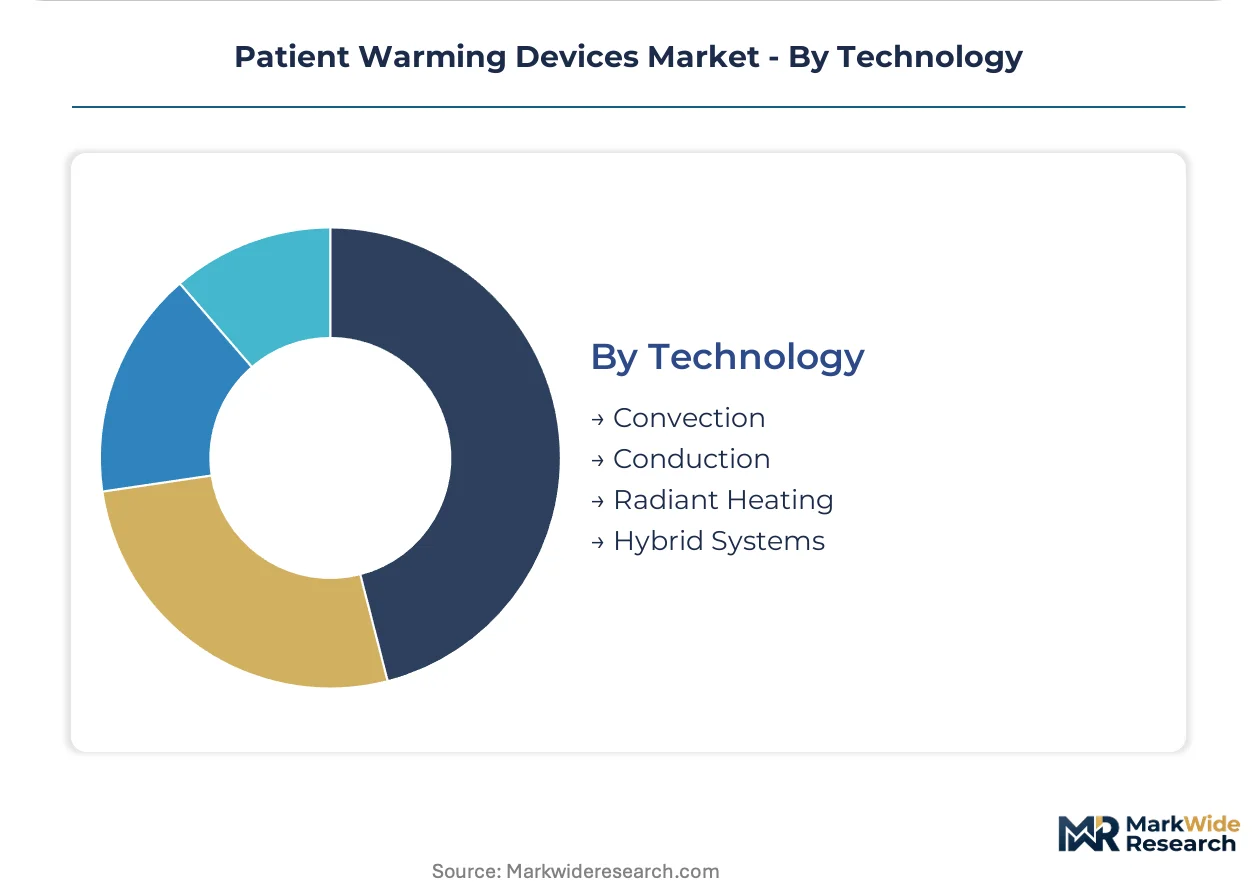
Convection platforms dominate installed base through forced-air warming standardization. Hybrid systems are expanding most quickly as manufacturers integrate multiple heat transfer modalities for precision control.
- Convection:Heated air circulation through disposable or reusable delivery systems. United States operating rooms maintain this as the default modality for general surgery and orthopedics due to staff familiarity and blanket availability.
- Hybrid Systems:Combined convection and conductive surface panels with independent zone control. Academic medical centers in the United States are piloting these for cardiac procedures requiring controlled core-to-peripheral temperature gradients.
- Conduction:Direct surface contact heating through resistive or circulating fluid elements.
- Radiant Heating:Infrared or ceramic emitter systems primarily deployed in neonatal and trauma applications.
Convection maintains protocol standardization. Hybrid systems are gaining share fastest through precision-controlled warming demand in specialized surgical suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and Class I rail networks enable rapid distribution of capital medical equipment from Midwest manufacturing zones to coastal health systems. This infrastructure underwrites North American dominance in patient warming device procurement.
United States
Joint Commission accreditation standards mandate continuous perioperative temperature monitoring for procedures exceeding 60 minutes. FDA 510(k) clearance pathways govern forced-air warming and conductive system approvals. The Southeast corridor from Atlanta to Charlotte anchors ambulatory surgical center construction, with group purchasing organizations consolidating procurement across multi-state health systems.
Germany
Academic medical centers in Bavaria and Baden-Württemberg pilot hybrid convection-conductive warming platforms for cardiac surgery protocols. EU Medical Device Regulation imposes post-market surveillance registries and periodic safety reporting for CE-marked devices. The Rhine-Main cluster around Frankfurt concentrates distributor networks serving Central European hospital systems.
China
Provincial health commissions in Jiangsu and Zhejiang accelerate tertiary hospital upgrades with integrated operating room infrastructure. National Medical Products Administration classifies warming devices under Class II medical device registration requiring clinical trial data. The Yangtze River Delta manufacturing belt produces cost-optimized conductive blankets for domestic hospital procurement.
Japan
Ministry of Health, Labour and Welfare reimbursement revisions incentivize same-day surgery migration to freestanding clinics. Pharmaceuticals and Medical Devices Agency enforces JIS T 0601-1-35 electrical safety standards for warming equipment. The Osaka-Kobe industrial zone houses precision polymer suppliers serving disposable blanket manufacturers.
United Kingdom
NHS England procurement frameworks standardize temperature management equipment across integrated care systems. Medicines and Healthcare products Regulatory Agency maintains vigilance reporting for adverse incidents involving warming devices. The Oxford-Cambridge-London research triangle hosts clinical validation studies for next-generation servo-controlled platforms.
Patient Warming Devices Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory sophistication, creating a tiered structure where scale advantages in distribution clash with niche expertise in specialized surgical applications. The vendor base separates into diversified medical technology conglomerates, dedicated thermal management specialists, and regional equipment fabricators serving price-sensitive procurement channels. Strategic moves concentrate on enterprise contract consolidation and hybrid modality convergence as manufacturers seek to displace single-technology incumbents.
Among diversified medical technology conglomerates, 3M Company and Stryker Corporation exemplify the integrated supply chain archetype, while Medtronic plc occupies a position emphasizing connected device platforms. These three entities represent contrasting strategic postures: one leveraging extensive hospital distribution infrastructure, another bundling capital equipment with surgical table systems, and the third extending into temperature monitoring software workflows.
| Leading Market Players |
|---|
| Solventum |
| 3M Company |
| Medtronic plc |
| Stryker Corporation |
| GE Healthcare |
| Gentherm Incorporated |
| ZOLL Medical Corporation |
| Smiths Medical |
| ICU Medical |
| Others |
Value Chain & Pricing Dynamics
Multi-year enterprise contracts with integrated delivery networks lock in both supply access and price visibility for patient warming device manufacturers, insulating preferred vendors from spot-market volatility while embedding disposable blanket volumes into predictable revenue streams across United States health systems.
Pricing Analysis
Volume-discount tiering structures separate capital equipment purchasers from disposable blanket replenishment buyers across the patient warming landscape. Pricing stratifies across premium, standard, and economy tiers based on ISO 80601-2-35 certification grade and after-sales service bundling. Cost compression in the economy tier intensifies as group purchasing organizations aggregate ambulatory surgical center demand. Hospitals with enterprise-wide standardization contracts exhibit the lowest price sensitivity, while independent home care distributors face acute margin pressure.
Supply Chain Analysis
Inventory positioning for forced-air warming disposables runs through six-to-eight-week lead times from Midwest polymer converters to coastal distribution centers. Manufacturing concentrates in the United States, China, and Germany, with precision heating element fabrication anchored in Japanese industrial zones. Supply chains draw from medical-grade silicone, conductive polymers, and temperature sensor arrays. Single-source vulnerability persists in FDA-cleared control firmware modules. Distribution runs through hospital supply distributors and direct-to-facility logistics networks serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient warming device incumbents face substitution pressure from reusable conductive alternatives that bypass disposable blanket economics, requiring defensive positioning around clinical evidence and workflow integration to protect installed base erosion.
For Market Incumbents: Compound defensive moats by deepening ISO 80601-2-35 certification investments that emerging competitors cannot replicate quickly, and secure exclusive group purchasing organization contracts that preempt ambulatory surgical center procurement aggregation. The threat of hybrid system convergence from surgical table manufacturers demands accelerated R&D in multi-modality platforms. For New Entrants and Emerging Players: Differentiate on cybersecurity-embedded architecture that addresses FDA guidance for connected devices, targeting the home care channel where hospital-at-home programs lack established vendor relationships. The most penetrable segment lies in portable electric blankets for post-acute recovery, with direct-to-patient rental models as the viable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale thermal management specialists with proprietary heating element technology and existing FDA 510(k) clearances that large conglomerates would otherwise spend years replicating. Long-term viability hinges on software-enabled temperature monitoring workflows rather than hardware commoditization. Watch for inflection when integrated delivery networks begin mandating cybersecurity audit certificates as mandatory bid criteria.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance opens access to German academic medical center procurement frameworks. |
| Hospital System Partnership | Mayo Clinic and Kaiser Permanente enterprise contracts displace fragmented site-by-site sales. |
| Software Companion Development | Temperature monitoring workflows extend value capture beyond capital equipment placement. |
| FDA Submission | 510(k) clearance for hybrid convection-conductive systems anchors premium positioning. |
| Reimbursement Strategy | Joint Commission accreditation alignment embeds normothermia maintenance into standard care protocols. |
Study Parameters
A standing panel of biomedical engineers, hospital purchasing committee members, group purchasing organization contract managers, and ambulatory surgical center operations directors provided ongoing calibration against real-world procurement patterns. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) clearance databases, hospital capital expenditure records, and GPO contract disclosure filings. Bottom-up modeling of device placements and disposables consumption triangulated against top-down health system expenditure analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product modality, application setting, end-user facility type, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity, technology substitution curves, and enterprise contract renewal patterns. Forecast inputs incorporated Joint Commission standard adoption timelines and EU MDR compliance cost trajectories.
The analysis sits within stated boundaries; outcomes outside sustained outpatient migration to ambulatory settings or accelerated FDA cybersecurity enforcement would require recalibration. Forecasts reflect documented assumptions around reimbursement stability and polymer input cost normalization. Cybersecurity talent scarcity and single-use component sustainability pressures represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Neuro Navigation System Market
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Subperiosteal Implants Market